
 Global Embedded Hypervisor Software Market | 2026-2036
Global Embedded Hypervisor Software Market Size, Share, and Industry Trends Forecast 2026-2036
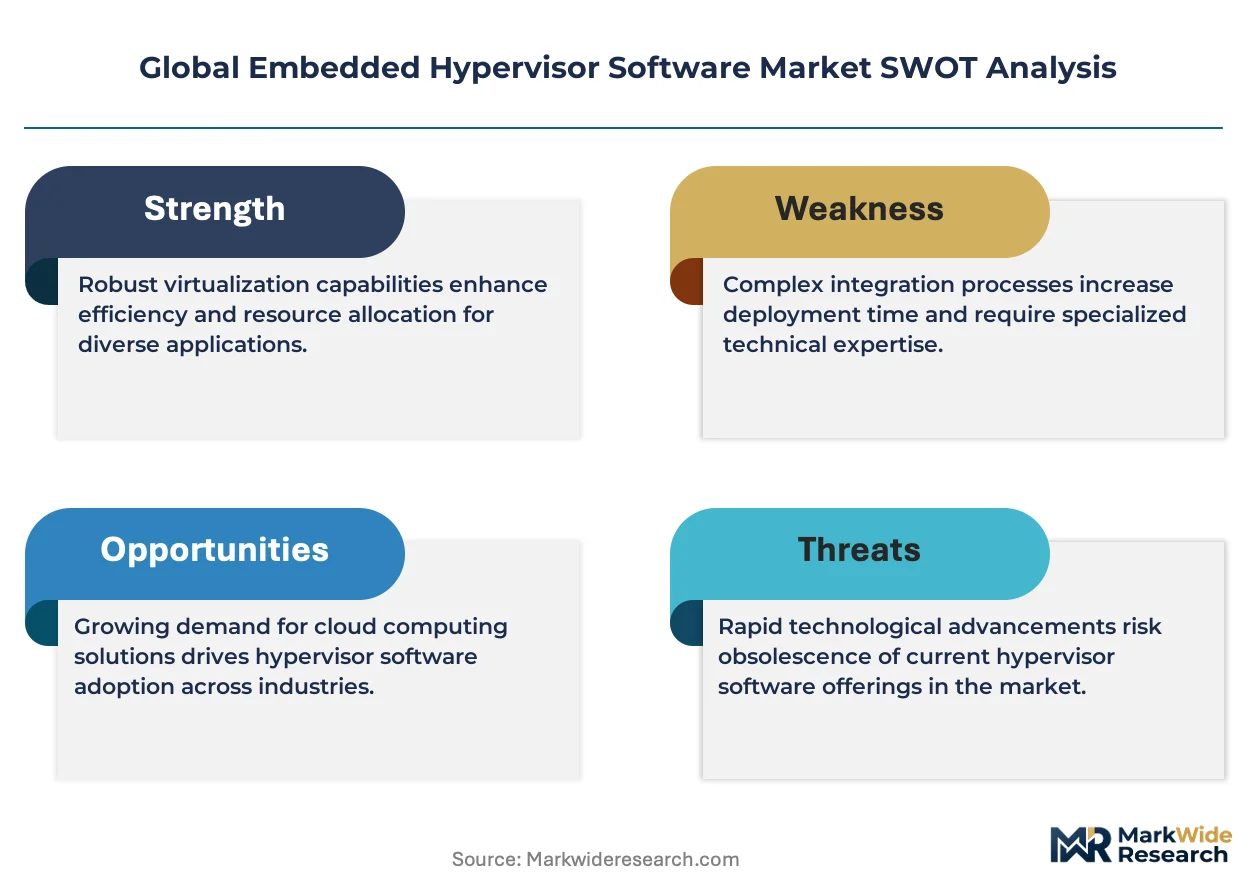
Global Embedded Hypervisor Software Market Analysis
The capital-intensity divergence between bare-metal specialists and hosted-platform incumbents is unwinding as automotive safety requirements harden. Wind River Systems leverages its long-standing aerospace and defense pedigree to anchor premium Type-1 deployments in autonomous drive platforms. Green Hills Software sustains differentiation through deep INTEGRITY-178B certification heritage, while SYSGO competes aggressively on European railway and industrial automation contracts where mixed-criticality consolidation drives procurement.
Embedded hypervisor software creates isolated execution environments atop hardware without underlying host operating systems, enabling concurrent operation of real-time and general-purpose guest OS instances with deterministic interrupt latency below fifty microseconds. Its primary purpose centers on reducing hardware bill-of-materials in safety-critical systems by virtualizing multiple control functions onto single multicore processors. Type-1 bare-metal architectures dominate automotive systems applications where ISO 26262 ASIL-D compliance commands premium pricing, while cloud-based deployment models in telecommunications infrastructure represent the fastest-expanding margin pool as carriers virtualize radio access network functions. Edge deployment models across healthcare devices remain nascent but carry outsized growth potential as FDA cybersecurity guidance hardens premarket submission requirements for networked medical equipment.
FDA cybersecurity premarket guidance, EU AI Act conformity obligations for autonomous systems, and Japan METI's connected vehicle security frameworks collectively reshape product certification roadmaps and elongate vendor qualification cycles. EMA and Health Canada are extending similar networked-device security expectations into diagnostic equipment, broadening addressable scope for healthcare-validated hypervisor stacks. Stakeholders must monitor how functional safety certification reciprocity agreements evolve between NHTSA, KBA, and Japan's Ministry of Land, Infrastructure, Transport and Tourism, as harmonized approval pathways would restructure competitive geography for automotive software suppliers.
Market Dynamics
Consolidation of real-time and general-purpose workloads onto single multicore processors is compressing hardware procurement cycles across automotive, healthcare, and industrial automation sectors. This consolidation force is reshaping vendor qualification timelines and certification roadmaps as safety-critical applications demand deterministic performance guarantees.
Growth Catalysts
- ISO 26262 ASIL-D mandates:Automotive OEMs in Germany and Japan face compulsory functional safety certification for autonomous drive platforms, creating procurement pull for bare-metal Type-1 hypervisors with sub-fifty-microsecond interrupt latency.
- FDA cybersecurity premarket guidance:Networked diagnostic equipment submissions now require demonstrable isolation between safety-critical and general-purpose compute domains, expanding addressable scope for healthcare-validated virtualization stacks.
- Edge compute densification:Telecommunications carriers virtualizing radio access network functions on commodity hardware are generating demand for carrier-grade hypervisors with carrier-grade reliability SLAs.
Market Restraints
- Certification cost concentration:Third-party functional safety validation for multicore interference analysis consumes twelve to eighteen months and six-figure euro expenditures per platform variant, privileging incumbent vendors with amortized certification libraries.
- Silicon supply dependency:Automotive hypervisor deployments remain tethered to ARM Cortex-R and Infineon AURIX processor availability, with foundry capacity allocation favoring high-volume consumer electronics over safety-qualified automotive volumes.
- Technical partitioning limits:Current hardware-assisted virtualization extensions on automotive-grade silicon lack full I/O device isolation, forcing software-based mediation that consumes deterministic latency budget.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for semiconductor and electronics manufacturing are attracting automotive Tier-1 suppliers to establish local software development centers, creating demand for railway and factory automation virtualization.
- EU AI Act conformity:Autonomous system deployers must demonstrate transparent decision-path isolation, positioning certified hypervisors as compliance infrastructure for high-risk AI applications in mobility and healthcare.
- Convergence of deterministic networking:Time-Sensitive Networking IEEE 802.1 standards integrated with hypervisor-based workload consolidation is enabling single-chip implementations of industrial control and machine vision.
Industry Challenges
- Multicore interference analysis expertise:Safety demonstration requires specialized skills in worst-case execution time modeling and shared resource contention, with fewer than two hundred qualified engineers available globally across certification consultancies.
- Legacy ECU integration friction:Decade-old automotive software stacks assume direct hardware access, forcing expensive abstraction layer development during platform migration to virtualized architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Embedded Hypervisor Software Market |
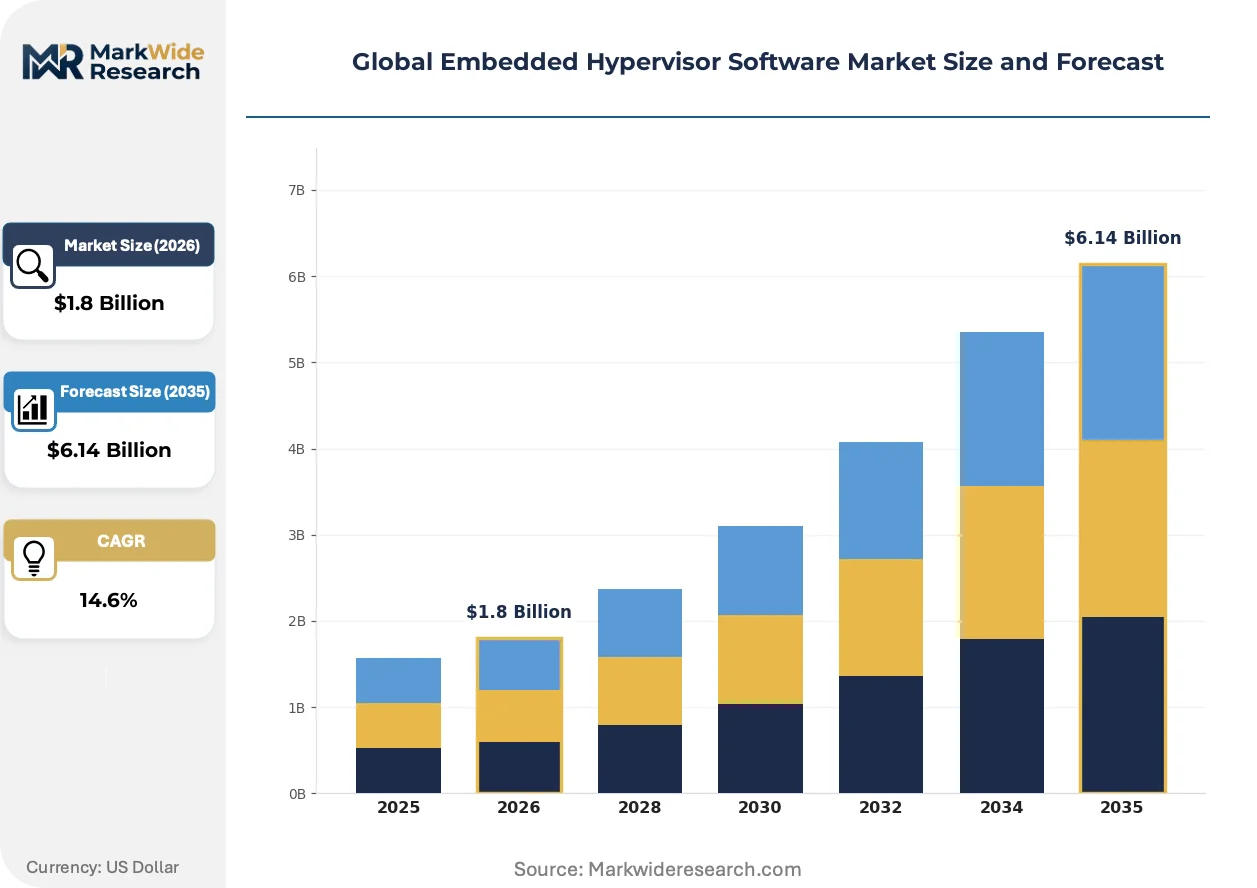
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type-1, Type-2, Bare-metal, Hosted Application: Automotive Systems, Telecommunications, Healthcare Devices, Consumer Electronics Deployment Model: On-Premises, Cloud-based, Hybrid, Edge End User: OEMs, Tier-1 Suppliers, System Integrators, Independent Developers |
| Companies Covered | Wind River Systems, Green Hills Software, VMware, SYSGO, BlackBerry, Citrix Systems, Microsoft Corporation, OpenSynergy, Lynx Software Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Embedded Hypervisor Software Market Emerging Trajectories
Deterministic virtualization is displacing redundant hardware architectures across safety-critical domains. Three convergent developments are compressing procurement timelines and expanding applicable use cases beyond traditional aerospace and defense origins.
Hardware-assisted virtualization extensions purpose-built for automotive silicon are displacing software-based paravirtualization approaches in engine control and battery management systems. Tier-1 suppliers in Stuttgart and Nagoya are mandating these extensions for new platform designs starting 2026 model years. This displacement is collapsing the historical separation between real-time operating systems and rich application environments onto single SoC implementations.
Japan METI's connected vehicle security frameworks and complementary EU AI Act conformity obligations are mandating demonstrable isolation between safety-critical and infotainment domains. Automotive OEMs must submit evidence of hypervisor-mediated boundary enforcement during type approval processes. European and Japanese regulators are coordinating reciprocal recognition of certification evidence, compressing vendor qualification cycles for dual-market suppliers.
Automotive procurement organizations are consolidating vendor panels from six to three approved hypervisor suppliers per platform generation, prioritizing those with pre-certified ASIL-D libraries. This concentration is visible most acutely in Germany, where KBA type approval timelines reward suppliers with existing certification dossiers. Long-term service agreements now bundle hypervisor licensing with decade-long cybersecurity maintenance commitments, shifting revenue toward recurring contractual structures.
Global Embedded Hypervisor Software Market Segmentation
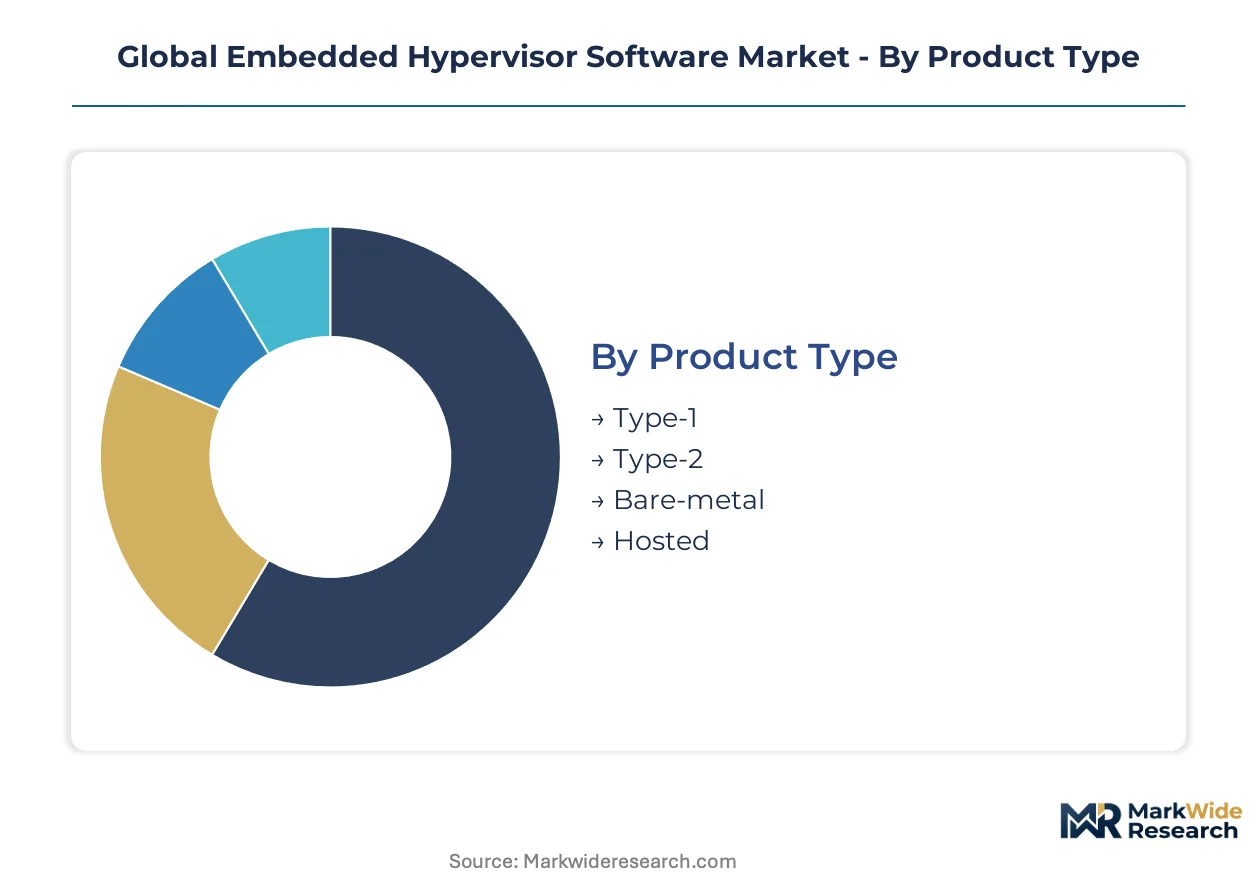
Embedded hypervisor software segments diverge sharply in certification burden and hardware dependency. Procurement patterns across product types and deployment models reveal which virtualization architectures command premium pricing and which face commoditization pressure from containerization alternatives.
Product Type:
Type-1 bare-metal architectures face intensifying substitution pressure from hardware-assisted container runtimes in non-safety workloads, while Type-2 and hosted variants confront direct competition from cloud-native orchestration layers.
- Type-1:Runs directly on processor hardware without intervening host OS, delivering deterministic interrupt latency below fifty microseconds. Automotive OEMs in Germany specify Type-1 hypervisors for autonomous drive platforms where ISO 26262 ASIL-D certification is mandatory.
- Type-2:Operates atop a conventional host operating system, trading deterministic performance for deployment flexibility. Telecommunications carriers in Japan leverage Type-2 implementations for network function virtualization where carrier-grade reliability SLAs apply.
- Bare-metal:Architectures eliminate abstraction layers entirely, enabling direct hardware resource allocation. Industrial automation deployments across Stuttgart manufacturing clusters favor bare-metal isolation for mixed-criticality control systems.
- Hosted:Solutions depend on underlying general-purpose operating systems, limiting applicability in safety-critical domains. Healthcare device developers in the United States deploy hosted hypervisors for non-diagnostic equipment where FDA cybersecurity guidance permits software-based isolation.
Type-1 retains volume leadership; bare-metal holds the steepest expansion curve.
Application:
Application segments distribute across cost tiers defined by certification stringency, with automotive systems commanding the highest per-unit licensing fees and consumer electronics facing severe price compression.
- Automotive Systems:Virtualized ECU platforms consolidate engine control, battery management, and infotainment workloads onto single multicore processors. KBA type approval timelines in Germany reward suppliers with pre-certified ASIL-D libraries.
- Telecommunications:Radio access network function virtualization on commodity hardware generates demand for carrier-grade hypervisors with five-nines availability guarantees. NTT and Rakuten deployments in Japan demonstrate commercial scale.
- Healthcare Devices:FDA cybersecurity premarket guidance mandates demonstrable isolation between safety-critical and general-purpose compute domains. Diagnostic equipment manufacturers face elongated qualification cycles for networked medical systems.
- Consumer Electronics:Low-margin applications tolerate higher latency and reduced isolation guarantees. Smart home device manufacturers prioritize cost minimization over deterministic performance.
Automotive systems dominate revenue concentration; telecommunications is climbing the fastest.
Deployment Model:
Deployment models map to customer infrastructure maturity, with edge implementations representing the highest-margin growth vector as latency requirements harden across industrial and healthcare domains.
- On-Premises:Traditional data center and factory floor installations where physical hardware control remains mandatory. German automotive Tier-1 suppliers maintain captive on-premises virtualization for proprietary control algorithms.
- Cloud-based:Telecommunications infrastructure represents the primary demand center, with carriers virtualizing core network functions on hyperscale platforms. Centralized orchestration reduces operational overhead for multi-site deployments.
- Hybrid:Configurations split workloads between local edge processing and remote cloud aggregation. Railway signaling systems across European corridors deploy hybrid architectures to balance real-time safety with centralized traffic optimization.
- Edge:Distributed compute nodes proximal to data sources, enabling sub-millisecond response for machine vision and robotic control. FDA guidance on networked medical equipment is accelerating healthcare edge deployments.
On-premises retains installed base dominance; edge is gaining share fastest.
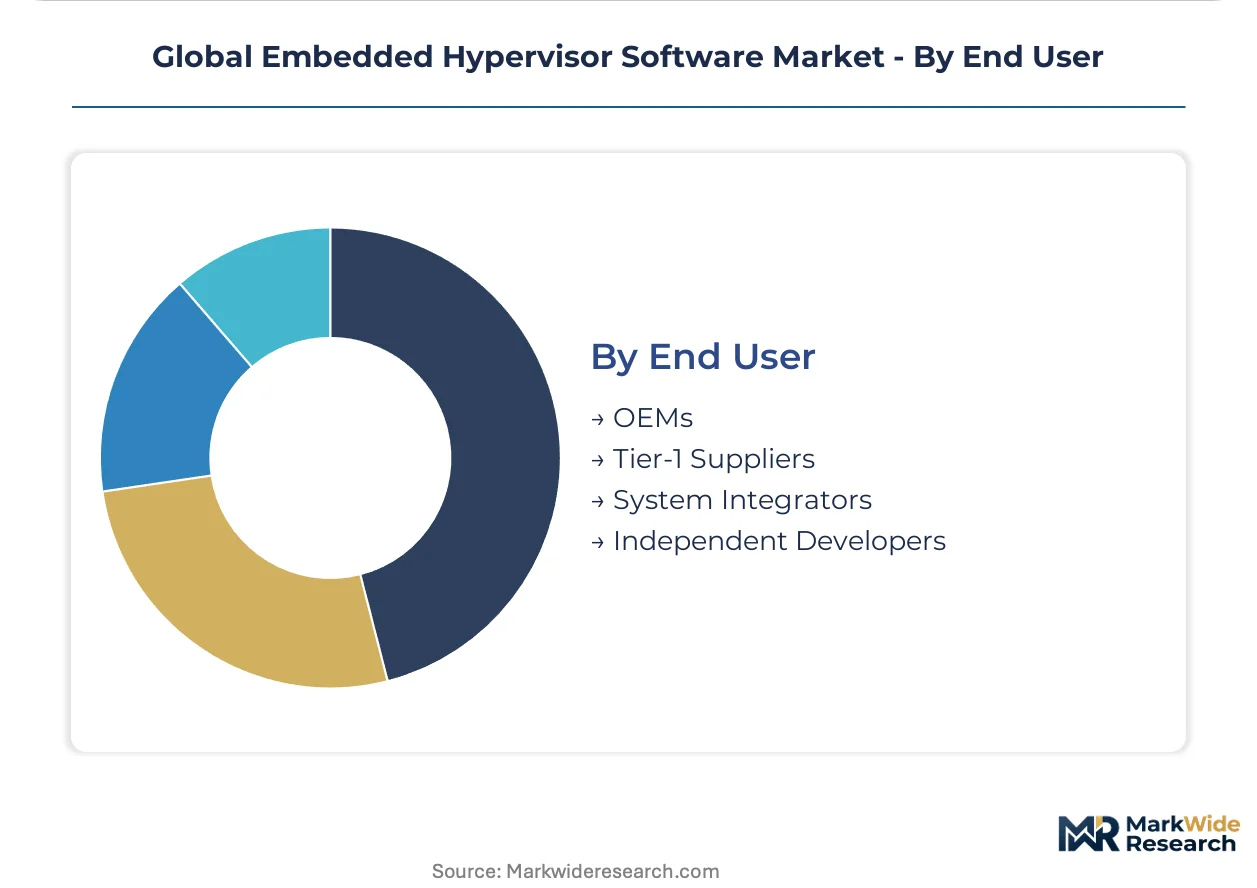
End User:
End user categories reflect supply chain position and technical integration depth, with OEMs capturing the steepest volume expansion as software-defined vehicle architectures proliferate.
- OEMs:Original equipment manufacturers specify hypervisor architectures during platform definition, locking in decade-long service agreements. BMW and Toyota procurement organizations have consolidated vendor panels to three approved suppliers per generation.
- Tier-1 Suppliers:Bosch and Continental develop virtualized ECU platforms for multiple OEM customers, amortizing certification costs across production volumes. Their software development centers in India are expanding under PLI scheme incentives.
- System Integrators:Specialized firms configure hypervisor stacks for industrial automation and railway applications. European system integrators compete aggressively on mixed-criticality consolidation contracts.
- Independent Developers:Individual software vendors and research institutions prototype novel virtualization techniques. Their influence concentrates in academic and standards-body participation rather than commercial procurement.
OEMs anchor demand volume; Tier-1 suppliers hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate minimal price sensitivity where ASIL-D certification commands premium licensing, while Indian industrial automation procurement remains acutely cost-conscious under PLI scheme constraints.
United States
FDA cybersecurity premarket guidance drives diagnostic equipment virtualization demand, mandating demonstrable isolation between safety-critical and general-purpose compute domains. NHTSA coordination with international regulators shapes automotive software approval pathways. Medical device clusters in Greater Boston and the San Francisco Bay Area anchor healthcare-validated hypervisor development.
Germany
KBA type approval timelines reward suppliers with pre-certified ISO 26262 libraries, consolidating procurement panels to three approved vendors per platform generation. EU AI Act conformity obligations mandate transparent decision-path isolation for autonomous systems. Stuttgart automotive Tier-1 suppliers drive bare-metal Type-1 deployments across virtualized ECU platforms.
Japan
METI connected vehicle security frameworks mandate hypervisor-mediated boundary enforcement during type approval processes. Reciprocal certification recognition with European regulators compresses vendor qualification cycles. Nagoya automotive clusters specify hardware-assisted virtualization extensions for 2026 model year platform designs.
India
PLI scheme incentives for semiconductor manufacturing attract automotive Tier-1 suppliers to establish local software development centers. Railway and factory automation virtualization demand concentrates under cost-optimized procurement parameters. Bengaluru and Pune industrial corridors host expanding embedded virtualization engineering capacity.
United Kingdom
Connected infrastructure investments align with automotive safety regulation harmonization efforts post-EU transition. Cybersecurity requirements for networked medical equipment extend FDA-equivalent isolation mandates through MHRA guidance. Midlands automotive engineering clusters participate in cross-border certification reciprocity programs.
Global Embedded Hypervisor Software Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with bare-metal specialists commanding premium pricing in safety-critical automotive applications while hosted-platform vendors compete on deployment flexibility. The vendor base concentrates around three strategic tiers: aerospace-defense heritage suppliers with amortized certification libraries, European industrial automation specialists, and cloud-native incumbents expanding into telecommunications infrastructure. Dominant competitive moves include strategic partnerships with automotive Tier-1 suppliers and technology licensing agreements for hardware-assisted virtualization extensions.
Within the aerospace-defense heritage tier, Wind River Systems and Green Hills Software exemplify vendors leveraging long-standing certification pedigrees to anchor premium Type-1 deployments. SYSGO occupies a position as the European specialist competing aggressively on mixed-criticality consolidation contracts. These three represent distinct geographic anchoring—United States-based heritage suppliers versus German industrial automation focus—while sharing reliance on pre-certified safety libraries as competitive moats.
| Leading Market Players |
|---|
| Wind River Systems |
| Green Hills Software |
| VMware |
| SYSGO |
| BlackBerry |
| Citrix Systems |
| Microsoft Corporation |
| OpenSynergy |
| Lynx Software Technologies |
| Others |
Supply Flow & Price Mechanics
Long-term service agreements bundling hypervisor licensing with decade-long cybersecurity maintenance commitments lock in supply access and price visibility for automotive OEMs. These contracts span platform generations and amortize certification costs across production volumes, insulating incumbent vendors from spot-market volatility while compressing procurement flexibility for buyers.
Pricing Analysis
After-sales service and cybersecurity maintenance contracts drive lifetime value in embedded hypervisor software. Three-tier pricing structure across premium ASIL-D certified, standard automotive-grade, and economy non-safety tiers separates Wind River Systems and Green Hills Software from hosted-platform competitors. Cost compression in the economy tier intensifies as container runtimes substitute for Type-2 hypervisors in non-critical workloads. Tier-1 suppliers in Germany demonstrate minimal price sensitivity for ASIL-D certified stacks, while Indian industrial automation procurement under PLI scheme constraints remains acutely cost-conscious.
Supply Chain Analysis
Lead times for safety-qualified automotive silicon extend eighteen to twenty-four months, constraining hypervisor deployment velocity. Supply concentrates in Taiwan for ARM Cortex-R fabrication, Germany for Infineon AURIX production, and the United States for aerospace-grade processor supply. Raw material dependencies include silicon wafers, automotive-grade packaging substrates, and specialized IP cores. Single-source vulnerability around foundry capacity allocation favors consumer electronics over safety-qualified volumes. Distribution runs through direct OEM and Tier-1 supplier contracts rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded hypervisor software functions as a defensive-moat market where regulatory entrenchment creates durable competitive advantages. Certification reciprocity agreements and pre-certified safety libraries erect barriers that compound over platform generations.
For Market Incumbents: Compound defensive positioning by deepening certification libraries for emerging EU AI Act conformity obligations and extending long-term service agreements to capture cybersecurity maintenance revenue. Threat from hardware-assisted container runtimes in non-safety workloads demands counterinvestment in deterministic performance differentiation. Priority lever rests on vertical integration into automotive Tier-1 supplier engineering centers in India under PLI scheme incentives.
For New Entrants and Emerging Players: Lead with specialized mixed-criticality consolidation expertise for European railway and industrial automation contracts where SYSGO has demonstrated market access. Most penetrable white space sits in healthcare edge deployments under FDA cybersecurity guidance, where diagnostic equipment manufacturers face elongated qualification cycles. Go-to-market angle should emphasize transparent decision-path isolation for high-risk AI applications.
For Investors and Strategic Acquirers: Boutique certification consultancies with multicore interference analysis expertise represent compelling acquisition targets as qualified engineering scarcity intensifies. Long-term viability frames around decade-long automotive platform cycles and recurring cybersecurity maintenance structures. Signal to watch is harmonization of functional safety approval pathways between NHTSA, KBA, and Japan's Ministry of Land, Infrastructure, Transport and Tourism as inflection indicator for vendor consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Pre-certified libraries compress KBA type approval timelines for German automotive OEM procurement panels. |
| Platform Integration Partnership | Hardware-assisted virtualization extensions with ARM and Infineon displace software-based paravirtualization in engine control. |
| Geographic Expansion | Software development centers in Bengaluru and Pune capture PLI scheme incentives for semiconductor manufacturing. |
| Strategic Partnership | Long-term service agreements with Toyota and BMW lock in decade-long cybersecurity maintenance commitments. |
| Acquisition of Specialist Firm | Multicore interference analysis consultancies address scarcity of fewer than two hundred qualified engineers globally. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive OEM platform engineers, Tier-1 supplier procurement leads, industrial automation system integrators, and healthcare device regulatory affairs specialists. Secondary validation drew from KBA type approval databases, FDA premarket submission records, METI connected vehicle security framework documentation, and EU AI Act conformity obligation drafts. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Across the projection horizon, the analytical framework modeled deployment model, product type, application vertical, and regional regulatory cluster dimensions. CAGRs were derived from installed base evolution and replacement cycle analysis. Forecast inputs incorporated ISO 26262 certification timeline elasticity, foundry capacity allocation shifts, and harmonized approval pathway progression.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification investment or delayed certification reciprocity agreements would require recalibration. Forecasts reflect documented assumptions around silicon supply normalization and regulatory harmonization velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Medical E-Commerce Software Market
Software & Services
Sales Compensation Software Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market
Software & Services
Global Time Tracking Software Market
Software & Services
Skills Management Software Market
Software & Services
Sales Enablement Software Market
Software & Services
Global Qualitative Data Analysis Software Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Anti-Plagiarism for the Education Sector Market
Software & Services
Family Law Software Market
Software & Services
Dealer Management System Market
Software & Services
Tech Support Services Market
Software & Services
Email Marketing Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Fire Software Market
Software & Services
G Suite Technology Services Market