
 Codeless Testing Market | 2026-2036
Codeless Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Codeless Testing Market Analysis
GDPR's Article 25 data-protection-by-design mandate is expanding the compliance burden for European enterprises shipping software with embedded analytics. Tricentis leverages model-based automation to sustain enterprise-grade validation pipelines across regulated industries. Katalon anchors its position through an open-core architecture that competes aggressively on total cost of ownership against proprietary alternatives.
Codeless testing denotes software quality assurance methodologies that employ visual interfaces, natural language processing, and record-replay engines to construct test scenarios without traditional scripting languages, typically supporting CI/CD integration through REST APIs and containerized execution agents. Its primary commercial purpose is to democratize test creation across business analysts and QA generalists while maintaining coverage depth previously reserved for engineering specialists. Cloud-based deployment configurations are capturing disproportionate growth as organizations retire on-premises grid infrastructure, while functional testing solutions retain the deepest margin pools due to their integration complexity and customization requirements. The IT end-user segment dominates current bookings, though BFSI applications are expanding fastest as open-banking APIs multiply validation touchpoints.
The EU AI Act, FDA's software-as-medical-device guidance, and ISO/IEC 25010 quality standards collectively elevate documentation and traceability requirements that codeless platforms must satisfy to serve regulated verticals. HIPAA's Security Rule in the United States imposes comparable audit-trail obligations on healthcare software testers selecting automation infrastructure. Stakeholders must weigh platform certification depth against vertical specialization when committing to multi-year test automation roadmaps.
Market Dynamics
Cloud migration mandates under the EU AI Act and parallel digital sovereignty frameworks are compressing enterprise test cycles, forcing quality assurance teams to validate software without heavy scripting overhead while maintaining audit-grade documentation trails.
Growth Catalysts
- Visual workflow automation:BFSI firms deploy drag-and-drop test builders to compress regression cycles for open-banking API validation. Financial services adoption accelerates as transaction volumes multiply validation touchpoints.
- GDPR Article 25:European enterprises face expanded compliance burdens for embedded analytics, driving demand for model-based automation that sustains data-protection-by-design pipelines without manual scripting.
- Containerized execution agents:DevOps teams integrate REST API-connected test runners directly into CI/CD pipelines, eliminating grid infrastructure maintenance and democratizing test creation across QA generalists.
Market Restraints
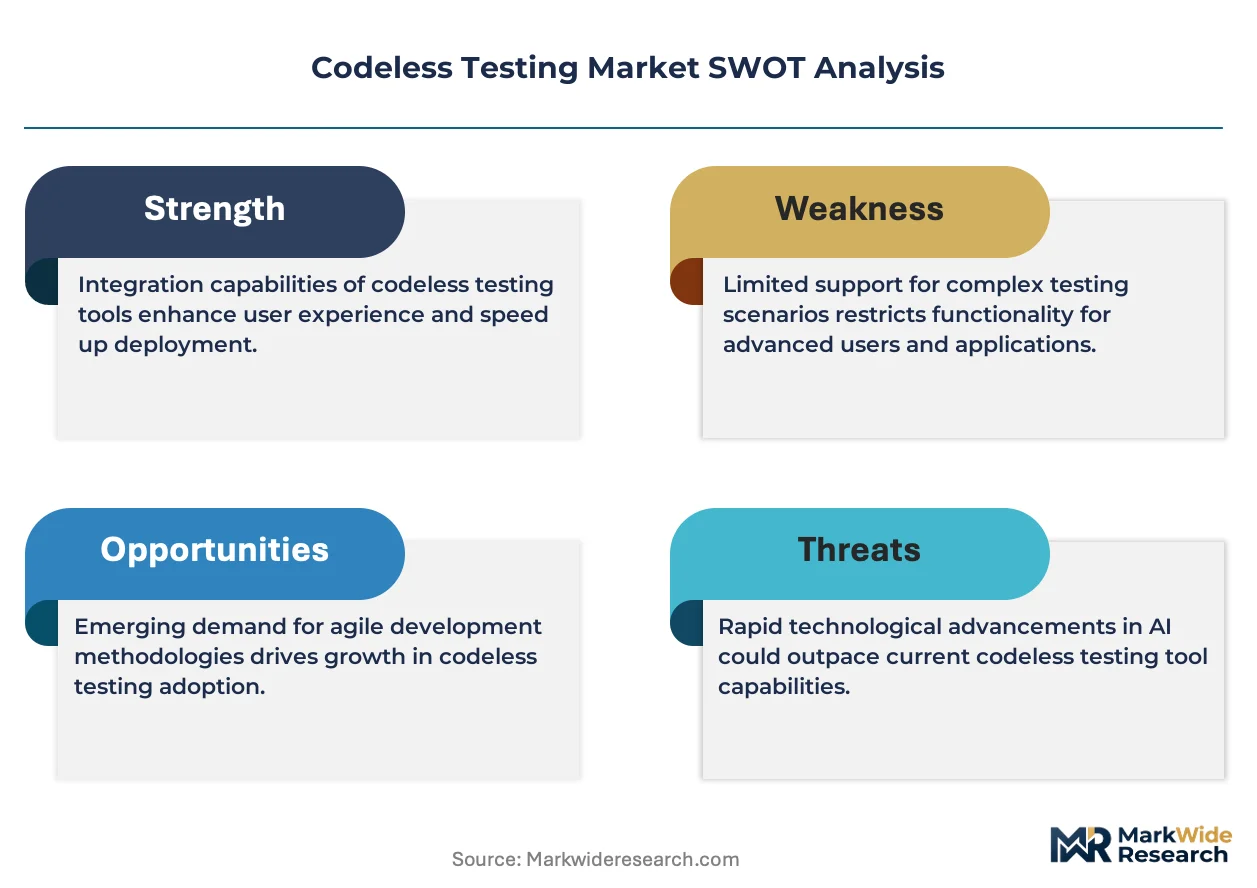
- Specialized talent scarcity:Platform configuration and maintenance require hybrid skill sets combining domain expertise with automation architecture, constraining rollout velocity at mid-market enterprises.
- Legacy system integration friction:Mainframe and COBOL environments resist standard API connectivity, forcing expensive custom adapter development for regulated industries with decades-old core systems.
- ISO/IEC 25010 certification costs:Quality standard compliance demands extensive documentation and third-party validation, elevating total cost of ownership for vendors serving healthcare and medical device verticals.
Strategic Opportunities
- FDA software-as-medical-device guidance:Healthcare automation platforms that pre-validate traceability workflows capture premium positioning in a compliance-intensive vertical with multi-year procurement cycles.
- Natural language processing convergence:LLM-powered test generation from plain English requirements documents opens new buyer segments among business analysts without technical scripting backgrounds.
- India's digital public infrastructure:Unified Payments Interface and Aadhaar-linked service delivery create massive validation surface areas for codeless platforms targeting government and fintech implementations.
Industry Challenges
- HIPAA Security Rule audit trails:Healthcare testers must demonstrate granular access logging and data lineage across distributed test environments, complicating multi-tenant platform architectures.
- Cross-browser execution consistency:Visual test recorders produce brittle selectors that break across browser engine updates, requiring continuous maintenance that undermines promised maintenance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Codeless Testing Market |
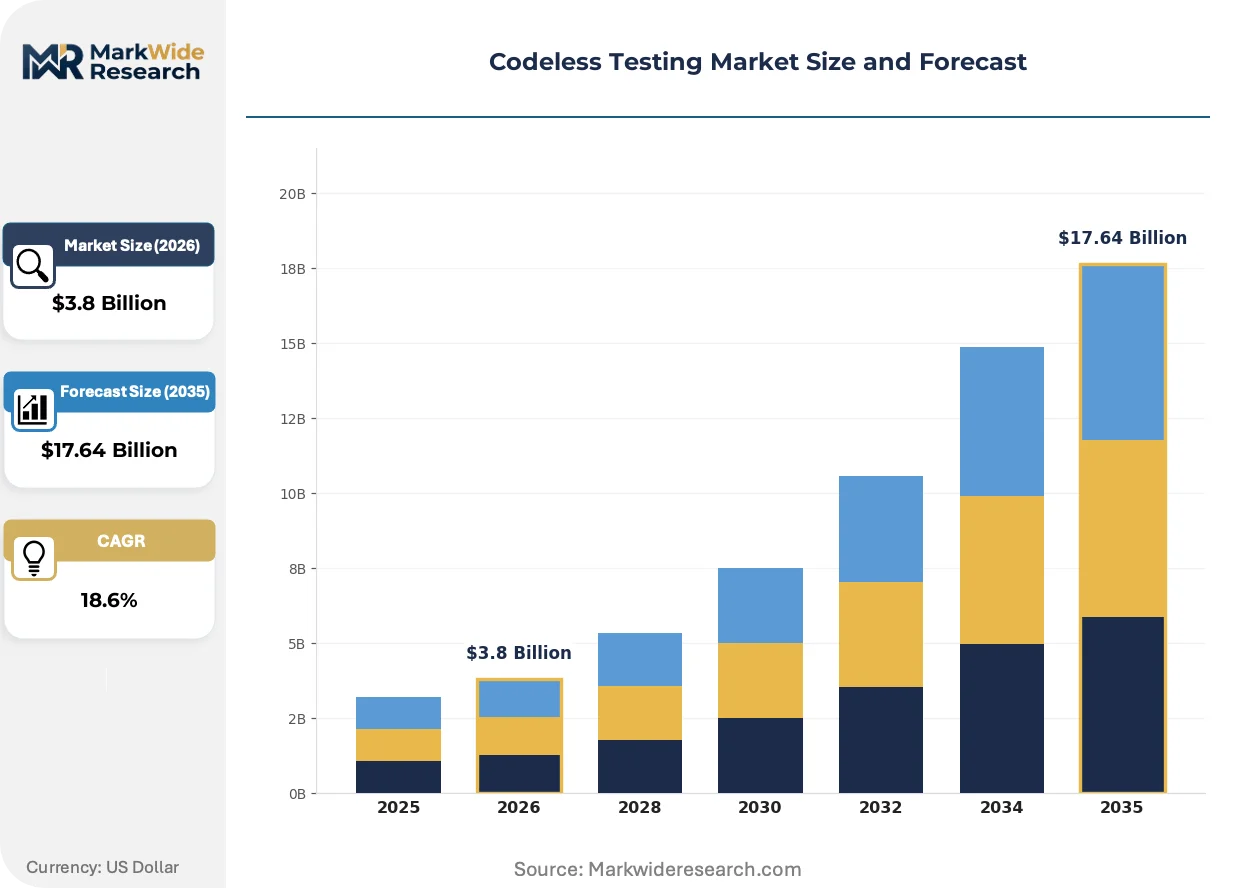
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
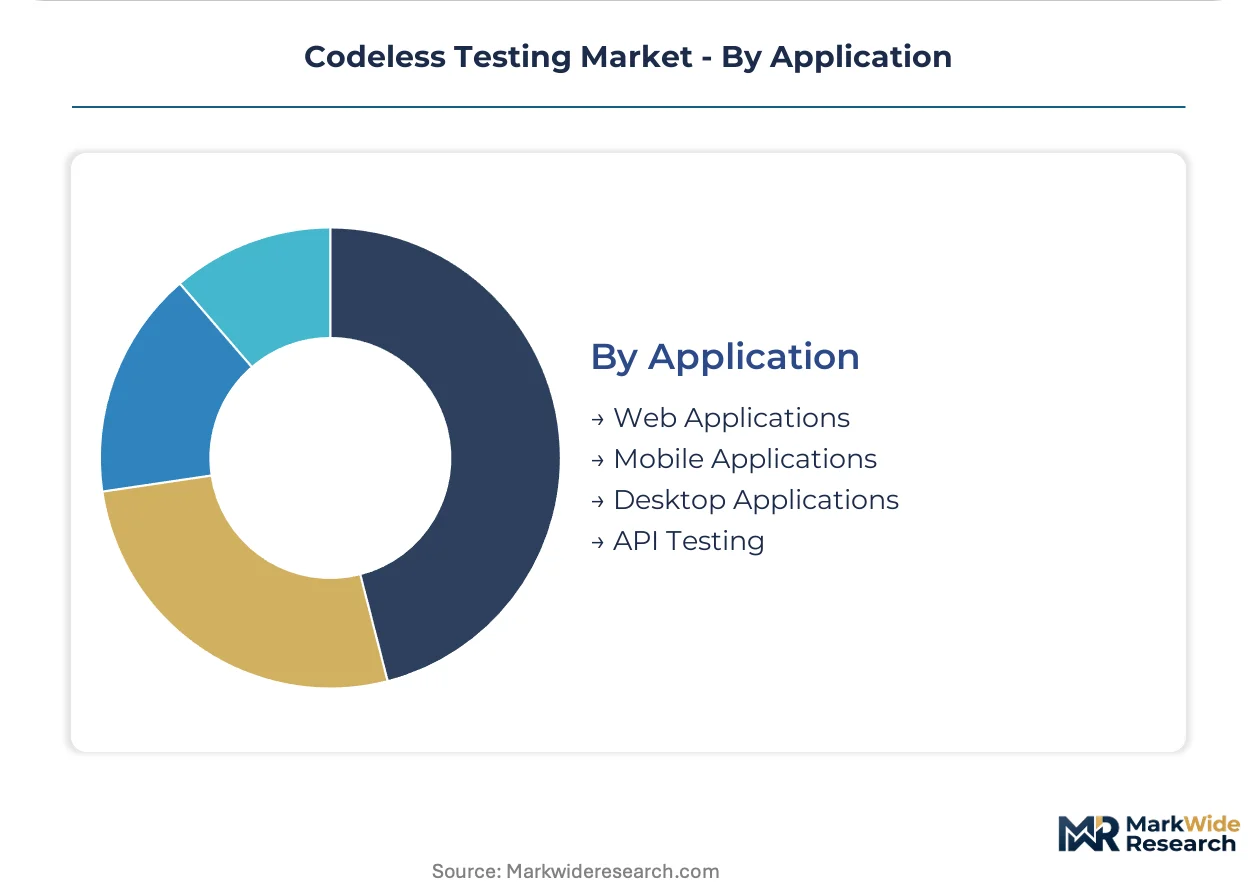
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service End User: IT, Telecom, BFSI, Retail Solution: Test Automation, Performance Testing, Continuous Testing, Functional Testing Application: Web Applications, Mobile Applications, Desktop Applications, API Testing |
| Companies Covered | Leapwork, Functionize, Tricentis, Testim, testRigor, Katalon, AccelQ, Smartester, UiPath, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Codeless Testing Market Emerging Trajectories
Self-healing test automation is reshaping how quality engineering teams maintain validation coverage, with AI-powered element detection reducing the manual intervention that previously consumed sprint capacity.
Intelligent object recognition engines now parse DOM structures through computer vision and machine learning classifiers rather than brittle XPath or CSS selectors. Enterprise QA organizations at Fortune 500 manufacturers are deploying these systems across thousands of test cases. This capability is electrifying test maintenance economics by collapsing the rework cycles that previously consumed 30-40% of automation engineering hours.
The EU AI Act's conformity assessment requirements for high-risk AI systems now extend to software testing tools themselves when used in regulated decision-making contexts. Vendors must demonstrate algorithmic transparency and bias mitigation in their own test generation engines. European pharmaceutical and medical device manufacturers are prioritizing platforms with pre-certified quality management systems over unvalidated alternatives.
Enterprise buyers are consolidating vendor relationships around platforms offering unified functional, API, and visual testing rather than maintaining fragmented point solutions. Mid-market technology companies are retiring Selenium Grid infrastructure in favor of managed cloud execution. United States-based DevOps-mature organizations lead this consolidation, with procurement committees demanding consolidated spend and single-pane governance dashboards.
Codeless Testing Market Segmentation

Codeless testing platforms serve heterogeneous buyer needs across infrastructure maturity, regulatory exposure, and technical complexity. Segmentation reveals where margin pools concentrate and which deployment patterns are displacing legacy approaches.
Deployment:
Cloud-native architectures are reshaping how quality engineering teams provision execution capacity and manage test data residency.
- Cloud-Based:Containerized execution agents connect directly to CI/CD pipelines through REST APIs, eliminating grid infrastructure maintenance. United States-based DevOps-mature enterprises are retiring Selenium Grid in favor of elastic scaling without capital overhead.
- Hybrid:Sensitive test data remains on-premises while execution bursts to cloud infrastructure, satisfying EU AI Act digital sovereignty mandates without sacrificing velocity. European pharmaceutical manufacturers prioritize this configuration for validated computer systems.
- On-Premises:Air-gapped environments serve defense contractors and classified government programs with strict network segmentation requirements.
- Managed Service:Third-party operations teams assume platform administration, appealing to mid-market enterprises with constrained automation architecture expertise.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
End User:
Vertical specialization determines platform certification depth and procurement cycle length.
- BFSI:Open-banking API multiplication creates validation surface areas that visual workflow automation compresses. Drag-and-drop test builders reduce regression cycles for transaction-heavy environments.
- IT:Internal software development organizations across Fortune 500 manufacturers deploy self-healing automation across thousands of test cases, collapsing rework cycles that previously consumed engineering capacity.
- Telecom:5G network function virtualization demands continuous validation of orchestration layers with complex state dependencies.
- Retail:Seasonal traffic spikes and omnichannel integration drive demand for elastic execution without permanent infrastructure investment.
Volume concentration sits with IT. Steepest expansion trajectory is visible in BFSI.
Solution:
Capability integration determines whether buyers consolidate vendors or maintain fragmented point solutions.
- Functional Testing:Visual recorders and model-based automation sustain data-protection-by-design pipelines without manual scripting, capturing premium pricing due to integration complexity.
- Continuous Testing:Shift-left validation embedded within CI/CD workflows demands real-time feedback loops that containerized execution agents enable.
- Test Automation:General-purpose platforms compete on total cost of ownership, with open-core architectures challenging proprietary alternatives.
- Performance Testing:Load generation and bottleneck analysis require specialized infrastructure that fewer vendors bundle comprehensively.
Margin depth sits with Functional Testing. Consolidation pressure is strongest around Continuous Testing.
Application:
Interface diversity drives selector brittleness and maintenance economics.
- Web Applications:Cross-browser execution consistency challenges visual test recorders as browser engine updates break brittle selectors, requiring continuous maintenance.
- API Testing:Headless validation of microservices and open-banking endpoints escapes UI fragility, appealing to BFSI automation architects.
- Mobile Applications:Device fragmentation across iOS and Android versions complicates object recognition engine training.
- Desktop Applications:Legacy Windows and Java client environments resist standard accessibility APIs, forcing custom adapter development.
Adoption maturity sits with Web Applications. API Testing is gaining share fastest as service-oriented architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangalore, Austin, and Shenzhen concentrate codeless testing R&D through tax-advantaged facilities that anchor vendor engineering centers and enterprise pilot programs.
United States
DevOps-mature enterprises in financial services and healthcare drive premium platform deployments. HIPAA's Security Rule imposes audit-trail obligations on healthcare software testers selecting automation infrastructure. The San Francisco Bay Area hosts dense clusters of platform vendors serving Fortune 500 manufacturers deploying self-healing automation.
Germany
Automotive and industrial machinery manufacturers demand ISO/IEC 25010-compliant validation pipelines for embedded software systems. The EU AI Act's conformity assessment requirements extend to testing tools used in regulated decision-making contexts. Munich and Stuttgart engineering centers prioritize platforms with pre-certified quality management systems.
India
Unified Payments Interface and Aadhaar-linked service delivery create massive validation surface areas for government and fintech implementations. RBI's digital payment security guidelines mandate rigorous software testing for financial infrastructure. Bangalore's technology corridor concentrates vendor delivery centers and enterprise QA outsourcing operations.
United Kingdom
Open-banking API proliferation drives BFSI demand for visual workflow automation that compresses regression cycles. FCA's operational resilience requirements elevate documentation standards for financial software testing. London's fintech cluster anchors early adoption of natural language processing test generation tools.
Japan
Automotive electronics and precision manufacturing sectors require traceability-compliant validation for embedded systems. METI's software quality standards emphasize model-based testing approaches for safety-critical applications. Nagoya's automotive engineering belt integrates codeless platforms into supplier quality assurance workflows.
Codeless Testing Market Vendor Landscape
United States vendors anchor the premium tier through DevOps-integrated cloud platforms; European specialists hold compliance-focused positioning for regulated verticals. Market structure tilts toward consolidation as enterprise buyers demand unified functional, API, and visual testing capabilities. Three archetypes dominate: open-core challengers competing on total cost of ownership, proprietary incumbents capturing enterprise-grade validation pipelines, and automation-native entrants leveraging LLM-powered test generation. Dominant competitive moves include strategic partnerships with CI/CD platform providers and vertical specialization through pre-certified healthcare and BFSI modules.
Within the open-core tier, Katalon and AccelQ exemplify architecture-driven positioning that challenges proprietary alternatives on implementation economics. Tricentis occupies a position representing model-based automation depth for regulated industries with multi-year procurement cycles. Among test-generation specialists, Functionize and Testim anchor the AI-native vector where natural language processing convergence opens buyer segments among business analysts without technical scripting backgrounds.
| Leading Market Players |
|---|
| Leapwork |
| Functionize |
| Tricentis |
| Testim |
| testRigor |
| Katalon |
| AccelQ |
| Smartester |
| UiPath |
| Others |
Supply Flow & Price Mechanics
Cloud compute and container orchestration licensing costs cascade through SaaS subscription tiers, with premium deployments absorbing elastic scaling overhead while mid-market buyers trade feature depth for predictable per-seat pricing. Procurement committees weigh vendor consolidation against point-solution flexibility, compressing margin pools for undifferentiated test execution layers.
Pricing Analysis
Short lead-time provisioning commands premium positioning, with same-day environment spin-up carrying surcharge structures against annual-commitment discounts. Three-tier pricing structure across enterprise, professional, and starter levels stratifies by CI/CD integration depth, audit-grade documentation, and dedicated support tiers. Pricing pressure stems from open-core challengers commoditizing baseline record-replay functionality. Mid-market IT organizations exhibit highest price sensitivity, while regulated BFSI and healthcare buyers prioritize certification depth over cost optimization.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler cloud infrastructure concentrated in United States, Ireland, and Singapore regions, where EU AI Act data residency mandates collide with execution latency requirements. Proprietary AI/ML inference engines, browser virtualization stacks, and compliance documentation frameworks constitute critical component dependencies. Tariff exposure on cross-border data transfers elevates total cost of ownership for European deployments. Distribution runs through direct enterprise sales with certified implementation partners anchoring mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer consolidation around unified platforms is accelerating vendor attrition, with undifferentiated point-solution providers facing displacement within 24-36 month procurement cycles.
For Market Incumbents: Deploy self-healing AI engines as defensive moats against LLM-native entrants, while embedding pre-certified compliance modules for FDA and EU AI Act verticals to extend procurement cycle lock-in. Channel control through CI/CD platform partnerships (GitLab, GitHub, Azure DevOps) limits substitution risk from open-core alternatives. For New Entrants and Emerging Players: Capture India's UPI-linked fintech validation surface and Japan's automotive embedded software traceability gaps where incumbent platform localization lags. Natural language test generation from plain English requirements documents opens buyer segments among business analysts without scripting backgrounds, bypassing engineering-led procurement committees. For Investors and Strategic Acquirers: ISO/IEC 25010 pre-certification completion announcements signal platform readiness for pharmaceutical and medical device multi-year procurement cycles, indicating defensible revenue visibility. Target acquisition archetypes combine vertical-specific compliance automation with existing hyperscaler marketplace distribution. Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to LLM commoditization of test generation and hyperscaler native testing tool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified functional, API, and visual testing consolidates vendor relationships and reduces procurement friction. |
| Vertical Specialization | Pre-certified healthcare and BFSI modules capture premium positioning in compliance-intensive procurement cycles. |
| Strategic Partnership | CI/CD platform alliances embed codeless tools into DevOps workflows, limiting substitution risk. |
| Acquisition of Specialist Firm | Self-healing AI and computer vision capabilities fill capability gaps without multi-year R&D timelines. |
| Geographic Expansion | India's digital public infrastructure and Japan's automotive belt offer validation surface areas with limited incumbent penetration. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across QA directors, DevOps platform engineers, enterprise procurement officers, and compliance auditors at regulated manufacturers. SEC 10-K disclosures, EU AI Act implementation guidance, FDA software-as-medical-device guidance documents, and hyperscaler marketplace transaction data supplied quantitative anchors. Bottom-up test automation spend estimates triangulated against top-down enterprise IT budget allocations.
Segmentation granularity modeled deployment configuration, end-user vertical, solution capability, and application interface type at the country level across the analysis window. CAGRs derived from elasticity-adjusted adoption curves incorporating DevOps maturity indices and regulatory compliance burden trajectories. Cloud migration mandates under digital sovereignty frameworks and open-banking API proliferation rates served as demand-side forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to LLM commoditization of test generation, hyperscaler native tool expansion, and regulatory framework evolution. Forecasts reflect documented assumptions regarding CI/CD penetration rates and compliance standard adoption timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
HSM-As-A-Service Market
Software & Services
Generative Design Software Market
Software & Services
Global Business Management Software Market
Software & Services
Simulation Software Market
Software & Services
Global Recreation Management Software Market
Software & Services
Labeling Software Market
Software & Services
3D Animation Production Software Market
Software & Services
Global Customer Service Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Casino Management Systems Market
Software & Services
Global Online Assessment Software Market
Software & Services
Live Software Market
Software & Services
Software-Defined Anything Market
Software & Services
Global OKR Software Market
Software & Services
Human Resource Management Software Market
Software & Services
Global Landscape Software Market