
 Service Dispatch Software Market | 2026-2036
Service Dispatch Software Market Size, Share, and Industry Trends Forecast 2026-2036
Service Dispatch Software Market Analysis
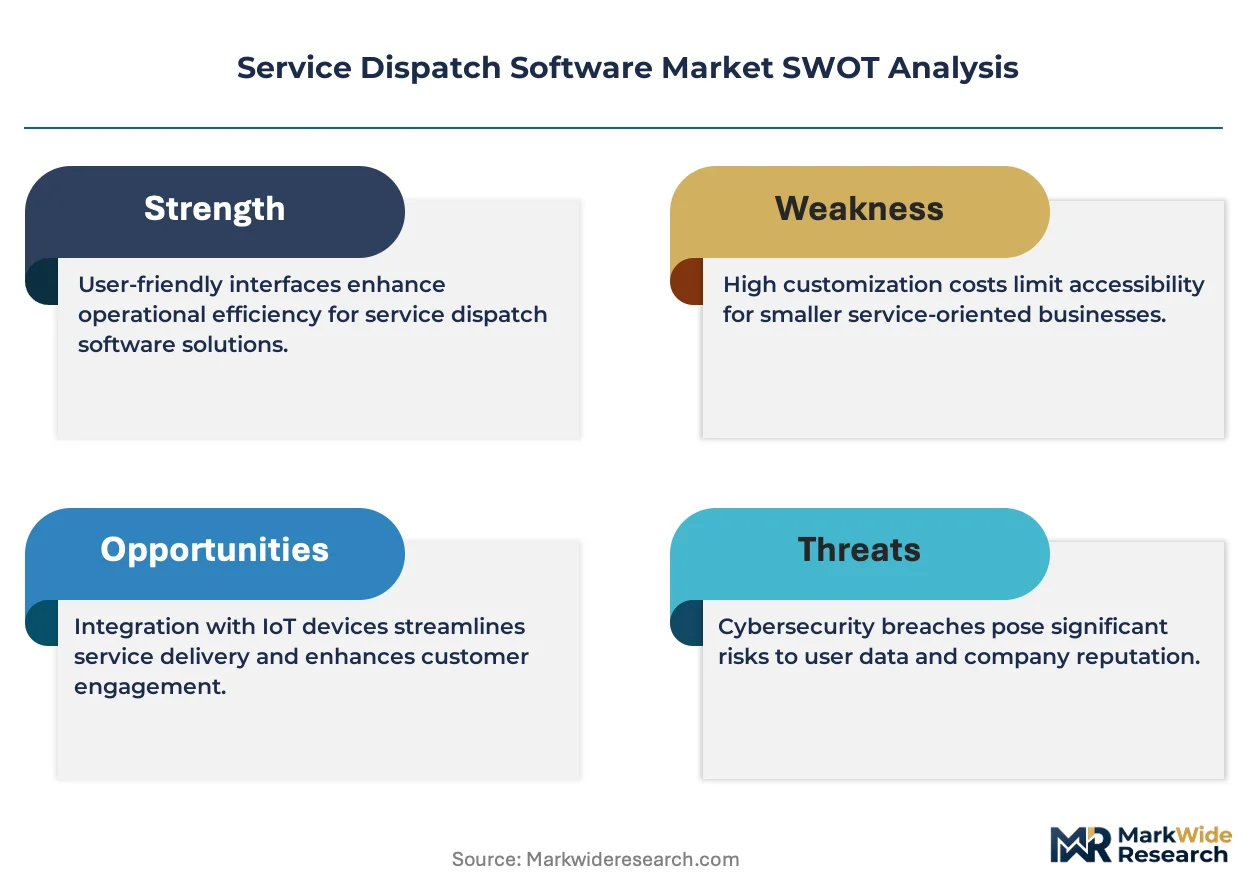
API-first architecture is rebalancing the economics of service dispatch platforms, displacing legacy monolithic codebases that demand heavy customization. ServiceTitan leverages vertical integration into payment processing and financing tools to deepen contractor retention. ServiceMax anchors its position through IoT-enabled predictive maintenance modules that sync with enterprise asset management systems. Jobber competes aggressively on price and onboarding speed for trades with under ten technicians.
Service dispatch software coordinates field technician deployment through algorithmic scheduling, GPS-based routing optimization, and real-time status tracking, typically delivered via cloud-native platforms with sub-second synchronization across mobile endpoints. Its primary purpose is minimizing travel time, reducing appointment windows, and accelerating cash conversion through automated invoicing. Cloud-based deployment now leads the market as small and mid-sized operators abandon on-premise servers, while the field service segment sustains the deepest margin pools due to recurring subscription attach rates for routing and tracking modules.
FCC guidelines on wireless spectrum allocation shape mobile connectivity standards for dispatch applications, while GDPR and the EU AI Act impose algorithmic transparency requirements on automated scheduling systems in European jurisdictions. OSHA recordkeeping mandates in the United States drive demand for integrated safety checklists within technician workflows. Stakeholders must weigh compliance costs against automation gains as regulatory fragmentation intensifies across jurisdictions.
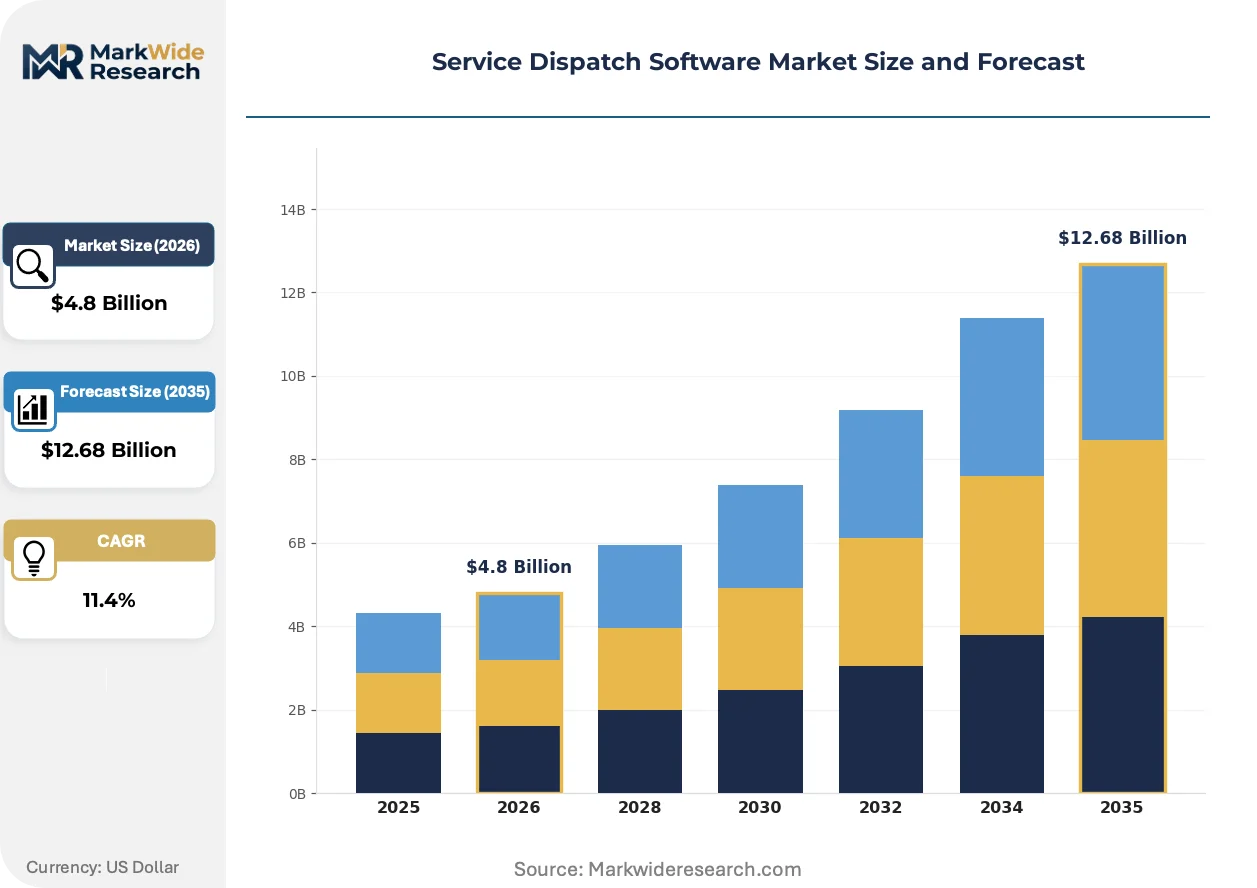
Market Dynamics
API-first architecture is modularizing service dispatch platforms and compressing deployment timelines for field service operators who previously endured multi-year customization cycles on legacy monolithic systems.
Growth Catalysts
- Cloud migration tailwinds:Small and mid-sized HVAC contractors are abandoning on-premise servers for cloud-native dispatch platforms that synchronize technician locations in sub-second intervals.
- EU AI Act compliance mandates:Automated scheduling algorithms deployed in European jurisdictions must now demonstrate algorithmic transparency, creating upgrade cycles for legacy dispatch systems.
- Integrated payment workflows:Field service operators are consolidating routing, invoicing, and cash collection into single platforms to accelerate working capital conversion.
Market Restraints
- Connectivity infrastructure gaps:Rural technician deployments in the United States suffer from FCC spectrum allocation dead zones that interrupt real-time GPS synchronization.
- Data residency requirements:GDPR and emerging national privacy frameworks fragment cloud hosting architectures, forcing redundant infrastructure investments.
- Legacy system entrenchment:Enterprise asset management integrations with decade-old ERP installations create technical debt that slows platform migration.
Strategic Opportunities
- IoT-enabled predictive maintenance:Convergence of dispatch algorithms with sensor telemetry from connected equipment allows proactive technician deployment before failure events.
- OSHA safety checklist integration:Mandated recordkeeping requirements create attach-rate opportunities for compliance modules within technician mobile workflows.
- Mid-market consolidation:Field service operators with 10-50 technicians remain underpenetrated by integrated routing-and-invoicing suites, presenting white-space expansion targets.
Industry Challenges
- API standardization delays:Absence of unified data exchange protocols between dispatch platforms and third-party CRM systems forces costly bilateral integrations.
- Technician digital literacy gaps:Aging field workforces struggle with mobile interface complexity, elevating onboarding costs and support ticket volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Dispatch Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Field Service, Repairs, Maintenance, Installations Deployment Model: On-Premise, Cloud-Based, Hybrid, Mobile End User: Manufacturing, Construction, IT Services, Transportation Feature Set: Scheduling, Routing, Tracking, Invoicing |
| Companies Covered | ServiceTitan, ServiceMax, Jobber, Housecall Pro, FieldAware, Service Fusion, Skedulo, Workiz, Zuper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Dispatch Software Market Emerging Trajectories
Dispatch platforms are compressing from monolithic suites into composable microservices that field service operators can assemble against specific workflow requirements rather than accepting bundled feature bloat.
Containerized deployment architectures are modularizing how dispatch functionality reaches field endpoints. Kubernetes-orchestrated microservices allow HVAC contractors to activate only routing, invoicing, or inventory modules without licensing unused capabilities. Mid-market operators with under fifty technicians are adopting this selective activation fastest, trimming subscription costs by thirty to forty percent against full-suite alternatives.
The EU AI Act is imposing documentation burdens on automated scheduling systems that deploy machine learning for technician assignment. European field service operators must now maintain algorithmic impact assessments and human-in-the-loop override protocols. Germany and France are seeing the earliest enforcement activity, with national regulators requesting training data audits for dispatch platforms serving utilities and municipal infrastructure.
Subscription fatigue among field service buyers is fragmenting procurement toward usage-based billing for dispatch seats rather than fixed annual contracts. Smaller trades with seasonal demand volatility prefer per-technician-month pricing that scales with headcount fluctuations. This pattern is most visible in the United States, where plumbing and electrical contractors with under ten technicians are negotiating month-to-month terms with platform vendors.
Service Dispatch Software Market Segmentation
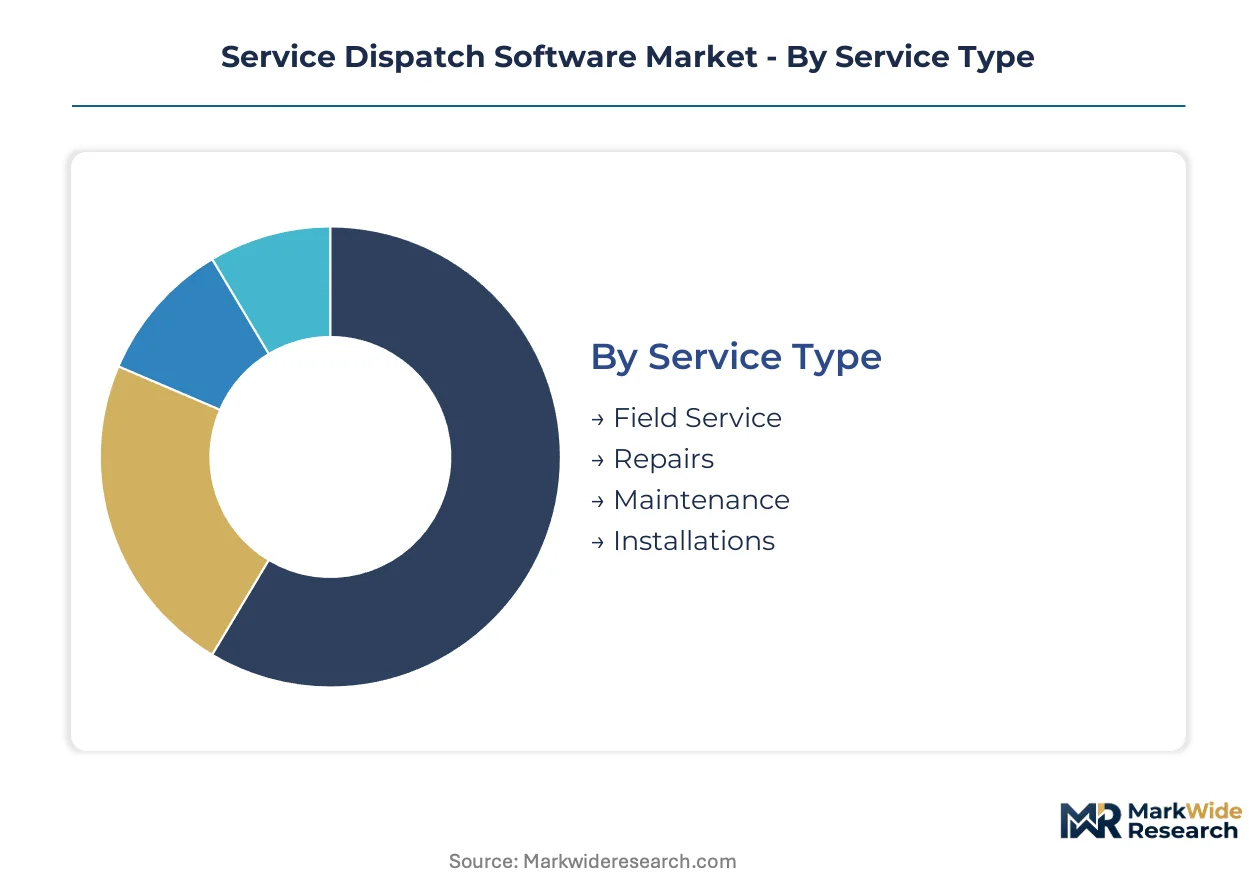
Service dispatch software vendors configure pricing and feature packaging around how technicians interact with physical assets, where data sovereignty requirements apply, and which back-office systems must synchronize. Segment boundaries reflect operational complexity rather than firm size alone.
Service Type:
Contractors select dispatch modules based on whether their work is reactive or planned, and how customer SLAs govern response windows.
- Field Service:Encompasses emergency dispatches with sub-hour response commitments. Demand clusters among utility contractors in Texas and Florida where storm recovery mandates real-time crew coordination. Hurricane seasonality drives volatile seat licensing.
- Repairs:Covers break-fix scenarios requiring parts availability lookup before technician dispatch. HVAC dealers in Arizona and Nevada prioritize this segment for compressor failure triage during peak cooling months.
- Maintenance:Planned preventive work with recurring appointment templates. Manufacturing plants in Michigan and Ohio attach this to CMMS integrations for production line uptime guarantees.
- Installations:Project-based dispatch with multi-day crew scheduling and permit tracking. Commercial construction firms in Georgia and North Carolina demand this for new build electrical and plumbing rough-ins.
Volume sits with Field Service; growth tilts toward Maintenance as predictive contracts displace reactive models.
Deployment Model:
Hosting architecture selection tracks IT staff capacity, data residency obligations, and mobile connectivity reliability in technician operating zones.
- Cloud-Based:Fully managed SaaS with automatic updates and elastic compute scaling. Small HVAC contractors across California and Illinois abandoned on-premise servers fastest after FCC spectrum improvements enabled reliable rural mobile sync.
- On-Premise:Self-hosted servers behind corporate firewalls with custom backup protocols. Defense contractors and municipal water utilities in Virginia and Maryland retain this for air-gapped security compliance.
- Hybrid:Core dispatch logic in cloud with local edge nodes for offline continuity. Mining operators in Colorado and Wyoming deploy this for pit technician coordination where cellular dead zones persist.
- Mobile:Native iOS and Android applications with offline-first architecture. Plumbing contractors with under ten technicians in Pennsylvania and New Jersey prefer lightweight mobile-only deployments to minimize IT overhead.
Cloud-Based commands current volume; Hybrid is climbing the fastest as edge computing costs decline.
End User:
Industry verticals impose distinct workflow templates, safety documentation requirements, and customer communication protocols on dispatch platforms.
- Manufacturing:Integration with enterprise asset management systems for production line downtime minimization. Automotive suppliers in Indiana and Kentucky drive demand for OT-IT converged dispatch dashboards.
- Construction:Multi-trade coordination with general contractor scheduling interfaces and union labor dispatch rules. Commercial builders in Texas and Florida require certified payroll reporting modules.
- IT Services:Ticket-to-dispatch automation with SLA breach alerting and remote diagnostic pre-qualification. Managed service providers in Massachusetts and Washington state prioritize API density for PSA tool integration.
- Transportation:Fleet-aware routing with Hours of Service compliance and DOT inspection scheduling. Trucking maintenance depots in Tennessee and Arkansas anchor this segment for over-the-road breakdown response.
Manufacturing retains the deepest installed base; IT Services is gaining share fastest as MSPs consolidate tool stacks.
Feature Set:
Module activation patterns reveal whether buyers prioritize operational efficiency, cash conversion velocity, or technician accountability.
- Scheduling:Algorithmic appointment assignment with constraint-based optimization for skills, parts, and time windows. Mid-market HVAC contractors in Ohio and Michigan treat this as the entry module before expanding to full suites.
- Routing:GPS-based path optimization with traffic ingestion and fuel cost minimization. Electrical contractors with territory density in urban New Jersey and Connecticut extract maximum value from this capability.
- Tracking:Real-time technician location with geofenced arrival verification and job duration analytics. Property management dispatchers in Arizona and Nevada deploy this for tenant communication automation.
- Invoicing:Field-generated bills with payment capture, financing offers, and accounting system sync. Plumbing contractors in Georgia and North Carolina accelerate working capital conversion through same-day mobile payment workflows.
Scheduling and Routing dominate current activation; Invoicing shows the steepest expansion trajectory as contractors prioritize cash flow over operational metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentrates among mid-market field service operators in Texas, Florida, and California, where integrated routing and invoicing capabilities command premium positioning. FCC spectrum allocation guidelines shape mobile connectivity standards for dispatch applications, while OSHA recordkeeping mandates drive integrated safety checklist adoption. Houston storm-recovery contractors deploy real-time crew coordination platforms during hurricane season, creating volatile seat licensing patterns.
United States
HVAC contractors across California and Illinois abandoned on-premise servers fastest after FCC spectrum improvements enabled reliable rural mobile synchronization. OSHA mandates integrated safety documentation within technician workflows, elevating compliance module attach rates. Dallas-Fort Worth mid-market operators consolidate routing, invoicing, and payment capture into single platforms to accelerate working capital conversion.
Germany
EU AI Act enforcement targets automated scheduling algorithms serving utilities and municipal infrastructure, forcing algorithmic transparency documentation. The national regulator requests training data audits for machine learning-based technician assignment systems. Munich automotive suppliers demand OT-IT converged dispatch dashboards for production line downtime minimization.
United Kingdom
GDPR data residency requirements fragment cloud hosting architectures, forcing redundant infrastructure investments for field service operators. The Information Commissioner's Office scrutinizes algorithmic decision-making in automated workforce deployment. London managed service providers prioritize API density for professional services automation tool integration.
Japan
METI industrial digitization programs accelerate cloud-native dispatch adoption among manufacturing plants seeking CMMS integration. JIS standards govern data exchange protocols between dispatch platforms and enterprise asset management systems. Nagoya automotive suppliers anchor demand for predictive maintenance modules synchronized with production line uptime guarantees.
Australia
TGA-equivalent privacy frameworks impose technician location data retention limits on field service operators. Mining operators in Western Australia deploy hybrid architectures with edge nodes for pit technician coordination where cellular dead zones persist. Sydney plumbing contractors with seasonal demand volatility negotiate per-technician-month pricing to match headcount fluctuations.
Service Dispatch Software Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical SaaS platforms commanding recurring revenue pools against horizontal ERP extensions. The vendor base organizes into three tiers: enterprise suites with IoT-enabled predictive modules, mid-market integrated routing-and-invoicing suites, and lightweight mobile-first tools for sub-ten-technician trades. Dominant competitive moves include API-first architecture migration displacing legacy monolithic codebases, and backward integration into payment processing to deepen contractor retention.
Within the enterprise tier, ServiceMax exemplifies IoT-enabled predictive maintenance positioning, while ServiceTitan anchors vertical integration into financing tools. Jobber occupies the aggressive price-competition vector for rapid onboarding in small-trade segments. These three represent distinct archetype strategies: sensor-telemetry convergence, financial services embedding, and friction-free adoption for underpenetrated micro-contractors.
| Leading Market Players |
|---|
| ServiceTitan |
| ServiceMax |
| Jobber |
| Housecall Pro |
| FieldAware |
| Service Fusion |
| Skedulo |
| Workiz |
| Zuper |
| Others |
Supply Flow & Price Mechanics
Enterprise-mid-market-mobile tier divergence splits the Service Dispatch Software Market into distinct economic zones where platform complexity, integration depth, and technician scale determine both subscription rates and cloud infrastructure sourcing strategies. Premium suites with IoT predictive modules command annual commitments from manufacturing plants in Germany and Japan, while lightweight mobile deployments serve seasonal plumbing contractors in Australia through per-technician-month elasticity.
Pricing Analysis
Volume concentrates in mid-market integrated suites while margin pools accrue to enterprise IoT-enabled platforms. Three-tier pricing structure across premium, standard, and economy levels reflects deployment architecture complexity, with cloud-native SaaS commanding premiums over mobile-only alternatives. Pricing pressure stems from subscription fatigue among seasonal trades seeking usage-based alternatives. Small contractors with under ten technicians exhibit highest price sensitivity, negotiating month-to-month terms; enterprise asset management integrators show lowest sensitivity due to uptime guarantee dependencies.
Supply Chain Analysis
Cloud hosting logistics and edge node freight costs concentrate supply chain leverage among hyperscale providers operating data centers in the United States, Germany, and Japan. Platform development draws from open-source container orchestration frameworks, proprietary mapping APIs, and payment processing gateways. Single-source vulnerability sits with dominant cloud infrastructure providers serving European jurisdictions under GDPR data residency mandates. Distribution runs through direct sales teams for enterprise accounts and self-service digital channels for sub-fifty-technician operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service Dispatch Software Market consolidation accelerates as API-first architecture investments force legacy monolithic vendors into acquisition or exit. Compliance burdens from the EU AI Act and OSHA recordkeeping mandates disproportionately strain undercapitalized regional players.
For Market Incumbents: Acquire specialized IoT sensor integration capabilities to deepen predictive maintenance positioning against ServiceMax's enterprise anchor. Consolidate payment processing infrastructure in-house to capture financing fee revenue streams and elevate contractor switching costs. Defend against API-first challengers by certifying algorithmic transparency documentation for European utility contracts before enforcement escalates.
For New Entrants and Emerging Players: Rural HVAC contractors with connectivity infrastructure gaps represent the most penetrable buyer archetype. Target hybrid deployment architectures with edge node offline continuity for mining operators in Colorado and Wyoming where cellular dead zones persist. Lead with per-technician-month pricing to exploit subscription fatigue among seasonal trades.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertical SaaS platforms with captive payment processing and financing tool integration. Long-term viability favors vendors demonstrating algorithmic compliance documentation for EU AI Act enforcement and OSHA safety checklist module attach rates. Watch for FCC spectrum allocation improvements in rural United States jurisdictions as inflection signal for cloud migration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Migration | Modular microservices displace monolithic codebases, compressing deployment timelines for mid-market operators. |
| IoT Predictive Maintenance Integration | Sensor telemetry convergence enables proactive technician deployment before equipment failure events. |
| Payment Processing Backward Integration | Captive financing tools deepen contractor retention and accelerate working capital conversion velocity. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation secures utility and municipal infrastructure contracts in Germany and France. |
| Hybrid Edge Node Deployment | Local compute continuity addresses cellular dead zones for mining operators in Colorado and Wyoming. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Service Dispatch Software Market analysis. Primary interviews with HVAC contractor operations managers, IT procurement officers at manufacturing plants, platform engineering leads, and field service technician supervisors combined with bottom-up and top-down triangulation. Secondary sources encompassed FCC spectrum allocation guidelines, EU AI Act enforcement documentation, OSHA recordkeeping mandates, GDPR compliance frameworks, and METI industrial digitization program disclosures.
Data-stream reconciliation across deployment model adoption curves, technician scale distributions, and feature module activation patterns shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompassed service type, deployment architecture, end-user vertical, and feature set complexity. CAGRs derived from elasticity-adjusted seat licensing trajectories and attach rate assumptions for routing, tracking, and invoicing modules. Forecast inputs incorporated cloud migration velocity among small contractors and predictive maintenance contract displacement rates.
Revisions become necessary when FCC rural spectrum allocation delays, EU AI Act enforcement escalation, or technician digital literacy gaps materialize beyond baseline assumptions. Forecasts reflect documented assumptions about API standardization timelines and edge computing cost decline curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Procure to Pay Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Patent Management Software Market
Software & Services
Europe Printing Software Market
Software & Services
Embedded Graphical User Interface (GUI) Development Software Market
Software & Services
Procurement Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Cursor Reviewer Market
Software & Services
High Education Software Market
Software & Services
Global Campaign Management Software Market
Software & Services
Application Virtualization Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Marketing Automation Software Market
Software & Services
Radio Propagation Software Market
Software & Services
Laboratory Management Software Market
Software & Services
Global Cinema Software Market