
 Sentiment Analytics Market | 2026-2036
Sentiment Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Sentiment Analytics Market Outlook
North America is fragmenting as hyperscalers and independent vendors compete for enterprise sentiment analytics contracts. IBM Watson sustains a strong position in regulated industries through compliance-oriented feature sets. Amazon Comprehend leverages AWS infrastructure to control pricing and deployment velocity for cloud-native buyers. Google Cloud NLP specializes in multilingual models that anchor its appeal across European and Asian language markets.
Sentiment analytics encompasses computational techniques that classify, quantify, and interpret emotional tone within textual, audio, or multimodal data streams, typically employing natural language processing pipelines with transformer-based architectures and domain-specific training corpora. These systems serve commercial and governmental users by converting unstructured human expression into structured intelligence for decision support. Natural language processing dominates current deployments due to its maturity in handling social media and customer feedback volumes, while deep learning represents the fastest-expanding technology segment as organizations pursue nuanced emotion detection beyond polarity scoring. Cloud-based deployment captures the majority of new implementations, though hybrid configurations retain relevance among financial and healthcare entities with data residency requirements.
The EU AI Act classifies emotion recognition systems as high-risk, mandating conformity assessments and human oversight that reshape product roadmaps for vendors serving European corporate and government end users. FDA guidance on software as a medical device intersects with sentiment analytics in digital therapeutics and mental health applications, creating additional validation burdens for healthcare-focused developers. HIPAA constraints on protected health information limit how US healthcare organizations deploy cloud-based sentiment tools without business associate agreements and encryption controls. Stakeholders must monitor evolving algorithmic accountability requirements across jurisdictions to determine where compliance investments yield sustainable market access versus competitive exclusion.
Market Dynamics
Transformer-based architectures are compressing development cycles for emotion detection systems while regulatory fragmentation across the EU AI Act, FDA guidance, and HIPAA constraints forces vendors to maintain parallel compliance roadmaps.
Growth Catalysts
- EU AI Act high-risk classification:Emotion recognition systems face mandatory conformity assessments that create certified-vendor moats for early-compliant developers serving European corporate buyers.
- Financial services real-time deployment:Trading desks and risk departments integrate sentiment streams for signal generation, with cloud infrastructure enabling sub-second latency for quantitative strategies.
- Deep learning architectures:Transformer models with domain-specific fine-tuning capture nuanced emotional states beyond polarity scoring, opening clinical and therapeutic applications.
Market Restraints
- GPU compute cost volatility:Training and inference for large language models depends on concentrated semiconductor supply from Taiwan and South Korea, creating margin pressure during shortage cycles.
- Data residency requirements:Financial and healthcare entities in Germany, Switzerland, and France mandate on-premise or sovereign-cloud deployments, limiting pure-SaaS expansion.
- Annotation bottleneck:High-quality labeled emotional datasets require specialized linguists and psychologists, with scarcity concentrated in non-English language markets.
Strategic Opportunities
- India's BIS certification pathway:The country's standards body is developing AI system classifications that will create first-mover advantages for compliant sentiment analytics vendors.
- Digital therapeutics convergence:FDA software-as-medical-device pathways for mental health applications create regulated revenue streams distinct from general enterprise SaaS.
- Edge deployment architectures:On-device inference for voice-based emotion detection opens automotive and consumer electronics channels without cloud dependency.
Industry Challenges
- Multilingual model engineering:Building performant systems across Arabic, Hindi, and East Asian languages requires native speaker networks and cultural validation that most vendors lack.
- Cross-border data transfer protocols:HIPAA business associate agreements and EU adequacy decisions create legal complexity for healthcare analytics spanning US-European patient populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sentiment Analytics Market |
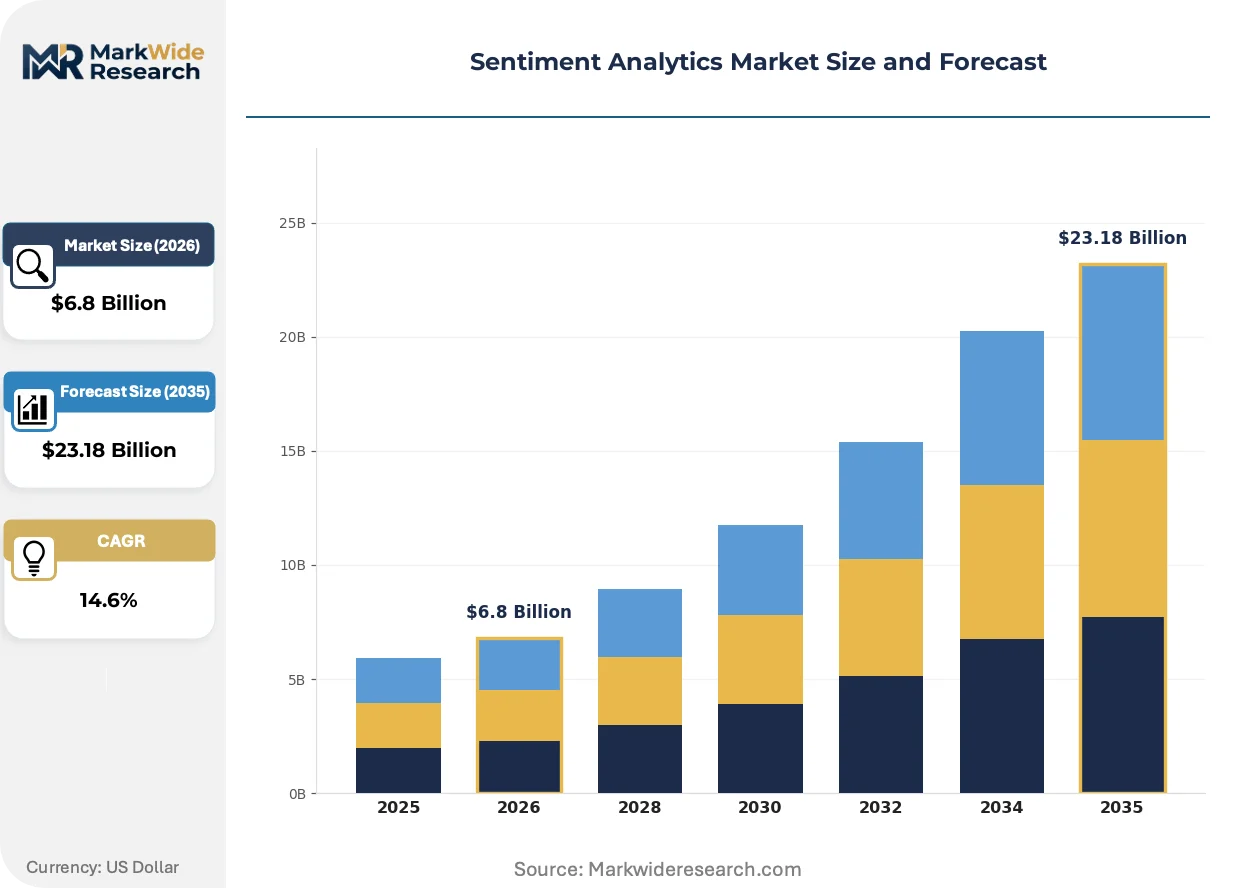
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Deep Learning, Text Analytics Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Corporate, Government, Non-Profit, Education Application: Market Research, Brand Monitoring, Customer Feedback, Social Media Analysis |
| Companies Covered | Brandwatch, Microsoft Azure Text Analytics, IBM Watson, Qualtrics, Lexalytics, Amazon Comprehend, Talkwalker, MonkeyLearn, Google Cloud NLP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sentiment Analytics Market Strategic Shifts
Sentiment analytics is pivoting from batch-processed social media monitoring toward real-time, multimodal inference across voice, text, and video streams, with architectural choices increasingly determined by regulatory jurisdiction rather than technical performance alone.
Multimodal emotion detection is migrating from research prototypes to production deployments. Automotive cabin monitoring systems and call-center quality platforms now fuse acoustic, lexical, and facial cues into unified scores. Tier-one suppliers to German and Japanese automakers are driving standardization. This migration from single-modality pipelines is compressing vendor differentiation around proprietary fusion architectures.
The EU AI Act's high-risk system obligations are reshaping product development timelines. Conformity assessments for emotion recognition in workplace and educational settings now require human-in-the-loop designs and bias auditing. Vendors serving European financial and public sector clients are reengineering inference pipelines to satisfy documentation and traceability mandates.
Subscription pricing for API-based sentiment services is fragmenting into consumption-metered and outcome-guaranteed models. Enterprise procurement teams in US healthcare and banking now demand usage-based billing with service-level agreements tied to accuracy benchmarks. This shift is most visible among Fortune 500 buyers consolidating vendor relationships around fewer, more deeply integrated platforms.
Sentiment Analytics Market Segmentation
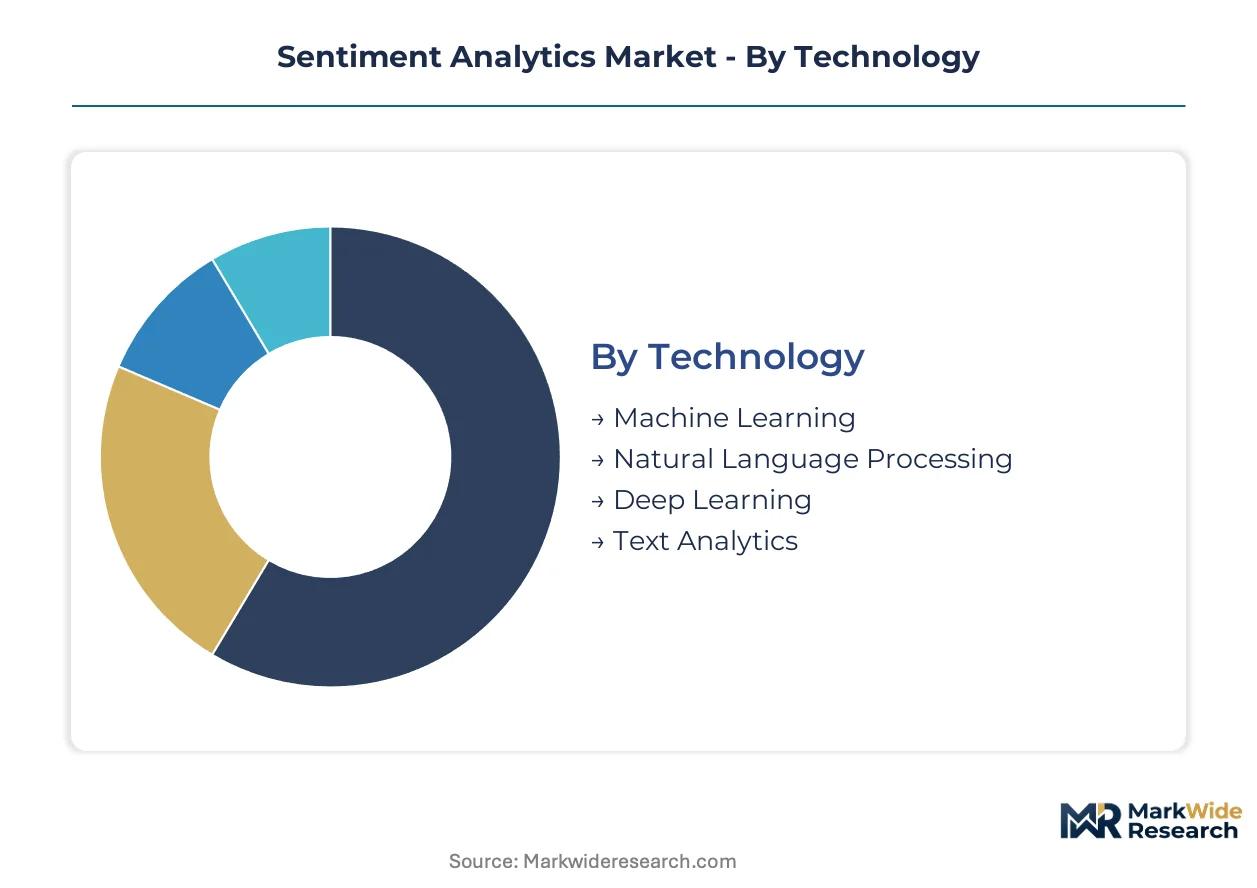
Sentiment analytics vendors structure product roadmaps around four intersecting dimensions: underlying technology, infrastructure deployment, organizational buyer type, and operational use case. Procurement cycles and compliance burdens vary sharply across these boundaries, with cloud-native financial services buyers moving fastest and regulated healthcare entities lagging by 18-24 months.
Technology:
Natural language processing commands the shortest sales cycles among established buyers, while deep learning implementations stretch pilot phases due to validation requirements for emotion detection accuracy.
- Natural Language Processing:Mature pipelines parse syntactic structure and lexical polarity across high-volume text streams. Banking call centers and social media monitoring platforms drive procurement, with transformer architectures displacing earlier bag-of-words approaches.
- Deep Learning:Neural architectures with domain-specific fine-tuning detect nuanced emotional states including sarcasm, micro-expressions, and contextual sentiment shifts. Clinical trials and automotive cabin monitoring create validation-heavy demand concentrated in Germany, Japan, and the United States.
- Machine Learning:Traditional supervised classifiers with feature engineering retain relevance for resource-constrained deployments and legacy system integration.
- Text Analytics:Statistical and rule-based extraction methods serve regulatory document processing and archival search applications where interpretability outweighs predictive precision.
Natural language processing anchors the volume base while deep learning gains share at the steepest rate.
Deployment:
Cost tiers separate segments sharply, with sovereign-cloud and edge configurations commanding 3-4x infrastructure premiums over standard public cloud offerings.
- Cloud-Based:Scalable API access with metered consumption dominates North American and Asian enterprise adoption. AWS, Azure, and Google Cloud infrastructure enables sub-second latency for real-time trading and customer service applications.
- Hybrid:Split architectures process sensitive data on-premise while leveraging cloud compute for model training. German automotive manufacturers and Swiss private banking groups mandate this configuration for GDPR and FINMA compliance.
- On-Premises:Fully captive infrastructure serves defense contractors and classified government programs with air-gapped security requirements.
- Edge Computing:On-device inference eliminates network dependency for automotive voice assistants and consumer electronics with privacy-preserving local processing.
Cloud-based deployments capture the majority of new implementations, though hybrid configurations are climbing the fastest among regulated European buyers.
End User:
Customer type determines pricing power and contract duration, with corporate procurement teams consolidating vendors while government tenders fragment awards across compliance-certified suppliers.
- Corporate:Fortune 500 technology, financial services, and retail sectors drive recurring revenue through enterprise-wide platform licenses. Procurement teams demand outcome-guaranteed SLAs with accuracy benchmarks above 85 percent.
- Government:National security, public health, and border control agencies require FedRAMP, ISO 27001, and country-specific security clearances. Contract cycles extend 18-36 months with heavy documentation burdens.
- Education:University research programs and learning analytics platforms purchase through consortia pricing, with emphasis on multilingual model access and academic citation rights.
- Non-Profit:Humanitarian monitoring and election observation groups prioritize low-cost API tiers with batch processing capabilities over real-time infrastructure.
Corporate buyers anchor the volume base while government segments are expanding most quickly following EU AI Act procurement mandates.
Application:
Use case maturity separates high-frequency transactional deployments from episodic research engagements, with customer feedback and social media analysis operating on continuous ingestion pipelines.
- Customer Feedback:Real-time analysis of support tickets, surveys, and voice transcripts enables churn prediction and service recovery. Airlines, telecommunications carriers, and subscription software vendors maintain always-on ingestion architectures.
- Social Media Analysis:Firehose access to Twitter, Reddit, and regional platforms supports crisis communications and influencer identification. Political campaigns and consumer packaged goods brands drive seasonal demand spikes.
- Brand Monitoring:Longitudinal tracking of sentiment trajectories across earned media and review aggregators informs marketing spend allocation and product launch timing.
- Market Research:Ad-hoc survey analysis and focus group transcription services operate on project-based contracting with lower technology stickiness.
Customer feedback anchors the volume base while social media analysis is gaining share at the steepest rate among political and crisis communications buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on software as a medical device intersects with sentiment analytics deployment across US healthcare systems, while the EU AI Act imposes parallel compliance burdens on emotion recognition systems serving European corporate buyers.
United States
Financial services firms in New York and Chicago deploy real-time sentiment streams for quantitative trading strategies, with cloud infrastructure enabling sub-second latency. HIPAA constraints on protected health information limit healthcare deployments without business associate agreements and encryption controls. The Boston-Cambridge corridor anchors digital therapeutics development where FDA software-as-medical-device pathways create regulated revenue streams.
Germany
Automotive manufacturers in Stuttgart and Munich drive demand for multimodal emotion detection in cabin monitoring systems. The EU AI Act mandates conformity assessments and human oversight for workplace emotion recognition applications. Frankfurt's financial sector maintains hybrid cloud configurations for FINMA compliance, processing sensitive data on-premise while leveraging cloud compute for model training.
United Kingdom
London's banking sector integrates sentiment tools for risk assessment and trading signal generation, with procurement teams demanding outcome-guaranteed service level agreements. The Information Commissioner's Office enforces GDPR-aligned accountability for automated decision systems processing emotional data. Cambridge and Oxford research clusters advance transformer-based architectures for clinical emotion detection applications.
India
Bengaluru's enterprise software sector and Mumbai's financial services industry drive cloud-based sentiment analytics adoption across customer feedback and social media monitoring use cases. The Bureau of Indian Standards is developing AI system classifications that will create first-mover advantages for compliant vendors. Hyderabad's technology corridor hosts multilingual model engineering efforts targeting Hindi, Tamil, and Telugu language markets.
Japan
Tokyo's automotive suppliers and Osaka's consumer electronics manufacturers pioneer edge deployment architectures for on-device emotion detection. METI standards for AI quality and safety shape product development timelines for vendors serving domestic industrial buyers. Nagoya's manufacturing cluster drives standardization efforts for voice-based sentiment analysis in industrial human-machine interfaces.
Sentiment Analytics Market Competitive Environment
Capability concentration sits with specialized vendors holding domain-specific training corpora and linguistic expertise; scale advantage sits with hyperscalers leveraging cloud infrastructure for pricing and deployment velocity. The market structures around three tiers: compliance-oriented incumbents serving regulated industries, cloud-native platforms capturing high-volume transactional demand, and boutique specialists anchoring premium pricing through multilingual and multimodal depth. Dominant competitive moves include strategic partnerships with automotive and healthcare OEMs, plus geographic expansion through sovereign-cloud configurations for data residency requirements.
Within the compliance-oriented tier, IBM Watson represents the archetype of regulated-industry positioning, while Microsoft Azure Text Analytics and Amazon Comprehend exemplify scale-driven cloud-native deployment models. Google Cloud NLP occupies a position anchored in multilingual model depth across European and Asian language markets. These three hyperscalers collectively shape procurement expectations around consumption-metered billing and accuracy-benchmarked service level agreements.
| Leading Market Players |
|---|
| Brandwatch |
| Microsoft Azure Text Analytics |
| IBM Watson |
| Qualtrics |
| Lexalytics |
| Amazon Comprehend |
| Talkwalker |
| MonkeyLearn |
| Google Cloud NLP |
| Others |
Value Chain & Pricing Dynamics
GPU compute cost volatility from concentrated semiconductor supply in Taiwan and South Korea compresses margin structures across deployment tiers while forcing vendors toward hybrid architectures that balance performance against sovereign-cloud premiums.
Pricing Analysis
Geographic price spreads separate North American cloud-native deployments from European hybrid configurations by three-to-fourfold infrastructure premiums. Subscription SaaS-tiered models dominate API-based sentiment services, with consumption-metered billing displacing flat-rate licenses among Fortune 500 procurement teams. Price differentiation rests on certification grade—EU AI Act conformity assessments and FDA software-as-medical-device pathways command substantial premiums over standard enterprise tiers. Pricing pressure stems from hyperscaler margin compression in raw compute layers, with Amazon Comprehend and Google Cloud NLP driving benchmark SLAs above 85 percent accuracy. Government and healthcare segments exhibit lowest price sensitivity due to compliance-driven vendor consolidation, while mid-market corporate buyers in retail and telecommunications drive hardest bargain.
Supply Chain Analysis
Tariff exposure between United States and China dominates risk planning for on-premise hardware deployments and edge inference chip sourcing. Supply concentrates in Taiwan for advanced GPU fabrication, South Korea for HBM memory modules, and United States for cloud hyperscaler infrastructure. Raw material dependencies span NVIDIA A100/H100 accelerators, specialized AI training silicon from TSMC foundries, and high-bandwidth memory stacks from Samsung and SK Hynix. Single-source vulnerability in TSMC's leading-edge node capacity creates procurement bottlenecks during shortage cycles. Distribution runs through AWS, Azure, and Google Cloud direct sales organizations for cloud deployments, with systems integrators and regional VARs handling hybrid and on-premise implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
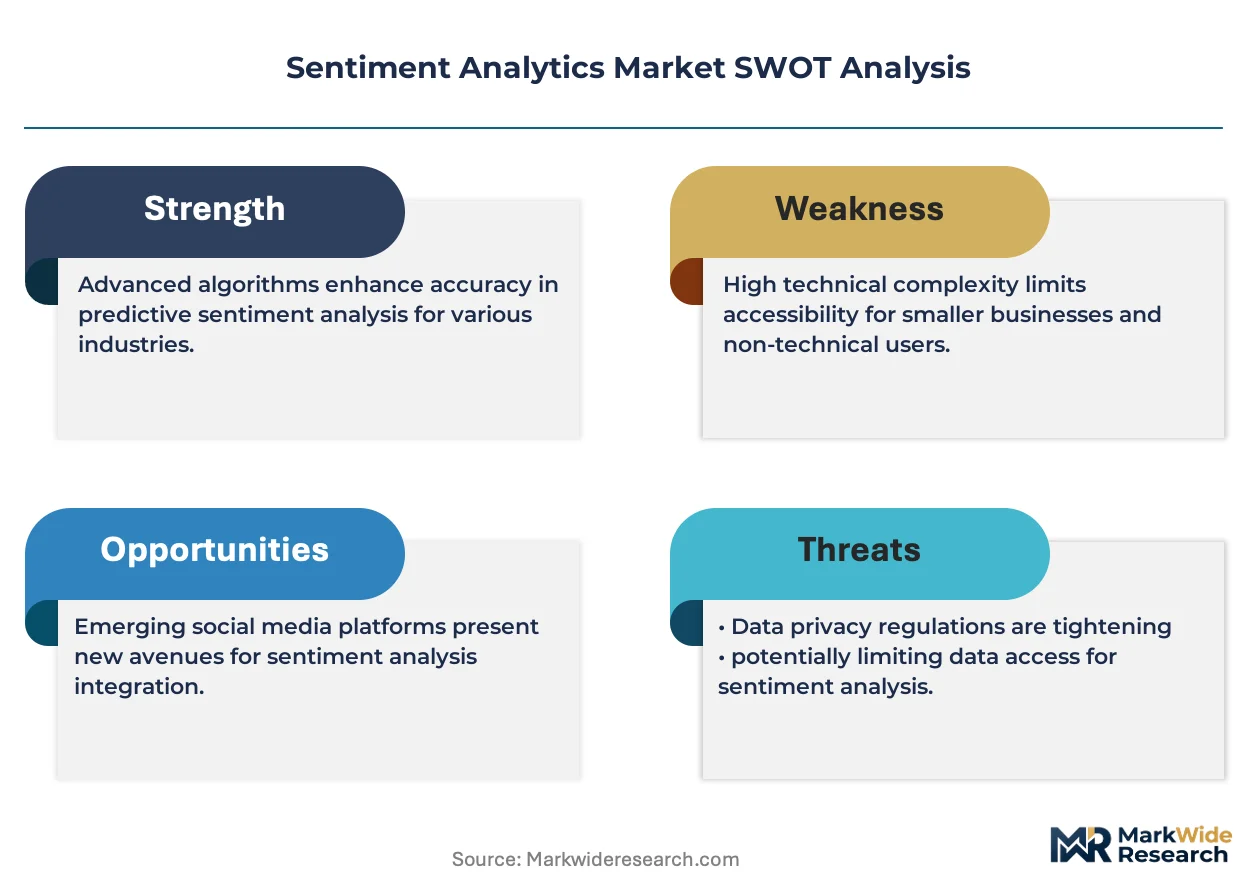
Open-source large language models threaten to commoditize baseline polarity scoring, forcing incumbents to defend positioning through regulatory certification depth and multimodal fusion architectures.
For Market Incumbents: Entrench compliance moats by accelerating EU AI Act conformity assessments and FDA software-as-medical-device pathways ahead of open-source model maturation. Acquire specialized annotation firms with native speaker networks in Arabic, Hindi, and East Asian languages to defend multilingual differentiation. Prioritize backward integration into domain-specific training corpora for clinical and automotive applications where labeled emotional datasets create scarcity value. For New Entrants and Emerging Players: India's BIS certification pathway represents the most penetrable entry point before standards crystallize around incumbent-compliant vendors. Edge deployment architectures for automotive cabin monitoring and consumer electronics voice assistants offer white-space opportunity unclaimed by hyperscaler API dominance. Pursue OEM partnership routes with Tier 1 automotive suppliers in Germany and Japan rather than direct enterprise SaaS competition. For Investors and Strategic Acquirers: Boutique specialists holding proprietary multimodal fusion architectures and non-English linguistic depth command scarcity premiums in consolidation scenarios. Long-term viability hinges on regulatory certification durability rather than raw model performance gains. Watch FDA software-as-medical-device approval velocity as inflection indicator for healthcare sentiment analytics valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Creates certified-vendor moats for emotion recognition systems serving European corporate buyers. |
| Multimodal Fusion Architecture Development | Enables unified acoustic-lexical-facial scoring for automotive cabin monitoring and call-center quality platforms. |
| Domain-Specific Training Corpus Acquisition | Secures labeled emotional datasets in clinical and therapeutic applications with high annotation barriers. |
| Edge Inference Chip Partnership | Opens automotive and consumer electronics channels without cloud dependency or data residency complications. |
| Sovereign-Cloud Configuration Expansion | Addresses FINMA and GDPR requirements for German automotive and Swiss private banking hybrid deployments. |
Study Parameters
The analysis maps natural language processing pipelines, deep learning emotion detection systems, cloud-based API services, and edge inference architectures, each validated through primary interviews with sentiment analytics product managers, enterprise AI procurement officers, regulatory compliance leads, and automotive Tier 1 supplier technology directors. Secondary sources include SEC filings from hyperscaler platforms, EU AI Act implementation guidance, FDA software-as-medical-device guidance documents, and cloud infrastructure capex disclosures. Bottom-up triangulation across vendor revenue estimates and top-down validation against enterprise software spending patterns anchor volume and value outputs.
Assumption sets held regulatory enforcement timelines and GPU supply availability fixed while varying enterprise adoption velocity and multimodal deployment penetration across the projection horizon. Segmentation dimensions modeled span technology type, deployment infrastructure, end-user organization category, and operational application with regional regulatory cluster overlays. CAGRs derive from installed base growth rates and average revenue per account expansion trajectories, with transformer architecture development cycles and annotation labor market constraints as sentiment-specific forecast inputs.
Stress conditions across GPU supply shocks, EU AI Act enforcement stringency, and open-source model capability advancement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and hyperscaler pricing discipline. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
ASEAN Geospatial Analytics Market
Analytics
China Contact Center Analytics Market
Analytics
APAC Data Wrangling Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Cloud Analytics Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
Manufacturing Predictive Analytics Market
Analytics
APAC Retail Analytics Market
Analytics
Network Traffic Analytics Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Italy ICT Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
FMCG Spending on Analytics Market
Analytics
Connected Device Analytics Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Global Business Intelligence (BI) Software Market