
 Global Business Intelligence (BI) Software Market | 2026-2036
Global Business Intelligence (BI) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Intelligence (BI) Software Market Foresight
Data engineering talent scarcity is rotating enterprise priorities toward self-service analytics platforms that reduce dependency on specialized IT staff. Microsoft Corporation leverages its Azure cloud infrastructure to embed Power BI across Office 365 workflows. SAP SE anchors its competitive position through deep ERP integration that unifies operational and analytical data layers. Tableau Software, Inc. differentiates via intuitive visualization interfaces that accelerate citizen data scientist adoption.
Business intelligence software encompasses platforms that extract, transform, and analyze structured and unstructured data to generate actionable insights, typically processing petabyte-scale datasets through in-memory computing architectures and natural language query interfaces. Its primary commercial purpose is to reduce decision latency by surfacing predictive patterns from enterprise data reservoirs. Cloud-based deployment now captures the dominant margin pool as organizations abandon capital-intensive on-premises infrastructure. Predictive analytics represents the fastest-expanding solution type, driven by embedded machine learning modules that forecast demand fluctuations and customer churn. Customer analytics applications command premium pricing due to the direct revenue linkage of personalization engines.
FDA oversight of clinical decision support tools and the EU AI Act's risk-based classification system for automated analytics are tightening algorithmic transparency requirements across healthcare and financial deployments. ISO 27001 and SOC 2 Type II certifications have become baseline prerequisites for vendor selection in regulated industries. Stakeholders must weigh interoperability commitments against the accelerating pace of generative AI integration that threatens to obsolete traditional dashboard-centric architectures.
Market Dynamics
The EU AI Act's risk-based classification system for automated analytics is compressing deployment timelines and forcing vendors to rearchitect algorithmic transparency layers across healthcare and financial services deployments.
Growth Catalysts
- EU AI Act compliance mandates:Financial services firms in Germany and France must upgrade decision-support systems to meet explainability requirements, triggering platform replacement cycles.
- Healthcare interoperability frameworks:FDA-cleared clinical decision support tools are expanding embedded analytics penetration across US hospital networks.
- Cloud-native enterprise migration:Retail and healthcare sectors in the United States are abandoning on-premises data warehouses for elastic consumption models.
Market Restraints
- Specialized talent scarcity:Data engineering skill gaps inflate implementation costs and extend deployment timelines for complex ETL pipelines.
- Certification backlog:ISO 27001 and SOC 2 Type II audit queues create six-to-nine month vendor qualification delays in regulated industries.
- Legacy system entanglement:Decades-old ERP investments in manufacturing and logistics sectors obstruct cloud-native BI adoption.
Strategic Opportunities
- Generative AI convergence:Natural language interfaces paired with predictive modules are opening self-service analytics to non-technical users in mid-market enterprises.
- India's digital public infrastructure:Account Aggregator framework and UPI data streams create native demand for real-time consumer analytics platforms.
- Japan's healthcare digitization:METI incentives for AI-enabled diagnostic tools are accelerating clinical BI procurement in Tokyo-Osaka medical corridors.
Industry Challenges
- Embedded machine learning explainability:Black-box algorithm documentation requirements under EU AI Act consume substantial product engineering resources.
- Cross-border data residency:Conflicting sovereignty rules between GDPR, China's PIPL, and sector-specific US regulations fragment cloud architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Intelligence (BI) Software Market |
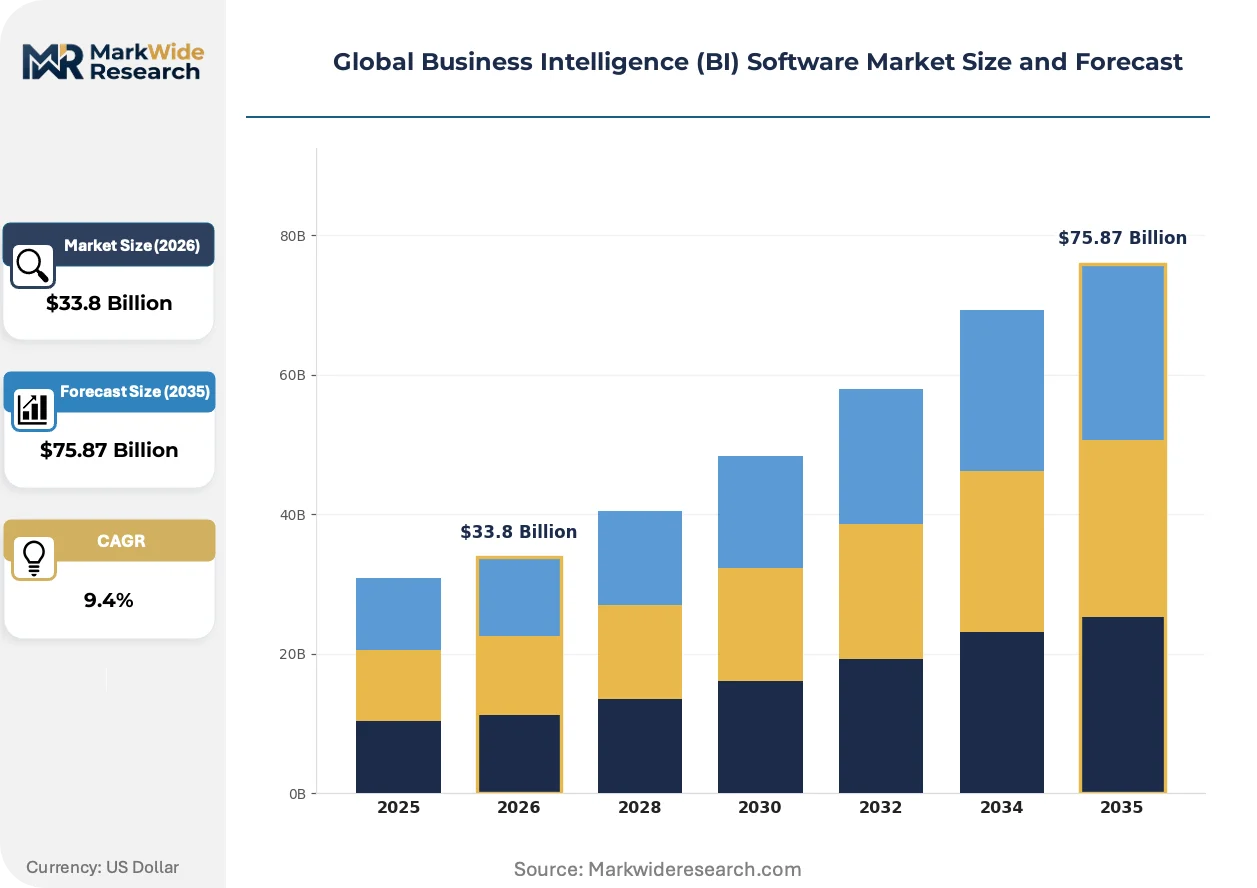
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $75.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud, SaaS Solution Type: Data Visualization, Predictive Analytics, Reporting, OLAP, Data Mining, Performance Management Application: Customer Analytics, Risk Management, Supply Chain Optimization, Sales Intelligence, Fraud Detection, Market Analysis End User Industry: Telecommunications, Manufacturing, Government, Education, Transportation, Energy |
| Companies Covered | Microsoft Corporation, SAP SE, Oracle Corporation, International Business Machines Corporation, Tableau Software, Inc., SAS Institute Inc., QlikTech International AB, MicroStrategy Incorporated, TIBCO Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Intelligence (BI) Software Market Shifts & Advancements
Natural language query interfaces and generative AI modules are compressing the traditional dashboard-to-insight pipeline, forcing incumbent vendors to rearchitect core product architectures around conversational analytics.
In-memory computing architectures with embedded vector databases are displacing disk-based OLAP systems that dominated enterprise data warehousing for two decades. Fortune 500 retailers and healthcare networks are adopting these platforms to support sub-second predictive queries. The structural consequence is collapsing hardware refresh cycles and compressing price premiums for traditional database management licenses.
The EU AI Act's mandatory algorithmic impact assessments for high-risk automated decision systems are reshaping vendor liability frameworks across European deployments. Healthcare and credit-scoring applications face the steepest compliance burdens. German and French insurers are now requiring contractual indemnification clauses that transfer audit costs to platform providers.
Enterprise procurement of analytics capabilities is fragmenting from monolithic platform licenses toward modular, API-consumable microservices. Line-of-business buyers in US retail and healthcare are bypassing centralized IT procurement to acquire specialized customer analytics modules. This pattern concentrates purchasing authority with chief marketing officers and clinical operations leaders rather than CIOs.
Global Business Intelligence (BI) Software Market Segmentation
BI software segmentation reveals where vendor profitability concentrates and how procurement authority is fragmenting across technical and functional dimensions. Deployment architecture and solution type together determine pricing power, while application focus shapes customer lifetime value.
Deployment:
Cloud-based deployment captures the dominant margin pool as elastic consumption models displace capital-intensive infrastructure commitments.
- Cloud-Based:Multi-tenant architectures with auto-scaling compute layers dominate new procurement in United States retail and healthcare networks. AWS, Azure, and Google Cloud infrastructure underpins vendor cost structures and customer switching costs.
- SaaS:Subscription pricing with embedded maintenance and automatic feature updates appeals to mid-market enterprises lacking dedicated data engineering staff. Procurement concentrates among line-of-business buyers bypassing centralized IT.
- On-Premises:Legacy installations in German manufacturing and Japanese automotive sectors resist migration due to data residency requirements and sunk capital.
- Hybrid:Split architectures process sensitive workloads locally while bursting analytics to public cloud during peak demand.
- Private Cloud:Single-tenant deployments satisfy French and Italian financial services firms under strict CNIL and Bank of Italy oversight.
Cloud-based deployment holds the dominant share, while SaaS is climbing the fastest as procurement authority shifts to business-unit leaders.
Solution Type:
Volume concentrates in visualization and reporting modules, though predictive analytics commands the steepest price premiums.
- Predictive Analytics:Embedded machine learning modules forecast demand fluctuations and customer churn using petabyte-scale training datasets. Demand concentrates in United States financial services for real-time risk modeling and credit scoring.
- Data Visualization:Drag-and-drop interfaces accelerate citizen data scientist adoption across non-technical user bases. Intuitive design reduces training costs and implementation timelines for mid-market deployments.
- Reporting:Scheduled distribution of standardized dashboards remains prevalent in regulated industries requiring audit trails.
- OLAP:Multidimensional cube analysis persists in legacy enterprise data warehouses despite displacement by in-memory computing.
- Data Mining:Pattern discovery algorithms process unstructured text and behavioral signals for marketing segmentation.
- Performance Management:KPI tracking and scorecarding align operational metrics with strategic objectives in large conglomerates.
Data Visualization maintains the largest installed base, though Predictive Analytics is gaining share fastest as embedded AI modules mature.
Application:
Customer-facing applications extract premium pricing due to direct revenue linkage, while risk and fraud modules face stringent regulatory validation.
- Customer Analytics:Personalization engines segment audiences for targeted campaigns and dynamic pricing. United States e-commerce and retail sectors drive procurement as first-party data strategies replace deprecating third-party cookies.
- Risk Management:Real-time scoring models for credit, market, and operational risk require explainable algorithmic outputs under EU AI Act mandates. German and French insurers demand contractual indemnification from platform providers.
- Sales Intelligence:Pipeline forecasting and opportunity scoring integrate with CRM workflows to accelerate revenue operations.
- Fraud Detection:Anomaly detection in payment streams and claims processing faces FDA-equivalent scrutiny for automated decision systems.
- Supply Chain Optimization:Demand sensing and inventory positioning algorithms reduce working capital in volatile commodity environments.
- Market Analysis:Competitive intelligence and pricing surveillance support strategic planning in fragmented B2B sectors.
Customer Analytics commands the highest pricing tiers, while Risk Management is expanding most quickly under regulatory pressure for automated transparency.
End User Industry:
Procurement maturity varies sharply, with telecommunications and energy leading technical sophistication while government and education lag in cloud adoption.
- Telecommunications:Network optimization and churn prediction leverage real-time streaming analytics across subscriber bases. Indian and Brazilian carriers invest heavily as 5G rollout accelerates data generation.
- Manufacturing:Predictive maintenance and quality control integrate with IoT sensor networks on factory floors. German and Japanese automotive suppliers anchor demand for edge-computing analytics.
- Energy:Grid balancing and renewable forecasting require sub-second predictive queries across distributed generation assets.
- Government:Procurement cycles extend twelve to eighteen months due to public tender requirements and security clearance protocols.
- Transportation:Route optimization and fleet management compete with specialized logistics software for budget allocation.
- Education:Student retention and learning analytics remain underpenetrated outside United States research universities and ed-tech platforms.
Telecommunications holds the deepest analytics penetration, while Manufacturing is closing the gap fastest through Industry 4.0 investment waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises favor cloud-native elastic consumption models, while German and Japanese buyers prioritize data sovereignty through private cloud and hybrid architectures. This consumption-mix differential fragments vendor go-to-market strategies across major economies.
United States
Healthcare networks and retail chains drive cloud-native BI procurement through AWS, Azure, and Google Cloud infrastructure. FDA oversight of clinical decision support tools tightens algorithmic documentation requirements for hospital deployments. The Boston-Cambridge medical corridor and Seattle tech cluster anchor demand for real-time predictive analytics platforms.
Germany
Automotive suppliers and industrial conglomerates invest in edge-computing analytics for predictive maintenance and quality control. The EU AI Act's risk-based classification system forces explainability upgrades for credit-scoring and insurance decision systems. Munich and Stuttgart manufacturing belts concentrate procurement of ERP-integrated BI solutions.
Japan
METI incentives for AI-enabled diagnostic tools accelerate clinical BI procurement across Tokyo-Osaka medical corridors. Pharmaceutical regulators require algorithmic transparency documentation for automated patient risk stratification. Automotive suppliers in Aichi Prefecture deploy IoT-integrated analytics for factory-floor quality control.
India
The Account Aggregator framework and UPI data streams create native demand for real-time consumer analytics platforms. RBI guidelines on data localization influence cloud architecture decisions for financial services deployments. Bengaluru and Mumbai fintech clusters drive procurement of embedded machine learning modules for credit underwriting.
United Kingdom
Financial services firms in the City of London upgrade decision-support systems for EU AI Act compliance despite post-Brexit regulatory divergence. FCA scrutiny of algorithmic trading tools elevates documentation standards for automated risk models. The London-Edinburgh axis concentrates procurement of cloud-based regulatory reporting solutions.
Global Business Intelligence (BI) Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across deployment architectures and vertical applications. The upper tier commands pricing power through cloud infrastructure integration and ERP ecosystem lock-in. Specialist players occupy positions in visualization interfaces, embedded machine learning, and industry-specific compliance modules. Competitive moves concentrate on generative AI convergence and API-consumable microservices that bypass centralized IT procurement.
Among integrated platform providers, Microsoft Corporation and SAP SE exemplify contrasting ecosystem strategies. Microsoft leverages Azure infrastructure to embed analytics across productivity workflows, while SAP anchors positioning through operational-analytical data unification. Tableau Software, Inc. occupies a position within the visualization specialist tier, representing the citizen data scientist adoption vector that reduces enterprise dependency on specialized engineering staff.
| Leading Market Players |
|---|
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| International Business Machines Corporation |
| Tableau Software, Inc. |
| SAS Institute Inc. |
| QlikTech International AB |
| MicroStrategy Incorporated |
| TIBCO Software Inc. |
| Others |
Supply & Pricing Matrix
Cloud infrastructure substitution for on-premises data centers is simultaneously redrawing vendor cost structures and compressing enterprise pricing power across deployment tiers. This displacement concentrates procurement leverage with hyperscaler-aligned platform providers while fragmenting margin pools for legacy license-dependent vendors.
Pricing Analysis
Long-term SaaS subscription contracts dominate enterprise procurement, though project-based professional services retain pricing premiums for complex ERP integration engagements. Price differentiation separates ISO 27001-certified deployments from baseline tiers, with SOC 2 Type II attestation commanding additional premiums in financial services. Cost compression in mid-market SaaS tiers is intensifying because citizen data scientist tools reduce implementation service attach rates. Small and mid-sized enterprises exhibit the highest price sensitivity, while Fortune 500 healthcare networks demonstrate lowest elasticity due to compliance-driven vendor consolidation.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for specialized GPU hardware provisioning cloud analytics infrastructure. Geographic supply concentration centers on Taiwan for advanced semiconductor fabrication, South Korea for memory components, and the United States for hyperscaler data center buildouts. Raw material dependencies include high-bandwidth memory modules, specialized AI accelerators, and rare earth elements for server manufacturing. Single-source vulnerability in advanced node chip fabrication represents the dominant structural risk. Distribution runs through direct hyperscaler marketplaces and authorized systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise software procurement cycles are recovering from post-pandemic budget compression, with cloud-native analytics spend leading the rebound as organizations prioritize operational efficiency investments.
For Market Incumbents: Shield installed base revenue through embedded generative AI modules that raise switching costs across Office 365 and ERP-integrated workflows. Accelerate ISO 27701 privacy certification investment to preempt EU AI Act audit requirements that threaten contract renewals in German and French financial services. Prioritize backward integration into vector database technology to capture margin from the fastest-expanding predictive analytics tier. For New Entrants and Emerging Players: SOC 2 Type II fast-track programs open immediate access to mid-market healthcare and retail procurement queues that bypass lengthy enterprise IT reviews. India's Account Aggregator ecosystem and UPI data infrastructure present the most penetrable geography for real-time consumer analytics deployment. A channel-first go-to-market through AWS Marketplace and Azure Marketplace reduces customer acquisition friction against direct sales-dependent incumbents. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors specialized machine learning explainability tools over horizontal platform consolidation. Long-term viability hinges on regulatory compliance automation capabilities that deepen enterprise dependency across the projection horizon. Acquisition targets should demonstrate embedded vector database architecture and EU AI Act documentation workflows. The signal to watch is hyperscaler partnership tier elevation, which indicates distribution leverage and validates technical integration depth.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Module Integration | Natural language interfaces from Microsoft and SAP compress dashboard-to-insight timelines for non-technical users. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation from German and French insurers mandates vendor liability restructuring. |
| Hyperscaler Marketplace Expansion | AWS and Azure distribution channels bypass centralized IT procurement for line-of-business analytics buyers. |
| Vector Database Architecture Investment | In-memory computing with embedded vector stores displaces disk-based OLAP in Fortune 500 retail networks. |
| India Digital Infrastructure Partnership | Account Aggregator framework integration captures UPI data streams for real-time credit underwriting platforms. |
Research Methodology
The analysis maps cloud deployment models, predictive analytics modules, and vertical application stacks, each validated through CTO interviews, IT procurement officers, platform integration specialists, and channel partner executives. Primary fieldwork combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie enterprise software rankings, and EU regulatory filings established demand-side triangulation. Bottom-up segment sizing and top-down macro anchoring ensured cross-verification across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across deployment architecture, organization size tiers, vertical adoption patterns, and regional regulatory clusters. CAGRs were derived from segment-level growth trajectory modeling and cross-referenced with disclosed vendor revenue patterns. Forecast inputs incorporated EU AI Act implementation timelines, FDA clinical decision support guidance evolution, and cloud infrastructure capacity expansion announcements from major hyperscalers.
Decision-makers should treat outputs as directional under assumptions of sustained cloud migration momentum and regulatory compliance cost pass-through; material deviation in hyperscaler pricing or sovereign data localization mandates would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Canada Contact Center Analytics Market
Analytics
Analytics Sandbox Market
Analytics
Asia-Pacific Emotion Analytics Market
Analytics
Europe Operational Intelligence Market
Analytics
Spend Analytics Software Market
Analytics
Content Intelligence Market
Analytics
Data Analytics in Telecom Market
Analytics
Human Resource Analytics Market
Analytics
Scientific Text Analytics and Annotators Market
Analytics
US Predictive Analytics Market
Analytics
Global Social Intelligence Market
Analytics
Mobile App Attribution Tool Market
Analytics
Lead Intelligence Software Market
Analytics
Latin America Big Data Analytics Market
Analytics
Automated Analytics Market
Analytics
Global Streaming Analytics Market