
 Network Traffic Analytics Market | 2026-2036
Network Traffic Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Network Traffic Analytics Market Analysis
Subscription-based financing and managed-service leasing is tilting competitive dynamics toward vendors with recurring-revenue infrastructure. NETSCOUT Systems sustains deep packet inspection leadership through hardware-software integration. Palo Alto Networks leverages cloud-native architecture to capture hybrid deployment contracts. Kentik Technologies specializes in SaaS delivery models that lower upfront barriers for mid-market buyers.
Network traffic analytics encompasses the real-time capture, processing, and interpretation of data packets traversing digital infrastructure, typically operating at line rates exceeding 100 Gbps while applying machine learning classification to detect anomalies, optimize quality-of-service, and enforce security policies. The technology serves critical commercial and industrial purposes including DDoS mitigation, application performance management, and forensic investigation of security incidents. Cloud-based deployment now captures the fastest expansion as enterprises abandon capital-intensive on-premise appliance refresh cycles. Security analytics applications command the deepest margin pools due to regulatory pressure and breach-cost escalation. Deep packet inspection retains structural importance in carrier networks where encrypted traffic visibility remains essential for lawful intercept and traffic engineering.
The Federal Communications Commission shapes US market access through net-neutrality enforcement and critical infrastructure designation, while the European Union AI Act imposes algorithmic transparency requirements on automated traffic classification systems. ISO 27001 and the NIST Cybersecurity Framework further constrain product architecture decisions for vendors seeking federal and enterprise procurement channels. Stakeholders must monitor how quantum-resistant encryption standards will force next-generation deep packet inspection architectures.
Market Dynamics
Encrypted traffic now exceeds ninety percent of carrier backbone volume, forcing deep packet inspection vendors to deploy TLS 1.3 decryption proxies and machine learning inference at the network edge. This cryptographic shift is compressing legacy hardware refresh cycles and elevating software-defined visibility platforms.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated traffic classification systems in European telecom networks must now maintain auditable decision logs, creating compliance-driven replacement demand for legacy black-box analytics engines.
- 5G standalone core deployment:Telecom service providers in Germany, Japan, and the United States are instrumenting service-based architecture interfaces with real-time analytics to manage network slicing quality-of-service guarantees.
- Quantum-resistant encryption standards:NIST post-quantum cryptography guidelines are accelerating carrier investment in next-generation traffic inspection capable of handling Kyber and Dilithium handshake protocols without latency degradation.
Market Restraints
- Silicon supply concentration:Merchant silicon for 100Gbps+ network processors concentrates among three foundry sources in Taiwan, creating procurement risk for appliance vendors dependent on custom ASIC refresh cycles.
- GDPR data localization friction:Cross-border traffic analysis for multinational enterprises requires region-segregated processing infrastructure, elevating operational complexity and duplicative capital deployment.
- Homomorphic encryption emergence:Privacy-preserving computation techniques threaten long-term demand for plaintext deep packet inspection in sensitive verticals including healthcare and financial services.
Strategic Opportunities
- Federal critical infrastructure mandates:CISA directive 23-01 in the United States compels energy and water utilities to deploy continuous network monitoring, opening a regulated procurement channel previously served by basic firewall logging.
- India telecom infrastructure expansion:Reliance Jio and Bharti Airtel 5G rollouts lack indigenous traffic analytics capabilities, creating white space for managed service providers with localized data center presence.
- eBPF kernel instrumentation convergence:Cloud-native observability platforms are merging with security analytics through extended Berkeley Packet Filter technology, enabling unified vendor positioning across IT and network operations centers.
Industry Challenges
- ML model operations talent scarcity:Carrier procurement teams struggle to evaluate vendor claims of encrypted traffic classification accuracy due to shortage of staff with both telecommunications and machine learning engineering competencies.
- ISO 27001 certification timeline compression:Enterprise buyers now demand twelve-week security audit completion rather than historical six-month cycles, straining vendor documentation and evidence-collection workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Traffic Analytics Market |
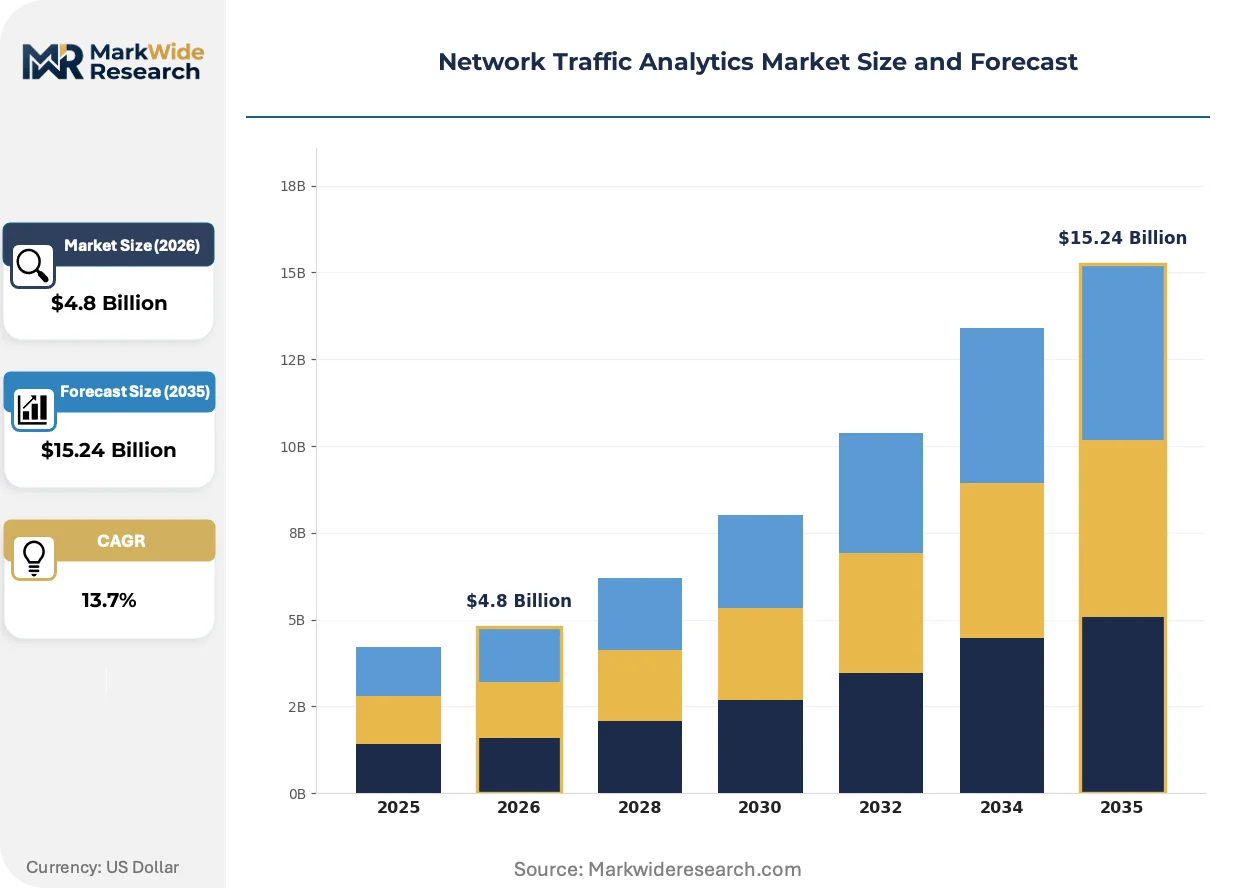
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Application: Network Performance Monitoring, Security Analytics, User Behavior Analytics, Compliance Management End User: Enterprises, Service Providers, Government Agencies, Educational Institutions Technology: Machine Learning, Big Data Analytics, Artificial Intelligence, Deep Packet Inspection |
| Companies Covered | SolarWinds Corporation, Juniper Networks Inc., NETSCOUT Systems Inc., Fortinet Inc., IBM Corporation, Cisco Systems Inc., Kentik Technologies Inc., ExtraHop Inc., Palo Alto Networks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Traffic Analytics Market Emerging Trajectories
Traffic analytics architecture is bifurcating between centralized cloud processing for enterprise security operations and distributed edge inference for carrier latency-sensitive applications. This dual-deployment pattern is fragmenting vendor roadmaps and elevating hybrid orchestration capabilities.
eBPF-based kernel instrumentation is rendering obsolete traditional agent-based network monitoring in Kubernetes environments. Cloud-native enterprises in financial services and SaaS sectors are deploying Cilium and Falco sidecars at container runtime. The technology is rendering obsolete the three-year appliance refresh cycles that previously dominated data center visibility procurement.
The EU AI Act risk classification framework now designates real-time biometric and behavioral traffic analysis as high-risk AI systems. Vendors serving European critical infrastructure must implement human-in-the-loop override mechanisms and algorithmic impact assessments. Telecom operators in Germany and France are responding by segregating automated classification pipelines from enforcement actions.
Subscription financing now dominates procurement above three million dollar annual contract value, displacing capital expenditure approval cycles that previously stretched eighteen to twenty-four months. Managed detection and response providers are capturing hybrid deployment contracts through operational expenditure structures. This shift is most pronounced in United States healthcare and federal contractor segments where budget authority resides with CISOs rather than infrastructure teams.
Network Traffic Analytics Market Segmentation
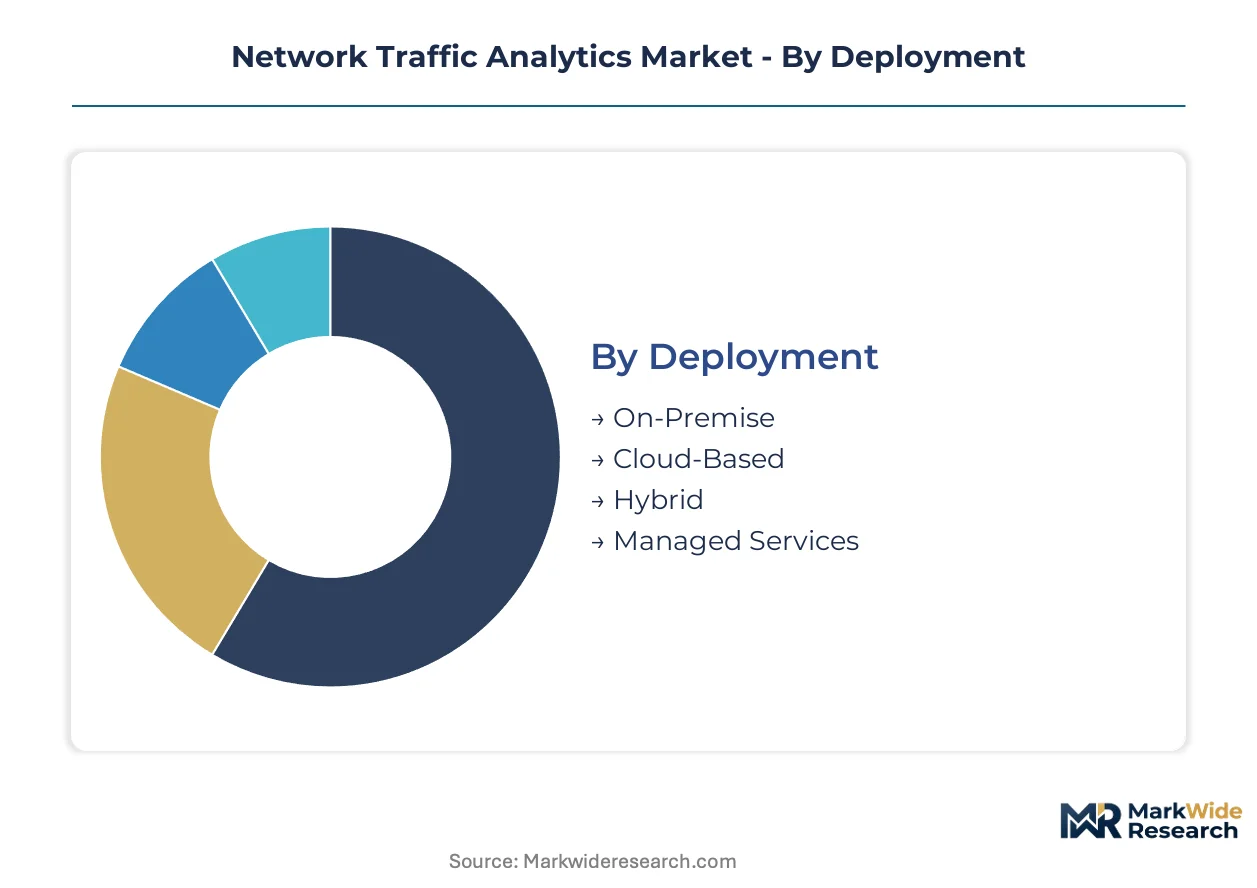
Segmentation in network traffic analytics reveals divergent procurement cycles and margin structures. Deployment models range from three-year appliance refresh programs to monthly SaaS subscriptions. Application priorities shift between cost-center optimization and revenue-protecting security investments.
Deployment:
Cycle times vary dramatically across deployment modes, with cloud-native platforms refreshing quarterly while on-premise hardware extends across 36-month amortization schedules.
- Cloud-Based:Multi-tenant architectures deliver elastic compute for traffic spike handling without capital commitment. Financial services firms in the United States and Germany are migrating security operations centers to cloud-native visibility stacks to compress procurement approval from 18 months to 30 days. Cloud-based deployment captures the steepest expansion trajectory as enterprises abandon depreciating appliance assets.
- On-Premise:Dedicated hardware appliances with custom ASICs maintain relevance for carrier networks requiring line-rate decryption above 100 Gbps. Japanese telecom operators continue procuring on-premise deep packet inspection for lawful intercept compliance where data sovereignty prohibits offshore processing. Refresh cycles stretch 24-36 months, constraining vendor revenue predictability.
- Hybrid:Split-plane architectures process metadata in cloud while retaining sensitive payload inspection on-premise. Multinational manufacturers deploy hybrid models to satisfy GDPR data localization without sacrificing centralized security analytics.
- Managed Services:Outsourced network operations centers assume monitoring responsibility under outcome-based contracts. Mid-market enterprises in India leverage managed services to access Tier-1 analyst capabilities without internal security engineering headcount.
On-Premise deployments anchor the volume base in carrier infrastructure while Cloud-Based models gain share at the steepest rate.
Application:
Cost tier stratification separates commodity performance monitoring from premium security analytics commanding 40-60% gross margins.
- Security Analytics:Real-time threat detection pipelines correlate traffic anomalies with threat intelligence feeds. CISA directive 23-01 compels United States energy utilities to deploy continuous security analytics, opening a regulated procurement channel with mandatory compliance timelines. Breach-cost escalation and cyber insurance requirements are concentrating security analytics demand in healthcare and financial services verticals.
- Network Performance Monitoring:Latency and packet-loss measurement for service-level agreement enforcement. 5G standalone core deployments in Germany and Japan instrument service-based architecture interfaces with performance monitoring to guarantee network slicing quality-of-service.
- User Behavior Analytics:Baseline deviation detection for insider threat identification. European telecom operators under EU AI Act mandates implement human-in-the-loop overrides for behavioral classification systems designated as high-risk AI.
- Compliance Management:Automated evidence collection for ISO 27001, NIST Cybersecurity Framework, and sector-specific regulations. Enterprise buyers now compress security audit completion from six months to twelve weeks, elevating demand for pre-packaged compliance reporting modules.
Security Analytics commands the deepest margin pools while Compliance Management climbs fastest as regulatory pressure intensifies across jurisdictions.
End User:
Customer type determines procurement authority location and contract structure preferences.
- Service Providers:Telecom and cloud operators instrumenting backbone and edge infrastructure for traffic engineering and customer experience management. Reliance Jio and Bharti Airtel 5G rollouts in India lack indigenous analytics capabilities, creating white space for vendors with localized data center presence.
- Enterprises:Corporate networks spanning campus, branch, and multi-cloud environments. United States healthcare systems and federal contractors favor operational expenditure structures placing budget authority with CISOs rather than infrastructure teams.
- Government Agencies:National security and civilian departments with classified and unclassified network monitoring mandates. Lawful intercept requirements and critical infrastructure protection directives shape procurement specifications.
- Educational Institutions:University and research networks with high-volume scientific data flows and open-access policies. Budget constraints favor open-source and community-licensed analytics platforms over commercial appliances.
Service Providers represent the largest addressable spend while Enterprises are pivoting most aggressively toward subscription financing models.
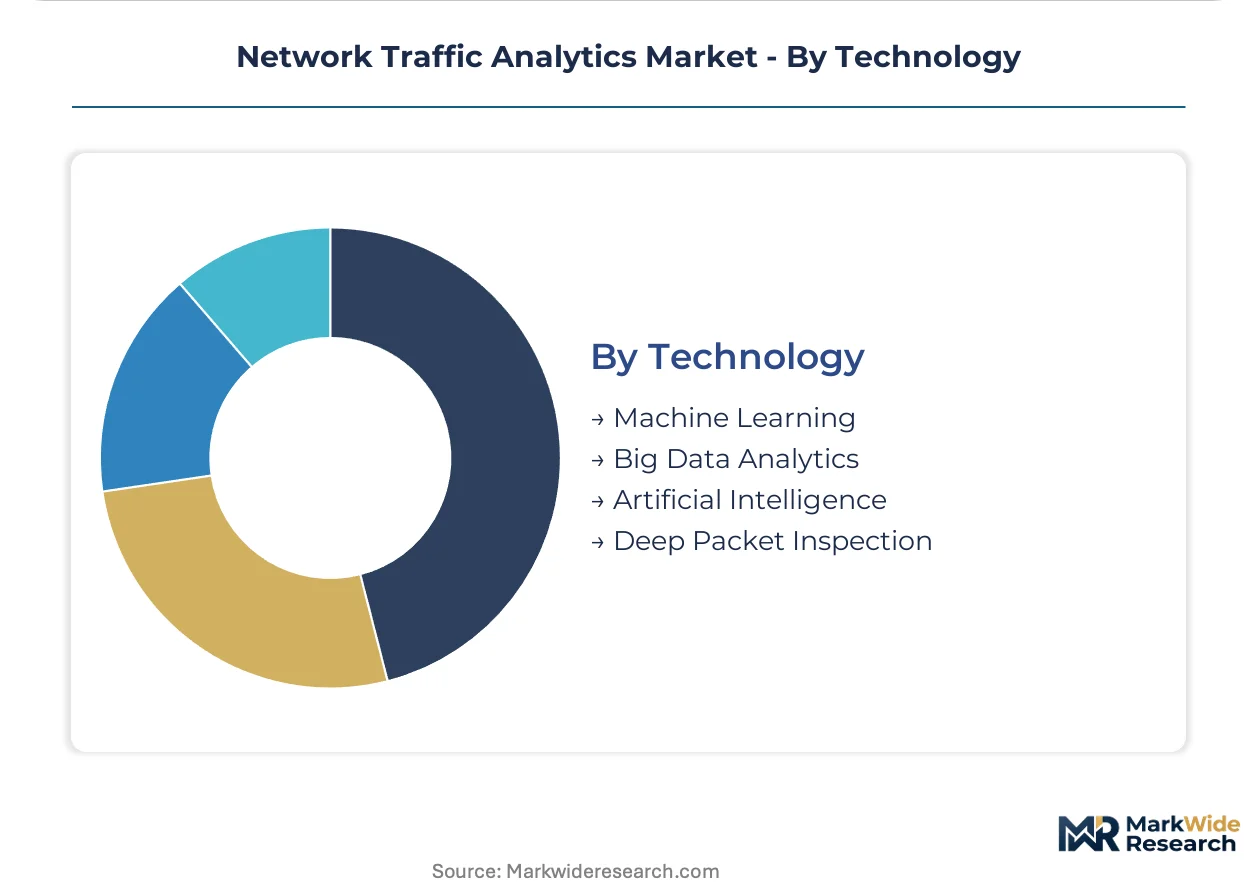
Technology:
Supply concentration in merchant silicon constrains vendor roadmaps for high-throughput processing engines.
- Deep Packet Inspection:Layer 7 protocol analysis and payload inspection at line rate. TLS 1.3 encryption proliferation is forcing deployment of decryption proxies and edge inference engines, compressing legacy hardware relevance.
- Machine Learning:Supervised and unsupervised models for encrypted traffic classification without payload decryption. Carrier procurement teams struggle to evaluate vendor accuracy claims due to scarce talent possessing both telecommunications and ML engineering competencies.
- Artificial Intelligence:Generative and predictive systems for automated incident response and root-cause analysis. EU AI Act transparency mandates require auditable decision logs, displacing black-box analytics engines in European deployments.
- Big Data Analytics:Distributed storage and query systems for petabyte-scale traffic metadata retention. Forensic investigation requirements drive retention policies extending 12-24 months for regulated verticals.
Deep Packet Inspection retains structural importance in carrier networks while Machine Learning expands most quickly as encrypted traffic volumes exceed ninety percent of backbone capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in network traffic analytics tilt toward service delivery rather than hardware trade, with United States vendors licensing cloud-native platforms to European carriers while Japanese and German operators procure on-premise appliances domestically. Cross-border data flows governed by GDPR and emerging AI regulations reshape where processing infrastructure must reside.
United States
CISA directive 23-01 compels energy and water utilities to deploy continuous network monitoring, creating regulated procurement channels with mandatory compliance timelines. The FCC shapes market access through net-neutrality enforcement and critical infrastructure designation. Dallas-Fort Worth and Northern Virginia data center clusters host concentrated cloud-native analytics operations serving federal contractors.
Germany
Telecom service providers instrument 5G standalone core deployments with real-time analytics to manage network slicing quality-of-service guarantees. The EU AI Act imposes algorithmic transparency requirements on automated traffic classification systems in European networks. Munich and Frankfurt anchor carrier infrastructure investment where data sovereignty mandates prohibit offshore processing.
Japan
METI guidelines accelerate post-quantum cryptography migration, forcing carrier investment in next-generation traffic inspection capable of handling Kyber and Dilithium protocols. Lawful intercept compliance requires on-premise deep packet inspection where data sovereignty prohibits cloud alternatives. Tokyo and Osaka metropolitan areas concentrate telecom infrastructure spending for 5G edge analytics.
India
Reliance Jio and Bharti Airtel 5G rollouts lack indigenous traffic analytics capabilities, creating white space for managed service providers with localized data center presence. TRAI regulations mandate data localization for telecom traffic analysis. Mumbai and Bangalore clusters attract vendor investment to serve mid-market enterprises through subscription financing models.
United Kingdom
Financial services firms migrate security operations centers to cloud-native visibility stacks to compress procurement approval cycles. The National Cyber Security Centre shapes vendor product roadmaps through critical infrastructure protection guidance. London's fintech corridor drives demand for encrypted traffic classification without payload decryption.
Network Traffic Analytics Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic archetypes: hardware-integrated specialists, cloud-native platform vendors, and managed service orchestrators. Tiered competitive positioning separates line-rate appliance providers from elastic SaaS operators. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and vertical integration into silicon-optimized processing engines for 100Gbps+ carrier workloads.
Within the hardware-integrated tier, NETSCOUT Systems Inc. and Juniper Networks Inc. exemplify appliance-centric positioning, while Palo Alto Networks Inc. anchors the cloud-native platform archetype. Cisco Systems Inc. occupies a hybrid position spanning both deployment models. These three entities collectively represent the structural segmentation between capital-intensive carrier infrastructure and operational expenditure-driven enterprise adoption.
| Leading Market Players |
|---|
| SolarWinds Corporation |
| Juniper Networks Inc. |
| NETSCOUT Systems Inc. |
| Fortinet Inc. |
| IBM Corporation |
| Cisco Systems Inc. |
| Kentik Technologies Inc. |
| ExtraHop Inc. |
| Palo Alto Networks Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Taiwan's merchant silicon foundries is compressing lead times for 100Gbps network processors while simultaneously eroding pricing power for appliance vendors dependent on custom ASIC refresh cycles. This utilization dynamic is forcing vendors toward software-defined architectures that reduce silicon dependency and shift buyer negotiations toward recurring-revenue SaaS tiers.
Pricing Analysis
Enterprise CISOs anchor pricing negotiations through operational expenditure structures that displace eighteen-month capital approval cycles. Three-tier pricing structure across premium, standard, and economy levels separates carrier-grade hardware appliances from mid-market SaaS subscriptions and open-source community editions. Cost compression in the standard tier intensifies because hyperscaler cloud-native platforms are absorbing price-sensitive mid-market demand. Healthcare systems exhibit highest price sensitivity due to constrained IT budgets, while Japanese telecom operators demonstrate lowest sensitivity given lawful intercept compliance mandates that prohibit offshore processing alternatives.
Supply Chain Analysis
US export controls on advanced network processors and EU dual-use technology restrictions are constraining cross-border flows of deep packet inspection hardware to Chinese and Russian carrier markets. Merchant silicon for 100Gbps+ processors concentrates in Taiwan, South Korea, and the United States, while specialized FPGA and custom ASIC design capabilities cluster in Israel and the United Kingdom. Supply chain risk centers on single-source vulnerability for 7nm and below fabrication nodes. Distribution runs through direct enterprise sales forces for cloud-native platforms and systems integrators for carrier appliance deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
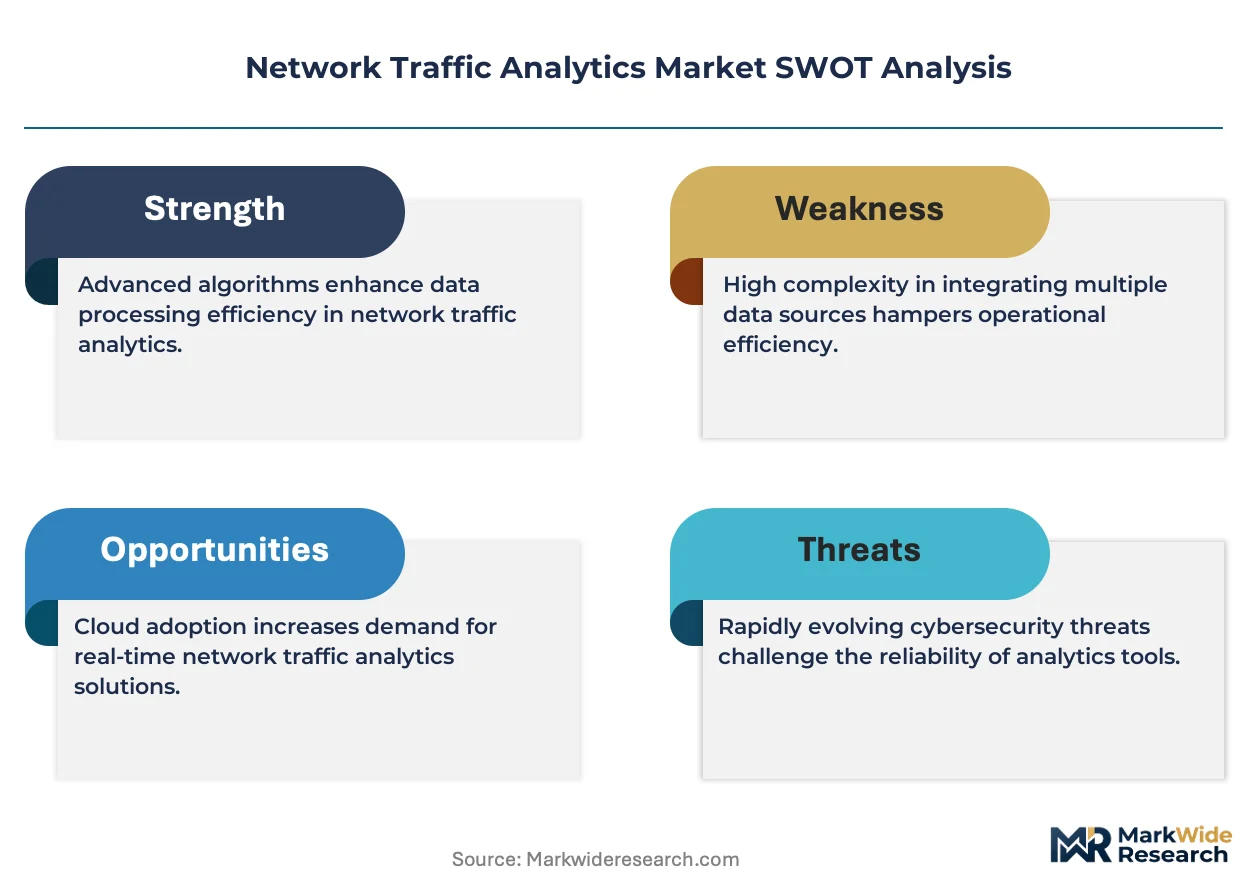
Network traffic analytics sits in early-cycle expansion as encrypted traffic volumes exceeding ninety percent of backbone capacity force replacement demand for legacy decryption architectures. 5G standalone core deployments and quantum-resistant cryptography migration are accelerating procurement timelines beyond historical refresh patterns.
For Market Incumbents: Insulate recurring-revenue streams by embedding eBPF-based kernel instrumentation into hybrid orchestration platforms that span cloud and on-premise environments. Threat from cloud-native entrants demands backward integration into silicon-optimized processing engines for carrier latency-sensitive applications. Priority lever rests on certification acceleration for ISO 27001 and NIST Cybersecurity Framework compliance to compress twelve-week audit timelines.
For New Entrants and Emerging Players: India's 5G infrastructure expansion represents the most penetrable geographic white space given Reliance Jio and Bharti Airtel's absence of indigenous analytics capabilities. Managed service delivery models with localized Mumbai and Bangalore data center presence unlock mid-market enterprises lacking internal security engineering headcount. Go-to-market angle emphasizes subscription financing that places budget authority with CISOs rather than infrastructure teams.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS-native vendors serving United States healthcare and federal contractor segments where operational expenditure structures dominate above three million dollar annual contract value. Long-term viability favors platforms with hybrid orchestration capabilities spanning edge inference and centralized cloud processing. Signal to watch is carrier procurement team investment in ML model operations talent as validation of encrypted traffic classification accuracy claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | eBPF kernel instrumentation merges observability with security analytics across Kubernetes environments. |
| Geographic Expansion | Localized data center presence in India satisfies TRAI data localization mandates for telecom traffic analysis. |
| Strategic Partnership | Hyperscaler cloud alliances accelerate hybrid deployment contracts through pre-integrated marketplaces. |
| Product Launch | Post-quantum cryptography-ready inspection engines capture METI-guided carrier upgrade cycles in Japan. |
| Acquisition of Specialist Firm | ML engineering talent pools address scarcity blocking carrier evaluation of encrypted traffic classification accuracy. |
Methodological Framework
Initial hypotheses were tested against primary input from carrier network architects, enterprise CISOs, cloud platform engineers, and managed security service provider operations leads and refined through secondary validation. Primary interviews explored procurement authority shifts, compliance timeline compression, and encrypted traffic classification evaluation challenges. Secondary sources encompassed FCC net-neutrality enforcement records, EU AI Act implementation guidance, NIST post-quantum cryptography standards, hyperscaler capex disclosures, and carrier infrastructure investment filings. Bottom-up and top-down triangulation reconciled vendor-reported deployment metrics with enterprise IT spending patterns.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed deployment model, application priority, end-user archetype, and technology foundation alongside regional regulatory cluster variations. CAGRs were derived from fitted growth curves calibrated to historical adoption inflection points and forward-looking infrastructure investment commitments. Industry-specific forecast inputs included 5G standalone core deployment timelines and quantum-resistant encryption migration schedules.
Practitioners should monitor NIST post-quantum cryptography standard finalization and EU AI Act enforcement precedent for early signals of replacement demand acceleration. Forecasts reflect assumptions regarding carrier capital expenditure stability and enterprise cloud migration continuity. Material shifts in Taiwan semiconductor fabrication capacity or GDPR cross-border data flow rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
Load (ETL) Market
Analytics
TV Analytics Solutions Market
Analytics
Global People and HR Analytics Software Market
Analytics
Saudi Arabia Geospatial Analytics Market
Analytics
Global E-Commerce Analytics Software Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
Spain Geospatial Analytics Market
Analytics
SME Big Data Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Europe Operational Intelligence Market
Analytics
Global Customer Analytics Market
Analytics
Video Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
Mobile Apps and Web Analytics Market