
 APAC Retail Analytics Market | 2026-2036
APAC Retail Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Retail Analytics Market Outlook
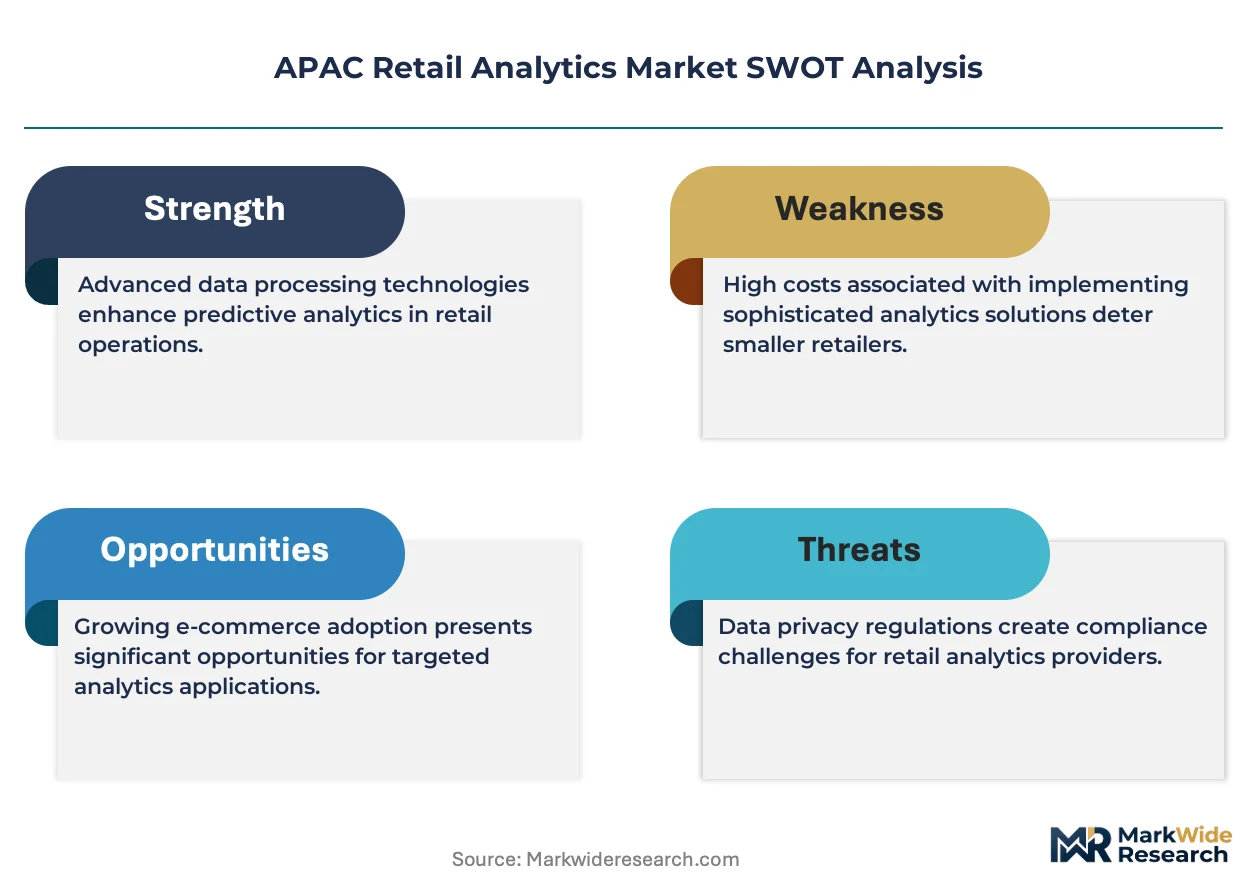
Cloud infrastructure is decoupling retail analytics from on-premises hardware economics across APAC. Microsoft leverages its Azure stack to anchor enterprise deployments in Australia and Japan. IBM competes through Watson-powered demand forecasting tailored for grocery and apparel chains. SAP dominates ERP-integrated analytics among large franchise networks spanning Thailand and Vietnam.
Retail analytics encompasses software platforms that ingest point-of-sale streams, inventory logs, and customer journey signals to generate actionable merchandising and operations intelligence. These systems typically process terabyte-scale transaction data with sub-second query latency to enable dynamic pricing and shelf optimization. Predictive analytics leads product type demand as retailers automate demand sensing and markdown timing. Cloud deployment expands fastest where telecom infrastructure supports edge-to-core data pipelines. Omni-channel retailers represent the deepest end-user margin pool because they synchronize web, mobile, and store analytics into unified customer profiles.
Japan's METI promotes data-free flow frameworks that ease cross-border analytics sharing between retail headquarters and offshore processing centers. India's TRAI governs data localization rules affecting where customer transaction records must reside. China's SAMR enforces algorithmic recommendation transparency standards that reshape how analytics engines present personalized offers. Stakeholders must weigh compliance architecture investments against latency penalties from fragmented data sovereignty requirements.
Market Dynamics
Cloud infrastructure is decoupling retail analytics from on-premises hardware economics across APAC. Microsoft leverages its Azure stack to anchor enterprise deployments in Australia and Japan. IBM competes through Watson-powered demand forecasting tailored for grocery and apparel chains. SAP dominates ERP-integrated analytics among large franchise networks spanning Thailand and Vietnam.
Growth Catalysts
- PLI scheme:India's production-linked incentive for electronics manufacturing indirectly boosts analytics demand as domestic retail networks digitize inventory tracking. Small-format grocers accelerate sensor deployment to capture subsidy-linked efficiency gains.
- Footfall sensors:Southeast Asian grocery chains deploy basket-analysis tools to shrink shrinkage and sharpen promotions. Real-time shelf monitoring compresses restock cycles from days to hours.
- Alibaba data ecosystems:Tier-one cities in China set the benchmark for real-time consumer behavior modeling. Competing retailers replicate these architectures to match personalization depth.
Market Restraints
- Data localization:India's TRAI governs where customer transaction records must reside, fragmenting cloud architectures and inflating compliance overhead. Latency penalties degrade real-time analytics performance.
- Algorithmic transparency:China's SAMR enforces recommendation-engine disclosure standards that constrain personalization granularity. Retailers must reweight models toward interpretability at accuracy cost.
- Edge infrastructure gaps:Tier-three cities across Indonesia and Philippines lack fiber density to support sub-second query latency. On-premise fallback deployments erode cloud economics.
Strategic Opportunities
- Vietnam franchise networks:Underpenetrated mid-market retail chains seek ERP-integrated analytics without legacy system migration costs. Greenfield deployments skip mainframe bridging entirely.
- Cross-border data flows:Japan's METI promotes frameworks easing analytics sharing between headquarters and offshore processing centers. Regional hub architectures consolidate fragmented country operations.
- Convergence of computer vision and POS streams:Shelf-mounted cameras feeding directly into transaction databases enable unified loss-prevention and merchandising intelligence. Early adopters in Australian grocery pilot unified dashboards.
Industry Challenges
- Data engineering talent:Shortage of pipeline architects fluent in both retail operations and distributed systems constrains deployment velocity. Training programs lag demand in Indonesia and Philippines.
- Legacy ERP integration:Decades-old inventory systems in Thai and Vietnamese retail chains resist API-based connectivity. Custom middleware consumes 40% of implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Retail Analytics Market |
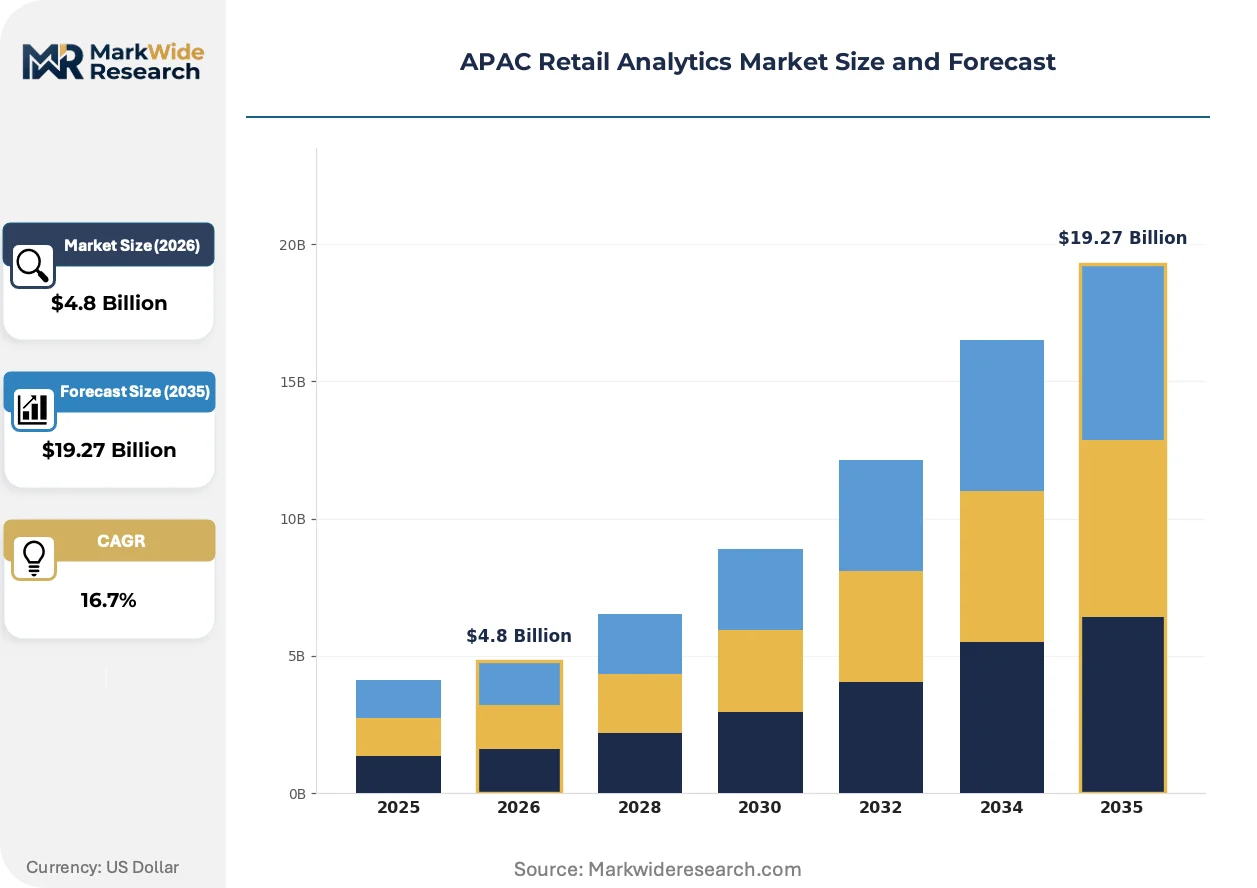
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboard, Reporting Tools, Predictive Analytics, Data Mining End User: Brick-and-Mortar Stores, E-Commerce Platforms, Omni-Channel Retailers, Brands Deployment: On-Premises, Cloud, Hybrid, SaaS Customer Type: Small Enterprises, Medium Enterprises, Large Corporations, Franchise Chains |
| Companies Covered | Microsoft, Adobe, Oracle, Blue Yonder, Manthan Software Services, IBM, SAS Institute, HCL Technologies, SAP, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Retail Analytics Market Strategic Shifts
Real-time inference at the edge is compressing decision cycles from batch overnight to continuous optimization. Retailers now embed analytics engines directly within store infrastructure rather than centralizing all processing.
Computer vision platforms are automating shelf compliance monitoring across Australian and Japanese supermarket chains. These systems scan planogram adherence through ceiling-mounted cameras, flagging stockouts and misplacements without human patrols. Grocery operators are automating markdown timing by correlating visual freshness signals with velocity forecasts, reducing spoilage write-offs.
METI's data-free flow frameworks are easing cross-border analytics governance between Japanese retail headquarters and offshore processing centers. The policy reduces legal review cycles for multi-country customer profiling from months to weeks. Apparel chains with regional hub architectures are consolidating fragmented country operations into unified data lakes.
Omni-channel buyers now demand unified customer profiles synchronizing web, mobile, and in-store behavior. This procurement pattern is displacing siloed channel-specific analytics contracts. Australian department stores and Chinese marketplace sellers lead this consolidation, bundling previously separate vendor relationships into single-platform mandates.
APAC Retail Analytics Market Segmentation
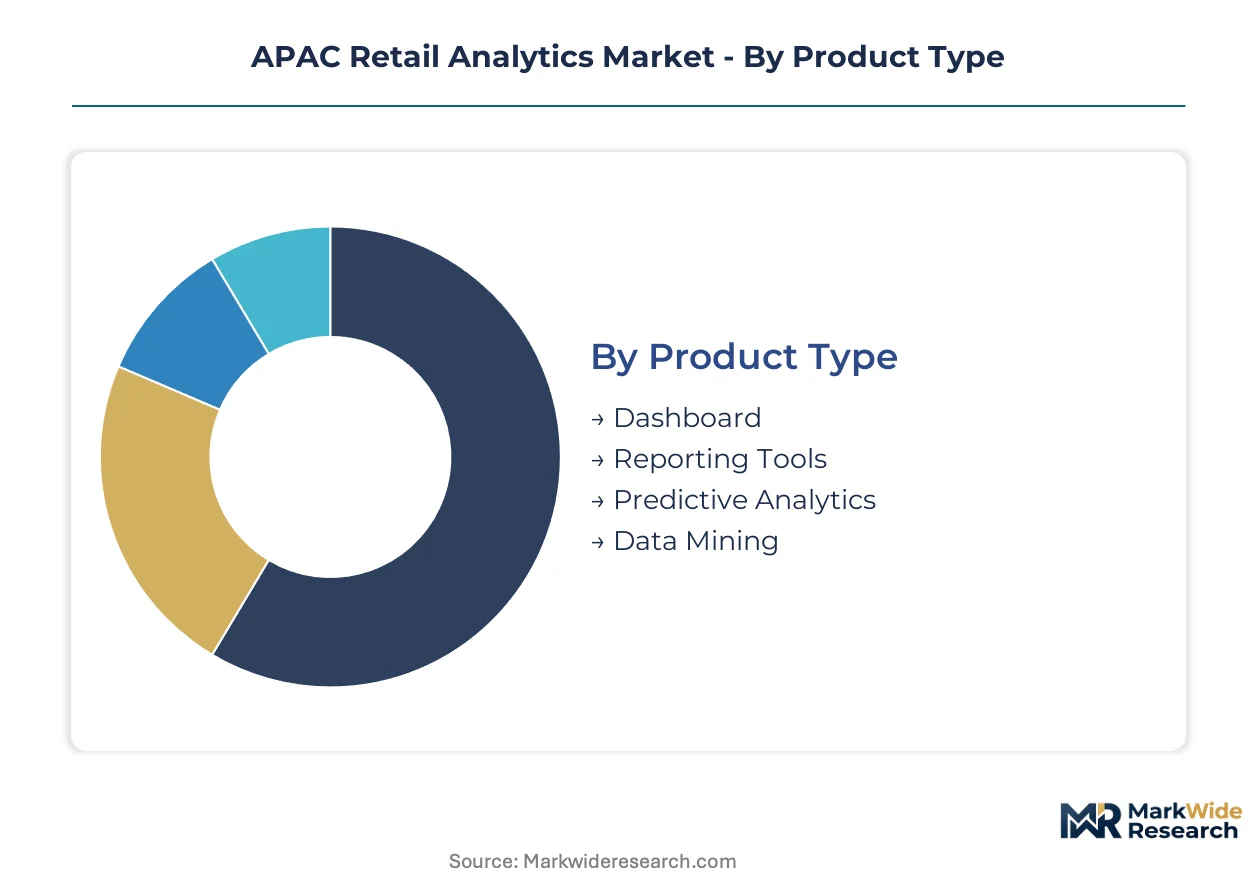
APAC retail analytics procurement diverges sharply across deployment economics, customer scale, and channel complexity. Buyers prioritize latency performance against data sovereignty constraints while weighing legacy system migration costs against greenfield agility.
Product Type:
Investment priority follows predictive capability depth and real-time query performance.
- Predictive Analytics:Machine learning engines automate demand sensing, markdown timing, and inventory positioning with sub-second inference latency. Australian grocery chains and Chinese tier-one marketplace operators deploy these systems to compress decision cycles from batch overnight to continuous optimization. Demand concentrates where fiber density supports edge-to-core pipelines.
- Dashboard:Visualization layers aggregate POS streams, inventory logs, and customer journey signals into unified merchandising intelligence. Southeast Asian grocery operators prioritize shelf-compliance dashboards integrating computer vision feeds with transaction databases. Procurement prioritizes vendors offering API-native connectivity to legacy ERP systems.
- Reporting Tools:Standardized performance summaries for franchise networks lacking in-house data engineering capacity. Thai and Vietnamese retail chains deploy these for weekly category reviews.
- Data Mining:Pattern extraction from historical transaction archives to inform private-label development and store format planning. Indian electronics retailers leverage these tools following PLI-linked digitization.
Dashboard leads on scale; Predictive Analytics leads on momentum.
End User:
Channel architecture determines data integration complexity and customer profile unification requirements.
- Omni-Channel Retailers:Unified analytics synchronizing web, mobile, and in-store behavior into single customer profiles. Australian department stores and Chinese marketplace sellers mandate single-platform contracts displacing siloed channel-specific vendors. These buyers represent the deepest margin pool due to data volume and cross-touchpoint attribution needs.
- E-Commerce Platforms:Real-time recommendation engines and dynamic pricing systems processing terabyte-scale clickstream data. Alibaba and JD.com data ecosystems in China's tier-one cities set personalization benchmarks competitors replicate.
- Brick-and-Mortar Stores:Footfall sensors and basket-analysis tools deployed by Southeast Asian grocery chains to shrink shrinkage and sharpen promotions.
- Brands:Sell-through analytics and retail execution monitoring for consumer goods manufacturers supplying fragmented APAC retail networks.
Omni-Channel Retailers command premium pricing; E-Commerce Platforms expand most quickly.
Deployment:
Infrastructure maturity and regulatory jurisdiction shape cloud-versus-on-premise trade-offs.
- Cloud:Decouples analytics from hardware economics where telecom infrastructure supports edge-to-core pipelines. Microsoft Azure anchors enterprise deployments in Australia and Japan; expansion accelerates in tier-one cities while tier-three Indonesian and Philippine markets face latency constraints.
- Hybrid:Sensitive customer data resides on-premise while compute-intensive modeling runs in cloud. India's TRAI localization rules and China's SAMR algorithmic transparency standards drive this architecture.
- On-Premises:Fallback deployment where fiber density cannot support sub-second query latency, eroding cloud economics in Indonesian and Philippine tier-three cities.
- SaaS:Subscription-based analytics for mid-market retailers seeking rapid deployment without capital expenditure.
Cloud dominates addressable spend; Hybrid climbs the fastest on compliance tailwinds.
Customer Type:
Enterprise scale dictates integration complexity tolerance and vendor relationship structures.
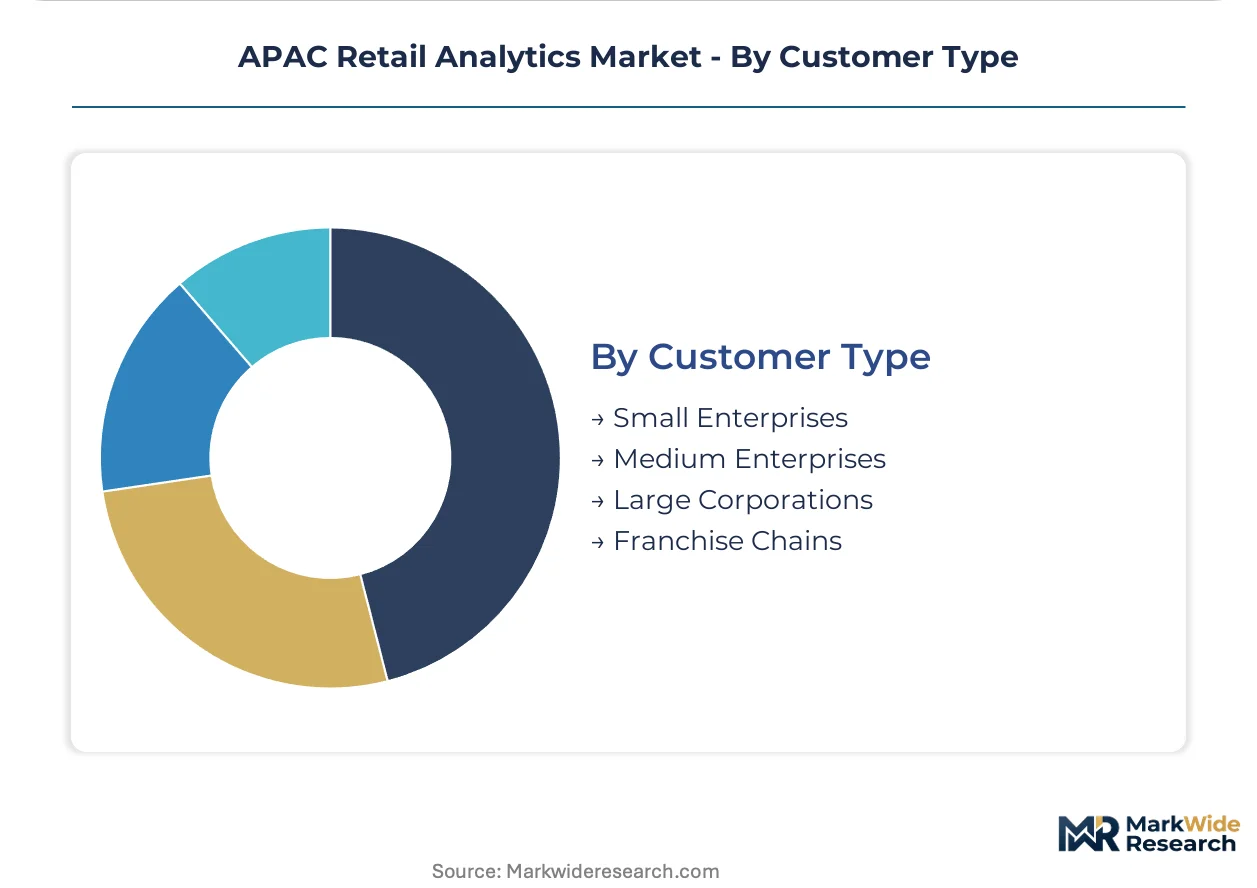
- Large Corporations:ERP-integrated analytics requiring custom middleware for decades-old inventory systems. SAP dominates among Thai and Vietnamese franchise networks where legacy system resistance consumes 40% of implementation timelines.
- Franchise Chains:Underpenetrated mid-market retail networks in Vietnam seek greenfield deployments without mainframe bridging. These buyers skip legacy migration entirely.
- Medium Enterprises:Standardized cloud deployments with pre-configured connectors to common retail management platforms.
- Small Enterprises:PLI scheme subsidies accelerate sensor deployment among Indian small-format grocers capturing efficiency-linked gains.
Large Corporations anchor vendor revenue; Franchise Chains present steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities anchor analytics deployment density across APAC, with Alibaba and JD.com data ecosystems setting benchmarks for real-time consumer behavior modeling that regional competitors replicate.
China
Beijing and Shanghai concentrate predictive analytics adoption among omni-channel retailers synchronizing marketplace, social commerce, and physical store data. SAMR enforces algorithmic recommendation transparency standards that constrain personalization granularity. Yangtze River Delta logistics hubs embed edge inference engines directly within warehouse automation systems.
Japan
Kanto region retailers deploy computer vision platforms for shelf compliance monitoring through ceiling-mounted camera networks. METI promotes data-free flow frameworks easing cross-border analytics sharing between headquarters and offshore processing centers. Osaka-based department stores consolidate fragmented country operations into unified customer data lakes.
India
Maharashtra and Karnataka electronics retailers accelerate sensor deployment following PLI scheme subsidies for domestic manufacturing digitization. TRAI data localization rules fragment cloud architectures and inflate compliance overhead for transaction record storage. Delhi-NCR mid-market chains seek greenfield ERP-integrated analytics without legacy mainframe bridging.
Australia
New South Wales and Victoria grocery operators pilot unified dashboards converging computer vision feeds with POS transaction streams. Microsoft Azure anchors enterprise cloud deployments where fiber density supports edge-to-core pipelines. Sydney department stores mandate single-platform contracts displacing previously siloed channel-specific analytics vendors.
Vietnam
Ho Chi Minh City franchise networks represent underpenetrated demand for ERP-integrated analytics without legacy system migration costs. SAP dominates among Thai and Vietnamese retail chains where decades-old inventory systems resist API-based connectivity. Greenfield deployments in emerging commercial districts skip mainframe bridging entirely.
APAC Retail Analytics Market Competitive Environment
Global majors compete with regional champions across cloud infrastructure and ERP integration dimensions, producing a tiered structure where hyperscale platforms anchor enterprise accounts while specialized vendors capture mid-market greenfield opportunities. Microsoft leverages Azure stack dominance in Australia and Japan against IBM's Watson-powered demand forecasting specialization. Strategic moves concentrate on hybrid cloud architectures compliant with data sovereignty requirements and computer vision convergence with transaction databases.
Within the hyperscale cloud tier, Microsoft and Oracle represent infrastructure-anchored deployment models, while SAP exemplifies ERP-native analytics integration. Manthan Software Services occupies a position among India-based specialists serving domestic retail digitization demand. IBM sits within the predictive analytics archetype competing through Watson-powered grocery and apparel forecasting capabilities.
| Leading Market Players |
|---|
| Microsoft |
| Adobe |
| Oracle |
| Blue Yonder |
| Manthan Software Services |
| IBM |
| SAS Institute |
| HCL Technologies |
| SAP |
| Others |
Value Chain & Pricing Dynamics
Data engineering talent shortages across Bengaluru and Singapore widen pricing-tier spreads between premium predictive analytics suites and standardized dashboard offerings. Labor-cost differentials between tier-one cloud architects and mid-market implementation specialists translate directly into three-tier pricing structures across premium, standard, and economy levels.
Pricing Analysis
Input-cost pass-through from cloud infrastructure and specialized talent drives subscription-tier differentiation across deployment models. Pricing stratifies across premium, standard, and economy tiers based on edge-compute latency guarantees and API-native ERP connectivity depth. Cost compression in mid-market SaaS tiers intensifies because Indian PLI-subsidized sensor deployment floods lower-margin segments with efficiency-seeking buyers. Franchise chains in Vietnam exhibit highest price sensitivity; omni-channel retailers in Australian tier-one cities demonstrate lowest sensitivity due to unified customer profile requirements.
Supply Chain Analysis
Regional distribution centers in Singapore, Sydney, and Tokyo anchor hub-and-spoke patterns for analytics software delivery across APAC. Solution development draws from Indian engineering hubs, Chinese hardware manufacturing clusters, and Japanese precision electronics suppliers. Single-source vulnerability concentrates in hyperscale cloud infrastructure where Microsoft Azure and Oracle Cloud dominate enterprise anchoring. Distribution runs through direct enterprise sales teams for large corporations alongside channel partners serving mid-market franchise networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC retail analytics has entered late-cycle quality phase where omni-channel buyers consolidate vendor relationships into single-platform mandates. Procurement shifts toward premium specifications featuring sub-second inference latency and unified customer profile synchronization.
For Market Incumbents: Hedge against margin erosion from PLI-subsidized Indian sensor deployment by deepening vertical integration into edge-compute hardware partnerships. Prioritize certification investment in Japan's METI data-free flow frameworks to capture cross-border analytics consolidation. Defensive positioning requires pre-emptive API-native connectivity to SAP ERP systems dominating Thai and Vietnamese franchise networks.
For New Entrants and Emerging Players: Launch via SaaS subscription models targeting Vietnam's underpenetrated mid-market franchise chains seeking greenfield ERP-integrated analytics. White-space concentration sits with tier-three Indonesian and Philippine cities lacking fiber density for hyperscale cloud latency. Go-to-market acceleration demands computer vision-POS convergence pilots replicating Australian grocery unified dashboard architectures.
For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, consolidating specialized analytics vendors to anchor hybrid deployment architectures. Five-to-ten year viability hinges on data sovereignty compliance capabilities across India's TRAI localization rules and China's SAMR algorithmic transparency standards. Acquisition target archetype: regional specialists with pre-built ERP connectors and edge-inference engineering depth. Monitor fiber density expansion timelines in Indonesian and Philippine tier-three cities as inflection indicator for cloud economics penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Architecture Deployment | Balances India's TRAI data localization against compute-intensive modeling in offshore centers. |
| Computer Vision-POS Convergence | Australian grocery pilots demonstrate unified loss-prevention and merchandising intelligence potential. |
| ERP-Native API Development | Reduces 40% implementation timeline consumption from Thai and Vietnamese legacy system resistance. |
| Edge Inference Engine Embedding | Compresses decision cycles from batch overnight to continuous optimization in Yangtze River Delta hubs. |
| Cross-Border Data Flow Certification | Japan's METI frameworks reduce legal review cycles for regional customer profiling consolidation. |
Study Parameters
Bottom-up omni-channel retailer modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core of this study. Primary interviews with chief technology officers, IT procurement officers, platform integration specialists, and ERP system administrators informed demand-side assumptions. Secondary validation drew from hyperscaler capex disclosures, SEC filings, telecom infrastructure deployment databases, and regulatory filings with India's TRAI and China's SAMR. Triangulation between stakeholder-reported implementation timelines and vendor-announced connectivity capabilities anchored segmentation splits.
Historical trendline analysis of predictive analytics adoption velocity across China's tier-one cities established baseline growth patterns. The projection framework models deployment mode, customer scale, channel architecture complexity, and regional fiber density maturity as primary segmentation dimensions. CAGRs derive from curve-fitting observed adoption rates against infrastructure readiness indicators. Forecast inputs include PLI scheme subsidy trajectories, METI data-free flow policy implementation pace, and edge-compute hardware cost decline curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden data localization rule tightening or fiber infrastructure deployment delays. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
South Korea Contact Center Analytics Market
Analytics
Brazil Geospatial Analytics Market
Analytics
Event Stream Processing Market
Analytics
Big Data Analytics Market
Analytics
Construction Data Analytics Software Market
Analytics
Spend Analytics Software Market
Analytics
Content Analytics Software Market
Analytics
Global Performance Analytics Market
Analytics
Global System Monitoring Market
Analytics
Identity Analytics Market
Analytics
Big Data Analytics in Manufacturing Market
Analytics
North America Crowd Analytics Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Self Service Analytics Market
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Advanced Analytics Market