
 Italy ICT Market | 2026-2036
Italy ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Italy ICT Market Foresight
Cloud-native architecture is narrowing the gap between legacy enterprise systems and modern service delivery across Italian enterprises. Telecom Italia S.p.A. (TIM) anchors nationwide fiber and 5G infrastructure expansion, sustaining capital-intensive network modernization. Engineering Ingegneria Informatica S.p.A. specializes in mission-critical systems integration for public administration and defense clients. Fastweb S.p.A. competes aggressively in the wholesale connectivity segment, extending fiber reach into secondary urban centers.
Information and communications technology encompasses hardware, software, services, and networking solutions that process, transmit, and store digital information across enterprise and consumer environments, typically operating through protocols such as TCP/IP, 5G NR, and virtualized compute orchestration to enable real-time data exchange and automated decision workflows. The primary commercial purpose centers on reducing operational latency, securing data integrity, and enabling scalable collaboration across distributed organizations. Services and software together capture the dominant margin pools as recurring revenue models displace one-time hardware transactions, while cloud and hybrid deployment models outpace on-premises installations among mid-market adopters seeking operational flexibility without full capital commitment. Security and data analytics solution types attract disproportionate investment as regulatory pressure and threat surface expansion compel continuous monitoring capabilities.
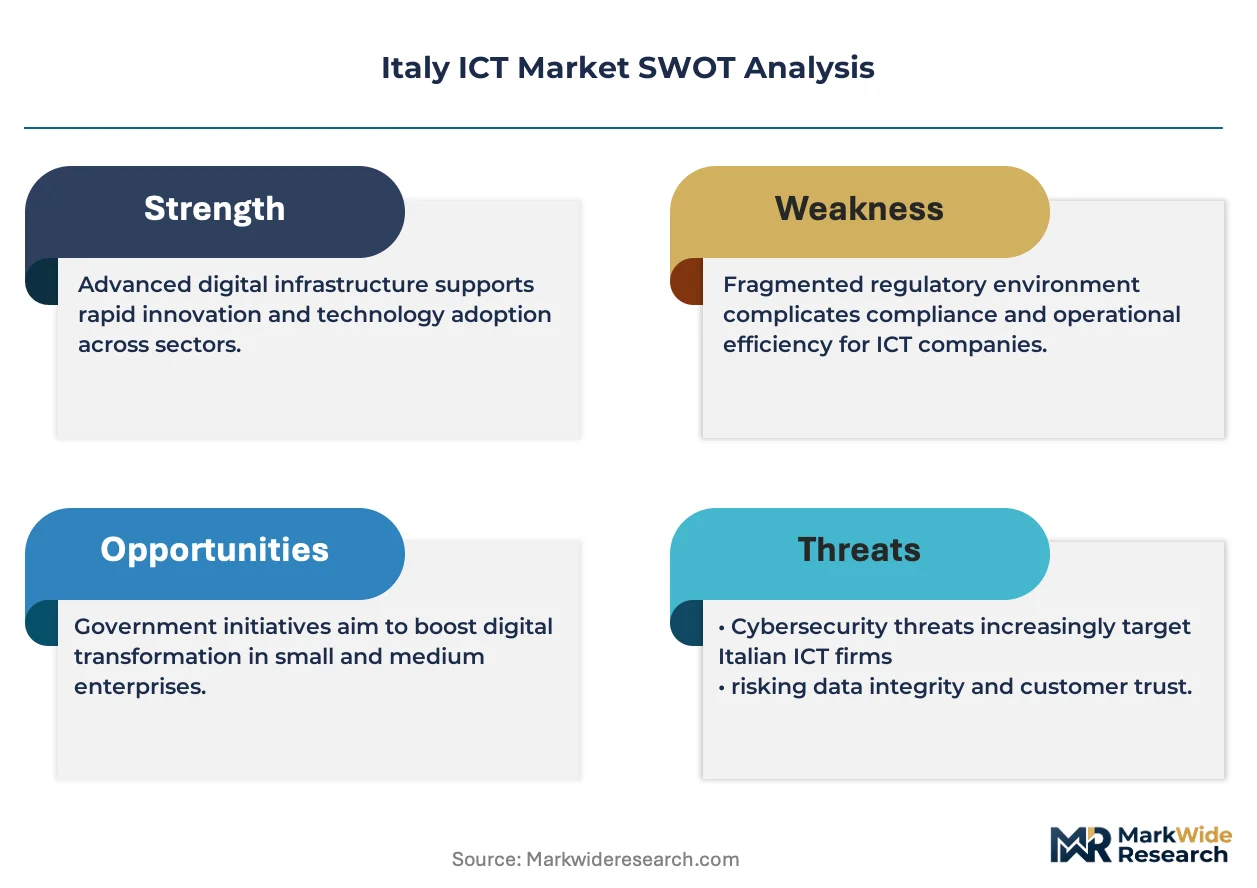
Italy's ICT sector operates under the European Union's Digital Operational Resilience Act (DORA), the NIS2 Directive transposed through national cybersecurity frameworks, and AGID's cloud-first mandates for public administration procurement, each elevating compliance costs while creating certified-provider advantages for domestic incumbents. The national data protection authority enforces GDPR-aligned standards that shape cross-border service architectures and data residency requirements. Stakeholders must weigh sovereign cloud investments against interoperability with EU-wide digital service markets as procurement rules tighten around qualified security certifications.
Market Dynamics
Italy's ICT sector faces structural pressure from AGID's cloud-first mandates for public administration, which compress procurement timelines while elevating compliance thresholds for domestic solution providers competing against EU-wide certified vendors.
Growth Catalysts
- PNRR capital injection:Recovery and Resilience Plan funds channel billions toward cybersecurity hardening and cloud migration, accelerating public-sector digital transformation timelines.
- DORA compliance preparation:Financial services institutions across Milan and Rome are expanding digital resilience investments ahead of the Digital Operational Resilience Act's full enforcement window.
- 5G standalone deployment:Telecom infrastructure modernization creates downstream demand for edge computing, IoT platforms, and mission-critical system integration across manufacturing and logistics verticals.
Market Restraints
- Certified provider concentration:AGID's qualification requirements for public cloud services limit vendor pools to a handful of domestic and EU-accredited operators, constraining price competition.
- GDPR-aligned data residency:Cross-border service architectures face friction from national data protection authority enforcement of strict localization requirements for sensitive public administration datasets.
- Legacy system technical debt:Deep embeddedness of on-premises enterprise resource planning systems in northern Italy's industrial base slows hybrid cloud migration velocity despite policy pressure.
Strategic Opportunities
- Secondary urban fiber extension:Wholesale connectivity providers are penetrating Turin, Bologna, and Naples metropolitan zones where fiber-to-the-home penetration lags Milan by significant margins.
- Sovereign cloud infrastructure:NIS2 Directive transposition creates certified-provider advantages for Italian operators capable of delivering EU-trusted data sovereignty guarantees.
- AI governance tooling:EU AI Act risk-classification requirements generate demand for automated compliance monitoring and algorithmic audit platforms among financial services and healthcare adopters.
Industry Challenges
- Cybersecurity talent scarcity:Specialized skills in zero-trust architecture and threat intelligence operations command premium compensation, stretching mid-market enterprise security budgets.
- Multi-cloud integration complexity:Heterogeneous environments spanning AGID-qualified public cloud, private sovereign instances, and residual on-premises workloads demand scarce systems integration expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy ICT Market |
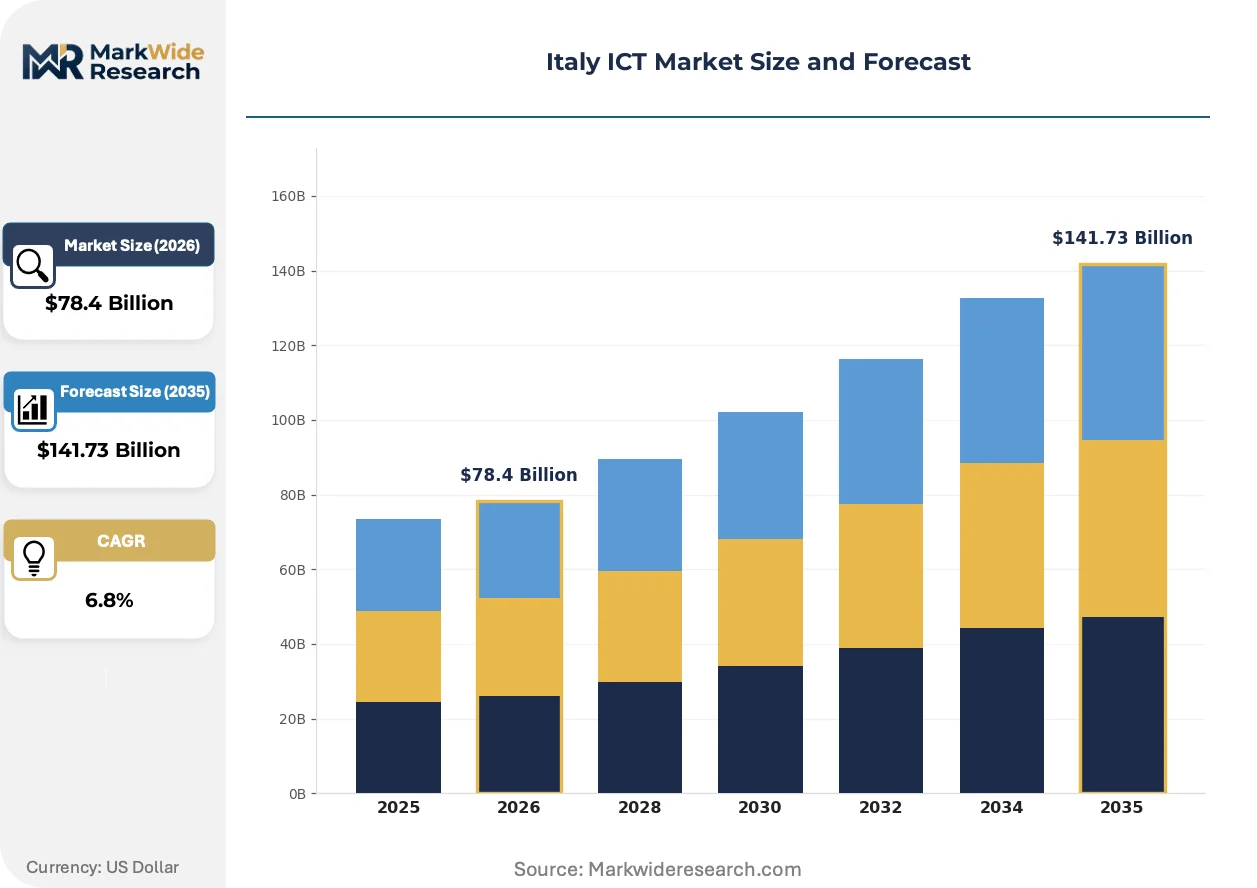
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Networking Deployment Model: On-Premises, Cloud, Hybrid, Managed End User: Government, Education, Healthcare, Financial Services Solution Type: Security, Data Analytics, Telecommunications, IoT |
| Companies Covered | Engineering Ingegneria Informatica S.p.A., Fastweb S.p.A., Telecom Italia S.p.A. (TIM), Accenture S.p.A., Wind Tre S.p.A., Nexi S.p.A., Leonardo S.p.A., Capgemini Italia S.p.A., Reply S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy ICT Market Shifts & Advancements
Italian enterprises are compressing decision cycles around infrastructure modernization as regulatory deadlines and competitive pressure converge, forcing faster technology adoption across traditionally conservative buyer segments.
Container orchestration and Kubernetes-native workloads are migrating from experimental development environments to production-grade enterprise deployments. Mid-market manufacturers in Lombardy and Emilia-Romagna are adopting these platforms at accelerated pace to enable real-time supply chain visibility. This migration from monolithic application architectures is compressing deployment timelines from quarters to weeks while elevating demand for platform engineering expertise.
AGID's cloud-first procurement mandates are reshaping public administration technology sourcing, requiring all new IT investments to prioritize qualified cloud service providers. This policy creates structural advantage for domestic operators holding national security certifications while excluding non-qualified international competitors from contested tenders. Central government agencies and regional health authorities represent the most affected segments, with procurement teams retraining on technical evaluation criteria.
Subscription-based consumption models for infrastructure software are displacing perpetual license arrangements across Italian enterprise buyers. System integrators and value-added resellers face margin compression as vendors pursue direct customer relationships through marketplace channels. This shift is most visible among Milan-headquartered financial services institutions and Rome-based public sector entities seeking operational expenditure predictability.
Italy ICT Market Segmentation
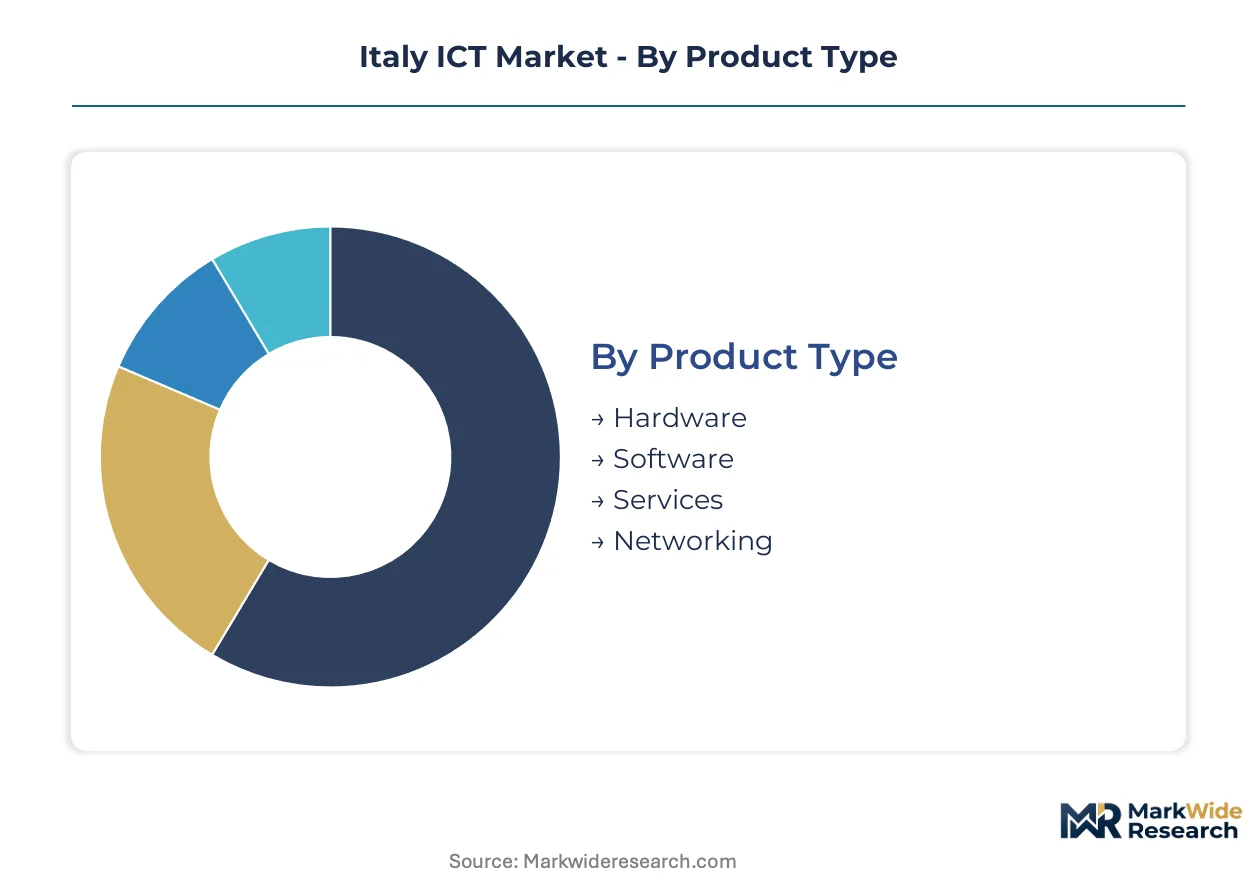
Segmentation reveals how procurement priorities diverge across Italian enterprises, with regulatory mandates and infrastructure maturity creating distinct demand pockets. Understanding these divisions clarifies where capital concentrates and which solution architectures face accelerated adoption timelines.
Product Type:
Hardware investments concentrate in network modernization cycles, while software and services capture recurring revenue streams as enterprises shift from capital-intensive to operational expenditure models.
- Hardware:Servers, storage arrays, and networking equipment form the physical foundation of enterprise infrastructure. Northern Italy's manufacturing belt drives sustained procurement of industrial-grade edge devices and 5G radio units. AGID's cloud-first mandates are compressing direct hardware purchases in public administration while elevating demand for sovereign-certified appliances.
- Software:Enterprise applications, system software, and development platforms enable automated workflows and data-driven decision-making. Milan's financial services institutions prioritize compliance-enabled core banking platforms and risk analytics suites. Subscription licensing models are displacing perpetual arrangements across mid-market adopters seeking predictable cost structures.
- Services:Systems integration, managed services, and consulting engagements bridge legacy environments with modern architectures. Rome's public-sector digital transformation hubs generate concentrated demand for certified integration partners. Skills scarcity in zero-trust architecture and multi-cloud orchestration elevates premium pricing for specialized providers.
- Networking:Fiber infrastructure, wireless systems, and software-defined wide area networks connect distributed operations. Telecom Italia S.p.A. and Fastweb S.p.A. compete aggressively in wholesale connectivity expansion toward secondary urban centers.
The dominant share belongs to Services, while Software is closing the gap fastest as recurring revenue models displace one-time transactions.
Deployment Model:
Cost tier differentiation separates enterprises with full capital commitment capability from those prioritizing operational flexibility and risk transfer.
- Cloud:Public and private cloud instances deliver scalable compute and storage without on-premises infrastructure ownership. AGID-qualified providers capture public administration demand under strict certification requirements. Financial services institutions in Milan favor hybrid-ready cloud platforms enabling workload portability across sovereignty boundaries.
- Hybrid:Interoperable environments spanning on-premises, private cloud, and public cloud resources balance control with scalability. Northern Italy's industrial base adopts hybrid architectures to preserve legacy ERP investments while enabling IoT analytics at the edge. Complexity in multi-cloud integration creates sustained demand for platform engineering expertise.
- On-Premises:Dedicated infrastructure within enterprise facilities maintains direct control over sensitive data and critical workloads. Defense and intelligence applications mandate air-gapped deployments regardless of cloud policy pressure. Technical debt in legacy system architectures slows migration velocity despite regulatory deadlines.
- Managed:Outsourced infrastructure operations transfer operational risk to specialized service providers. Mid-market enterprises lacking internal cybersecurity capabilities favor managed security services and threat monitoring platforms.
Hybrid deployments command the largest committed spend, though Cloud is expanding most quickly as procurement teams gain confidence in qualified provider ecosystems.
End User:
Customer type determines compliance burden, procurement timeline, and solution complexity, with public-sector mandates creating structural market access barriers.
- Government:Central ministries, regional authorities, and local administrations execute Europe's most aggressive public-sector digital transformation agenda. PNRR funding channels billions toward cybersecurity hardening and cloud migration under AGID oversight. Procurement qualification requirements limit vendor pools to certified domestic and EU-accredited operators.
- Financial Services:Banks, insurers, and asset managers face DORA compliance deadlines demanding operational resilience investments. Milan's concentrated financial district generates premium demand for real-time payment infrastructure and algorithmic audit platforms. Data localization requirements shape cross-border service architectures.
- Healthcare:Regional health authorities and hospital networks modernize electronic health record systems and telemedicine platforms. Patient data sensitivity elevates cybersecurity investment priorities above other verticals.
- Education:Universities and research institutions deploy high-performance computing and collaborative platforms. Funding constraints relative to other verticals compress solution evaluation cycles and favor open-source alternatives.
Government entities anchor procurement volume, while Financial Services is gaining share fastest as DORA enforcement windows approach.
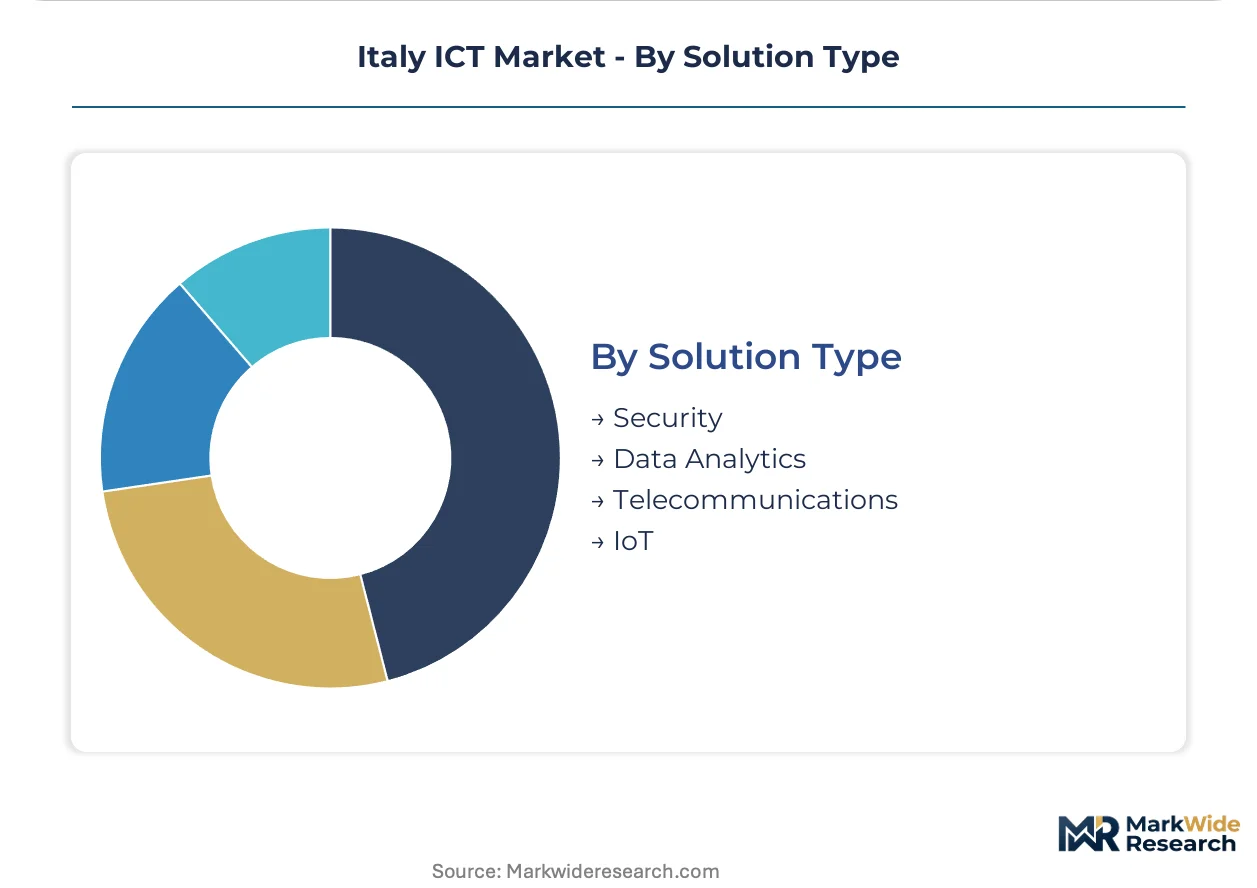
Solution Type:
Margin concentration follows regulatory pressure and threat surface expansion, with security and analytics commanding disproportionate investment.
- Security:Zero-trust architecture, threat intelligence, and identity management protect expanding attack surfaces. NIS2 Directive transposition through national frameworks elevates mandatory capability investments across critical infrastructure operators. Talent scarcity in specialized security functions stretches enterprise budgets and favors managed service consumption.
- Data Analytics:Business intelligence, predictive modeling, and real-time visualization extract operational value from enterprise data. Manufacturing adopters in Lombardy and Emilia-Romagna prioritize supply chain visibility platforms. EU AI Act risk-classification requirements generate demand for automated compliance monitoring tooling.
- Telecommunications:5G standalone deployment, fiber backhaul, and edge computing infrastructure enable next-generation connectivity. TIM's nationwide modernization program creates downstream demand for mission-critical system integration across logistics and manufacturing verticals.
- IoT:Sensor networks, device management platforms, and edge analytics connect physical operations to digital systems. Smart manufacturing and precision agriculture applications drive adoption outside traditional technology centers.
Security solutions hold the dominant position, with Data Analytics climbing the fastest as enterprises operationalize AI governance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision manufacturing equipment and industrial automation systems to Italian enterprises modernizing production lines. France supplies cybersecurity platforms and cloud infrastructure services to Milan's financial district. Spain provides telecommunications hardware supporting TIM's fiber expansion programs.
Lombardy
Milan anchors Italy's financial technology corridor with concentrated demand for DORA-compliant core banking platforms and algorithmic audit systems. AGID cloud-first mandates accelerate procurement cycles for qualified service providers. The metropolitan zone generates premium pricing for zero-trust architecture specialists as compliance deadlines approach.
Lazio
Rome's public-sector digital transformation hubs channel PNRR capital toward cybersecurity hardening and sovereign cloud migration. National government agencies enforce strict data residency requirements for sensitive administrative datasets. Central ministries and regional health authorities represent the most procurement-active segments under tightened qualification rules.
Piedmont
Turin's automotive and aerospace manufacturing base drives demand for industrial IoT platforms and edge computing infrastructure. NIS2 Directive transposition elevates mandatory security investments across critical infrastructure operators. The metropolitan zone lags Milan in fiber penetration, creating whitespace for wholesale connectivity expansion.
Emilia-Romagna
Bologna's precision manufacturing cluster adopts Kubernetes-native workloads to enable real-time supply chain visibility. Container orchestration migrates from experimental environments to production-grade deployments across mid-market enterprises. Technical debt in legacy ERP systems slows hybrid cloud velocity despite policy pressure from Brussels-aligned frameworks.
Veneto
Padua and Verona host pharmaceutical and medical device manufacturers prioritizing patient data protection and telemedicine platform modernization. GDPR-aligned enforcement from the national data protection authority shapes cross-border service architectures. Regional health authorities concentrate procurement for electronic health record systems with elevated cybersecurity investment priorities.
Italy ICT Market Competitive Landscape
On the supply side, the industry is tiered between infrastructure-heavy incumbents and specialized systems integrators. Telecom operators anchor capital-intensive network modernization while IT services firms capture recurring integration revenue. Three archetypes dominate: sovereign-certified cloud providers, mission-critical defense contractors, and wholesale connectivity specialists. Competitive moves center on M&A for cybersecurity capabilities and strategic partnerships for multi-cloud orchestration expertise.
Within the infrastructure tier, Telecom Italia S.p.A. (TIM) and Fastweb S.p.A. occupy positions as scale-driven connectivity providers. Engineering Ingegneria Informatica S.p.A. exemplifies the mission-critical integration archetype serving public administration and defense clients. These three entities represent distinct strategic postures—nationwide infrastructure ownership, wholesale market penetration, and certified government systems integration—each capturing margin pools aligned with regulatory qualification requirements.
| Leading Market Players |
|---|
| Engineering Ingegneria Informatica S.p.A. |
| Fastweb S.p.A. |
| Telecom Italia S.p.A. (TIM) |
| Accenture S.p.A. |
| Wind Tre S.p.A. |
| Nexi S.p.A. |
| Leonardo S.p.A. |
| Capgemini Italia S.p.A. |
| Reply S.p.A. |
| Others |
Supply & Pricing Matrix
Undercapacity in sovereign-certified cloud infrastructure across southern Italy compresses procurement timelines while elevating premium pricing for qualified providers serving AGID-mandated public administration contracts. This utilization imbalance shapes supplier investment priorities and buyer negotiation leverage across the national market.
Pricing Analysis
Legacy on-premises infrastructure versus cloud-native platforms versus sovereign-certified hybrid instances creates a three-tier pricing structure across premium, standard, and economy levels. Subscription-based SaaS consumption models dominate software procurement, with certification grade and volume scale driving price differentiation. Cost compression in mid-market hardware procurement is intensifying because AGID cloud-first mandates redirect capital toward operational expenditure models. Public administration entities show lowest price sensitivity due to PNRR funding availability, while education sector buyers face highest budget constraints favoring open-source alternatives.
Supply Chain Analysis
Tariff exposure between Germany and Italy dominates component sourcing risk for industrial-grade edge devices and precision manufacturing equipment. Hardware supply concentrates in Germany, Taiwan, and South Korea for semiconductors and networking equipment, while software development feeds from Ireland, Poland, and domestic Italian centers. The supply chain rests on specialized silicon components, fiber optic cable, and sovereign-certified server appliances. Single-source vulnerability persists for AGID-qualified security certification bodies. Distribution runs through systems integrators and value-added resellers serving vertical-specific buyer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's ICT sector is recovering from legacy modernization backlog as PNRR capital injection and DORA compliance deadlines synchronize procurement cycles across public and financial services verticals.
For Market Incumbents: Insulate core revenue streams by deepening sovereign cloud certification portfolios ahead of NIS2 Directive full enforcement, and secure multi-cloud orchestration talent pools before cybersecurity skills scarcity intensifies pricing pressure. TIM and Fastweb must defend fiber infrastructure margins against wholesale market entrants, while Engineering Ingegneria Informatica should anchor mission-critical integration relationships through AGID procurement channel control. For New Entrants and Emerging Players: Turin and Naples metropolitan zones offer whitespace for sovereign-certified managed security services targeting NIS2-mandated critical infrastructure operators. Secondary urban fiber extension presents the most penetrable infrastructure opportunity, with AI governance tooling for EU AI Act compliance representing the fastest-closing software segment. A channel partnership strategy with established systems integrators accelerates access to AGID-qualified procurement pipelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed security service providers with AGID certification and zero-trust architecture capabilities. Long-term viability over a multi-year horizon favors platforms combining sovereign cloud infrastructure with automated compliance monitoring. The acquisition target archetype is mid-scale systems integrators holding national security certifications. The signal to watch is acceleration in PNRR disbursement velocity as inflection indicator for public-sector procurement momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Investment | AGID qualification requirements limit vendor pools, creating structural advantage for certified domestic operators. |
| Multi-Cloud Orchestration Platform Integration | Heterogeneous environments spanning public, private, and residual on-premises workloads demand scarce integration expertise. |
| Zero-Trust Architecture Specialist Acquisition | Cybersecurity talent scarcity stretches enterprise budgets and favors consolidated providers with captive technical capabilities. |
| Secondary Urban Fiber Infrastructure Expansion | Turin, Bologna, and Naples metropolitan zones lag Milan in penetration, creating whitespace for wholesale connectivity growth. |
| AI Governance Compliance Tooling Development | EU AI Act risk-classification requirements generate demand for automated audit platforms among financial services adopters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with public sector CIOs, financial services CTOs, systems integration executives, AGID procurement officers, and hyperscaler platform engineers. Secondary validation drew from AGID cloud qualification registries, PNRR disbursement tracking databases, DORA implementation guidance documents, and EU NIS2 transposition monitoring. Bottom-up segment sizing and top-down macroeconomic calibration were triangulated to ensure consistency across data sources.
Calibration against historical procurement cycles and regulatory deadline impacts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical sector, solution type, and regional adoption pattern. CAGRs were derived from trend extrapolation moderated by policy implementation timelines. Forecast inputs incorporated PNRR funding allocation velocity and DORA compliance preparation spending patterns among Milan financial institutions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by sovereign cloud specialists or accelerated PNRR disbursement would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Mobile Apps and Web Analytics Market
Analytics
Global Visual Analytics Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
France Contact Center Analytics Market
Analytics
Global Network Analytics Market
Analytics
Global E-Commerce Analytics Software Market
Analytics
Iraq ICT Market
Analytics
Europe Big Data and Business Analytics Market
Analytics
Manufacturing Analytics Market
Analytics
Global Graph Analytics Market
Analytics
Digital Analytics Solutions Market
Analytics
Global Digital Intelligence Platform Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
IoT Analytics Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market