
 Research and Development (Randd) Analytics Market | 2026-2036
Research and Development (Randd) Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Research and Development (Randd) Analytics Market Analytics
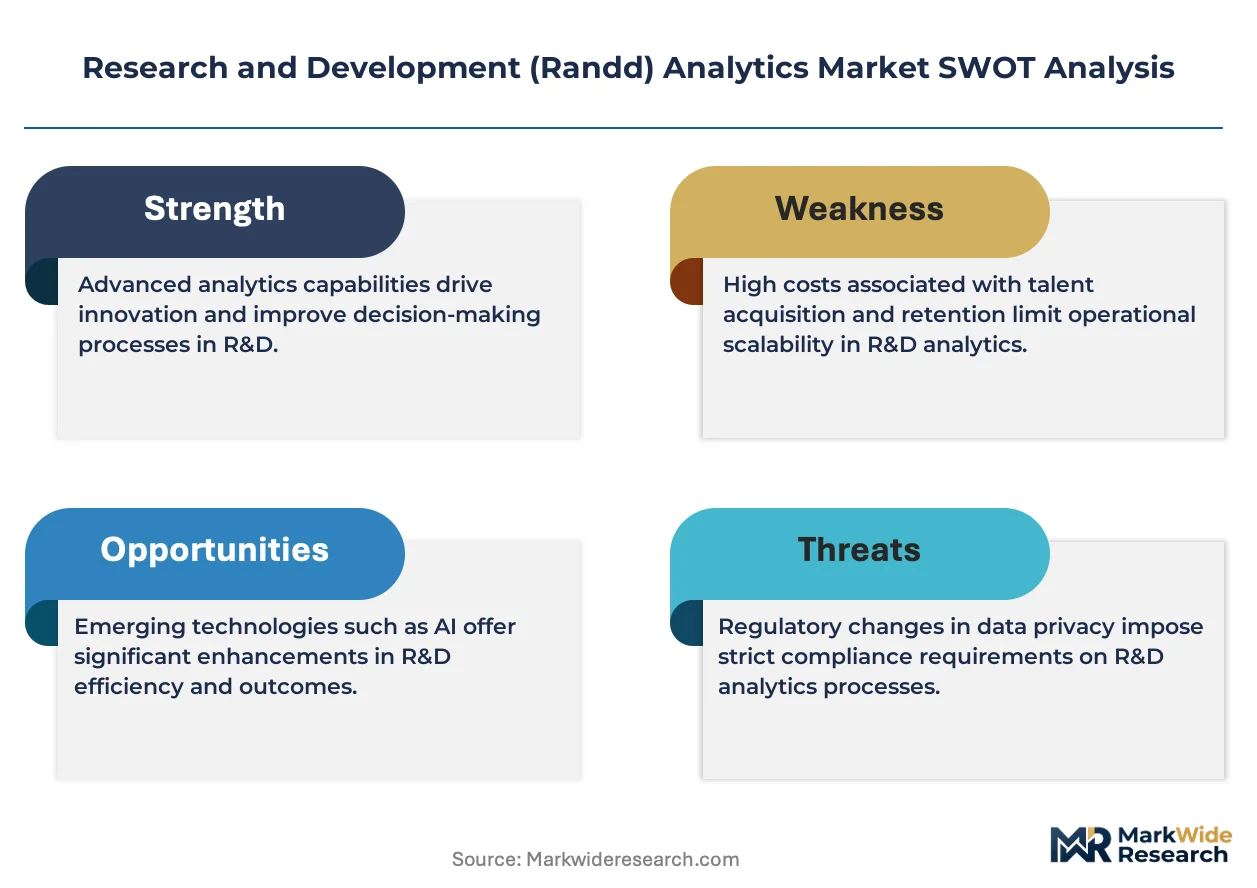
Subscription-based SaaS licensing is fragmenting capital requirements across mid-tier biotech firms and academic consortia. IBM Corporation leverages its Watson Health infrastructure to anchor clinical trial analytics for large pharmaceutical sponsors. Oracle Corporation sustains competitive positioning through in-house cloud architectures that reduce third-party dependency. SAS Institute Inc. specializes in statistical validation protocols that satisfy regulatory submission standards across multiple jurisdictions.
Research and Development Analytics encompasses software platforms that ingest structured and unstructured experimental data, apply machine learning algorithms with p-value thresholds below 0.05, and generate reproducible visualizations for hypothesis validation. These systems primarily accelerate decision cycles in drug discovery, materials science, and engineering design. Cloud-based deployment now leads in new installations, while on-premise systems retain dominance in government labs with classified or patient-identifiable data. Predictive modeling represents the fastest-expanding solution type as sponsors seek to forecast trial enrollment failures before protocol amendments.
FDA 21 CFR Part 11 compliance requirements shape software validation procedures for electronic records in United States clinical trials. EMA's Good Clinical Practice guidelines and GDPR data residency rules in Europe compel vendors to architect region-specific instance isolation. HIPAA security rule enforcement in the United States adds encryption and access-log mandates that increase implementation complexity. Stakeholders must weigh jurisdictional compliance fragmentation against unified platform architectures when selecting deployment strategies.
Market Dynamics
Predictive modeling platforms are compressing trial timelines across pharmaceutical sponsors, creating a structural pull toward cloud-native architectures that can ingest real-world evidence streams at scale.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records compliance mandates in United States clinical trials are forcing sponsors to upgrade validation protocols, expanding addressable market for compliant analytics suites.
- Biopharma cluster concentration:Dedicated analytics centers in Germany's Rhine-Main and Boston-Cambridge corridors are normalizing platform standardization through shared infrastructure investments.
- Machine learning inference at the edge:On-device model deployment is reducing latency for real-time biomarker monitoring in decentralized trials.
Market Restraints
- GDPR data residency:European instance isolation requirements fragment platform architectures, raising operational overhead for unified analytics deployments.
- Specialized biostatistician scarcity:Talent pipelines for regulatory-grade statistical validation remain concentrated in United States and Western European academic centers.
- Legacy on-premise lock-in:Government labs with classified datasets maintain captive infrastructure, slowing cloud migration timelines.
Strategic Opportunities
- Japan's PMDA digital transformation:Regulatory acceptance of synthetic control arms is opening trial design innovation for analytics vendors with Japanese biopharma relationships.
- Materials science convergence:Battery and advanced materials R&D programs are adopting pharmaceutical-grade statistical rigor, expanding addressable use cases.
- Academic consortia subscription models:Shared licensing across university research networks is lowering customer acquisition costs in underpenetrated European markets.
Industry Challenges
- HIPAA security rule implementation:Encryption and access-log mandates add implementation complexity that stretches deployment timelines for United States healthcare data integrations.
- Interoperability with legacy ELN systems:Electronic laboratory notebook data formats lack standardization, requiring costly custom extraction pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Research and Development (Randd) Analytics Market |
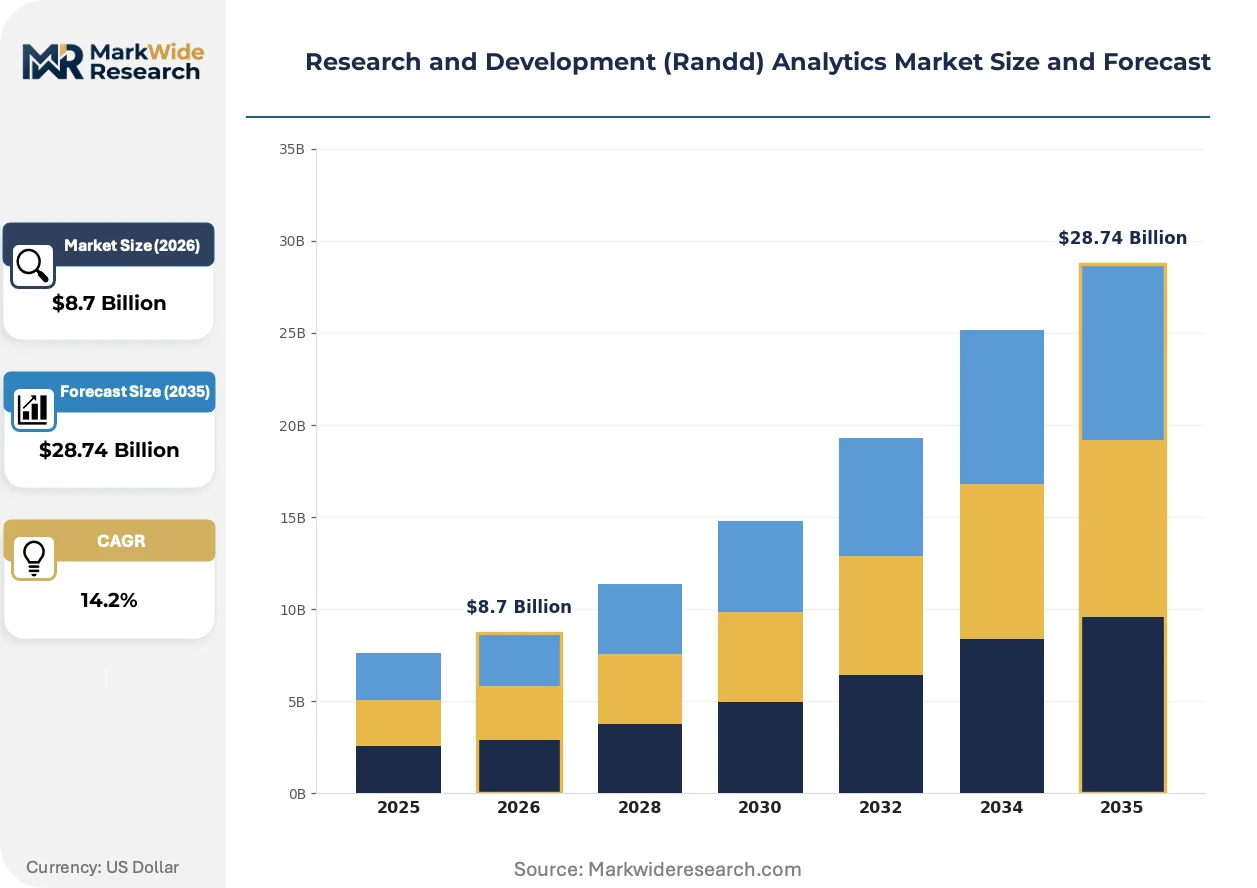
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Analytics, Predictive Modeling, Statistical Analysis, Dashboarding End User: Pharmaceuticals, Biotechnology, Academia, Government Labs Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS Application: Clinical Trials, Product Development, Market Research, Innovation Management |
| Companies Covered | IBM Corporation, Oracle Corporation, SAS Institute Inc., SAP SE, Microsoft Corporation, Accenture, TIBCO Software Inc., Tableau Software, Teradata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Research and Development (Randd) Analytics Market Evolving Landscape
Generative architectures are reshaping how experimental hypotheses get formulated and validated, compressing the iteration cycle between data ingestion and protocol amendment.
Federated learning frameworks are collapsing the traditional trade-off between data utility and privacy preservation in multi-site trials. Large pharmaceutical sponsors in the United States and European Union are deploying these architectures for cross-border biomarker analysis. The structural consequence is collapsing regulatory submission preparation timelines as pooled datasets reach statistical power faster.
EMA's Good Clinical Practice guideline updates are mandating risk-proportionate monitoring approaches that favor centralized statistical surveillance over on-site source verification. This industrial consequence accelerates demand for real-time anomaly detection algorithms. Contract research organizations in Germany and the United Kingdom are responding by consolidating vendor relationships around platforms with embedded compliance modules.
Biotech procurement functions are unbundling analytics licensing from full-service clinical trial contracts, creating direct vendor relationships previously intermediated by CROs. Mid-tier sponsors in Japan and South Korea are leading this disintermediation, negotiating SaaS terms directly. The channel shift is most visible in oncology and rare disease verticals where specialized analytics requirements outstrip generalist CRO capabilities.
Research and Development (Randd) Analytics Market Segmentation
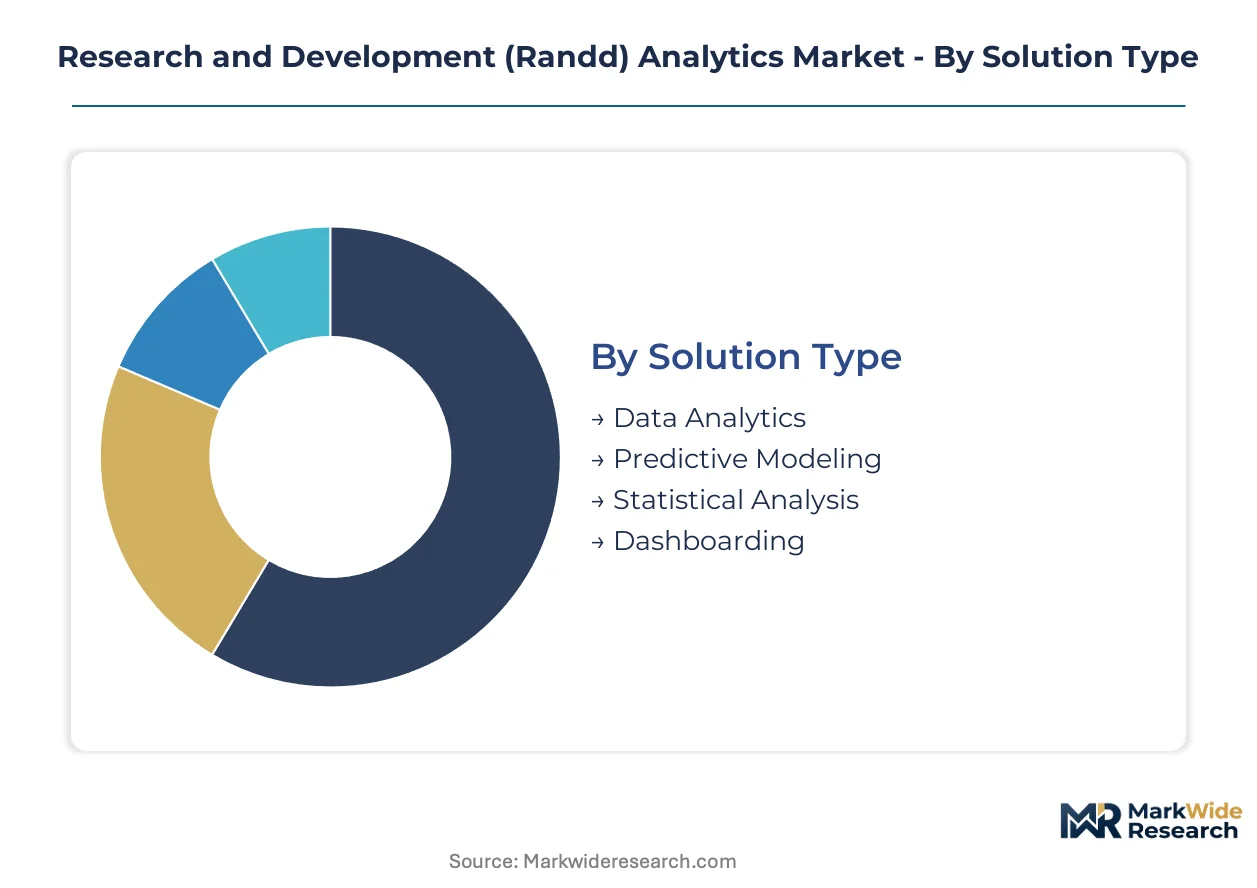
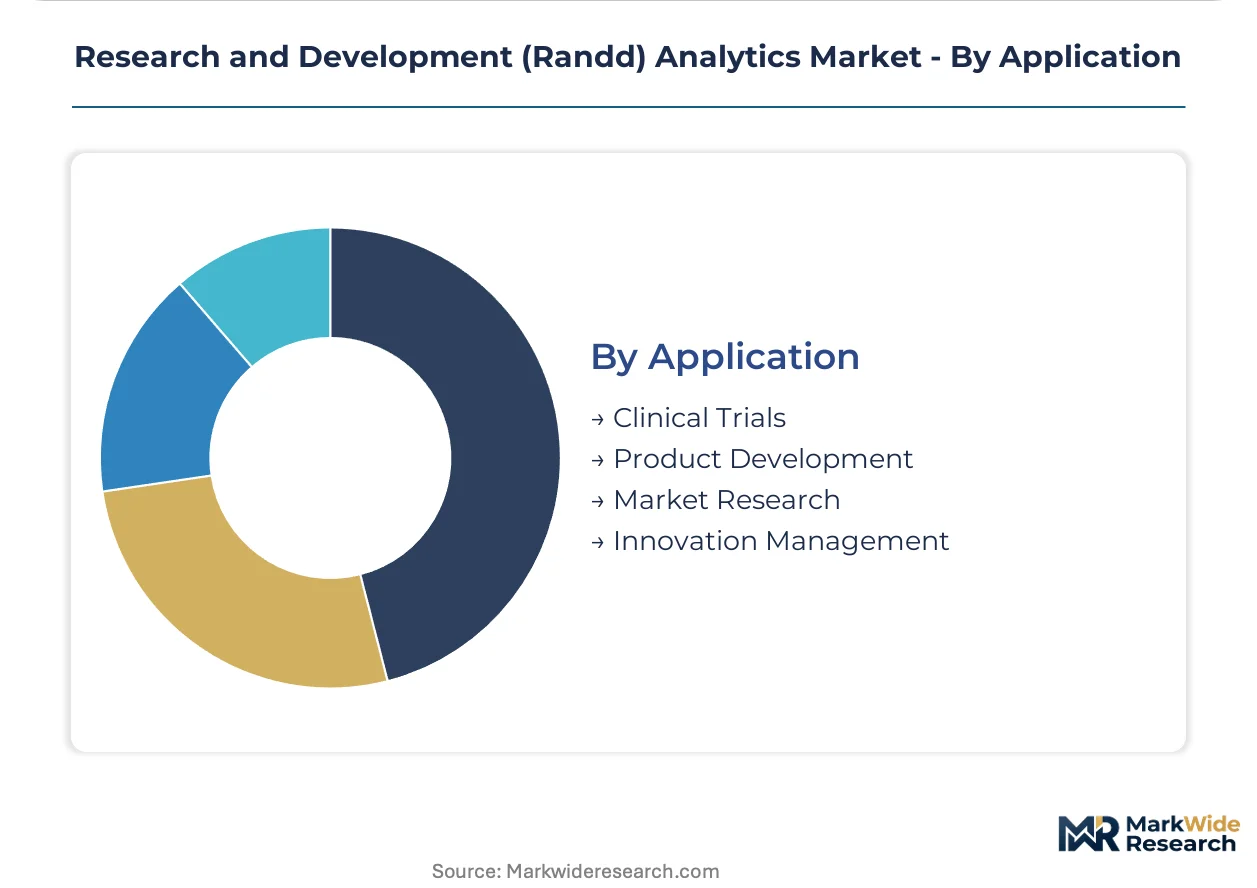
R&D analytics vendors architect platform roadmaps around four intersecting dimensions. Solution type determines computational depth, while deployment model dictates compliance architecture and customer acquisition economics.
Solution Type:
Mature statistical suites coexist with emerging generative architectures across the maturity spectrum.
- Predictive Modeling:Machine learning algorithms forecast trial enrollment failures and biomarker trajectories with p-value thresholds below 0.05. Pharmaceutical sponsors in the United States deploy these platforms to compress protocol amendment cycles ahead of FDA submissions.
- Data Analytics:Ingestion engines process structured and unstructured experimental data from electronic laboratory notebooks and real-world evidence streams. Demand concentrates in Germany's Rhine-Main biopharma corridor where shared infrastructure investments normalize platform standardization.
- Statistical Analysis:Regulatory-grade validation protocols satisfy EMA Good Clinical Practice guidelines across multiple jurisdictions.
- Dashboarding:Visualization layers generate reproducible outputs for hypothesis validation in academic consortia.
Predictive modeling handles the majority of throughput; data analytics is expanding most quickly on share.
End User:
Customer type shapes pricing architecture from enterprise licensing to fractional subscription models.
- Pharmaceuticals:Large sponsors deploy cloud-native architectures with embedded FDA 21 CFR Part 11 compliance modules. IBM Watson Health anchors clinical trial analytics for these customers through dedicated validation protocols.
- Biotechnology:Mid-tier firms fragment capital requirements through subscription-based SaaS licensing. Japan's PMDA digital transformation is opening trial design innovation for vendors with established Japanese biopharma relationships.
- Academia:Shared licensing across university research networks lowers customer acquisition costs in underpenetrated European markets.
- Government Labs:Classified datasets and patient-identifiable data maintain captive on-premise infrastructure, slowing cloud migration timelines.
Pharmaceuticals anchor revenue concentration; biotechnology is climbing the fastest on customer acquisition.
Deployment Model:
Volume distribution tilts toward cloud-native installations while margin pools in hybrid configurations.
- Cloud-Based:Real-time ingestion of real-world evidence streams at scale. HIPAA-aligned data governance protocols in the United States accelerate platform standardization for healthcare data integrations.
- SaaS:Subscription licensing fragments capital requirements across mid-tier biotech firms and academic consortia. Oracle Corporation sustains competitive positioning through in-house cloud architectures that reduce third-party dependency.
- On-Premise:Government labs with classified datasets retain dominance where encryption and access-log mandates stretch deployment timelines.
- Hybrid:Federated learning frameworks collapse the trade-off between data utility and privacy preservation in multi-site trials across the United States and European Union.
Cloud-based deployments handle the majority of new installations; SaaS is gaining share fastest on pricing accessibility.
Application:
Geography determines regulatory overlay intensity across use case portfolios.
- Clinical Trials:EMA risk-proportionate monitoring mandates favor centralized statistical surveillance over on-site source verification. Contract research organizations in Germany and the United Kingdom consolidate vendor relationships around platforms with embedded compliance modules.
- Product Development:Battery and advanced materials R&D programs adopt pharmaceutical-grade statistical rigor, expanding addressable use cases beyond life sciences.
- Market Research:Synthetic control arms and real-world evidence integration reshape competitive intelligence workflows.
- Innovation Management:Generative architectures compress iteration cycles between data ingestion and protocol amendment in early-stage discovery.
Clinical trials handle the majority of platform throughput; product development is expanding most quickly on cross-industry adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 compliance mandates and Japan's PMDA digital transformation are reshaping procurement patterns across major biopharma clusters. Government-funded analytics centers in Germany and academic consortia in the United Kingdom are accelerating platform standardization through shared infrastructure investments.
United States
HIPAA-aligned data governance protocols and cloud migration incentives are compressing deployment timelines for healthcare data integrations. FDA 21 CFR Part 11 electronic records compliance forces sponsors to upgrade validation protocols, expanding demand for compliant analytics suites. The Boston-Cambridge corridor anchors dedicated analytics centers where large pharmaceutical sponsors deploy predictive modeling platforms.
Germany
EMA Good Clinical Practice guidelines and risk-proportionate monitoring mandates favor centralized statistical surveillance over traditional verification methods. GDPR data residency requirements compel vendors to architect region-specific instance isolation, fragmenting platform architectures. The Rhine-Main biopharma corridor normalizes platform standardization through shared infrastructure investments across contract research organizations.
Japan
PMDA regulatory acceptance of synthetic control arms opens trial design innovation for vendors with established biopharma relationships. METI digital transformation programs accelerate cloud-native platform procurement among mid-tier sponsors. Tokyo and Osaka clusters lead disintermediation trends as biotech procurement functions unbundle analytics licensing from full-service contracts.
United Kingdom
EMA guideline updates and post-Brexit regulatory alignment discussions are reshaping compliance module requirements for analytics platforms. GDPR enforcement maintains strict data residency rules that raise operational overhead for unified deployments. London and Cambridge academic consortia lower customer acquisition costs through shared licensing across university research networks.
India
CDSCO regulatory harmonization efforts and government-funded pharmaceutical research programs are expanding analytics platform procurement among domestic manufacturers. The country's national data protection framework is evolving toward stricter residency requirements. Hyderabad and Bangalore biotech clusters are adopting subscription-based SaaS licensing to fragment capital requirements across emerging sponsors.
Research and Development (Randd) Analytics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where scale advantages concentrate in cloud-native architectures. Large technology conglomerates anchor enterprise licensing through embedded compliance modules, while statistical specialists occupy regulatory-grade validation niches. Two strategic archetypes dominate: infrastructure-integrated platforms and domain-specific analytics suites. Competitive moves center on federated learning partnerships and academic consortia subscription models that lower customer acquisition costs.
Among infrastructure-integrated platforms, IBM Corporation and Oracle Corporation exemplify the channel-control archetype through captive cloud architectures and enterprise validation protocols. SAS Institute Inc. occupies a specialist position representing the regulatory-grade statistical validation tier, with its positioning reflecting demand for multi-jurisdictional submission standards. These three anchors illustrate how vendor strategies diverge between unified platform breadth and compliance-depth specialization.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| SAS Institute Inc. |
| SAP SE |
| Microsoft Corporation |
| Accenture |
| TIBCO Software Inc. |
| Tableau Software |
| Teradata |
| Others |
Value Network & Pricing Analysis
The Rhine-Main logistics corridor's data-center connectivity costs compress margins for cloud-native platform providers while amplifying price spreads between FDA-validated enterprise suites and mid-market SaaS tiers. Supply concentration in Germany's biopharma cluster creates procurement leverage for large sponsors, forcing vendors to absorb infrastructure overhead or cede share to Oracle's captive cloud architecture.
Pricing Analysis
Certification level (FDA 21 CFR Part 11, EMA GCP, HIPAA Security Rule) creates the primary spread between enterprise and mid-market tiers. Subscription-based SaaS licensing dominates, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on validation protocol depth and embedded compliance module scope. Pricing pressure stems from academic consortia subscription models fragmenting capital requirements. Government labs with classified datasets exhibit lowest price sensitivity; mid-tier biotech firms in Japan and South Korea show highest.
Supply Chain Analysis
Extended payment terms from large pharmaceutical sponsors in the United States and Germany compress working capital for specialized statistical validation vendors. Supply concentrates in the United States, Germany, and Japan where biopharma clusters fund dedicated analytics centers. Raw material dependencies include cloud compute capacity, proprietary machine learning frameworks, and regulatory-grade validation talent pools. Single-source vulnerability sits with hyperscaler infrastructure for real-world evidence ingestion. Distribution runs through direct vendor relationships increasingly disintermediated from CRO channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where FDA 21 CFR Part 11 validation protocols create switching costs that compound with each protocol amendment cycle.
For Market Incumbents: Build switching-cost moats through deeper FDA validation protocol integration that locks sponsors into amendment-cycle dependencies. Consolidate federated learning partnerships with European academic consortia before GDPR instance isolation requirements fragment architectures further. Threat of emerging cloud-native entrants with generative architectures demands capacity addition in Germany's Rhine-Main corridor to defend latency advantages.
For New Entrants and Emerging Players: Mid-market biotech firms in Japan's Tokyo-Osaka corridor represent the most penetrable entry point where PMDA synthetic control arm acceptance outstrips incumbent localization. Academic consortia in the United Kingdom offer shared licensing traction with lower customer acquisition costs than direct pharmaceutical sponsorship. Go-to-market angle: federated learning frameworks that collapse GDPR data residency trade-offs for multi-site European trials.
For Investors and Strategic Acquirers: Statistical validation specialists with multi-jurisdictional submission capabilities anchor acquisition interest as regulatory fragmentation accelerates. Long-term viability frames around 5-10 year entrenchment of predictive modeling platforms in protocol amendment workflows. Signal to watch: PMDA regulatory guidance updates on real-world evidence integration as inflection indicator for Japanese market penetration depth.
| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Collapses GDPR data residency trade-offs for EMA-compliant multi-site biomarker analysis. |
| Regulatory Validation Investment | Deepens FDA 21 CFR Part 11 entrenchment to compress sponsor switching timelines. |
| Academic Consortia Licensing | Fragments capital requirements across underpenetrated European university research networks. |
| Cloud-Native Architecture Migration | Reduces third-party dependency for real-world evidence ingestion at pharmaceutical scale. |
| Synthetic Control Arm Development | Captures PMDA regulatory acceptance for trial design innovation in Japanese oncology. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, platform engineers, and CRO procurement managers and refined through secondary validation. Sources included FDA 21 CFR Part 11 guidance documents, EMA Good Clinical Practice updates, ClinicalTrials.gov protocol registries, and hyperscaler cloud infrastructure disclosures. Bottom-up triangulation across deployment model economics and top-down validation against biopharma R&D expenditure patterns anchored segmentation integrity.
Demand-supply balance framing shaped the analytical framework across the analysis window. Segmentation dimensions modeled include solution type, deployment architecture, end-user scale tier, and regional regulatory cluster complexity. CAGRs derived from cohort-based progression analysis of cloud migration timelines and SaaS pricing accessibility curves. Industry-specific inputs incorporated HIPAA security rule implementation lag times and PMDA digital transformation procurement velocity.
Macroeconomic conditions sit as an overlay; deviation in biopharma R&D funding cycles or cloud infrastructure cost trajectories would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization pace and federated learning adoption thresholds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Augmented Analytics Market
Analytics
Brazil Big Data Analytics Market
Analytics
CSP Network Analytics Market
Analytics
Europe Data Monetization Market
Analytics
Social Business Intelligence Market
Analytics
IT Operation Analytics (ITOA) Market
Analytics
Embedded Analytics Market
Analytics
US Video Analytics Market
Analytics
Global AI Video Analytics Market
Analytics
Data Discovery Market
Analytics
Global Customer Experience Analytics Market
Analytics
Content Analytics and Discovery Software Market
Analytics
Global Development Analytics Tools Market
Analytics
Embedded Analytics Software Market
Analytics
Data Visualization Market
Analytics
Multi-Touch Attribution Market