
 China Contact Center Analytics Market | 2026-2036
China Contact Center Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
China Contact Center Analytics Market Insights
China's domestic software infrastructure is consolidating around state-backed cloud platforms and licensed foreign technology partnerships. Huawei leverages its nationwide server footprint to anchor on-premises deployment pipelines for state-owned enterprises. NICE Ltd competes through specialized speech analytics modules adapted for Mandarin phonetic structures. Cisco Systems Inc sustains channel control via certified reseller networks in tier-one cities.
Contact center analytics encompasses the capture, processing, and interpretation of structured and unstructured customer interaction data across voice, text, and digital channels, employing natural language processing engines with sub-200-millisecond latency requirements to surface operational intelligence. Its primary commercial purpose is reducing average handle time while elevating first-contact resolution rates in high-volume service environments. Cloud-based deployment is displacing legacy on-premises installations as Chinese enterprises prioritize elastic capacity scaling during promotional surges. Speech analytics leads technology adoption among Mandarin-language service operations, while predictive analytics represents the fastest-expanding margin pool as insurers and lenders apply churn models to voice transcripts.
SAMR enforces algorithmic recommendation provisions that constrain how analytics platforms process personal data from customer interactions. MIIT's cybersecurity review framework mandates domestic data residency for cloud-based contact center operations. GB standards for information security technology shape product certification requirements for foreign vendors seeking market access. Stakeholders must monitor regulatory adjustments to cross-border data transfer mechanisms that could alter hybrid deployment economics.
Market Dynamics
MIIT's data localization mandate is compressing deployment timelines and forcing vendors to re-architect cloud infrastructure around domestic server footprints, fundamentally restructuring how analytics platforms reach Chinese enterprises.
Growth Catalysts
- Speech Analytics:Mandarin phonetic processing engines are automating quality assurance workflows across Chinese banking call centers, reducing manual review overhead.
- SAMR Algorithmic Oversight:Compliance requirements for recommendation algorithms are creating audit-trail demand that analytics platforms monetize through specialized modules.
- Shanghai Financial Corridor:Concentrated insurer and lender headquarters are driving cluster procurement of predictive churn modeling tools.
Market Restraints
- GPU Supply Concentration:Training latency for NLP engines depends on NVIDIA accelerator availability, with import restrictions creating pipeline bottlenecks.
- GB Certification Timelines:Foreign vendors face extended product approval cycles under information security technology standards, delaying market entry.
- On-Premises Lock-In:State-owned enterprises maintain legacy hardware investments that resist cloud migration despite elastic capacity advantages.
Strategic Opportunities
- Guangdong Manufacturing Belt:Industrial equipment suppliers remain underserved by voice analytics, presenting greenfield deployment potential for Mandarin-speaking technician support lines.
- Dual Carbon Goals:Energy consumption reporting requirements are extending analytics procurement to utility sector contact centers tracking customer efficiency programs.
- Edge-NLP Convergence:On-device inference chips paired with lightweight transformer models are enabling real-time sentiment analysis without cloud round-trips.
Industry Challenges
- Mandarin Dialect Variation:Training data scarcity for Cantonese and regional accents degrades transcription accuracy in southern province deployments.
- Hybrid Integration Complexity:Enterprises running parallel on-premises and cloud instances face synchronization failures between transcript repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Contact Center Analytics Market |
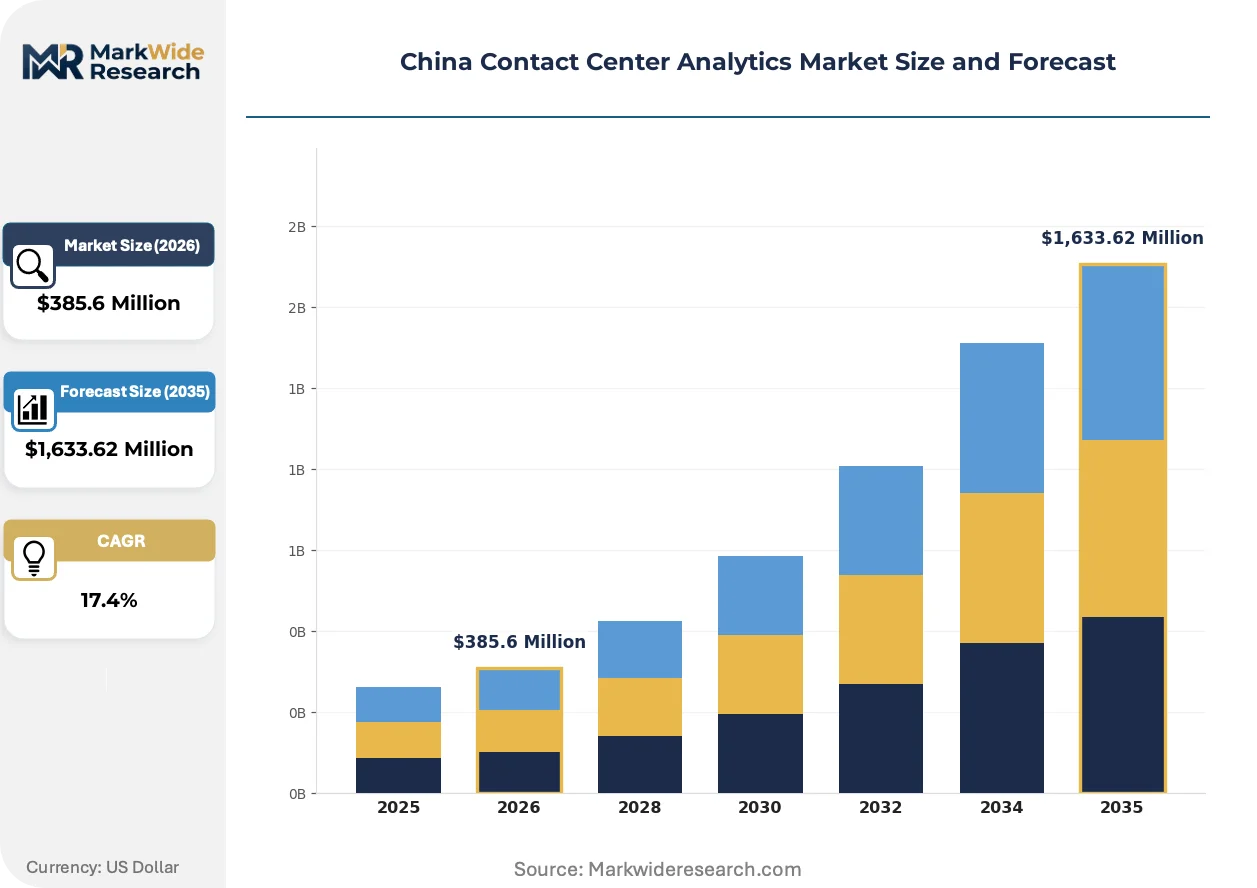
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,633.62 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service Technology: Speech Analytics, Text Analytics, Predictive Analytics, Reporting Tools End User: Retail, Telecommunications, Banking, Healthcare Solution: Workforce Optimization, Quality Management, Customer Feedback, Performance Analytics |
| Companies Covered | Huawei, NICE Ltd, Oracle Corp, Cisco Systems Inc, Genesys, Five9 Inc, CallMiner, 8x8 Inc, SAP SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Contact Center Analytics Market Trends and Innovations
Real-time inference architectures are compressing decision windows from minutes to milliseconds, forcing vendors to re-engineer processing pipelines around sub-200-millisecond latency benchmarks.
Transformer-based speech recognition is overtaking traditional acoustic models in Mandarin contact center deployments. Chinese insurers are adopting these engines for live call guidance, embedding next-best-action prompts directly into agent desktops. The shift is overtaking rule-based quality scoring systems that required post-call batch processing.
MIIT's cybersecurity review framework is mandating domestic data residency for all cloud-based customer interaction storage. Foreign vendors must establish sovereign infrastructure partnerships or forfeit public sector contracts. Financial services firms in Shanghai are responding by bifurcating deployments: domestic clouds for regulated data, offshore instances for non-sensitive analytics development.
Subscription pricing for analytics modules is displacing perpetual license structures among mid-market Chinese enterprises. SaaS consumption models align vendor incentives with measurable outcome improvements rather than upfront feature delivery. This transition is most visible among Shenzhen-based electronics manufacturers consolidating vendor relationships under platform-wide agreements.
China Contact Center Analytics Market Segmentation
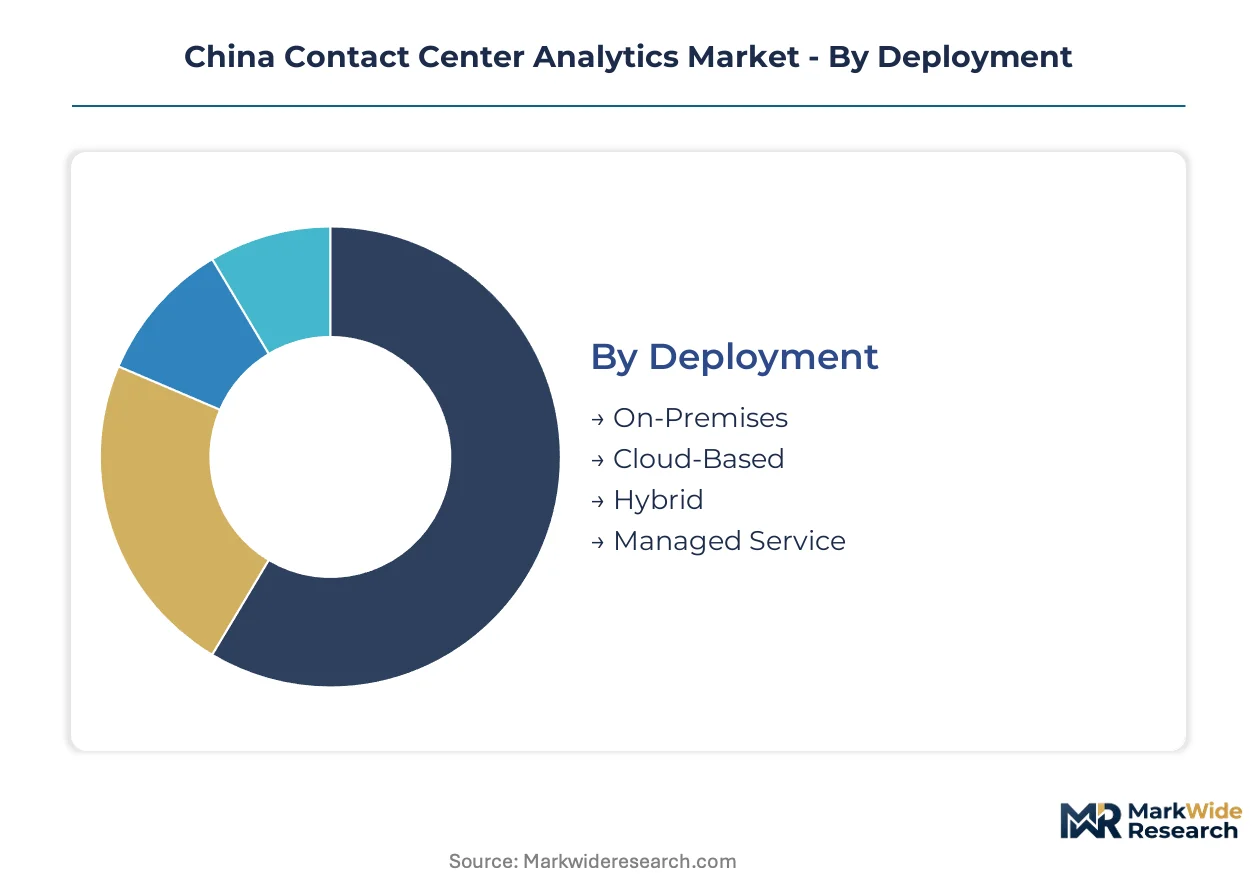
Contact center analytics in China fragments across deployment architectures, underlying technologies, industry verticals, and functional solution modules. Procurement patterns diverge sharply between state-owned enterprises favoring capital-intensive on-premises stacks and private-sector firms prioritizing operational flexibility through cloud consumption models.
Deployment:
Capital intensity varies dramatically across deployment modes, with on-premises installations demanding the heaviest upfront infrastructure commitment while cloud alternatives shift expenditure to recurring operational budgets.
- On-Premises:Dedicated server racks and licensed software installations within enterprise data centers. State-owned banks in Beijing and Shanghai sustain this model to satisfy MIIT data residency mandates and maintain direct control over sensitive voice recordings.
- Cloud-Based:Elastic compute resources provisioned through domestic hyperscale providers. Shenzhen-based electronics manufacturers and Hangzhou e-commerce platforms favor this architecture for promotional surge capacity without hardware procurement cycles.
- Hybrid:Bifurcated architectures splitting regulated data onto private infrastructure while routing development workloads to public cloud. Financial services firms in Shanghai's Lujiazui district deploy this pattern to reconcile compliance with innovation velocity.
- Managed Service:Outsourced operation of analytics infrastructure by third-party specialists. Mid-market insurers lacking internal IT depth contract these arrangements for predictable monthly expenditure.
Most installed capacity flows through On-Premises deployments among state-affiliated institutions. Expansion is steepest in Cloud-Based configurations as private enterprises abandon hardware ownership.
Technology:
Processing sophistication and integration complexity distinguish these technology layers, with speech engines requiring the most specialized Mandarin linguistic training.
- Speech Analytics:Real-time phonetic transcription and acoustic pattern recognition for Mandarin-language voice interactions. Chinese banking call centers deploy these engines to automate quality assurance and flag compliance violations during live conversations.
- Predictive Analytics:Machine learning models applied to historical interaction data for churn forecasting and next-best-action recommendation. Lenders in Shanghai's financial corridor concentrate procurement here for customer retention optimization.
- Text Analytics:Natural language processing of written channels including chat transcripts, email threads, and social media mentions. E-commerce platforms deploy these tools for sentiment monitoring across customer service tickets.
- Reporting Tools:Dashboard and visualization modules aggregating operational metrics for management review. These solutions command lower unit pricing and integrate across upstream analytics engines.
Speech Analytics absorbs the largest share of current technology spending. Predictive Analytics is climbing the fastest as insurers and lenders operationalize churn models.
End User:
Regulatory exposure and customer interaction volume shape procurement intensity across verticals, with financial services facing the strictest oversight requirements.
- Banking:Commercial and retail banks deploying speech analytics for automated compliance monitoring under SAMR algorithmic oversight rules. State-owned institutions dominate this segment with multi-year transformation budgets.
- Telecommunications:Mobile network operators processing massive call center volumes across subscriber base management and technical support functions. These carriers prioritize real-time sentiment analysis for churn prevention.
- Retail:Omnichannel merchants integrating analytics across physical store helplines and digital customer service platforms. Demand concentrates among Alibaba-affiliated and JD.com ecosystem sellers.
- Healthcare:Hospital appointment systems and pharmaceutical hotlines adopting voice analytics for patient interaction quality. Penetration remains limited due to fragmented provider IT maturity.
Banking channels the deepest analytics investment per seat. Retail is expanding most quickly as livestream commerce drives explosive customer service volume.
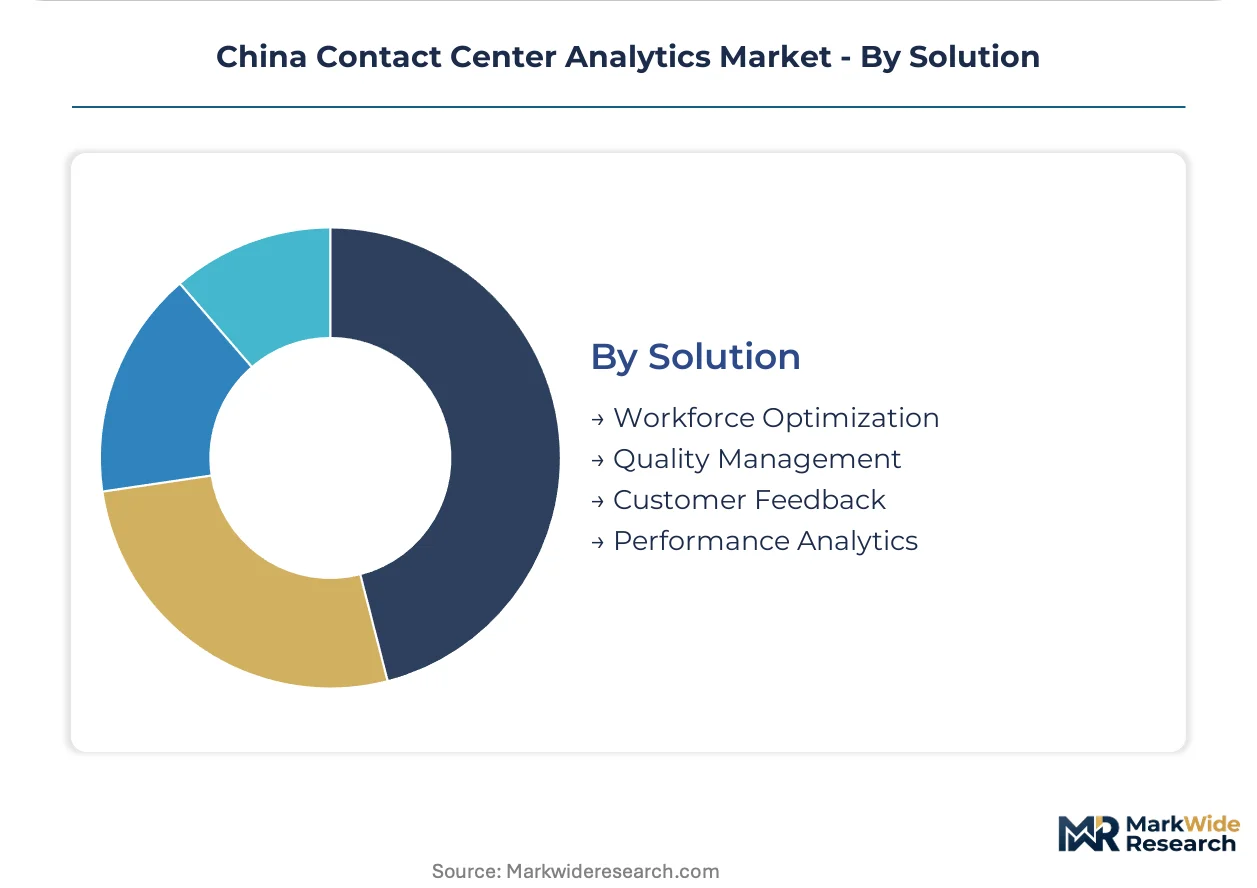
Solution:
Functional scope ranges from workforce-centric optimization tools to customer-facing feedback systems, with quality management commanding premium pricing for compliance-critical deployments.
- Quality Management:Automated scoring and compliance auditing of agent-customer interactions. Chinese insurers deploy these modules to satisfy SAMR audit-trail requirements for algorithmic decision documentation.
- Workforce Optimization:Scheduling, forecasting, and performance management tools for contact center staffing. Large telecommunications carriers in Guangdong and Jiangsu provinces drive volume here.
- Customer Feedback:Post-interaction survey orchestration and voice-of-customer aggregation. Retailers leverage these solutions to correlate service quality with repurchase behavior.
- Performance Analytics:Operational dashboards tracking handle time, first-contact resolution, and cost-per-interaction metrics. These tools penetrate most widely across mid-market enterprises seeking visibility without specialized compliance features.
Quality Management captures the highest solution-tier pricing. Customer Feedback is gaining share fastest as Net Promoter Score methodologies spread from multinational subsidiaries to domestic enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance cost differentials between domestic and foreign cloud infrastructure are redirecting procurement toward state-backed platforms. MIIT's data residency mandates compress deployment timelines for vendors lacking sovereign server partnerships. Enterprises arbitrage this gap by bifurcating sensitive workloads onto licensed domestic infrastructure.
Yangtze River Delta
Shanghai's financial services corridor concentrates insurer and lender headquarters driving predictive analytics procurement. SAMR algorithmic oversight rules mandate audit-trail capabilities that quality management modules satisfy. Lujiazui district firms deploy hybrid architectures splitting regulated data onto private clouds while routing development offshore.
Pearl River Delta
Shenzhen electronics manufacturers prioritize elastic capacity scaling during promotional surges through cloud consumption models. MIIT cybersecurity review frameworks accelerate domestic hyperscale provider selection over foreign alternatives. Guangzhou-based mid-market enterprises consolidate vendor relationships under platform-wide subscription agreements.
Beijing-Tianjin-Hebei
State-owned banks sustain capital-intensive on-premises installations to satisfy direct control requirements over sensitive voice recordings. GB standards for information security technology shape product certification timelines extending foreign vendor market entry. Beijing headquarters of national carriers drive workforce optimization tool procurement across technical support functions.
Sichuan-Chongqing
Western China manufacturing belt remains underserved by Mandarin-language voice analytics for technician support lines. Dual carbon goals extend analytics procurement to utility sector contact centers tracking customer efficiency programs. Chengdu-based industrial equipment suppliers present greenfield deployment potential for real-time sentiment analysis.
China Contact Center Analytics Market Competitive Landscape
Domestic technology conglomerates anchor one tier; specialized foreign analytics vendors hold differentiated positions through Mandarin phonetic adaptations. Market structure consolidates around state-backed cloud platforms with licensed foreign technology partnerships forming a secondary tier. Three archetypes dominate: infrastructure-integrated conglomerates, speech analytics specialists, and certified channel operators. Competitive moves concentrate on sovereign infrastructure partnerships and GB certification acceleration to compress approval cycles.
Among domestic infrastructure providers, Huawei leverages nationwide server footprints to anchor on-premises deployment pipelines for state-owned enterprises. NICE Ltd and Cisco Systems Inc occupy positions within the foreign specialist tier, with NICE representing speech analytics modules adapted for Mandarin phonetic structures and Cisco exemplifying channel control through certified reseller networks in tier-one cities.
| Leading Market Players |
|---|
| Huawei |
| NICE Ltd |
| Oracle Corp |
| Cisco Systems Inc |
| Genesys |
| Five9 Inc |
| CallMiner |
| 8x8 Inc |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
Mandarin NLP engineering talent clusters in Beijing and Shanghai, with labor-cost differentials between tier-one cities and interior provinces widening pricing-tier spreads for equivalent analytics modules by fifteen to twenty percent.
Pricing Analysis
Certified reseller margins absorb twelve to eighteen percent of end-customer expenditure before reaching enterprise buyers. Subscription SaaS tiers now dominate private-sector procurement, while state-owned banks negotiate perpetual licenses with multi-year support bundles. Price differentiation hinges on GB certification status and Mandarin phonetic engine accuracy scores. Cost compression in mid-market cloud tiers intensifies as domestic hyperscalers bundle analytics into broader enterprise suites. Electronics manufacturers in Shenzhen exhibit highest price sensitivity; state-owned financial institutions in Beijing show least.
Supply Chain Analysis
NVIDIA GPU supply rests on US and Taiwan fabrication capacity, with import licensing delays extending deployment timelines for training-intensive NLP engines. Chinese foundries draw from domestic silicon sources for inference-optimized chips. Transformer model weights and Mandarin acoustic training data represent secondary input dependencies. Single-source vulnerability concentrates in advanced node semiconductor access. Distribution runs through Huawei's nationwide server infrastructure partnerships and certified systems integrator networks in tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT's data localization mandate operates as a regulatory compounder, with cybersecurity review deadlines forcing procurement acceleration across financial services and telecommunications verticals.
For Market Incumbents: Deploy sovereign infrastructure partnerships as the primary lever. Foreign vendors must establish domestic cloud alliances or forfeit public sector contracts to Huawei-anchored competitors. Incumbents should accelerate GB certification investments to compress approval timelines against emerging domestic challengers. Channel control through certified reseller networks in Shanghai and Beijing remains defensible against direct-sales entrants.
For New Entrants and Emerging Players: SAMR algorithmic oversight rules in China open a window for compliance-specialist modules. Greenfield opportunity concentrates in Guangdong manufacturing belt technician support lines, currently underserved by Mandarin voice analytics. Edge-NLP convergence for on-device sentiment analysis represents the most penetrable technology entry point. Go-to-market should route through industrial equipment OEMs with captive service networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among speech analytics specialists with existing Mandarin phonetic adaptations and MIIT certification progress. Long-term viability favors vendors with hybrid deployment architectures reconciling domestic data residency with offshore R&D velocity. Watch GPU import license approval velocity as the critical inflection signal for training-capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | MIIT cybersecurity review mandates domestic data residency for public sector contracts. |
| GB Certification Acceleration | Information security technology standards shape foreign vendor market entry timelines. |
| Mandarin Phonetic Engine Development | Cantonese and regional accent coverage degrades transcription accuracy in southern deployments. |
| Edge-NLP Hardware Integration | On-device inference chips enable real-time sentiment analysis without cloud round-trips. |
| Vertical-Specific Compliance Modules | SAMR algorithmic oversight rules create audit-trail demand that analytics platforms monetize. |
Research Methodology
Direct dialogue with contact center operations directors, MIIT compliance officers, Huawei channel partners, and Mandarin NLP engineering leads grounded qualitative findings. Secondary validation drew from MIIT cybersecurity review filings, SAMR algorithmic recommendation enforcement notices, hyperscaler capex disclosures, and GB standards documentation. Bottom-up deployment counts triangulated against top-down enterprise IT expenditure estimates.
Segmented outputs across deployment architecture, underlying technology, industry vertical, and functional solution module structured the analytical framework. CAGRs derived from elasticity-adjusted adoption curves incorporating MIIT mandate compliance deadlines and cloud migration velocity across state-owned versus private enterprise archetypes. Forecast inputs included GPU import license approval rates and domestic foundry capacity expansion for inference-optimized chips.
Revisions become necessary when MIIT adjusts cross-border data transfer mechanisms or when NVIDIA export licensing frameworks shift materially. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and domestic cloud provider capacity scaling. A small set of triggers—GPU supply restrictions, GB certification timeline extensions, and SAMR algorithmic oversight scope expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Embedded Analytics Market
Analytics
Global Subscription Analytics Software Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
APAC Operational Intelligence Market
Analytics
Data Analysis Tools Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Global AI Video Analytics Market
Analytics
Application Analytics Market
Analytics
Global Telecom Analytics Market
Analytics
Europe Location Analytics Market
Analytics
In-Memory Analytics Tools Market
Analytics
Data Analytics Market
Analytics
France Contact Center Analytics Market
Analytics
Data Analytics Outsourcing Market
Analytics
Location Analytics Adoption Spending Market
Analytics
Voice Analytics Market