
 Global Saas-Based Business Analytics Market | 2026-2036
Global Saas-Based Business Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Saas-Based Business Analytics Market Foresight
ISO/IEC 27001 certification is reorganizing competitive access in SaaS-based business analytics, as enterprise procurement teams mandate verified information security management systems before vendor onboarding. Microsoft leverages its Azure cloud backbone to anchor large-scale deployments across Fortune 500 accounts. SAP differentiates through deep ERP integration that embeds analytics directly into operational workflows. Salesforce sustains its position by extending CRM-native intelligence into predictive revenue operations.
SaaS-based business analytics comprises cloud-delivered software platforms that ingest, process, and visualize structured and unstructured data through multi-tenant architectures with sub-second query response thresholds, serving primarily to compress decision cycles from weeks to hours in data-intensive organizations. Public cloud deployment dominates volume due to elastic scaling economics, though hybrid cloud configurations capture expanding margin pools from regulated industries requiring on-premise data sovereignty. Predictive analytics solutions are accelerating fastest as organizations embed machine learning models into recurring operational decisions rather than retrospective reporting.
The EU AI Act and GDPR jointly constrain algorithmic transparency requirements and cross-border data residency rules for analytics vendors serving European enterprises, while India's Digital Personal Data Protection Act imposes comparable localization obligations on cloud providers operating in South Asia. ISO standards for cloud service continuity and NIST cybersecurity frameworks further shape product architecture investments across major platforms. Stakeholders must monitor how divergent national AI governance regimes fragment platform development roadmaps and compliance cost structures.
Market Dynamics
Machine learning inference at the edge is compressing query latency requirements, forcing vendors to re-architect multi-tenant platforms for sub-second response on streaming data pipelines.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making tools in financial services and healthcare must now embed explainability layers, creating upgrade cycles across installed analytics bases.
- Retail omnichannel data unification:Merchants operating brick-and-mortar and digital storefronts require cloud-native platforms that harmonize inventory, customer, and transaction streams into single analytical views.
- India's analytics outsourcing expansion:Domestic IT services firms are building captive delivery centers in Bengaluru and Hyderabad, pulling platform licensing demand from Western enterprises seeking cost arbitrage.
Market Restraints
- Cross-border data localization costs:India's Digital Personal Data Protection Act and comparable EU GDPR residency rules force redundant infrastructure deployment, inflating operational expenditure for multi-region vendors.
- ISO/IEC 27001 certification bottlenecks:Enterprise procurement teams now mandate verified information security management systems, excluding uncertified challengers from Fortune 500 RFPs.
- Hybrid cloud architecture complexity:Regulated industries requiring on-premise data sovereignty demand bespoke configurations that fragment platform standardization and dilute SaaS margin economics.
Strategic Opportunities
- Predictive analytics in operational workflows:Organizations are embedding machine learning models into recurring decisions rather than retrospective reporting, opening subscription expansion within existing accounts.
- ERP-native analytics integration:Deep embedding of intelligence into operational systems like SAP creates switching costs and captive demand from manufacturing and supply chain verticals.
- NIST cybersecurity framework alignment:Federal contractor procurement standards in the US are creating preference for platforms with documented compliance, favoring established vendors with dedicated government sales teams.
Industry Challenges
- MLOps talent scarcity:The pipeline shortage of engineers capable of deploying production-grade machine learning operations is extending implementation timelines and inflating professional services costs.
- Legacy data warehouse migration friction:Enterprises with decades of on-premise analytical infrastructure face schema translation complexity and business-user retraining burdens that stall cloud transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Saas-Based Business Analytics Market |
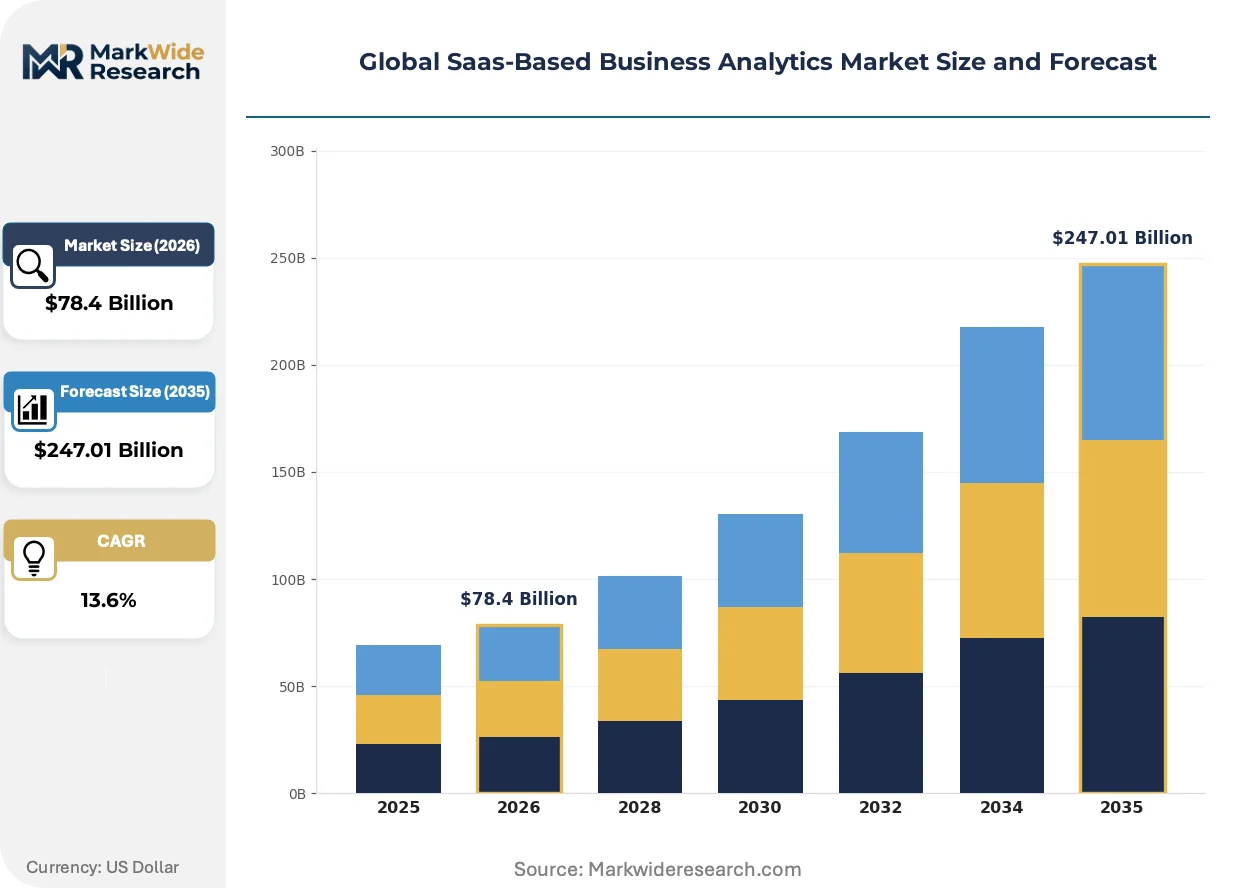
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Data Visualization, Predictive Analytics, Data Mining, Big Data Analytics, Performance Management Use Case: Customer Insights, Risk Management, Supply Chain Optimization, Financial Planning, Fraud Detection End User Industry: BFSI, Telecommunications, Manufacturing, Education, Energy |
| Companies Covered | Microsoft, Oracle, SAP, IBM, Salesforce, SAS Institute, Qlik, TIBCO Software, Tableau Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Saas-Based Business Analytics Market Shifts & Advancements
Real-time inference architectures are displacing batch-oriented analytical pipelines, compressing decision cycles from hours to seconds and redefing competitive table stakes for enterprise platforms.
Vector databases optimized for semantic search and recommendation engines are supplanting traditional relational stores for unstructured data workloads. E-commerce and media enterprises are deploying these systems at scale to power personalization pipelines. The structural consequence is a bifurcation in platform architecture, where general-purpose analytics vendors face pressure to acquire or build specialized retrieval infrastructure.
The EU AI Act's risk-tiered compliance framework is mandating human-in-the-loop oversight for high-stakes automated decisions in credit scoring and medical diagnostics. Vendors must now embed audit trails and explanation interfaces directly into product workflows. Financial services institutions in Germany and France are accelerating procurement of compliant platforms ahead of enforcement deadlines.
Subscription pricing tied to query volume is giving way to outcome-based contracts where fees scale with measurable business impact. Retail and logistics buyers are piloting these arrangements for demand forecasting and inventory optimization use cases. This shift is most advanced in North American enterprise accounts with mature data governance functions capable of isolating analytics-driven performance improvements.
Global Saas-Based Business Analytics Market Segmentation
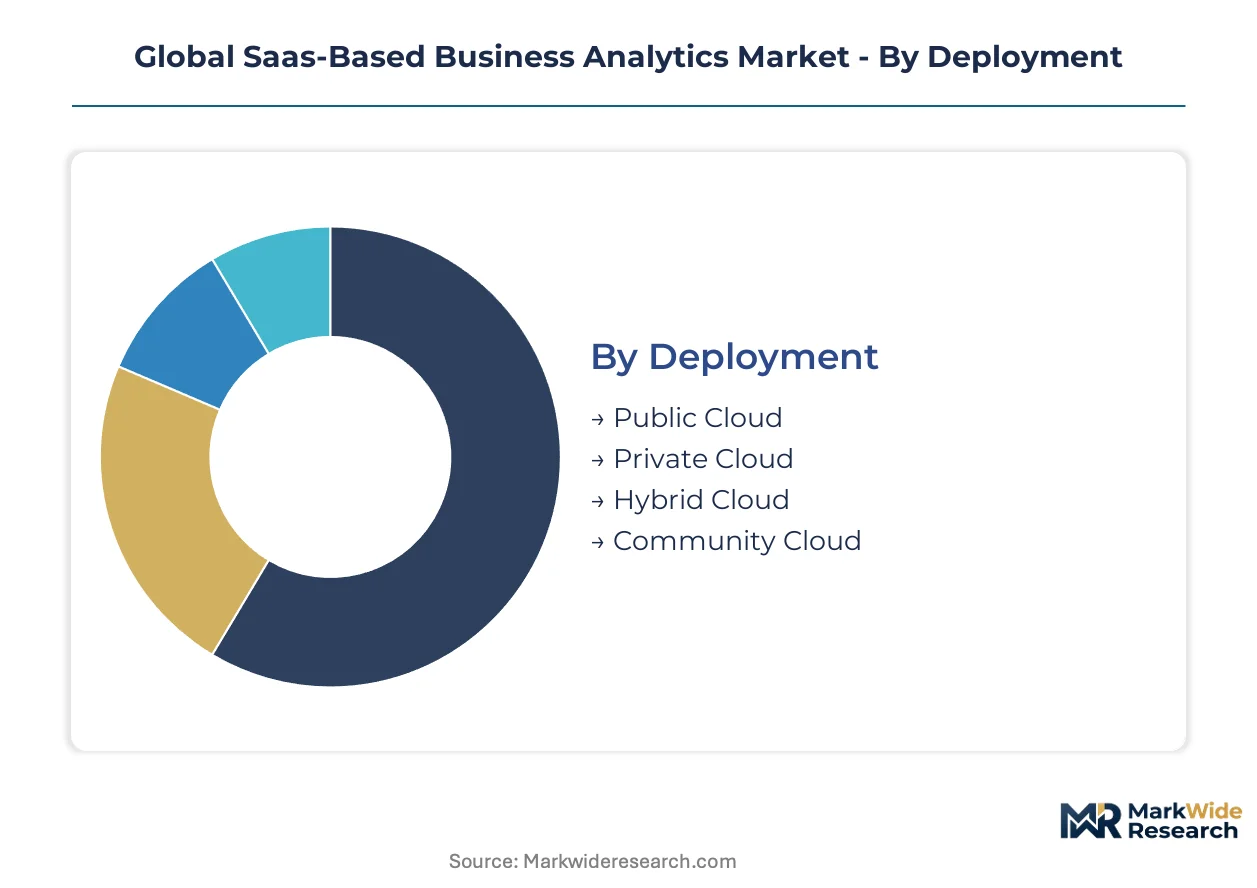
Segmentation reveals how SaaS analytics platforms fragment across technical architectures, functional modules, and operational use cases. Procurement patterns diverge sharply by deployment model and industry vertical, with compliance requirements and data sovereignty rules reshaping vendor selection criteria.
Deployment:
Public cloud deployments face mounting substitution pressure from hybrid configurations as regulated enterprises demand on-premise data residency without sacrificing elastic scaling economics.
- Public Cloud:Multi-tenant architectures deliver elastic compute and storage through shared infrastructure pools. Financial services firms in Singapore and retail enterprises in the United States concentrate demand here, driven by capital expenditure avoidance and rapid provisioning requirements.
- Private Cloud:Single-tenant dedicated environments isolate workloads on proprietary infrastructure stacks. German automotive manufacturers and Japanese pharmaceutical companies prioritize this model to satisfy regulatory audit requirements for sensitive operational data.
- Hybrid Cloud:Orchestrated workloads split between on-premise sovereignty zones and burst capacity in public pools. Indian IT services firms and Australian healthcare networks are expanding procurement of these configurations to navigate conflicting data localization mandates across operating jurisdictions.
- Community Cloud:Shared infrastructure restricted to defined industry consortia or regulatory peer groups. European banking federations and North American energy trading alliances deploy these to achieve cost pooling while maintaining sector-specific compliance postures.
Public Cloud retains volume leadership; Hybrid Cloud holds the steepest expansion curve.
Solution Type:
Cost tier differentiation separates commodity visualization tools from premium predictive engines, with procurement budgets stratifying by organizational data maturity and analytical ambition.
- Data Visualization:Dashboard and reporting interfaces rendering structured datasets into graphical formats for business consumption. Small and mid-sized enterprises across Brazil and South Korea standardize on these entry-level capabilities to democratize access without specialized data science staffing.
- Predictive Analytics:Machine learning pipelines generating forward-looking forecasts from historical pattern recognition. Telecommunications operators in Spain and logistics providers in the Netherlands embed these capabilities into network capacity planning and route optimization workflows.
- Data Mining:Algorithmic discovery of latent patterns within large unstructured repositories. Academic research institutions in Canada and market intelligence agencies in the United Kingdom sustain demand for exploratory analytical methods.
- Big Data Analytics:Distributed processing frameworks handling petabyte-scale ingestion and transformation. Streaming media platforms in Sweden and genomic research centers in Switzerland deploy these for real-time personalization and computational biology workloads.
- Performance Management:Integrated scorecarding and goal-tracking systems aligning operational metrics with strategic objectives. Professional services firms in France and public sector agencies in Italy utilize these for workforce productivity measurement and program accountability.
Data Visualization commands the widest installed base; Predictive Analytics is climbing the fastest as operational AI deployment accelerates.
Use Case:
Application maturity varies dramatically, with customer-facing intelligence commanding established budgets while supply chain optimization emerges as the priority investment for post-disruption resilience planning.
- Customer Insights:Behavioral segmentation and lifetime value modeling derived from transaction and interaction histories. E-commerce merchants in Mexico and subscription service providers in Norway concentrate spending here to reduce churn and improve conversion funnel efficiency.
- Risk Management:Quantitative exposure assessment and scenario simulation for operational and financial threats. Insurance underwriters in Bermuda and commodity traders in the United Arab Emirates depend on these capabilities for capital allocation and contract pricing decisions.
- Supply Chain Optimization:Demand forecasting, inventory positioning, and logistics coordination across distributed supplier networks. Electronics assemblers in Vietnam and food distributors in Poland are accelerating procurement to mitigate disruption vulnerability exposed by recent geopolitical shocks.
- Financial Planning:Budget variance analysis, rolling forecast consolidation, and profitability modeling. Corporate headquarters functions in Ireland and shared service centers in Malaysia standardize on these for group-level reporting and investor communication.
- Fraud Detection:Anomaly identification and pattern matching for transaction surveillance and identity verification. Payment processors in Nigeria and digital wallet operators in Indonesia deploy these to comply with anti-money laundering directives and reduce chargeback losses.
Customer Insights retains revenue concentration; Supply Chain Optimization is gaining share fastest as enterprises reconfigure operational footprints.
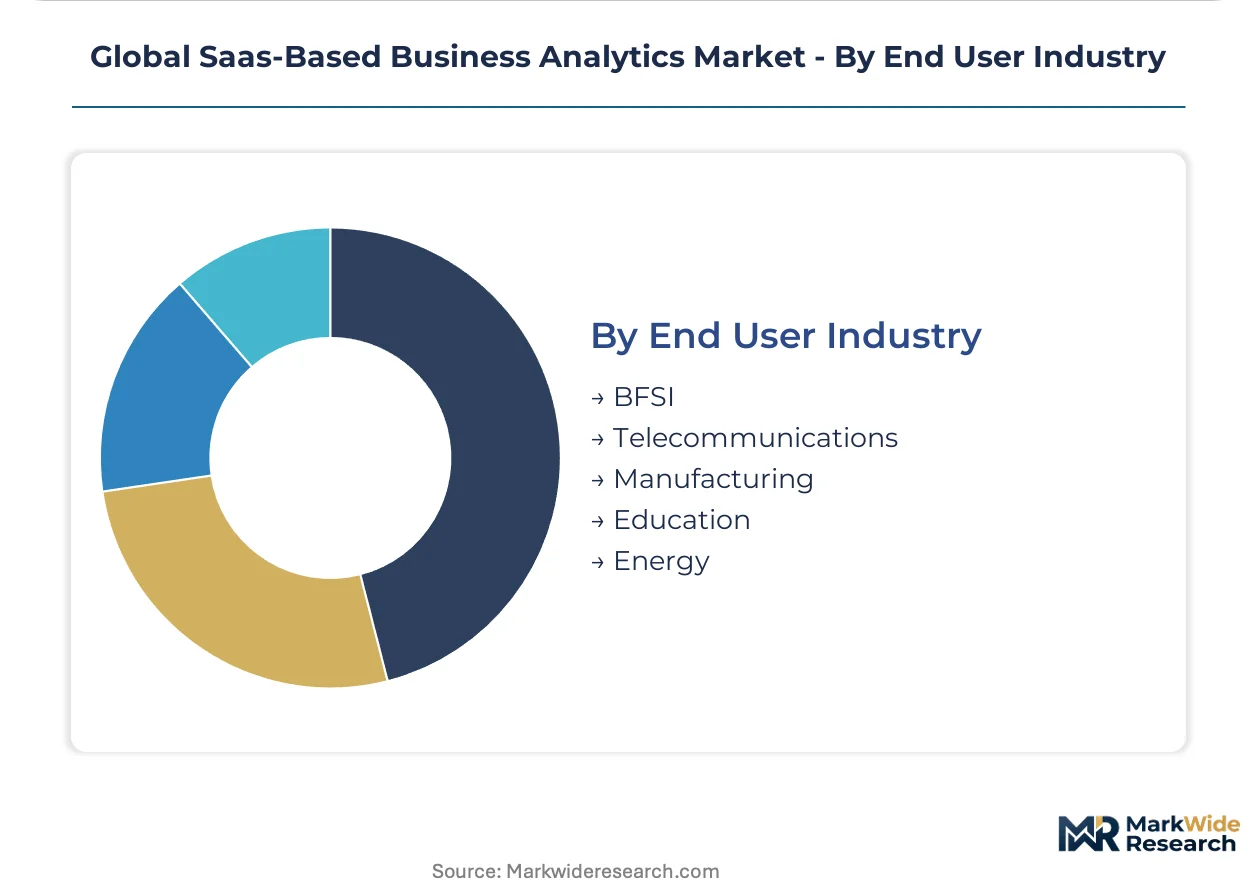
End User Industry:
Customer type segmentation shows BFSI and telecommunications as anchor demand pools, with manufacturing emerging as the most contested expansion frontier for platform vendors.
- BFSI:Banking, financial services, and insurance institutions requiring regulatory reporting, portfolio analytics, and algorithmic trading infrastructure. Asset managers in Luxembourg and retail banks in Thailand sustain substantial licensing volumes for compliance and competitive positioning.
- Telecommunications:Network operators analyzing subscriber behavior, optimizing infrastructure utilization, and predicting equipment failures. Mobile carriers in South Africa and fixed-line providers in Finland concentrate investment in churn prediction and capacity planning modules.
- Manufacturing:Industrial enterprises deploying quality control analytics, predictive maintenance, and demand-driven production scheduling. Precision engineering firms in Austria and chemical processors in Belgium are expanding deployments to capture Industry 4.0 productivity gains.
- Education:Universities and training organizations analyzing student progression, optimizing resource allocation, and personalizing learning pathways. Vocational institutes in Denmark and research universities in New Zealand utilize these for enrollment management and grant performance tracking.
- Energy:Utilities and oil and gas producers monitoring grid stability, optimizing extraction economics, and managing trading positions. Renewable portfolio operators in Chile and integrated majors in Saudi Arabia deploy analytics for generation forecasting and commodity risk management.
BFSI retains volume leadership; Manufacturing holds the steepest expansion curve as operational technology convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in the United States concentrate the highest absolute spending on SaaS analytics platforms, while Germany and India emerge as the fastest-growing demand poles driven by regulatory compliance mandates and IT services expansion respectively.
United States
Fortune 500 headquarters and federal contractors anchor platform demand, with NIST cybersecurity framework alignment shaping vendor selection criteria for defense and healthcare sectors. The SEC's climate disclosure rules are forcing listed enterprises to upgrade ESG analytics capabilities ahead of reporting deadlines. Seattle and San Francisco Bay Area technology clusters concentrate vendor engineering talent and enterprise sales operations.
Germany
Automotive manufacturers and industrial machinery producers drive operational analytics adoption for Industry 4.0 transformation programs. The EU AI Act's risk-tiered compliance framework mandates human-in-the-loop oversight for automated quality control decisions. Stuttgart and Munich engineering clusters host the densest concentrations of predictive maintenance deployments and ERP-native analytics integration.
India
Domestic IT services firms in Bengaluru and Hyderabad are building captive analytics delivery centers, pulling platform licensing demand from Western enterprises seeking cost arbitrage. The Digital Personal Data Protection Act imposes data localization obligations that force redundant infrastructure deployment across Mumbai and Delhi-NCR facilities. Domestic fintech operators in these metros are accelerating procurement of fraud detection and customer insights modules.
United Kingdom
Financial services institutions in London and Edinburgh are prioritizing algorithmic transparency tools ahead of EU AI Act enforcement deadlines affecting cross-border operations. The Financial Conduct Authority's operational resilience requirements are extending analytics procurement into business continuity planning functions. London's insurance market and Edinburgh's asset management cluster sustain concentrated demand for risk management and portfolio analytics.
Singapore
Wealth management firms and commodity trading houses deploy multi-tenant platforms for real-time portfolio surveillance and regulatory reporting. The Monetary Authority of Singapore's technology risk management guidelines mandate verified information security management systems for financial institution vendors. The Marina Bay financial district and one-north technology corridor concentrate regional headquarters procurement decisions for Southeast Asian operations.
Global Saas-Based Business Analytics Market Competitive Landscape
Player mix skews toward cloud-native specialists and legacy ERP incumbents with substantial installed bases. Market structure exhibits tiered concentration, with three to five platforms capturing majority share in Fortune 500 accounts while mid-tier challengers compete on vertical specialization and regional price positioning. Dominant strategic archetypes include hyperscale cloud providers leveraging infrastructure integration, enterprise software incumbents embedding analytics into operational workflows, and independent visualization specialists defending position through user experience differentiation. Competitive moves center on M&A activity targeting vector database and MLOps capabilities, alongside strategic partnerships bridging hybrid cloud deployment gaps.
Within the hyperscale infrastructure tier, Microsoft and Oracle occupy positions defined by cloud backbone integration and database-native architecture respectively. SAP exemplifies the ERP-embedded archetype through deep operational workflow integration. Salesforce sits within the CRM-native intelligence segment, extending predictive revenue operations capabilities. Among independent specialists, SAS Institute and Qlik represent contrasting approaches to statistical computing and associative analytics engines. Tableau Software anchors the self-service visualization category, while TIBCO Software occupies event-streaming and real-time inference positioning. IBM spans multiple archetypes through hybrid cloud and AI platform bundling.
| Leading Market Players |
|---|
| Microsoft |
| Oracle |
| SAP |
| IBM |
| Salesforce |
| SAS Institute |
| Qlik |
| TIBCO Software |
| Tableau Software |
| Others |
Supply & Pricing Matrix
Vector database substitution for traditional relational stores is redrawing procurement geography toward specialized retrieval infrastructure vendors, simultaneously fragmenting platform pricing power and compressing margins on general-purpose analytics tiers.
Pricing Analysis
Cost-plus contracts with CPI indexation govern enterprise licensing arrangements for hybrid cloud deployments, though outcome-based fee structures are displacing query-volume subscriptions in North American accounts with mature data governance functions. Price differentiation rests on ISO/IEC 27001 certification tier and integration complexity with legacy ERP systems. Cost compression in the mid-market visualization tier is intensifying because cloud-native challengers are undercutting incumbent per-seat rates. Small and mid-sized enterprises in Brazil and South Korea exhibit the highest price sensitivity, while Fortune 500 procurement teams in the United States prioritize compliance posture over license cost.
Supply Chain Analysis
Submarine cable chokepoints across the Strait of Malacca and Red Sea corridor tether latency-sensitive inference workloads to regional cloud availability zones, constraining vendor architecture decisions. Engineering talent concentrates in the United States, India, and Germany, with Bengaluru and Hyderabad delivery centers drawing platform licensing demand through IT services arbitrage. Raw material dependencies span specialized silicon for edge inference accelerators, enterprise-grade storage arrays, and optical networking equipment. Single-source vulnerability in Taiwan-based semiconductor fabrication threatens hardware refresh cycles for on-premise sovereignty deployments. Distribution runs through direct enterprise sales teams for Fortune 500 accounts and systems integrator channels for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed MLOps services represent a service-attach opportunity expanding faster than core platform subscriptions, as talent scarcity extends implementation timelines and inflates professional services demand.
For Market Incumbents: Compound switching costs through deeper ERP-native integration that embeds analytics into SAP and Oracle operational workflows, defending against cloud-native challengers. Prioritize ISO/IEC 27001 certification maintenance to retain Fortune 500 procurement eligibility as enterprise security mandates tighten. Capacity addition in Indian captive delivery centers captures cost arbitrage demand from Western enterprises.
For New Entrants and Emerging Players: ISO/IEC 27001 fast-track certification unlocks mid-market manufacturing accounts in Austria and Belgium where operational technology convergence is accelerating but incumbent penetration remains shallow. Target supply chain optimization use cases in Vietnamese electronics assemblers and Polish food distributors, segments gaining share fastest post-geopolitical disruption. Lead with API-first architectures that reduce integration friction against legacy data warehouse estates.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vector database and MLOps capability acquisitions over horizontal platform rollup. Long-term viability hinges on recurring revenue attach rates rather than perpetual license conversion. Watch EU AI Act enforcement velocity in German automotive and French financial services as the inflection indicator for compliance-tooling demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Vector database capabilities address semantic search workloads displacing relational stores in e-commerce personalization pipelines. |
| Strategic Partnership | Hybrid cloud deployment bridges address data sovereignty requirements from India's Digital Personal Data Protection Act. |
| Platform Integration | Deep ERP embedding into SAP operational workflows creates switching costs in manufacturing and supply chain verticals. |
| Geographic Expansion | Indian captive delivery centers in Bengaluru and Hyderabad capture Western enterprise cost arbitrage demand. |
| Product Launch | Explainability-layer upgrades satisfy EU AI Act human-in-the-loop mandates for German automotive quality control decisions. |
Research Methodology
A spread of perspectives from enterprise CTOs, IT procurement officers, platform engineers, and systems integrator partners converged on the working assumptions underlying demand forecasts. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie mobile analytics data, and enterprise software vendor 10-K segment reporting. Bottom-up account-level sizing and top-down market-level triangulation cross-checked volume and value estimates across the analysis window.
Segmentation dimensions modeled span deployment architecture, solution type, functional use case, and end-user industry vertical, with regional adoption patterns and integration complexity tiers as cross-cutting variables. CAGRs were derived from fitted growth curves applied to base-year estimates, with sensitivity testing around cloud migration velocity and regulatory enforcement timelines. Forecast inputs incorporated EU AI Act compliance cost assumptions, India IT services expansion trajectories, and edge inference hardware refresh cycles.
Decision-makers should treat outputs as directional under assumptions of steady regulatory enforcement and sustained cloud migration momentum; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as MLOps talent availability and cross-border data localization rule evolution reshape implementation economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Italy Geospatial Analytics Market
Analytics
Europe Big Data and Business Analytics Market
Analytics
Global Customer Analytics Market
Analytics
Human Resource Analytics Market
Analytics
Network Analytics Services Market
Analytics
Behavior Analytics Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
Digital Analytics Solutions Market
Analytics
Global Data Fusion Market
Analytics
Japan Geospatial Analytics Market
Analytics
Weather Data Services Market
Analytics
Global Data Analysis Software Market
Analytics
India Big Data Technology and Service Market
Analytics
Global Mobile BI Market
Analytics
Embedded Analytics Market
Analytics
FMCG Spending on Analytics Market