
 Extract, Transform, Load (ETL) Market | 2026-2036
Extract, Transform, Load (ETL) Market Size, Share, and Industry Trends Forecast 2026-2036
Extract, Transform, Load (ETL) Market Analysis
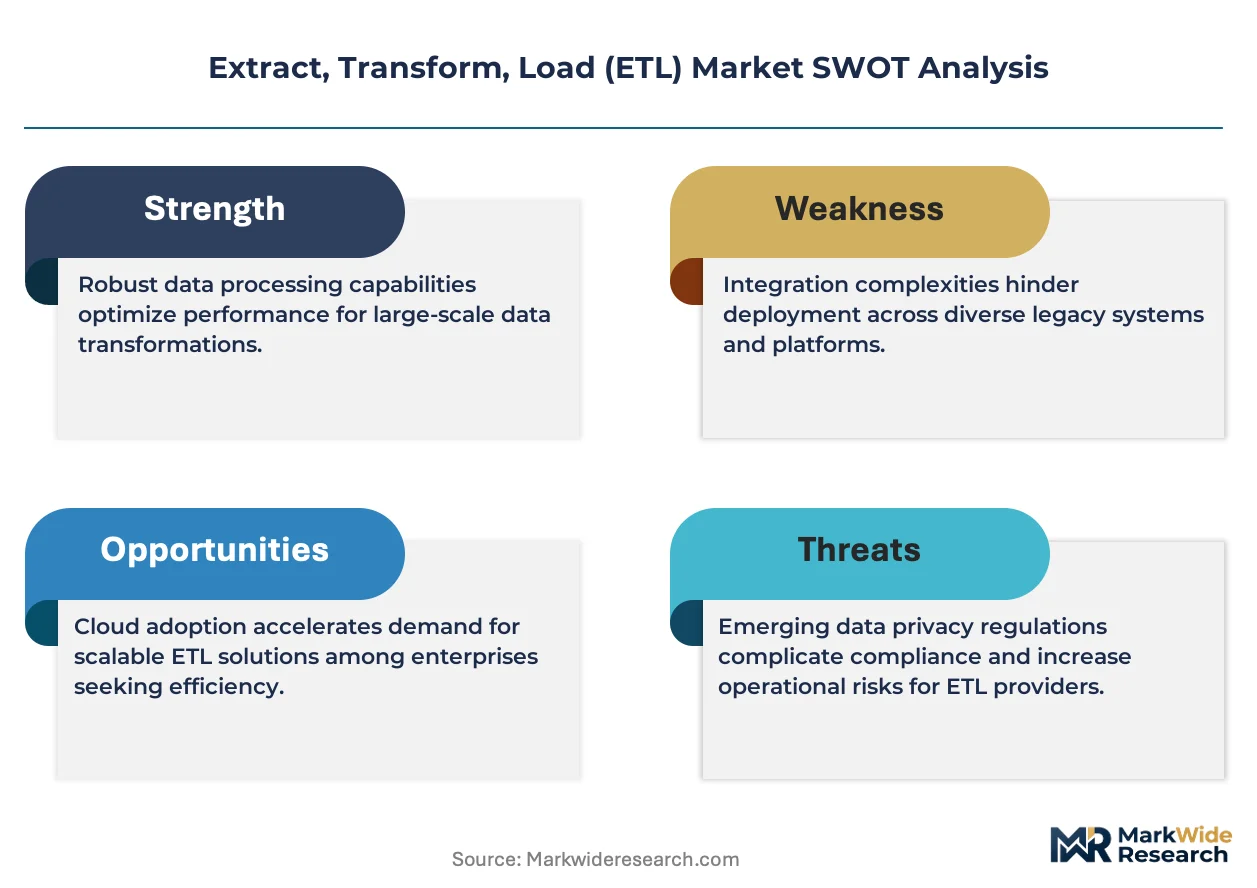
The monolithic ETL architecture is fragmenting into modular, API-first data pipeline components that vendors assemble through cloud-native orchestration. Informatica anchors enterprise-grade data governance through its Intelligent Data Management Cloud, sustaining long-term relationships with regulated industries. Fivetran competes on connector breadth, automating schema drift handling across hundreds of SaaS sources without engineering intervention.
Extract, Transform, Load denotes a three-stage data integration process wherein raw data is extracted from heterogeneous sources, cleansed and normalized through transformation rules, and loaded into target repositories for analytics or operational use. Batch Processing remains the revenue backbone for legacy warehouse refresh cycles, yet Real-Time Processing captures the fastest expansion as event-driven architectures displace overnight ETL windows. Cloud-Based deployment absorbs the majority of new customer acquisitions, while Hybrid configurations persist among organizations with sovereign data residency requirements.
GDPR in Europe and HIPAA in the United States impose strict lineage and encryption standards that elevate demand for audit-ready transformation logs. ISO 27001 certification functions as a baseline qualifier for vendor shortlists in financial services and healthcare procurement. Stakeholders must evaluate whether their pipeline architectures can absorb emerging AI governance requirements without rebuilding core transformation engines.
Market Dynamics
The ETL market is fragmenting as batch-centric architectures yield to streaming-first pipelines, forcing vendors to rebuild transformation engines around event-driven microservices rather than monolithic overnight workflows.
Growth Catalysts
- HIPAA audit mandates:Healthcare providers in the United States must maintain immutable lineage logs for patient data transformations, driving procurement of governance-integrated ETL platforms.
- Real-time fraud detection:Financial services firms deploy streaming ETL to feed machine learning models with sub-second transaction feeds, compressing detection windows from hours to milliseconds.
- API-first SaaS proliferation:The explosion of cloud applications with standardized REST endpoints creates connector demand that automated ETL services capture without engineering overhead.
Market Restraints
- Specialized talent scarcity:Data engineers with Spark, Kafka, and cloud-native orchestration expertise command premium compensation, inflating total cost of ownership for complex pipeline deployments.
- Hyperscaler concentration:AWS, Azure, and Google Cloud control the underlying compute substrate, exposing ETL vendors to pricing power asymmetry and service dependency risk.
- Schema drift complexity:Source systems modify data structures without notice, breaking transformation logic and requiring continuous engineering intervention to maintain pipeline stability.
Strategic Opportunities
- Edge computing integration:Manufacturing and logistics operators in Germany and Japan require ETL processing at plant-floor gateways, creating demand for lightweight, containerized transformation agents.
- EU AI Act compliance:Automated documentation of training data provenance becomes mandatory for high-risk AI systems, positioning lineage-capable ETL vendors as essential infrastructure providers.
- Data mesh architectures:Domain-oriented ownership models distribute transformation responsibility, opening markets for federated governance tools that interoperate across decentralized pipeline instances.
Industry Challenges
- Legacy warehouse entrenchment:Decades of stored procedures and proprietary SQL dialects in on-premise Teradata and Oracle installations resist migration to cloud-native equivalents without massive rewrite investments.
- Cross-functional coordination friction:Data platform teams, security officers, and business analysts maintain conflicting priorities for pipeline design, delaying production deployments and eroding stakeholder confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extract, Transform, Load (ETL) Market |
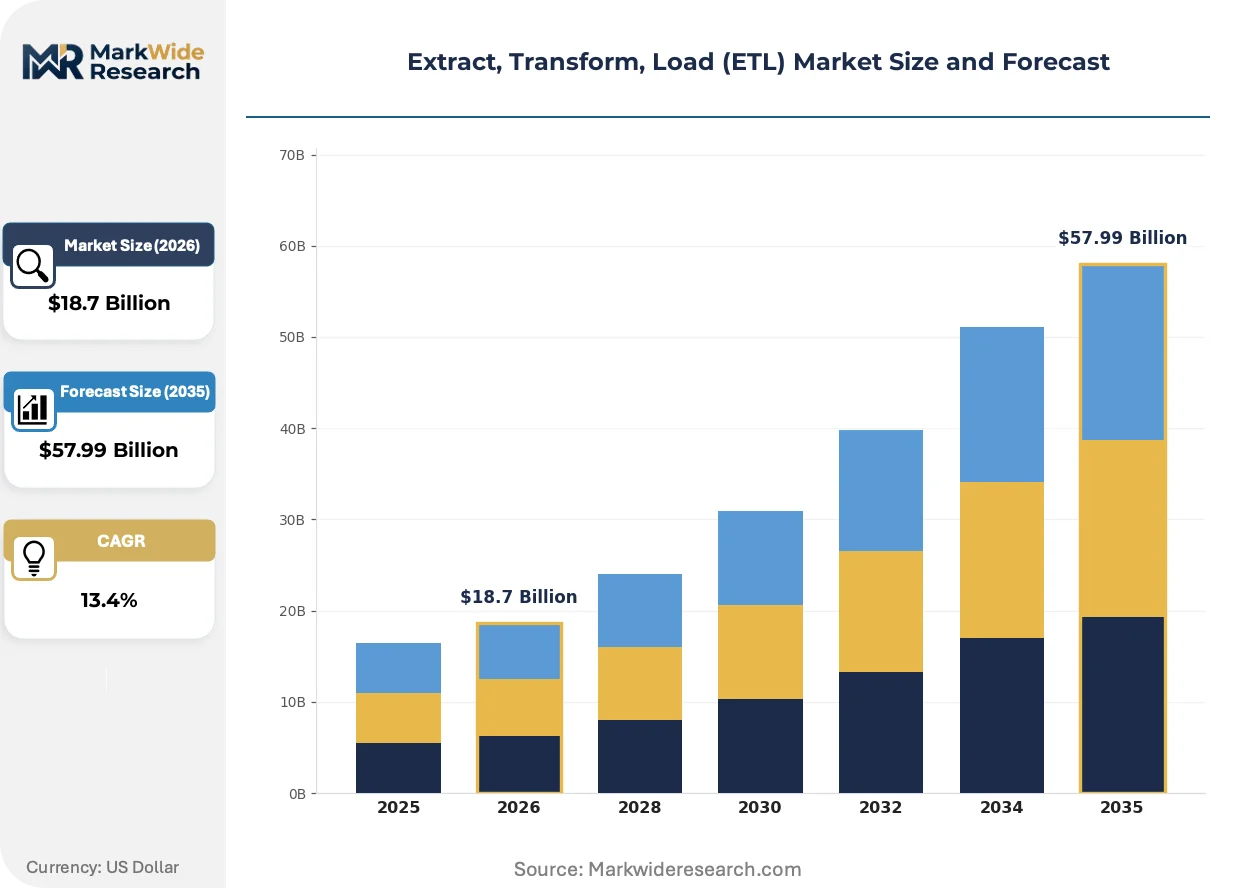
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Technology: Batch Processing, Real-Time Processing, Change Data Capture, Data Streaming End User: Financial Services, Retail, Healthcare, Telecommunications Integration Level: API Integrations, Custom Integrations, Pre-Built Connectors, Workflow Automation |
| Companies Covered | Azure Data Factory, Matillion, Fivetran, Estuary, Airbyte, Informatica, Talend, Google Cloud Data Fusion, AWS Glue, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extract, Transform, Load (ETL) Market Emerging Trajectories
Pipeline architectures are shedding monolithic constraints as engineering teams adopt composable, API-driven components that cloud orchestration layers assemble into domain-specific workflows.
Stream processing engines such as Apache Flink and Kafka Streams handle continuous data flows with exactly-once semantics, enabling financial services firms to operationalize real-time risk scoring without batch window latency. Capital markets desks in London and Singapore now demand sub-100-millisecond ingestion-to-insight pipelines, and ETL infrastructure is migrating from overnight refresh cycles to always-on stream consumption that never pauses for scheduled maintenance windows.
GDPR's Article 30 documentation requirements and the EU AI Act's training data transparency mandates compel vendors to embed automated lineage capture at every transformation node. Healthcare and banking procurement teams in France and Germany now disqualify solutions lacking immutable audit trails, forcing product roadmaps to prioritize governance over raw throughput.
Platform engineering teams increasingly self-serve pipeline construction through internal developer portals rather than ticketing data engineering queues. Retail and media companies in the United States deploy pre-approved connector libraries and transformation templates that domain teams compose without central team bottlenecks, compressing time-to-production from weeks to hours while distributing operational responsibility across business units.
Extract, Transform, Load (ETL) Market Segmentation
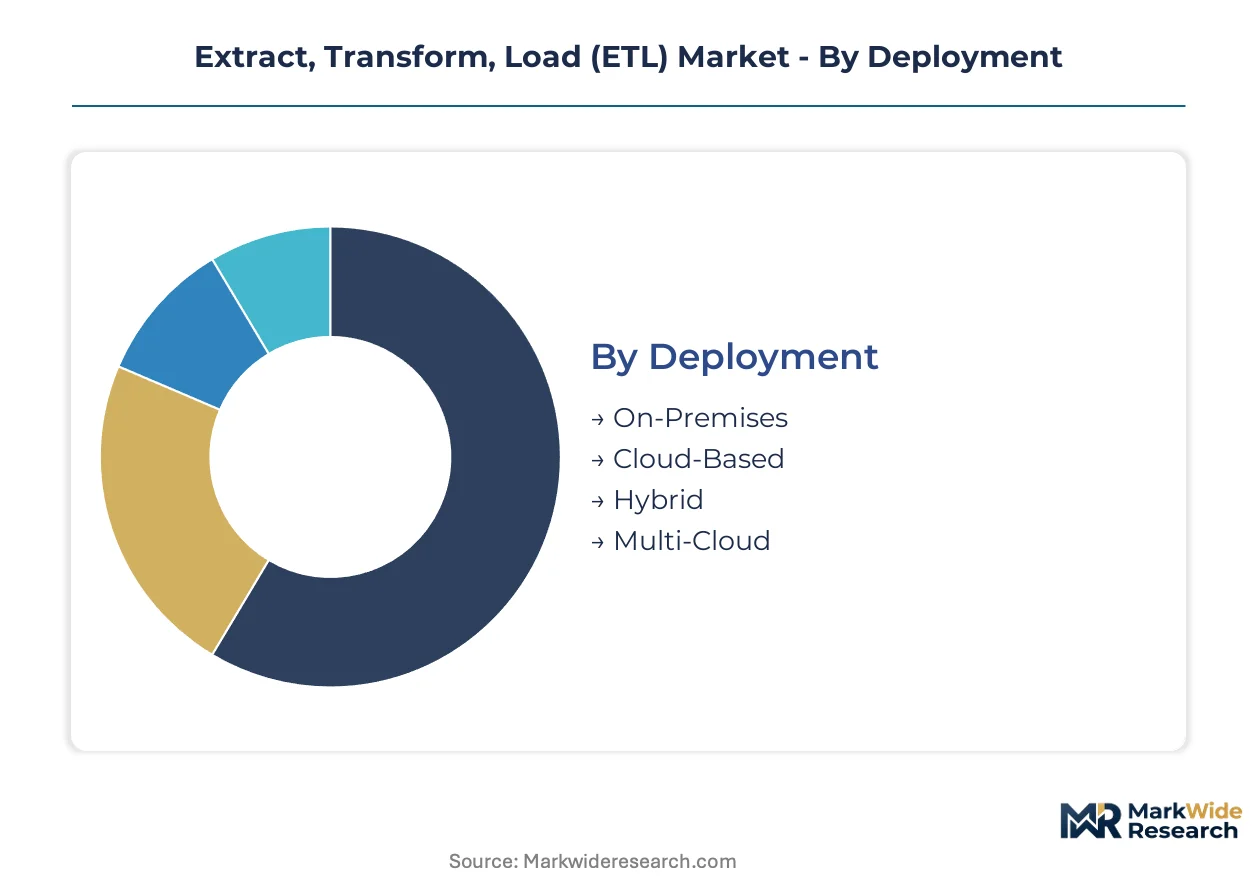
ETL procurement cycles vary dramatically across deployment modes and technology architectures, with cloud-native solutions refreshing quarterly while on-premises installations persist for years. Understanding these velocity differentials helps vendors align product roadmaps with customer replacement timelines and expansion budgets.
Deployment:
Cloud-based deployments compress sales cycles to weeks, while on-premises engagements stretch across quarters of security review and infrastructure provisioning.
- On-Premises:Hardware-resident transformation engines running within customer data centers, requiring dedicated server clusters and network isolation. Regulated banks in Switzerland and Saudi Arabia mandate on-premises deployments for sovereign data control, extending procurement timelines but securing multi-year contracts with premium support tiers.
- Cloud-Based:Fully managed SaaS pipelines leveraging hyperscaler compute without customer infrastructure ownership. Financial services firms in the United States dominate procurement, drawn by consumption-based pricing and automatic scaling during quarter-end reporting surges.
- Hybrid:Split architectures processing sensitive data on-premises while bursting transformation workloads to cloud during peak demand. German automotive suppliers favor this model to satisfy KBA data residency requirements while accessing elastic compute for supply chain analytics.
- Multi-Cloud:Orchestration layers abstracting AWS, Azure, and Google Cloud into unified pipeline fabrics. Large enterprises in Singapore and the Netherlands deploy multi-cloud strategies to avoid vendor lock-in and negotiate pricing leverage across providers.
On-Premises anchors the volume base while Cloud-Based gains share at the steepest rate.
Technology:
Cost structures stratify sharply between legacy batch infrastructure and streaming-first architectures requiring specialized engineering talent.
- Batch Processing:Scheduled ETL windows processing data in discrete chunks during off-peak hours. Overnight refresh cycles persist in retail inventory systems and monthly financial closes where latency tolerance spans hours.
- Real-Time Processing:Continuous data flows with sub-second transformation latency, operationalized through Apache Flink and Kafka Streams. Capital markets desks in London demand sub-100-millisecond ingestion for algorithmic trading risk models.
- Change Data Capture:Database log mining techniques that propagate incremental updates without full table scans. Healthcare providers in the United States deploy CDC to synchronize patient records across HIPAA-compliant environments with minimal network overhead.
- Data Streaming:Event-driven architectures consuming unbounded data sequences from IoT sensors and application logs. Manufacturing operators in Japan stream telemetry from METI-connected smart factories into predictive maintenance pipelines.
Batch Processing retains the largest installed base though Real-Time Processing climbs fastest as event-driven architectures displace overnight workflows.
End User:
Customer sophistication spans from template-driven retail deployments to bespoke healthcare integrations requiring extensive compliance engineering.
- Financial Services:Trading floors and risk departments demanding millisecond-latency pipelines with immutable audit trails. SEC-registered broker-dealers in New York and Chicago prioritize lineage documentation for regulatory examination readiness.
- Retail:Omnichannel merchants consolidating web, store, and marketplace data into unified customer views. Seasonal demand spikes around Black Friday and holiday periods drive elastic cloud procurement patterns.
- Healthcare:Hospital systems and payers integrating electronic health records with claims processing platforms. HIPAA audit mandates in the United States require transformation logs demonstrating patient data provenance across every pipeline stage.
- Telecommunications:Network operators processing call detail records and subscriber analytics at petabyte scale. 5G rollout investments in South Korea and Germany expand real-time streaming requirements for network optimization.
Financial Services commands the highest average contract values while Healthcare expands most quickly under regulatory pressure for data governance.
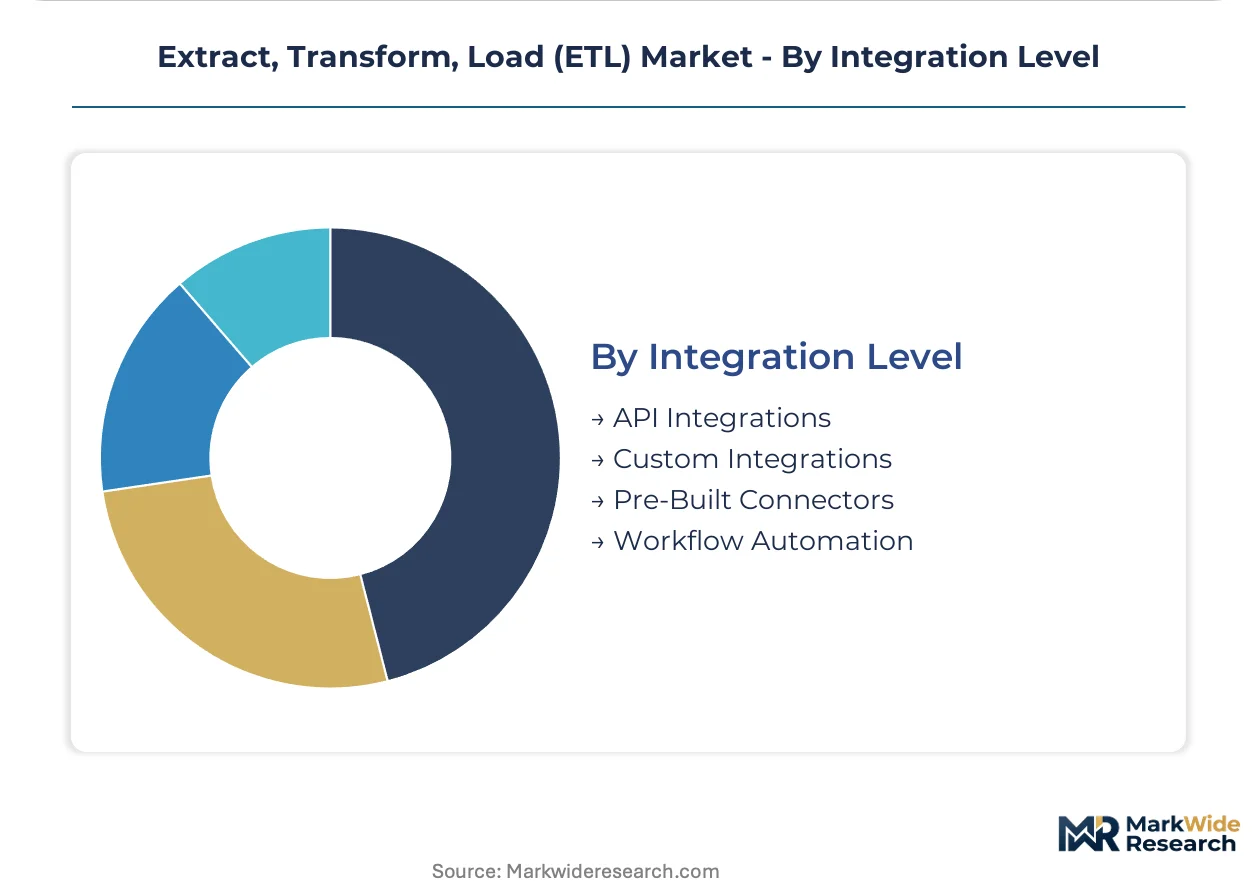
Integration Level:
Volume concentration sits with pre-built connector libraries, while margin accrues to custom integration services addressing edge cases.
- API Integrations:REST and GraphQL endpoint connections enabling programmatic data exchange between cloud applications. SaaS vendors in the United States standardize on OpenAPI specifications, reducing connector development friction.
- Custom Integrations:Bespoke pipeline engineering for proprietary systems lacking standardized interfaces. Legacy mainframe environments in insurance and banking require specialized COBOL parsing and EBCDIC conversion layers.
- Pre-Built Connectors:Vendor-maintained adapters for common enterprise applications spanning Salesforce, SAP, and Workday. Mid-market companies self-serve deployment without engineering teams, compressing time-to-value to days.
- Workflow Automation:Visual orchestration tools enabling business analysts to construct pipelines through drag-and-drop interfaces. Marketing operations teams in media companies automate campaign data flows without ticketing central data engineering queues.
Pre-Built Connectors dominate new customer acquisition volumes while Custom Integrations capture premium pricing for complex legacy modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based ETL vendors export cloud-native pipeline infrastructure to financial services buyers in London, Singapore, and Frankfurt, while German automotive suppliers and Japanese manufacturers import edge-computing transformation agents for plant-floor deployment.
United States
Fortune 500 data engineering teams in New York and Chicago drive hyperscaler marketplace procurement for real-time fraud detection pipelines. SEC examination readiness mandates immutable lineage documentation for broker-dealer transformation logs. Capital markets desks in Manhattan deploy sub-100-millisecond streaming ETL for algorithmic trading risk models.
Germany
Automotive suppliers in Stuttgart and Munich require KBA-compliant hybrid architectures splitting sensitive supply chain data on-premises while bursting analytics workloads to cloud. EU AI Act training data provenance rules position lineage-capable vendors as essential infrastructure. Industrial clusters in Bavaria integrate lightweight containerized agents at METI-connected smart factory gateways.
United Kingdom
Capital markets desks in the City of London demand always-on stream consumption without scheduled maintenance windows for risk scoring pipelines. GDPR Article 30 documentation requirements compel automated lineage capture at every transformation node. Fintech clusters in Canary Wharf operationalize event-driven microservices displacing overnight batch workflows.
Japan
Manufacturing operators in Nagoya and Osaka stream telemetry from plant-floor sensors into predictive maintenance pipelines requiring edge-computing transformation. METI-connected smart factories create demand for lightweight containerized agents processing data at gateway level. Automotive suppliers in Toyota City favor hybrid models satisfying data residency requirements while accessing elastic compute.
Singapore
Multi-cloud orchestration layers abstracting AWS, Azure, and Google Cloud attract large enterprises avoiding vendor lock-in across ASEAN financial hubs. MAS regulatory scrutiny elevates demand for audit-ready transformation logs in wealth management data pipelines. Trading infrastructure in Raffles Place compresses ingestion-to-insight latency for cross-border currency arbitrage strategies.
Extract, Transform, Load (ETL) Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: hyperscaler-native services, independent cloud-native specialists, and legacy enterprise platforms modernizing through SaaS transitions. Hyperscalers leverage compute substrate control to bundle ETL with broader cloud contracts. Independent vendors compete on connector breadth and schema automation. Legacy incumbents anchor regulated industries through governance-integrated platforms. Dominant competitive moves include API-first architectural pivots and strategic partnerships with SaaS application vendors to secure connector distribution.
Among cloud-native specialists, Fivetran and Airbyte exemplify the automated connector archetype, while Informatica occupies a position bridging legacy enterprise data governance with modern cloud orchestration. These three anchors span the competitive spectrum from zero-engineering SaaS ingestion to regulated-industry transformation platforms, representing how vendor positioning stratifies between self-serve automation and compliance-heavy enterprise procurement.
| Leading Market Players |
|---|
| Azure Data Factory |
| Matillion |
| Fivetran |
| Estuary |
| Airbyte |
| Informatica |
| Talend |
| Google Cloud Data Fusion |
| AWS Glue |
| Others |
Supply Flow & Price Mechanics
Hyperscaler compute concentration in the United States determines both pricing tier spreads and supply chain shape, as AWS, Azure, and Google Cloud pricing power compresses margins for independent ETL vendors while forcing architectural dependencies on cloud-native orchestration layers.
Pricing Analysis
The technology-generation pricing gap between legacy batch infrastructure, current streaming-first platforms, and emerging edge-computing agents structures commercial negotiations across the ETL market. Three-tier pricing stratifies across premium governance-integrated suites, standard SaaS connector libraries, and economy self-service tiers, with ISO 27001 certification and HIPAA audit readiness commanding substantial premiums in financial services and healthcare procurement. Cost compression in the economy tier intensifies as open-source alternatives commoditize basic data movement, while capital markets desks in New York demonstrate the least price sensitivity due to millisecond-latency requirements that justify premium expenditure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for hardware-dependent edge-computing deployments, particularly affecting German automotive suppliers and Japanese manufacturing operators sourcing gateway processors. Component dependencies rest on Intel and AMD server processors, NVIDIA GPU accelerators for ML-integrated transformations, and specialized network interface cards for sub-millisecond streaming. Distribution runs through hyperscaler marketplaces and direct SaaS procurement channels, with systems integrators capturing value in regulated industries requiring compliance engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment modes, processing architectures, and governance requirements creates specialist niches as domain-oriented data mesh models distribute transformation responsibility away from centralized platform teams.
For Market Incumbents: Pre-empt connector commoditization by embedding automated lineage capture and AI governance documentation into core transformation engines before EU AI Act mandates harden procurement requirements. Acquire specialized CDC vendors to close gaps in incremental data propagation for legacy mainframe environments, securing multi-year contracts with insurance and banking customers facing COBOL modernization pressure. For New Entrants and Emerging Players: Establish a beachhead in edge-computing transformation agents for METI-connected smart factories in Japan and KBA-regulated automotive suppliers in Germany, where lightweight containerized deployments address plant-floor latency requirements underserved by centralized cloud pipelines. Target healthcare payers in the United States with HIPAA-native SaaS offerings that automate audit trail generation without engineering intervention, competing on time-to-compliance rather than raw throughput. For Investors and Strategic Acquirers: The EU AI Act's training data provenance mandates reshape the acquisition landscape toward lineage-capable vendors with immutable audit infrastructure. Position portfolios for five-to-ten-year holding periods by targeting mid-scale platforms bridging self-serve automation and regulated-industry governance, with MAS regulatory scrutiny in Singapore and SEC examination readiness in the United States serving as signal indicators for procurement priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Connector Library Expansion | Breadth across SaaS sources reduces customer engineering overhead and accelerates procurement decisions. |
| Automated Lineage Embedding | GDPR Article 30 and EU AI Act compliance positions vendors as essential infrastructure for high-risk AI systems. |
| Edge Computing Agent Development | Lightweight containerized processing at plant-floor gateways addresses METI-connected smart factory requirements in Japan. |
| Data Mesh Architecture Support | Federated governance tools interoperate across decentralized pipeline instances as domain ownership models proliferate. |
| Real-Time Streaming Engine Integration | Sub-100-millisecond ingestion capabilities capture capital markets procurement in London and Singapore trading hubs. |
Methodological Framework
The analysis maps cloud-native orchestration, hybrid deployment configurations, and edge-computing transformation agents, each validated through platform engineering leads, data engineering directors, and healthcare compliance officers across primary interviews combined with secondary validation from hyperscaler capex disclosures, SEC filings, and regulatory submission databases. Bottom-up and top-down triangulation reconciles vendor-reported deployment metrics with end-user procurement patterns.
Assumptions around hyperscaler pricing trajectories, regulatory enforcement timelines, and streaming technology adoption curves were held fixed while varying enterprise cloud migration velocity and AI governance implementation pace across the projection horizon. Segmentation dimensions modeled include deployment mode, processing architecture, end-user vertical, integration complexity, and regional regulatory cluster, with CAGRs derived from fitted growth curves against historical replacement cycle data and cloud marketplace transaction velocity.
Stress conditions across hyperscaler pricing power asymmetry, schema drift incident frequency, and specialized talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates, with continuous validation against operating reality the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Global Data Fusion Market
Analytics
Geospatial Analytics Market
Analytics
North America Location Analytics Market
Analytics
Canada Contact Center Analytics Market
Analytics
Contact Center Analytics Market
Analytics
UAE Geospatial Analytics Market
Analytics
Europe Mobile Analytics Market
Analytics
Global Retail Analytics Software and Services Market
Analytics
Global Big Data Market
Analytics
Manufacturing Predictive Analytics Market
Analytics
IT Operation Analytics (ITOA) Market
Analytics
North America Operational Intelligence Market
Analytics
Japan Geospatial Analytics Market
Analytics
Germany Geospatial Analytics Market