
 Japan Rechargeable Battery Market | 2026-2036
Japan Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Rechargeable Battery Market Insights
The EU-Japan Green Alliance framework is hardening sustainability benchmarks for battery supply chains serving Japanese automotive OEMs. Panasonic Holdings Corporation leverages its vertical integration from cathode materials to finished cells, sustaining cost advantages in cylindrical formats for EV platforms. GS Yuasa Corporation anchors the domestic market for industrial and backup power applications, while LG Energy Solution competes aggressively through its joint manufacturing presence with Japanese partners.
Japan rechargeable batteries are electrochemical storage devices employing lithium-ion, nickel-metal hydride, or solid-state chemistries with nominal voltages ranging from 3.2V to 3.7V and cycle lives exceeding 2,000 charge-discharge repetitions, designed to convert and store electrical energy for repeated use across mobility, grid, and portable applications. Lithium-ion chemistries dominate value capture due to their energy density advantage in electric vehicles and consumer electronics, while solid-state technology represents the fastest-growing development trajectory as Japanese manufacturers race toward commercialization of sulfide-electrolyte architectures. Nickel-metal hydride retains stable demand in hybrid vehicle applications where Toyota and Honda maintain substantial installed bases, though margin pools increasingly shift toward lithium polymer formats in premium consumer devices.
METI enforces domestic content requirements and recycling quotas under the Act on Promotion of Resource Circulation for Batteries, while JIS standards govern cell safety testing protocols and performance verification. These frameworks compel manufacturers to localize supply chains and invest in closed-loop material recovery infrastructure. PMDA oversight intersects where medical device applications require specialized battery certifications. Stakeholders must monitor METI's forthcoming critical mineral stockpiling mandates and solid-state commercialization timelines to align capacity planning with regulatory thresholds.
Market Dynamics
METI's domestic content mandates under the Act on Promotion of Resource Circulation for Batteries are forcing manufacturers to reconfigure supply chains around localized cathode production and closed-loop recycling infrastructure.
Growth Catalysts
- EV platform expansion:Japanese automotive OEMs are accelerating cylindrical cell procurement for next-generation electric vehicle architectures, pulling capacity investments toward high-nickel cathode formats.
- METI stockpiling mandates:Critical mineral reserve requirements are stimulating domestic lithium and cobalt processing capacity, reducing import dependency for battery-grade materials.
- Osaka-Kobe industrial cluster:Concentrated materials science R&D and pilot production facilities are shortening solid-state electrolyte commercialization timelines.
Market Restraints
- Lithium carbonate volatility:Raw material price swings compress cathode producer margins and destabilize long-term cell pricing contracts with automotive buyers.
- Single-source electrolyte dependence:Sulfide solid-state electrolyte production concentrates among limited Japanese chemical suppliers, creating bottleneck risk for next-generation cell ramps.
- Energy density plateau:Conventional lithium-ion chemistries approach theoretical limits, constraining range extension for mass-market electric vehicle segments.
Strategic Opportunities
- Kyushu renewable integration:Grid-scale storage deployment lags behind solar and wind capacity additions, opening procurement channels for utility-scale battery systems.
- Medical device power:PMDA certification pathways for implantable batteries remain underdeveloped relative to demand from aging demographics and surgical robotics.
- EU-Japan Green Alliance alignment:Carbon border adjustment readiness creates first-mover advantage for Japanese manufacturers with verified low-carbon cathode supply chains.
Industry Challenges
- Solid-state manufacturing scale-up:Dry electrode processing and sulfide handling protocols require capital-intensive cleanroom expansion beyond existing lithium-ion infrastructure.
- Cross-chemistry talent scarcity:Battery engineering expertise fragments between liquid electrolyte veterans and emerging solid-state specialists, complicating workforce development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Rechargeable Battery Market |
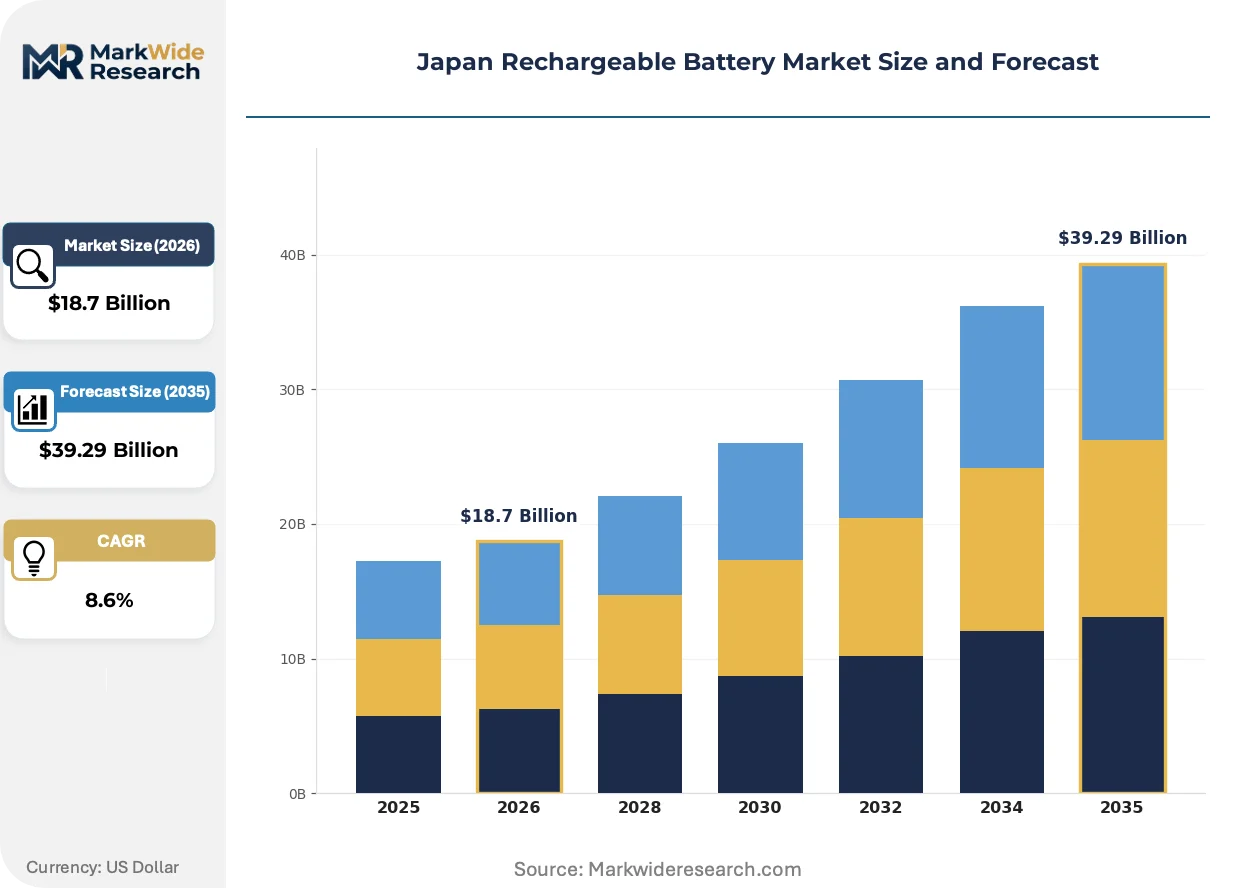
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead Acid, Lithium Polymer Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Equipment End User: Households, Automotive Manufacturers, Electronics Companies, Energy Providers Technology: Fast Charging, Solid-State, Wireless Charging, Hybrid Systems |
| Companies Covered | Panasonic Holdings Corporation, GS Yuasa Corporation, Toshiba Corporation, Samsung SDI, LG Energy Solution, BYD Company Ltd, EnerSys, Duracell Inc., Exide Industries Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Rechargeable Battery Market Trends and Innovations
Sulfide solid-state architectures are compressing development timelines as Japanese manufacturers race to unify materials innovation with automotive qualification protocols. Three interconnected shifts are restructuring competitive positioning.
Solid-state battery technology employing sulfide electrolytes is unifying energy density targets with intrinsic safety profiles previously treated as trade-offs. Toyota and Nissan are accelerating platform integration testing, compressing traditional automotive qualification cycles from five years toward three-year windows. This unification is enabling cylindrical formats to penetrate premium electric vehicle segments previously reserved for prismatic designs.
METI's forthcoming critical mineral stockpiling mandates are compelling cathode producers to secure lithium and cobalt through offtake agreements with Australian and Chilean miners. Domestic smelting capacity expansion in the Kanto corridor is absorbing these feedstocks, reducing spot market exposure. Automotive OEMs are responding by negotiating multi-year cell supply contracts with embedded price hedging mechanisms.
Buyer concentration among three major automotive groups is consolidating procurement leverage and compressing supplier qualification timelines. Tier-2 battery component vendors are bypassing traditional trading house intermediaries to secure direct relationships with cell manufacturers. This channel restructuring is most visible in the Nagoya industrial zone, where Toyota's supplier ecosystem is vertically integrating cathode active material production.
Japan Rechargeable Battery Market Segmentation
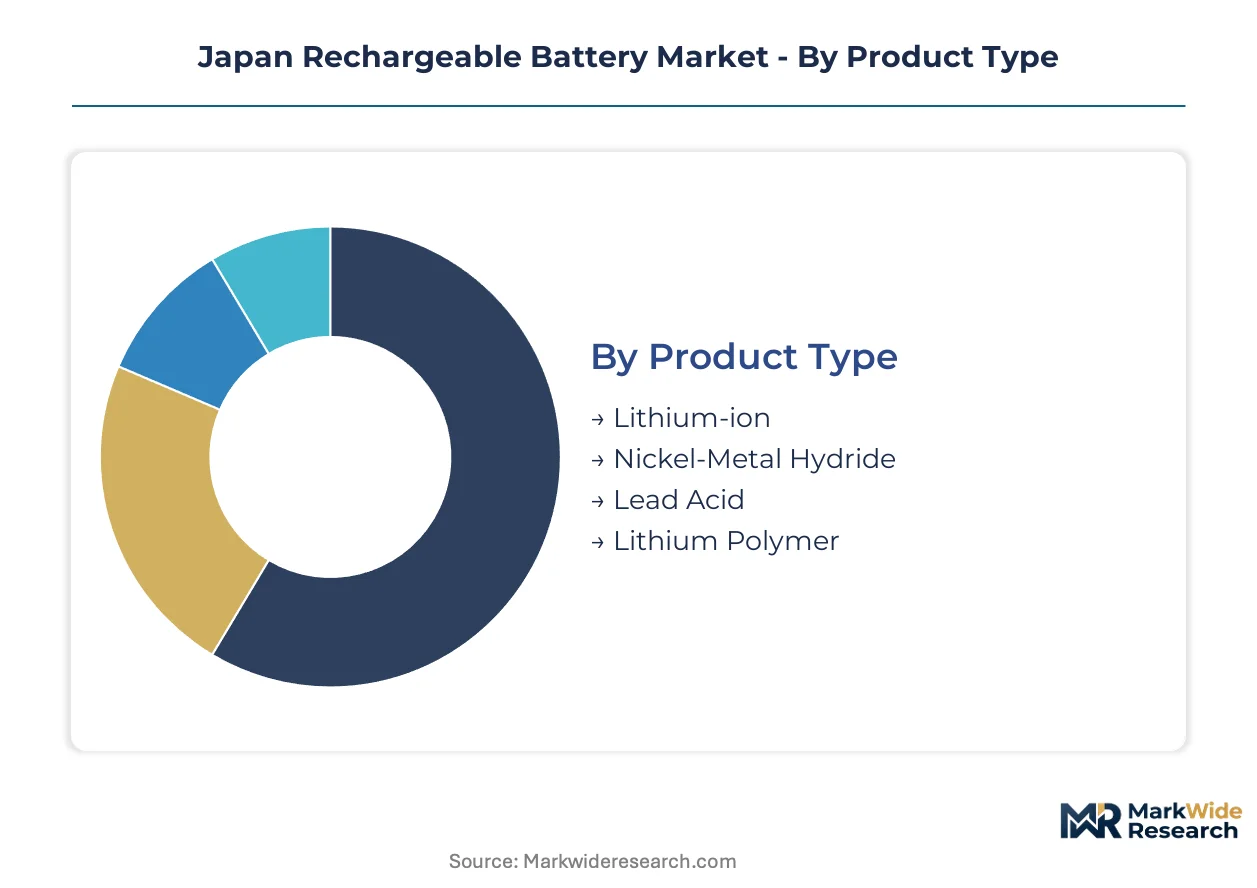
Segmentation reveals how METI policy and automotive procurement are concentrating investment across incompatible chemistries and charging architectures. Japanese manufacturers must navigate divergent margin pools between mature cylindrical formats and emerging solid-state platforms.
Product Type:
Standardization dominates high-volume automotive contracts, while specialty formats command customization premiums in medical and aerospace applications.
- Lithium-ion:Cylindrical and prismatic cells employing nickel-cobalt-manganese or nickel-cobalt-aluminum cathodes with energy densities exceeding 250 Wh/kg. Panasonic and LG Energy Solution concentrate cylindrical production in the Kanto corridor for Toyota and Nissan EV platforms, pulled by METI domestic content mandates.
- Nickel-Metal Hydride:Nickel hydroxide cathodes paired with hydrogen-absorbing alloy anodes deliver 30-50 Wh/kg with exceptional cycle stability. Toyota's hybrid vehicle installed base in the Nagoya industrial zone sustains steady demand despite lithium-ion displacement in new platforms.
- Lead Acid:Mature flooded and valve-regulated designs serve industrial backup power with lower energy density but cost advantages in stationary applications.
- Lithium Polymer:Pouch configurations with gel electrolytes enable form-factor flexibility for premium consumer electronics in Osaka-Kobe manufacturing clusters.
Most installed capacity flows through lithium-ion formats. Expansion is steepest in lithium polymer for wearable medical devices.
Application:
Volume concentration in automotive contracts compresses margins, while grid-scale deployments offer longer contract tenors with utility offtakers.
- Consumer Electronics:Smartphones, laptops, and tablets demand high-discharge-rate pouch cells with slim form factors. Osaka-based electronics assemblers source predominantly from domestic cylindrical suppliers for power tool derivatives.
- Electric Vehicles:Battery electric and plug-in hybrid platforms require 50-100 kWh packs with 800V architectures. Nissan's Ariya and Toyota's bZ series are accelerating cylindrical cell procurement from Kanto-region gigafactories.
- Renewable Energy Storage:Utility-scale lithium-ion systems buffer solar intermittency in Kyushu prefecture where grid integration lags behind generation capacity.
- Industrial Equipment:Forklifts, automated guided vehicles, and backup power systems favor lead acid and nickel-metal hydride for capital cost sensitivity.
Contract values peak in electric vehicle supply agreements. Deployment velocity is climbing fastest in renewable energy storage.
End User:
Procurement sophistication separates automotive OEMs with dedicated cell engineering teams from fragmented household demand served through retail channels.
- Automotive Manufacturers:Toyota, Nissan, and Honda operate direct supplier relationships with cathode active material producers, bypassing traditional trading houses. Multi-year offtake agreements now embed lithium carbonate price hedging mechanisms.
- Electronics Companies:Sony, Panasonic, and Sharp source custom pouch configurations for imaging equipment and professional audio systems with specialized discharge profiles.
- Energy Providers:Tokyo Electric Power and regional utilities procure containerized battery systems for frequency regulation and peak shaving.
- Households:Residential solar-plus-storage adopters in Kanto and Kansai metro areas purchase 5-15 kWh systems through installer networks.
Automotive manufacturers absorb the majority of high-capacity cell output. Residential adoption is accelerating most quickly in Kyushu prefecture.
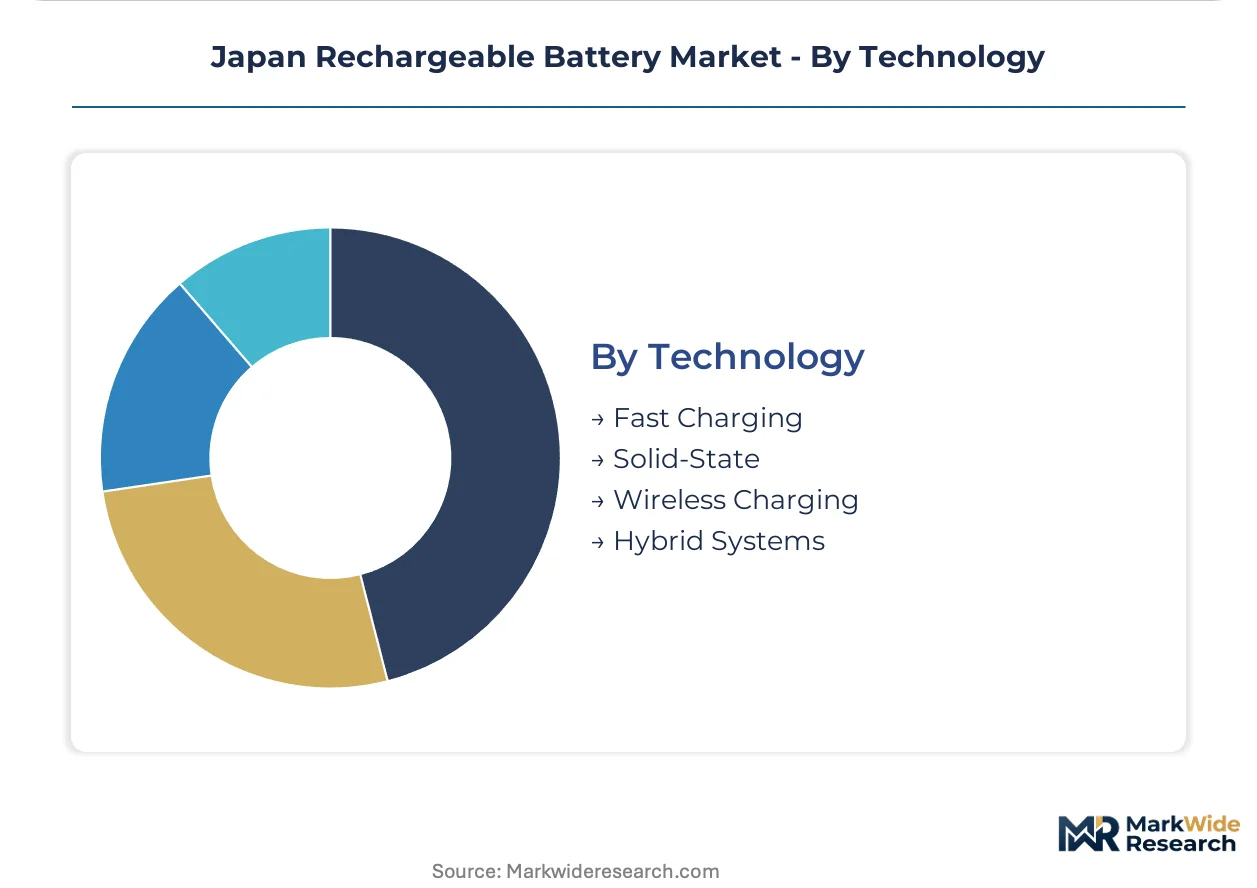
Technology:
Intellectual property concentration in sulfide electrolytes creates licensing leverage for early solid-state developers against incumbent liquid electrolyte incumbents.
- Solid-State:Sulfide and oxide electrolyte architectures eliminate flammable liquid components while targeting 400+ Wh/kg energy density. Toyota and Nissan are compressing automotive qualification timelines from five years toward three-year windows for platform integration.
- Fast Charging:Silicon-anode and high-nickel cathode combinations enable 10-80% charge in under 20 minutes. Charging infrastructure deployment along Tokyo-Osaka highway corridors is pulling cell specification requirements.
- Wireless Charging:Inductive pads for consumer electronics and prospective EV applications require specialized coil integration and thermal management.
- Hybrid Systems:Combined battery-supercapacitor architectures serve industrial applications needing high pulse power with moderate energy storage.
Solid-state pilot lines command the majority of METI R&D subsidies. Fast charging represents the fastest-growing specification requirement in automotive tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's rechargeable battery industry traces its commercial origins to Sony's 1991 lithium-ion commercialization, establishing a materials science foundation that now concentrates in three industrial corridors. Domestic production clusters around metropolitan manufacturing belts where automotive and electronics OEMs anchor demand.
Kanto/Tokyo
Panasonic's cylindrical cell production serves Toyota and Nissan EV platforms from facilities in Kanagawa and Tochigi prefectures. METI's domestic content mandates under the Act on Promotion of Resource Circulation for Batteries compel cathode material localization. The Tsukuba materials science corridor hosts pilot lines for sulfide solid-state electrolyte development.
Kansai/Osaka
Consumer electronics manufacturers in Osaka and Kyoto prefectures procure lithium polymer pouch cells for imaging equipment and professional audio systems. JIS safety testing protocols govern cell certification for these precision applications. The Sakai industrial zone concentrates gel electrolyte formulation capacity for wearable medical devices.
Chubu/Nagoya
Toyota's hybrid vehicle installed base sustains nickel-metal hydride demand across Aichi and Mie prefectures. The Nagoya supplier ecosystem is vertically integrating cathode active material production through direct OEM-supplier relationships. PMDA certification pathways for implantable batteries remain underdeveloped relative to surgical robotics demand from this manufacturing hub.
Kyushu
Utility-scale lithium-ion procurement lags behind solar capacity additions in Fukuoka and Kumamoto prefectures. Regional utilities negotiate containerized battery systems for frequency regulation and peak shaving. Residential solar-plus-storage adoption accelerates fastest here, with 5-15 kWh systems moving through installer networks.
Tohoku
Industrial backup power applications favor lead acid and nickel-metal hydride for capital cost sensitivity in Sendai and Fukushima prefectures. Grid resilience investments following the 2011 earthquake drive demand for stationary storage. METI's critical mineral stockpiling mandates are stimulating lithium processing pilot facilities in this region.
Japan Rechargeable Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across chemistry specialization and automotive qualification depth. The vendor base stratifies into three tiers: integrated material-to-cell producers, chemistry-specific specialists, and trading house-mediated distributors. Two strategic archetypes dominate: backward-integrated conglomerates controlling cathode supply chains, and joint-venture partners leveraging foreign cell engineering. Capacity expansion and direct OEM-supplier relationship building constitute the dominant competitive moves.
Among Japan-based producers, Panasonic Holdings Corporation and GS Yuasa Corporation exemplify the backward-integrated archetype, while LG Energy Solution represents the joint-venture partnership model. Panasonic anchors cylindrical production for premium EV platforms. GS Yuasa occupies a stable position in industrial and backup power segments. LG Energy Solution competes through manufacturing presence with domestic partners.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| GS Yuasa Corporation |
| Toshiba Corporation |
| Samsung SDI |
| LG Energy Solution |
| BYD Company Ltd |
| EnerSys |
| Duracell Inc. |
| Exide Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate feedstock from Australian and Chilean mines flows through Kanto-region smelters before reaching cathode producers, with METI's domestic content mandates compressing spot-market exposure into long-term offtake structures that stratify pricing across automotive contract tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with JIS certification grade and volume scale driving differentiation between automotive OEM supply agreements and industrial backup power deals. Pricing pressure stems from lithium carbonate volatility that destabilizes cathode producer margins. Automotive OEMs with embedded price hedging mechanisms exhibit lowest price sensitivity, while residential solar-plus-storage adopters in Kyushu face highest cost consciousness.
Supply Chain Analysis
Reverse-logistics flows for end-of-life batteries are consolidating around METI-mandated recycling quotas, with spent cells from Kanto automotive plants feeding closed-loop material recovery infrastructure. Cathode active materials draw from Australian lithium and Chilean cobalt processed through domestic Kanto and Tohoku facilities. Single-source vulnerability concentrates in sulfide solid-state electrolyte production among limited Japanese chemical suppliers. Distribution runs through direct OEM-supplier relationships that bypass traditional trading house intermediaries in the Nagoya industrial zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's rechargeable battery market functions as a geographic-arbitrage play where METI's domestic content requirements create cost premiums against South Korean and Chinese manufacturing, rewarding localized supply chain control.
For Market Incumbents: Lock in cathode material supply through offtake agreements with Australian and Chilean miners before METI's critical mineral stockpiling mandates tighten feedstock availability. Deepen backward integration into sulfide electrolyte production to mitigate single-source vulnerability from Japanese chemical suppliers. Prioritize capacity expansion in the Kanto corridor to satisfy Toyota and Nissan EV platform procurement acceleration. For New Entrants and Emerging Players: Begin with Kyushu utility-scale storage deployments where grid integration lags behind solar capacity additions, creating procurement channels for containerized battery systems. Target PMDA certification pathways for implantable medical device batteries, a segment where demand from surgical robotics outpaces qualified supplier capacity. Pursue direct relationships with regional utilities rather than competing for automotive OEM qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where cross-chemistry talent scarcity fragments between liquid electrolyte veterans and emerging solid-state specialists. Long-term viability favors integrated material-to-cell producers with captive cathode supply chains and automotive qualification depth. Watch METI's solid-state commercialization timeline announcements as the primary inflection signal for next-generation cell manufacturing investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Captive supply of nickel-cobalt-manganese precursors reduces import dependency under METI domestic content mandates. |
| Solid-State Pilot Line Expansion | Tsukuba materials science corridor facilities compress Toyota and Nissan automotive qualification timelines. |
| Direct OEM-Supplier Relationship Building | Bypassing trading house intermediaries in Nagoya secures multi-year cell supply contracts with price hedging. |
| Closed-Loop Recycling Infrastructure | Act on Promotion of Resource Circulation for Batteries compliance localizes end-of-life material recovery. |
| Kyushu Utility-Scale Deployment Partnership | Regional utilities procure containerized systems for frequency regulation where solar intermittency strains grid stability. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with battery cell engineering directors, automotive OEM procurement leads, cathode material plant managers, and METI policy officials with secondary validation through customs trade data, JIS standard documentation, SEC filings from listed producers, and vehicle production databases. Bottom-up cell shipment modeling and top-down automotive demand estimation triangulated volume outputs.
Segment-weighting approaches distributed value across lithium-ion, nickel-metal hydride, and solid-state chemistry tiers, with further disaggregation by cylindrical versus prismatic formats and automotive versus stationary applications. CAGRs derived from regression analysis against EV platform deployment schedules and renewable capacity addition trajectories. Forecast inputs incorporated METI subsidy allocation patterns and sulfide electrolyte pilot production timelines.
Several conditions sit outside the modeled scope, including unannounced revisions to critical mineral stockpiling thresholds and breakthroughs in oxide solid-state architectures that could redirect R&D subsidies. Forecasts reflect assumptions about automotive qualification cycle compression and lithium carbonate price stabilization. Practitioners should monitor METI solid-state commercialization announcements and EU-Japan Green Alliance carbon border adjustment implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Pack for Marine Hybrid and Full Electric Propulsion Market
Batteries
Global Industrial Lead Acid Battery Market
Batteries
Zinc Carbon Battery Market
Batteries
Global Bio Compatible Battery Market
Batteries
Bio Based Battery Market
Batteries
Battery Swapping Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Power Battery Cells Market
Batteries
Rechargeable Coin Cell Market
Batteries
Thin Film and Printed Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Military Battery Market
Batteries
48 Volt Battery System Market
Batteries
Redox Flow Battery Market
Batteries
South America Rechargeable Battery Market
Batteries
Lithium Marine Battery Market