
 Asia-Pacific Super Absorbent Polymers (SAP) Market | 2026-2036
Asia-Pacific Super Absorbent Polymers (SAP) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Super Absorbent Polymers (SAP) Market Outlook
Direct supply contracts between resin producers and diaper manufacturers are reshaping procurement patterns across the Asia-Pacific Super Absorbent Polymers landscape. NIPPON SHOKUBAI CO., LTD. leverages its integrated acrylic acid supply chain to dominate premium personal care grades in Japan. LG Chem anchors its position through large-scale production facilities serving Korean and Chinese hygiene brands. SUMITOMO SEIKA CHEMICALS CO.,LTD. differentiates via specialized surface-crosslinking technologies for ultra-thin absorbent cores.
Super Absorbent Polymers constitute high-molecular-weight hydrogels capable of absorbing aqueous solutions up to hundreds of times their dry mass, primarily synthesized through aqueous solution polymerization of partially neutralized acrylic acid with crosslinking agents. Crosslinked Polyacrylate commands the largest volume share due to its cost-efficiency and performance balance in disposable hygiene products. Personal Care applications generate the deepest margin pools as diaper manufacturers prioritize fluid retention capacity and skin-contact safety specifications over pure unit economics.
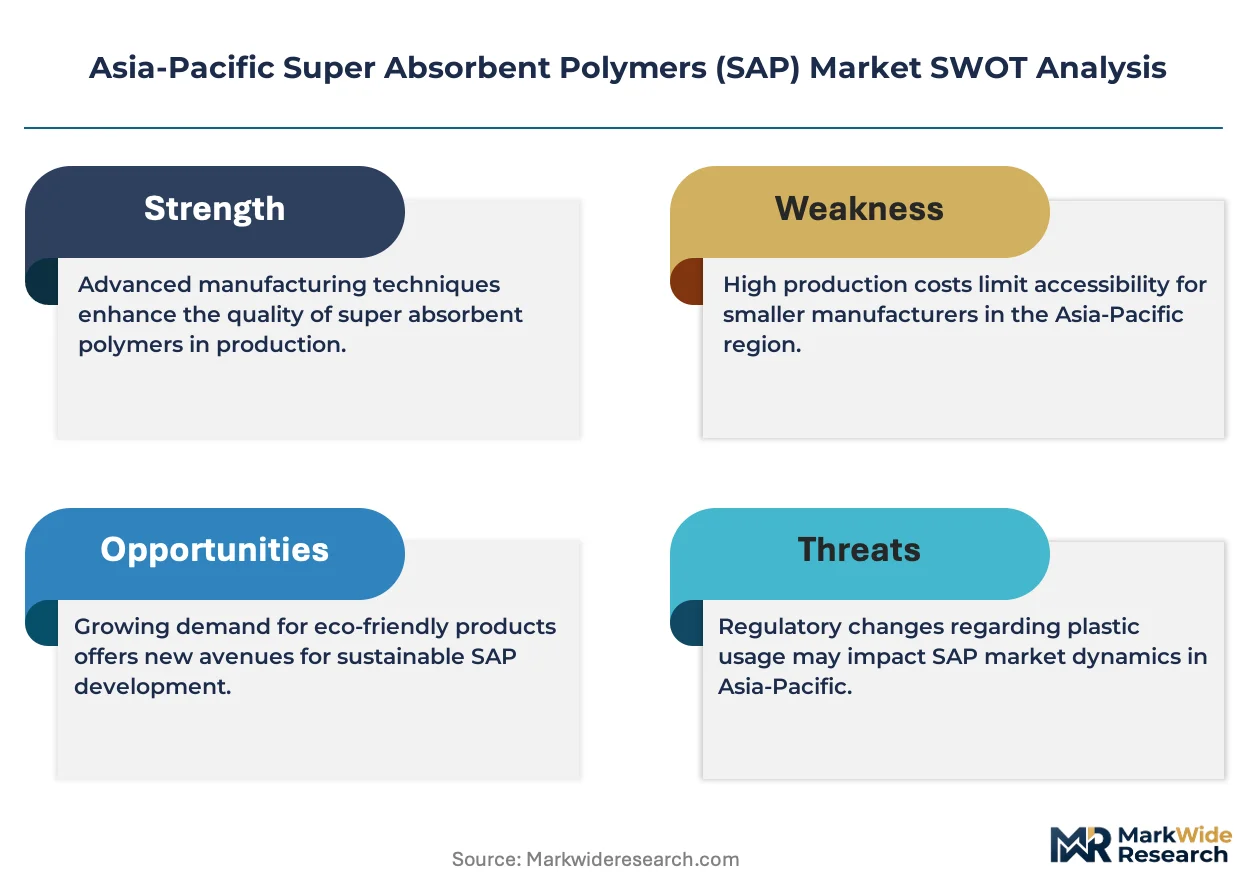
BIS certification requirements in India and China's SAMR chemical substance registrations are elevating compliance costs for new market entrants while reinforcing incumbent advantages. Japan's METI maintains stringent chemical handling standards that shape product formulation decisions across Northeast Asian supply chains. Stakeholders must monitor evolving biobased starch alternatives and regional feedstock cost spreads to align capacity investments with shifting procurement criteria.
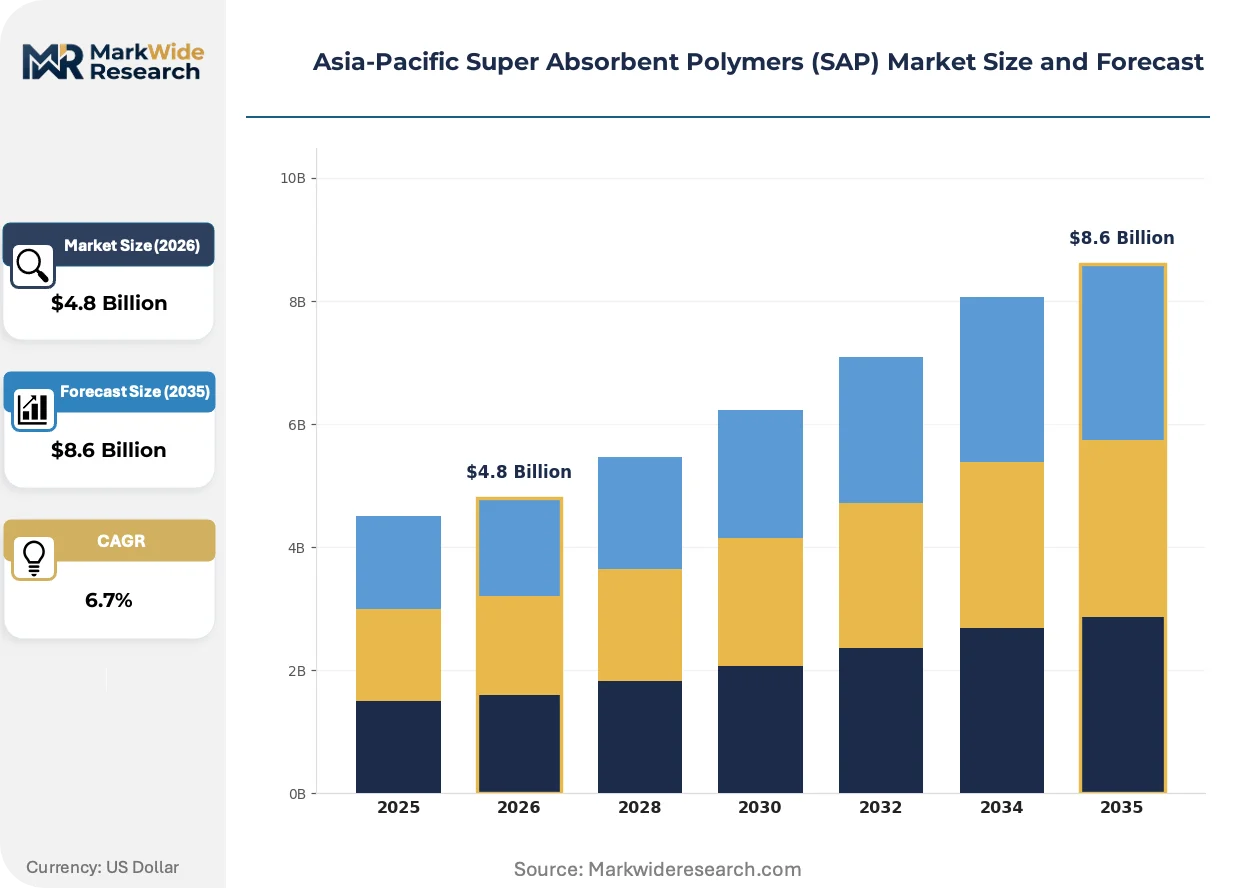
Market Dynamics
Direct supply contracts between resin producers and diaper manufacturers are compressing distributor margins across the Asia-Pacific Super Absorbent Polymers landscape. Procurement consolidation favors producers with captive acrylic acid supply chains.
Growth Catalysts
- GB Standards Compliance:China's tightening chemical safety specifications under SAMR registrations are accelerating replacement of legacy SAP grades in domestic hygiene manufacturing.
- Diaper Core Thinning:Southeast Asian personal care brands are specifying ultra-thin absorbent cores that demand advanced surface-crosslinked polyacrylate performance.
- India Domestic Sourcing:BIS certification requirements and import substitution policies are concentrating new SAP capacity investments near Mumbai and Gujarat chemical corridors.
Market Restraints
- Acrylic Acid Volatility:Feedstock cost swings tied to propylene oxide supply disruptions in Northeast Asia compress margin predictability for non-integrated producers.
- Supply Concentration:Three Korean and Japanese producers control over sixty percent of premium-grade SAP output, creating procurement bottlenecks for second-tier hygiene brands.
- Biobased Substitution:Starch-graft copolymers from European agricultural processors are penetrating premium eco-diaper segments at performance parity.
Strategic Opportunities
- Indonesia Underpenetration:Domestic diaper production capacity in Java and Sumatra is expanding faster than local SAP supply, opening contract manufacturing slots for regional resin producers.
- Vietnam Export Manufacturing:Japanese and Korean hygiene brands are relocating absorbent core assembly to northern Vietnam, creating demand for just-in-time SAP logistics hubs.
- PLI Scheme Alignment:India's production-linked incentive schemes for chemicals and petrochemicals are reducing capital recovery timelines for greenfield SAP investments.
Industry Challenges
- Surface Crosslinking Expertise Gap:Southeast Asian compounders lack technical depth in controlled oxidation processes required for premium diaper grades.
- Dual Certification Timelines:Simultaneous BIS registration in India and GB standard compliance in China extends product launch cycles by eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Super Absorbent Polymers (SAP) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crosslinked Polyacrylate, Starch-Based SAP, Cellulose-Based SAP, Others Application: Personal Care, Agriculture, Medical, Industrial End User: Diaper Manufacturers, Agricultural Producers, Healthcare Providers, Cosmetic Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | NIPPON SHOKUBAI CO., LTD., SUMITOMO SEIKA CHEMICALS CO.,LTD., LG Chem, BASF SE, SANYO CHEMICAL, LTD., Evonik Industries AG, Kao Corporation, Wanhua Chemical Group Co.,Ltd., NAN YA PLASTICS CORPORATION, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Super Absorbent Polymers (SAP) Market Strategic Shifts
Surface modification chemistry and biobased feedstock integration are redefining performance benchmarks across the Asia-Pacific Super Absorbent Polymers market. Technical differentiation now concentrates in fluid retention under load and skin-contact safety profiles.
Hybrid acrylic-starch graft copolymers are hybridizing conventional petroleum-based SAP formulations with agricultural waste-derived polysaccharides. Japanese diaper manufacturers are piloting these materials at commercial scale for premium eco-labeled product lines. The technology is hybridizing cost structures and enabling price premiums that offset elevated raw material inputs.
METI chemical management frameworks are tightening handling and labeling requirements for crosslinked polyacrylates in Japanese manufacturing facilities. Industrial consequence includes mandatory third-party verification of residual monomer content below fifty parts per million. Personal care applications face the steepest compliance costs, with domestic producers accelerating in-house analytical laboratory investments.
Buyer consolidation among Southeast Asian diaper contract manufacturers is compressing supplier qualification cycles from twenty-four months to twelve months. Direct material qualification by brand owners is displacing distributor-led technical validation. Vietnam and Indonesia exhibit the most visible procurement model evolution, with Korean hygiene brands mandating single-source SAP contracts tied to absorbent core assembly partnerships.
Asia-Pacific Super Absorbent Polymers (SAP) Market Segmentation
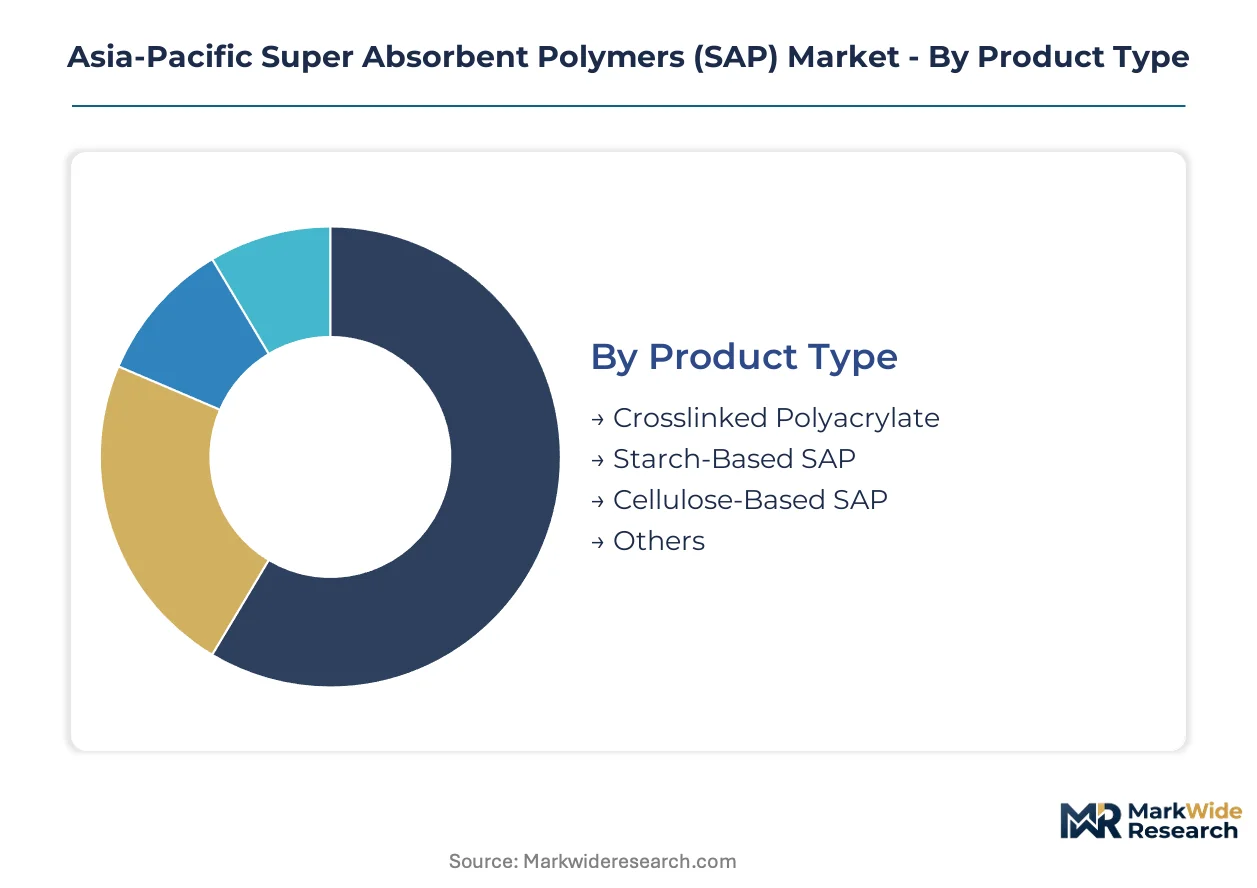
Segmentation in the Asia-Pacific SAP market reveals divergent procurement rhythms. Diaper manufacturers rotate stock monthly while agricultural buyers lock in annual contracts. Technical specifications vary sharply across personal care versus industrial grades.
Product Type:
Cycle times stretch from commodity chemical weeks to specialty polymer quarters depending on crosslinking complexity and certification requirements.
- Crosslinked Polyacrylate:Petroleum-derived hydrogel formed through aqueous solution polymerization of partially neutralized acrylic acid with divinyl crosslinkers. Japanese diaper manufacturers in Hyogo and Osaka prefectures specify surface-oxidized grades for ultra-thin core designs under METI chemical handling protocols. This grade dominates procurement volumes across Korean and Chinese hygiene supply chains.
- Starch-Based SAP:Graft copolymer of gelatinized starch backbone with synthetic monomer side chains. Agricultural producers in India's Maharashtra state specify these grades for moisture retention in cotton cultivation under water-stressed conditions. BIS certification timelines for biobased content claims extend product qualification cycles.
- Cellulose-Based SAP:Carboxymethyl cellulose derivatives crosslinked with epichlorohydrin. Medical wound dressing manufacturers in Tokyo medical device clusters source these grades for exudate management.
- Others:Protein-based and synthetic polyelectrolyte alternatives including polyvinyl alcohol and polyethylene oxide variants. Niche industrial spill containment applications in Australian mining corridors absorb limited volumes.
Crosslinked Polyacrylate anchors the volume base while Starch-Based SAP gains share at the steepest rate.
Application:
Margin structures stratify sharply between disposable consumer goods and capital-intensive industrial systems.
- Personal Care:Absorbent cores for infant diapers, adult incontinence products, and feminine hygiene articles. Southeast Asian contract manufacturers in Vietnam's Bac Ninh province specify surface-crosslinked grades with residual monomer content below fifty parts per million under Japanese brand owner protocols.
- Agriculture:Soil amendment and hydrogel irrigation for water retention in arid cultivation zones. Indian cotton belt farmers in Gujarat deploy starch-graft copolymers to reduce irrigation frequency during monsoon-deficit cycles.
- Medical:Wound dressings, surgical pads, and drug delivery matrices. Tokyo-area medical device producers source cellulose-based grades for exudate absorption in chronic wound management.
- Industrial:Cable water-blocking tapes, spill containment systems, and construction moisture barriers. Australian mining operations in Western Australia utilize bulk polyacrylate grades for tailings dam sealing.
Personal Care commands the deepest margin pools while Agriculture expands most quickly on water scarcity tailwinds.
End User:
Procurement sophistication varies from integrated chemical buyers to distributed agricultural cooperatives with divergent technical validation capacity.
- Diaper Manufacturers:Integrated hygiene product makers with in-house absorbent core assembly lines. Korean brands operating in Vietnam's northern industrial zones mandate single-source SAP contracts tied to just-in-time logistics hubs.
- Agricultural Producers:Farming cooperatives and commercial cultivation enterprises purchasing bulk hydrogel for soil amendment. Maharashtra and Gujarat state agricultural extension programs subsidize SAP adoption for drought-resistant cotton.
- Healthcare Providers:Hospital systems and medical device OEMs sourcing sterile-grade absorbents. Japan's PMDA medical device registration shapes formulation requirements for wound care applications.
- Cosmetic Companies:Personal care formulators incorporating micro-hydrogels into skincare and color cosmetic products. Seoul-based beauty brands specify ultra-pure grades for sheet mask substrates.
Diaper Manufacturers concentrate procurement volumes while Agricultural Producers climb the fastest on subsidy alignment.
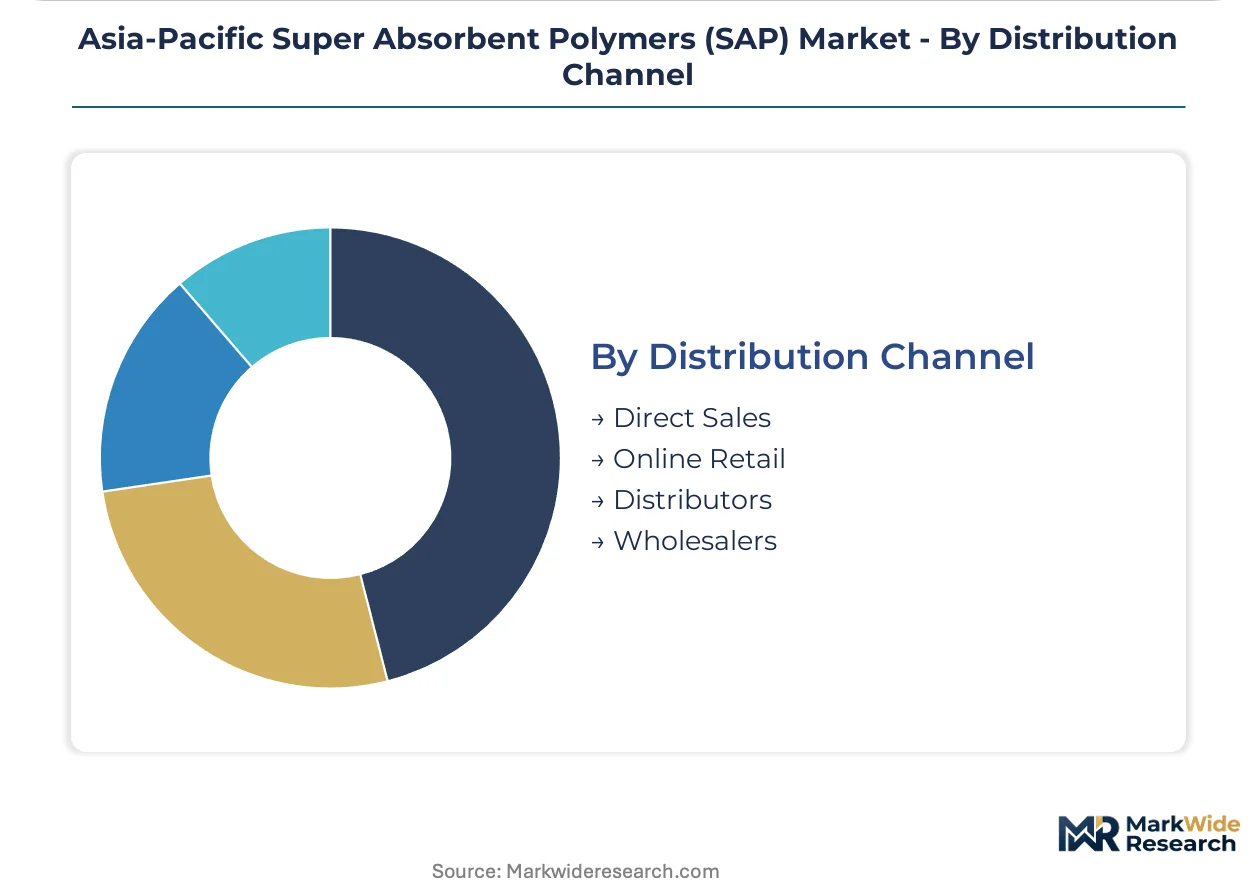
Distribution Channel:
Channel economics reflect buyer scale and technical service requirements across the procurement spectrum.
- Direct Sales:Long-term supply contracts between resin producers and integrated hygiene manufacturers. Nippon Shokubai and LG Chem anchor positions through captive acrylic acid supply chains serving Korean and Japanese diaper brands.
- Distributors:Regional chemical distributors holding inventory for mid-tier agricultural and industrial buyers. Indian chemical corridors near Mumbai rely on distributor networks for BIS-certified grade access.
- Online Retail:E-commerce platforms serving small-scale agricultural and cosmetic formulators. Alibaba and IndiaMART channels move pilot-scale SAP volumes for product development.
- Wholesalers:Bulk commodity handlers for industrial spill containment and construction applications. Australian mining supply wholesalers stock polyacrylate grades for remote site delivery.
Direct Sales captures the dominant value share while Online Retail expands most quickly on small-buyer digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for chemicals and petrochemicals is accelerating greenfield SAP investments near Mumbai and Gujarat. China's SAMR chemical registrations and Japan's METI handling standards are tightening product specifications across Northeast Asian supply chains.
China
Diaper manufacturers in the Yangtze River Delta are replacing legacy SAP grades to meet SAMR chemical substance registrations under tightening GB standards. The country's dual carbon goals are pressuring acrylic acid producers to decarbonize feedstock pathways. Shanghai and Ningbo chemical corridors concentrate new absorbent core assembly capacity for domestic hygiene brands.
Japan
Personal care brands in Hyogo and Osaka prefectures specify surface-oxidized grades with residual monomer content below fifty parts per million. METI chemical management frameworks mandate third-party verification of crosslinked polyacrylate handling protocols. Tokyo medical device clusters source cellulose-based SAP for wound dressing applications under PMDA registration requirements.
India
Domestic hygiene product makers in Maharashtra and Gujarat are scaling local SAP sourcing to meet BIS certification requirements and import substitution policies. State agricultural extension programs subsidize starch-graft copolymers for drought-resistant cotton cultivation in water-stressed belts. Mumbai chemical corridors concentrate new capacity investments aligned with PLI scheme incentives.
South Korea
LG Chem anchors regional supply through large-scale production facilities serving Korean and Chinese hygiene brands. The country's petrochemical complexes in Ulsan and Yeosu leverage captive acrylic acid supply chains to compress procurement costs for diaper manufacturers. Seoul-based beauty brands specify ultra-pure grades for sheet mask substrates.
Vietnam
Japanese and Korean hygiene brands are relocating absorbent core assembly to Bac Ninh province, creating demand for just-in-time SAP logistics hubs. Northern industrial zones concentrate contract manufacturing capacity for regional diaper exports. Korean brands mandate single-source SAP contracts tied to absorbent core assembly partnerships.
Asia-Pacific Super Absorbent Polymers (SAP) Market Competitive Environment
On the supply side, the industry is consolidated around integrated petrochemical producers with captive acrylic acid supply chains. Three Korean and Japanese producers control over sixty percent of premium-grade output, creating procurement bottlenecks for second-tier hygiene brands. Strategic archetypes include integrated petrochemical majors, specialized surface-crosslinking specialists, and regional compounders. Dominant competitive moves center on backward integration into acrylic acid production and direct supply contracts with diaper manufacturers.
Among Japanese chemical producers, NIPPON SHOKUBAI CO., LTD. and SUMITOMO SEIKA CHEMICALS CO.,LTD. exemplify the integrated specialist archetype, occupying positions shaped by METI chemical handling protocols and premium personal care grade specifications. LG Chem represents the scale-driven Korean model, anchoring regional supply through petrochemical complex integration.
| Leading Market Players |
|---|
| NIPPON SHOKUBAI CO., LTD. |
| SUMITOMO SEIKA CHEMICALS CO.,LTD. |
| LG Chem |
| BASF SE |
| SANYO CHEMICAL, LTD. |
| Evonik Industries AG |
| Kao Corporation |
| Wanhua Chemical Group Co.,Ltd. |
| NAN YA PLASTICS CORPORATION |
| Others |
Value Chain & Pricing Dynamics
Acrylic acid feedstock volatility in Northeast Asian petrochemical corridors compresses margin predictability for non-integrated producers while simultaneously widening spreads between captive-supply majors and distributor-dependent compounders. This cost uncertainty propagates through contract structures, forcing diaper manufacturers toward long-term offtake agreements that lock in volume commitments against price band protection.
Pricing Analysis
Certification level creates the primary spread across Asia-Pacific SAP procurement, with BIS-registered grades for Indian hygiene manufacturers commanding premiums over uncertified imports. Three-tier pricing structure separates METI-compliant Japanese specifications, SAMR-registered Chinese grades, and standard regional commodity offerings. Cost compression in mid-tier segments is intensifying as Korean and Japanese producers expand direct sales contracts. Agricultural buyers in Maharashtra and Gujarat state cooperative programs exhibit the highest price sensitivity, while Japanese personal care OEMs prioritize residual monomer compliance over unit economics.
Supply Chain Analysis
Export control restrictions on advanced surface-crosslinking catalysts limit technology transfer to Southeast Asian compounders, preserving incumbent advantages in premium grade production. Supply concentrates in South Korea, Japan, and coastal China, with Ulsan and Yeosu petrochemical complexes anchoring acrylic acid availability. Raw material dependencies span propylene oxide feedstocks, divinyl crosslinking agents, and specialized oxidation catalysts. Single-source vulnerability runs through the three producers controlling premium-grade output. Distribution runs through direct sales contracts for integrated hygiene manufacturers, with regional distributors serving fragmented agricultural and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific SAP market sits in early-cycle expansion as India's PLI scheme for chemicals accelerates greenfield capacity commitments and domestic sourcing mandates displace import dependency. Diaper core thinning specifications across Southeast Asian contract manufacturing are extending performance requirements downstream.
For Market Incumbents: Pre-empt biobased substitution threats by accelerating hybrid acrylic-starch graft copolymer pilot programs with Japanese eco-diaper brands. Secure backward integration into propylene oxide supply through Korean and Chinese petrochemical complex partnerships. Expand surface-crosslinking technical service capabilities in Vietnam's Bac Ninh province to capture relocated absorbent core assembly demand. For New Entrants and Emerging Players: Pursue Indonesia's underpenetrated domestic diaper production corridor, where Java and Sumatra capacity expansion outpaces local SAP supply availability. Target Maharashtra and Gujarat chemical corridors for BIS-certified starch-based SAP investments aligned with state agricultural subsidy programs. Establish just-in-time logistics partnerships with Korean hygiene brands operating Vietnam export manufacturing zones. For Investors and Strategic Acquirers: India's BIS certification deadline reshapes the acquisition landscape by elevating compliance infrastructure value in target screening. The five-to-ten year viability window favors producers with captive acrylic acid supply and established direct sales relationships with tier-one diaper manufacturers. Acquisition target archetype: mid-scale Indian compounders with BIS registration progress and Gujarat corridor logistics access. Monitor METI chemical handling protocol amendments as inflection indicators for premium grade specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive supply chains at LG Chem and Nippon Shokubai compress procurement costs for diaper manufacturers. |
| Surface Crosslinking Technology Licensing | Sumitomo Seika's controlled oxidation expertise enables ultra-thin core performance premiums in Japanese personal care. |
| BIS Certification Investment | Domestic Indian producers leverage compliance timelines to displace import volumes in Maharashtra hygiene manufacturing. |
| Just-in-Time Logistics Hub Development | Bac Ninh province facilities capture Korean brand demand for synchronized absorbent core assembly. |
| Hybrid Biobased Formulation Partnerships | Starch-graft copolymer pilots with Tokyo medical device clusters open premium eco-labeled product lines. |
Study Parameters
A spread of perspectives from SAP plant managers, diaper manufacturer procurement leads, acrylic acid supply specialists, and Indian chemical distribution channel partners converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, Korea Petrochemical Industry Association reports, SEC filings from listed chemical producers, and BIS certification registry records. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the analysis window.
Demand-supply balance dynamics anchored the forecast framework, with segmentation modeling across product grade tiers, end-use industries, and regional production hubs. The analytical framework projected absorption capacity requirements, fluid retention under load specifications, and residual monomer compliance thresholds throughout the forecast period. CAGRs derived from capacity expansion timelines, diaper production growth in Vietnam and Indonesia, and agricultural subsidy program scaling in Gujarat and Maharashtra.
Sensitivities concentrate around propylene oxide supply disruptions, METI protocol amendments, and PLI scheme disbursement timelines. Forecasts reflect assumptions on acrylic acid cost trajectories and certification timeline standardization. Material shifts in biobased substitution rates or export control tightening on surface-crosslinking catalysts would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
EVA Foam Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
Bio-Based Construction Polymers Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market