
 Vacuum Sealers Market | 2026-2036
Vacuum Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Sealers Market Analysis
Multi-source procurement for vacuum sealing systems is broadening as food manufacturers diversify supplier risk across European and Asian vendors. ULMA Packaging leverages its Basque manufacturing base to sustain chamber sealer exports into Latin American meat processing. MULTIVAC anchors premium automatic lines in German dairy and charcuterie operations. Sealed Air Corporation competes through Cryovac-branded barrier films integrated with its sealing hardware.
Vacuum sealers are electromechanical devices that extract air from a package cavity before heat-sealing a barrier film, typically achieving residual oxygen levels below 0.5% to inhibit aerobic microbial growth. Chamber sealers dominate industrial throughput with pump capacities reaching 100 m³/h and seal bar lengths exceeding 1,000 mm, while handheld units serve sous vide cooking and residential food preservation. External sealers occupy the fastest-expanding tier as small restaurants and ghost kitchens adopt countertop units for portion control and waste reduction. Automatic sealers command the strongest margin pools in pharmaceutical and medical device packaging, where ISO 11607 validation requirements elevate equipment specifications and service attach rates.
EMA and FDA both enforce material contact compliance for food-grade vacuum films, while EU MDR extends sterilization validation to medical vacuum packaging systems. REACH restricts phthalate plasticizers in PVC-based vacuum bags, redirecting formulation toward polyethylene and polyamide coextrusions. Stakeholders must monitor how ECHA's expanding SVHC candidate list reshapes film chemistry and whether USDA FSIS updates to HACCP documentation will mandate vacuum-sealed lot traceability in US meat plants.
Market Dynamics
The EU's F-Gas Regulation is forcing refrigerant-dependent vacuum cooling systems into accelerated replacement cycles, compressing equipment refresh timelines and elevating capital deployment for compliant pump technologies.
Growth Catalysts
- Food spoilage reduction mandates:Processors across Germany, France, and Italy deploy chamber sealers to meet retailer shelf-life specifications and cut waste-related losses.
- REACH-compliant film chemistry:ECHA's expanding SVHC list redirects formulation from phthalate-laden PVC toward polyethylene-polyamide coextrusions, opening retrofit demand.
- Pharmaceutical packaging validation:ISO 11607 requirements for sterile barrier systems pull automatic sealer upgrades in medical device manufacturing clusters.
Market Restraints
- Fluorinated gas phase-out costs:The EU F-Gas Regulation imposes steep retrofit expenses on vacuum cooling-integrated sealing lines, squeezing mid-tier processor margins.
- Pump and compressor supply concentration:German and Italian component specialists control high-capacity vacuum pump sourcing, exposing buyers to extended lead times.
- Barrier film raw material volatility:Polyamide resin prices fluctuate with caprolactam feedstock availability, compressing film converter margins.
Strategic Opportunities
- Ghost kitchen penetration:Countertop external sealers address portion-control needs in unlicensed food preparation facilities across urban Spain and Portugal.
- USDA FSIS traceability alignment:Anticipated HACCP documentation updates for vacuum-sealed meat lots create compliance-service revenue pools.
- IoT-enabled predictive maintenance:Sensor-integrated automatic lines converge operational data with service scheduling, unbundling traditional warranty models.
Industry Challenges
- Vacuum pump technician scarcity:Specialized electromechanical repair skills concentrate in Basque and Bavarian industrial zones, creating service coverage gaps.
- Legacy PLC integration friction:New sealing hardware faces protocol mismatches with existing packaging line control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Sealers Market |
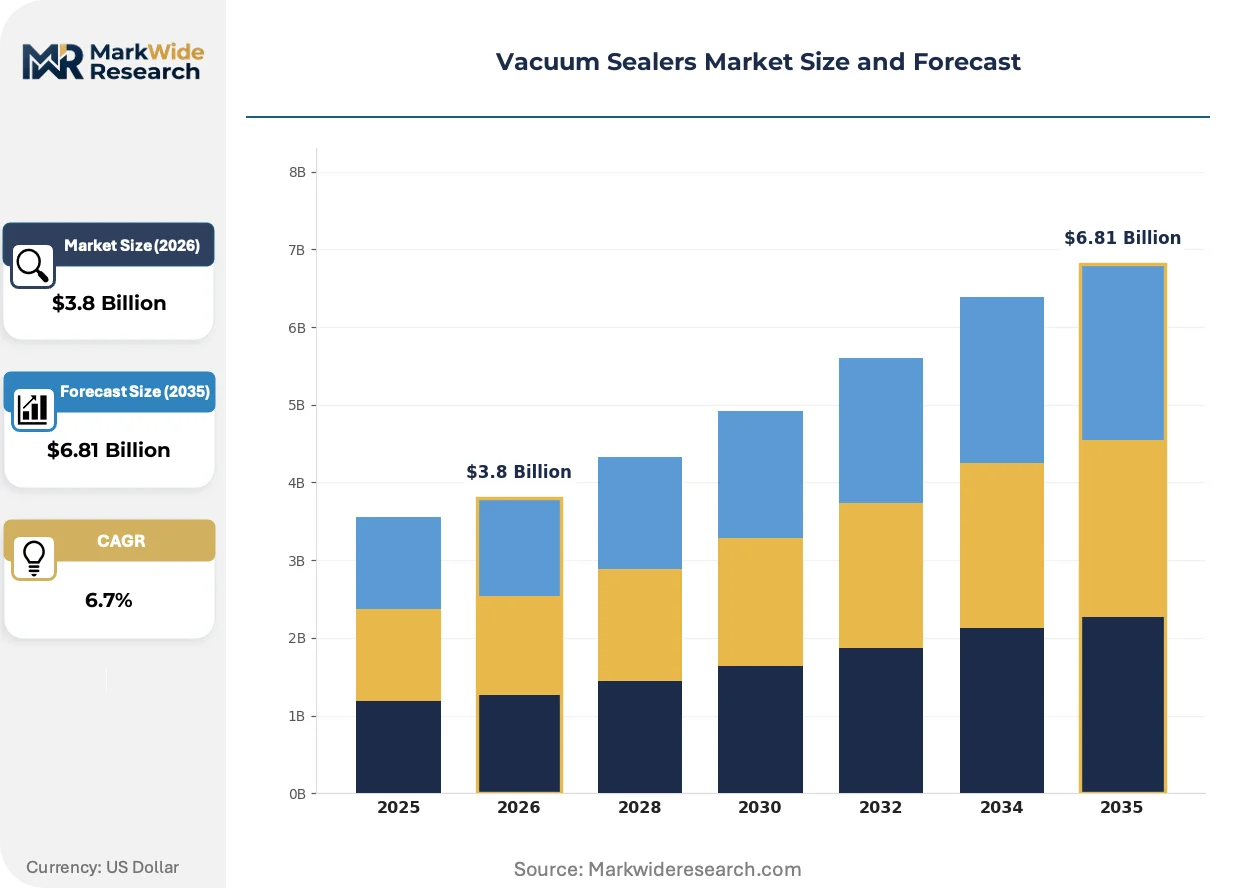
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Sealers, Chamber Sealers, Handheld Sealers, Multi-Functional Sealers End User: Restaurants, Households, Food Processors, Retail Stores Technology: Electric Sealers, Manual Sealers, Automatic Sealers, Pneumatic Sealers Application: Food Preservation, Sous Vide Cooking, Storage, Vacuum Packaging |
| Companies Covered | ULMA Packaging, IMA S.p.A., MULTIVAC, ORVED S.r.l., JBT Corporation, Sealed Air Corporation, Henkelman, Kenwei, Syntegon Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Sealers Market Emerging Trajectories
Equipment intelligence and material chemistry are converging to redefine performance benchmarks across food, pharmaceutical, and medical packaging applications.
Smart vacuum sealing systems is unifying pump performance monitoring with cloud-based predictive analytics. Pharmaceutical contract packagers in Switzerland and Germany adopt these platforms fastest. The technology is unifying hardware sales with recurring software revenue, compressing pure equipment margin dependence.
REACH restrictions on phthalate plasticizers are accelerating PVC displacement in food-contact films. Industrial converters in northern Italy and the Netherlands reformulate toward multilayer polyethylene-polyamide structures. Medical packaging lines face the steepest recertification timelines as ECHA evaluates additional SVHC candidates.
Small restaurant operators now specify countertop external sealers through specialized foodservice distributors rather than traditional industrial equipment channels. Ghost kitchens in Madrid and Lisbon drive this shift. The pattern compresses manufacturer-to-end-user relationships and elevates distributor technical support obligations.
Vacuum Sealers Market Segmentation
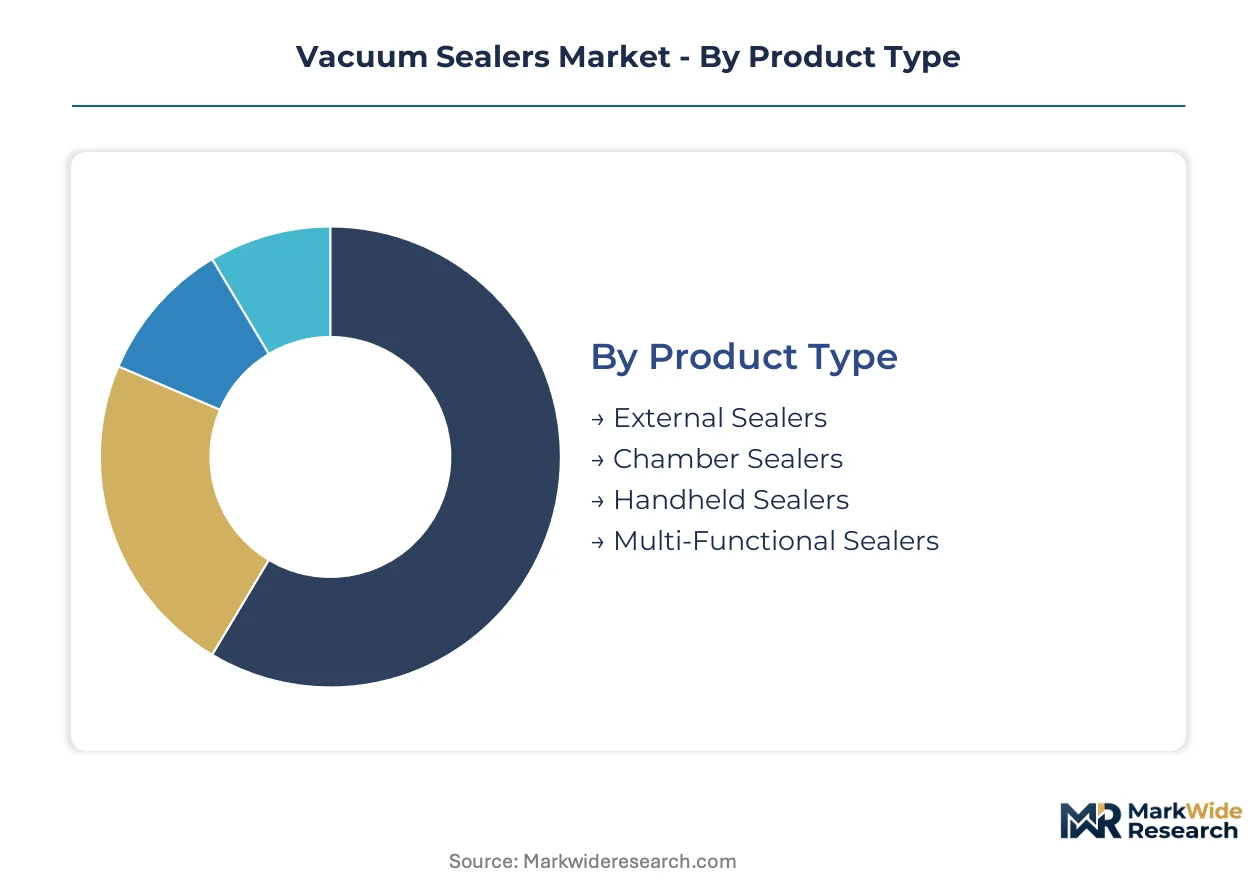
Vacuum sealer segmentation reveals divergent equipment architectures across foodservice, industrial, and residential contexts. Understanding these splits clarifies why chamber sealers dominate processor capital budgets while external units capture ghost kitchen expansion.
Product Type:
Standalone countertop units serve intermittent sealing cycles, while integrated chamber systems embed into continuous packaging lines with conveyor feed mechanisms.
- Chamber Sealers:These systems enclose entire product loads within a vacuum chamber, achieving sub-0.5% residual oxygen through pump capacities reaching 100 m³/h. German dairy and charcuterie operations anchor demand as retailer shelf-life specifications tighten. The EU F-Gas Regulation accelerates pump replacement cycles in these capital-intensive installations.
- External Sealers:Countertop units extract air through snorkel tubes without chamber enclosure, limiting vacuum depth but enabling rapid deployment. Ghost kitchens in Madrid and Lisbon drive fastest expansion as unlicensed food prep facilities prioritize portion control and waste reduction over industrial throughput.
- Handheld Sealers:Battery-powered portable units target sous vide cooking enthusiasts and residential food preservation in urban European households.
- Multi-Functional Sealers:Hybrid platforms combine vacuum extraction with auxiliary functions such as marination acceleration or container sealing for meal-prep subscription services.
Volume placements concentrate in chamber sealers; the faster expansion belongs to external sealers.
End User:
Customer archetypes span from price-sensitive households to validation-heavy pharmaceutical packagers, with procurement sophistication determining equipment specification tiers.
- Food Processors:Industrial-scale operators deploy chamber sealers with seal bar lengths exceeding 1,000 mm for bulk meat, cheese, and prepared meal packaging. Basque and Bavarian equipment clusters supply these installations with ISO 11607 validation for medical-adjacent production lines.
- Restaurants:Small operators now source countertop external sealers through foodservice distributors rather than industrial channels, compressing manufacturer relationships and elevating distributor technical support obligations in Spain and Portugal.
- Households:Residential demand clusters around handheld and compact external units for sous vide cooking and bulk food preservation in suburban German and French markets.
- Retail Stores:In-store packaging stations for meat and cheese counters specify mid-capacity chamber sealers with stainless steel construction for sanitation compliance.
Capital deployment runs heaviest among food processors; restaurant procurement is climbing the fastest as ghost kitchen proliferation reshapes foodservice equipment distribution.
Technology:
Automation intensity separates premium pharmaceutical lines from manual foodservice units, with pneumatic actuation gaining share in high-cycle industrial environments.
- Automatic Sealers:Sensor-integrated lines with PLC control and IoT connectivity command strongest margin pools in pharmaceutical and medical device packaging. Swiss and German contract packagers adopt these platforms fastest, converging hardware sales with recurring predictive maintenance software revenue.
- Electric Sealers:Electromechanical pump systems dominate mid-market food processing with standardized vacuum levels and heat-seal temperature control.
- Pneumatic Sealers:Compressed-air actuation enables faster cycle times in high-throughput meat processing lines where seal bar speed directly impacts line efficiency.
- Manual Sealers:Hand-operated lever mechanisms persist in low-volume retail and artisanal food production where capital constraints outweigh throughput requirements.
Revenue concentration sits with automatic sealers; pneumatic systems are gaining share fastest in fresh protein processing clusters.
Application:
Use-case specificity determines barrier film selection, vacuum depth requirements, and regulatory compliance obligations across food and medical domains.
- Food Preservation:Oxygen exclusion extends shelf life for refrigerated and frozen proteins, cheeses, and prepared meals. REACH-compliant polyethylene-polyamide coextrusions are displacing phthalate-laden PVC formulations in northern Italian and Dutch converter operations.
- Vacuum Packaging:Industrial barrier protection for distribution logistics demands multi-layer films with moisture and gas barriers, particularly in German retail supply chains.
- Sous Vide Cooking:Precision temperature cooking requires heat-stable bags with reliable seals, driving residential external sealer adoption among culinary enthusiasts.
- Storage:Long-term dry goods preservation and bulk ingredient management in commercial kitchens specifies mid-capacity chamber units.
Shipment volumes concentrate in food preservation; vacuum packaging for medical sterile barrier systems follows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyamide resin production clusters in northern Italy and caprolactam feedstock availability in Germany anchor European vacuum sealer supply chains. Industrial packaging automation investment runs heaviest in German-speaking industrial zones. Regulatory pressure from Brussels reshapes equipment refresh cycles across the continent.
Germany
Dairy and charcuterie operations drive chamber sealer deployment as retailer shelf-life specifications tighten. The EU F-Gas Regulation compresses pump replacement timelines for vacuum cooling-integrated lines. Bavarian industrial zones concentrate specialized vacuum pump technician skills, creating service coverage advantages for local equipment vendors.
Italy
Meat processing and prepared meal packaging anchor industrial demand for high-throughput pneumatic sealers. REACH-compliant film reformulation redirects northern Italian converters from phthalate-laden PVC toward polyethylene-polyamide coextrusions. Emilia-Romagna packaging machinery clusters supply chamber systems with seal bar lengths exceeding 1,000 mm.
Spain
Ghost kitchen proliferation in Madrid and Lisbon accelerates countertop external sealer adoption for portion control and waste reduction. ECHA's expanding SVHC candidate list pressures film chemistry compliance timelines. Basque Country equipment fabricators leverage regional manufacturing bases to sustain chamber sealer exports into Latin American meat processing.
Switzerland
Pharmaceutical contract packagers adopt IoT-enabled automatic sealers fastest, converging hardware sales with predictive maintenance software revenue. ISO 11607 validation requirements elevate equipment specifications and service attach rates. Swissmedic oversight extends sterilization validation standards to medical vacuum packaging systems.
Netherlands
Food preservation applications concentrate in Rotterdam-Antwerp logistics corridors serving refrigerated and frozen protein distribution. EMA material contact compliance enforcement shapes food-grade vacuum film procurement. Dutch converters reformulate barrier films toward multilayer structures as REACH restrictions accelerate PVC displacement.
Vacuum Sealers Market Vendor Landscape
Portfolio diversification dominates the current landscape as equipment vendors broaden from pure hardware into integrated film-sealing system offerings. The vendor base stratifies across premium automatic lines, mid-market electromechanical systems, and compact foodservice units. Three archetypes occupy distinct positions: integrated packaging system houses, specialized vacuum technology fabricators, and diversified materials-science conglomerates. Geographic expansion and technology licensing represent the dominant competitive vectors, with Basque and Bavarian manufacturing clusters serving as launch points for Latin American and Asian market penetration.
Within the integrated system tier, ULMA Packaging and MULTIVAC exemplify divergent geographic anchoring strategies. ULMA leverages its Basque manufacturing base to sustain export flows into Latin American meat processing, while MULTIVAC anchors premium automatic lines in German dairy and charcuterie operations. Sealed Air Corporation occupies a materials-science position, competing through Cryovac-branded barrier films integrated with sealing hardware rather than pure equipment specialization.
| Leading Market Players |
|---|
| ULMA Packaging |
| IMA S.p.A. |
| MULTIVAC |
| ORVED S.r.l. |
| JBT Corporation |
| Sealed Air Corporation |
| Henkelman |
| Kenwei |
| Syntegon Technology GmbH |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance mandates are compressing procurement timelines for vacuum cooling-integrated sealing lines, forcing buyers to absorb accelerated equipment refresh costs and elevating capital deployment for compliant pump technologies.
Pricing Analysis
Warranty and service bundling separates premium automatic sealers from mid-tier electromechanical units, with Swiss and German pharmaceutical packagers paying attach rates for predictive maintenance software while food processors negotiate stripped hardware-only contracts. Three-tier pricing structure across premium automatic, standard electric, and economy manual levels reflects ISO 11607 validation grade and pump capacity specifications. Cost compression in mid-tier chamber sealers is intensifying because REACH-compliant film reformulation redirects converter margins toward multilayer polyethylene-polyamide structures. Ghost kitchen operators in Iberia exhibit highest price sensitivity, while pharmaceutical contract packagers show lowest sensitivity due to sterilization validation requirements.
Supply Chain Analysis
Refurbishment flows for vacuum pump components concentrate in Basque and Bavarian industrial zones, where specialized electromechanical repair skills enable circular supply loops for chamber sealer maintenance. Manufacturing gravity centers on Germany, Italy, and Spain, with Emilia-Romagna packaging machinery clusters and Basque Country fabricators anchoring European production. Component sourcing draws from German and Italian high-capacity vacuum pump specialists, exposing buyers to extended lead times. Single-source vulnerability in caprolactam-derived polyamide resin feeds film price volatility. Distribution runs through foodservice distributors for countertop external sealers and direct OEM relationships for industrial chamber systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized vacuum pump technician scarcity in Basque and Bavarian zones props equipment pricing and service attach rates, constraining supply expansion faster than demand growth across pharmaceutical and food processing verticals.
For Market Incumbents: Hedge against margin erosion in mid-tier chamber sealers by securing captive supply of REACH-compliant polyethylene-polyamide films through backward integration into northern Italian converter operations. Counter emerging IoT-enabled predictive maintenance platforms from Swiss competitors by embedding sensor diagnostics into existing automatic lines and unbundling traditional warranty models into recurring software revenue streams. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for compliant vacuum cooling-integrated sealing lines targeting mid-tier German dairy processors facing accelerated replacement cycles. White-space opportunity concentrates in ghost kitchen countertop external sealers across urban Spain and Portugal, where unlicensed food prep facilities prioritize rapid deployment over industrial throughput. Go-to-market angle should leverage specialized foodservice distributor relationships rather than traditional industrial equipment channels. For Investors and Strategic Acquirers: The window for entry favors specialized vacuum technology fabricators with established Basque or Bavarian manufacturing bases and certified ISO 11607 validation capabilities for pharmaceutical adjacencies. Long-term viability hinges on convergence between hardware sales and recurring software revenue from IoT-enabled predictive maintenance platforms. Signal to watch is USDA FSIS HACCP documentation updates mandating vacuum-sealed lot traceability in US meat plants, which would elevate compliance-service revenue pools and reshape competitive positioning for vendors with integrated data capture systems.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Sensor-integrated automatic lines converge operational data with predictive maintenance scheduling in Swiss pharmaceutical clusters. |
| REACH-Compliant Film Backward Integration | Captive supply of polyethylene-polyamide coextrusions secures margin control as ECHA expands SVHC restrictions on phthalate plasticizers. |
| Ghost Kitchen Distribution Partnership | Foodservice distributor relationships compress manufacturer-to-end-user channels for countertop external sealers in Iberia. |
| Vacuum Pump Technician Training Programs | Localized skill development addresses service coverage gaps in Basque and Bavarian industrial zones. |
| USDA FSIS Traceability Alignment | Anticipated HACCP documentation updates for vacuum-sealed meat lots create compliance-service revenue pools. |
Methodological Framework
Independent corroboration across equipment vendor sales data, barrier film converter production records, and pharmaceutical packaging validation databases underwrites the qualitative findings in this study. Primary interviews with vacuum sealer plant engineers, food processor procurement leads, pharmaceutical contract packaging executives, and aftermarket service heads combined with secondary validation from ECHA SVHC candidate list updates, EU F-Gas Regulation compliance filings, and ISO 11607 certification records. Bottom-up equipment shipment tallies and top-down end-use demand estimates triangulate market sizing.
Rate-of-change decomposition across the analysis window segments expansion by chamber sealer, external sealer, handheld sealer, and multi-functional sealer product types; by automatic, electric, pneumatic, and manual technology tiers; and by food processor, restaurant, household, and retail store end users. CAGRs derive from pump capacity deployment trends, film chemistry reformulation timelines, and regulatory compliance cycle analysis. Industry-specific inputs include vacuum cooling system replacement rates under F-Gas Regulation and IoT-enabled predictive maintenance adoption curves in Swiss pharmaceutical clusters.
The model assumes a particular technology adoption path; alternative pathways for IoT-enabled predictive maintenance platforms would alter the outlook if pharmaceutical packagers delay sensor integration investments. Forecasts reflect assumptions about REACH SVHC list expansion timing and USDA FSIS traceability mandate implementation. Practitioners should monitor ECHA candidate list updates, F-Gas Regulation enforcement intensity, and HACCP documentation revision proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Automatic Liquid Filling Market
Packaging Equipment
Cannabis Packaging Equipment Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Filling Equipment Market