
 Sack Tip Stations Market | 2026-2036
Sack Tip Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Sack Tip Stations Market Insights
The EU Green Deal is restructuring procurement criteria for bulk material handling equipment across European food and chemical plants. GEA Group leverages its hygienic design expertise to dominate pharmaceutical-adjacent food installations. AZO GmbH anchors its position through deep integration with pneumatic conveying networks. Palamatic Process specializes in custom-engineered dust containment architectures for high-potency chemical applications.
A sack tip station is a contained discharge unit engineered to empty flexible intermediate bulk containers or sacks while capturing fugitive dust through integrated extraction systems, typically achieving filtration efficiencies down to one micron via cartridge or bag filter assemblies. Its primary purpose is to protect operator health, prevent cross-contamination, and maintain material integrity during manual or semi-automated unloading operations. Fully automatic systems command the largest revenue share due to labor cost arbitrage in high-throughput environments, while mobile sack tips represent the fastest-expanding category as contract manufacturers prioritize flexible floor layouts. Pneumatic systems lead technology adoption where explosion protection and gentle handling converge, though electro-mechanical solutions are gaining traction for their precision in weighed discharge applications.
EMA guidelines on occupational exposure limits and REACH substance restrictions are tightening containment performance requirements for chemical handling installations across Europe, directly elevating specification thresholds for sealed discharge architectures. FDA food safety modernization mandates in the United States are parallelly driving hygienic design investments in dairy and powder ingredient processing. ISO 14120 machinery guarding standards further shape access panel and interlock configurations. Stakeholders must monitor how evolving ATEX classification refinements interact with national implementation timelines to calibrate regional product portfolios.
Market Dynamics
REACH substance restrictions and EMA occupational exposure guidelines are compressing specification cycles for sealed discharge architectures, forcing equipment vendors to revalidate filtration performance against tightening containment thresholds.
Growth Catalysts
- Food safety mandates:FDA food safety modernization directives in the United States are mandating hygienic design investments across dairy and powder ingredient processing facilities.
- Automation economics:Labor cost arbitrage in high-throughput chemical handling environments is accelerating specification of fully automatic sack tip configurations.
- Explosion protection convergence:ATEX classification refinements are elevating demand for pneumatic conveying-integrated discharge systems in solvent-adjacent applications.
Market Restraints
- Stainless steel input volatility:Grade 316L sheet pricing fluctuations compress margin visibility for hygienic-design fabricators serving pharmaceutical-adjacent food installations.
- Filter media supply concentration:Cartridge and bag filter assemblies rely on specialized non-woven suppliers concentrated in German and Swiss industrial clusters.
- Legacy pneumatic infrastructure incompatibility:Existing dilute-phase conveying networks in mature chemical plants resist seamless integration with modern dust-controlled discharge architectures.
Strategic Opportunities
- Contract manufacturing mobility:Mobile sack tip configurations address flexible floor layout requirements among third-party powder processing operators in the United Kingdom and Ireland.
- CSRD procurement alignment:Corporate sustainability reporting directives are elevating energy-efficient pneumatic systems in EU-based food and chemical capital planning.
- Weighed discharge precision:Convergence of electro-mechanical actuation with gravimetric feeding is opening precision ingredient handling applications in bakery and nutraceutical compounding.
Industry Challenges
- Containment validation expertise:Smaller fabricators lack in-house capability to execute SMEPAC-style performance verification for high-potency active pharmaceutical ingredient handling.
- Multi-standard certification timelines:Simultaneous ATEX, CE machinery directive, and FDA food contact compliance extends product launch cycles for cross-border equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sack Tip Stations Market |
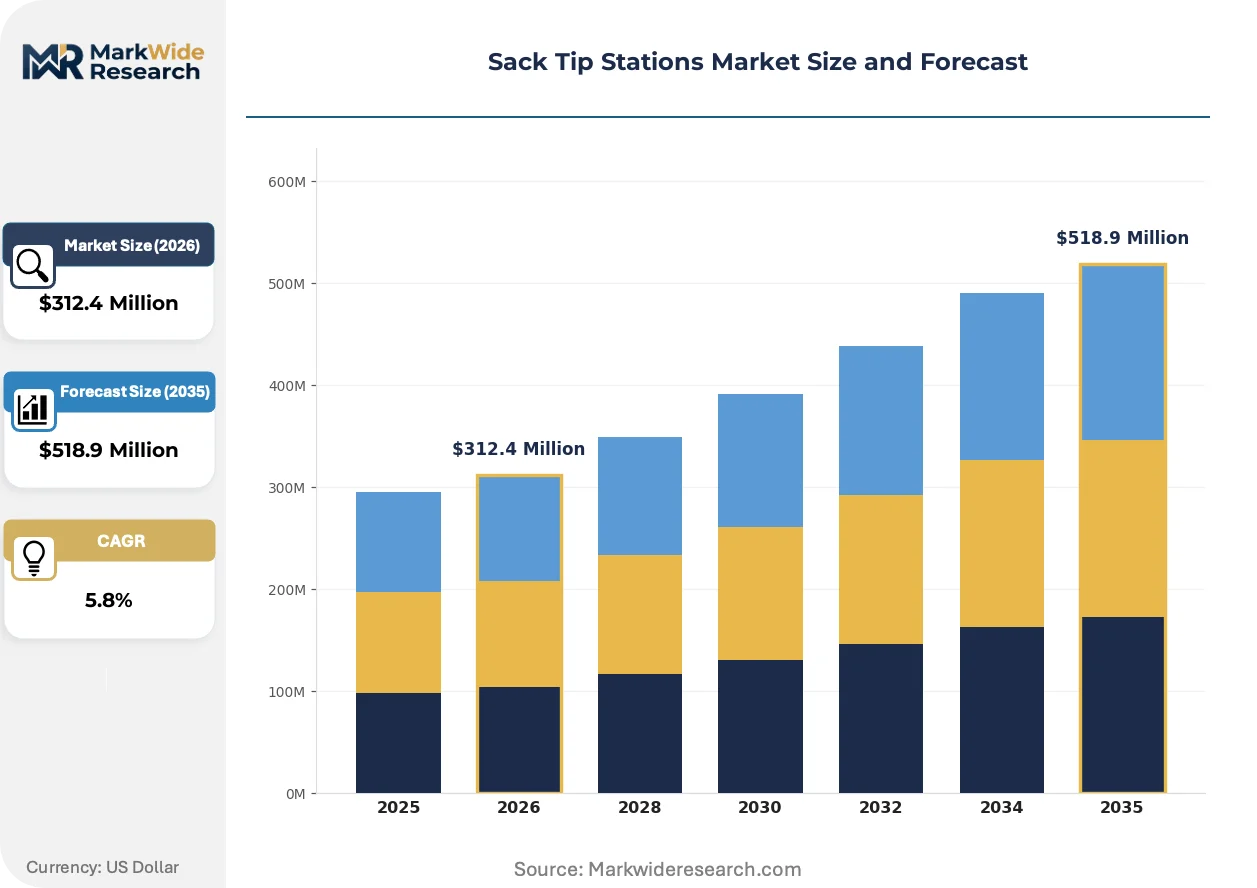
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Sack Tip Stations, Semi-Automatic Units, Fully Automatic Systems, Mobile Sack Tips Technology: Hydraulic Mechanisms, Pneumatic Systems, Electric Drives, Mechanical Lifting, Electro-Mechanical Solutions Application: Food Processing, Chemical Handling, Construction Materials, Agriculture Feed Handling, Waste Management End User: Manufacturers, Bulk Material Handlers, Packaging Plants, Warehousing Facilities, Distribution Centers |
| Companies Covered | GEA Group, AZO GmbH, Palamatic Process, Gericke AG, Russell Finex, Flexicon Corporation, Engelsmann AG, RHEWUM, Tetra Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sack Tip Stations Market Trends and Innovations
Equipment architectures are converging around modular filtration and conveying integration, with vendor R&D prioritizing reconfigurable platforms that compress validation overhead across multiple regulatory jurisdictions.
Integrated cartridge-to-pneumatic transfer systems are unifying dust capture and gentle material transport in a single contained footprint. Pharmaceutical excipient processors in the Netherlands and Belgium are specifying these configurations to eliminate intermediate handling steps. The technology is unifying previously separate capital procurement decisions for discharge and conveying equipment.
REACH authorization requirements for hazardous substance handling are mandating sealed discharge performance documentation across European chemical installations. ECHA substance evaluation timelines are accelerating replacement of open dumping stations with contained architectures in pigment and additive processing. Specialty chemical producers in the Rhine-Ruhr corridor are front-loading capital commitments to preempt authorization bottlenecks.
Service unbundling is fragmenting traditional turnkey supply relationships in the sack tip segment. Powder handling contractors in France are separating equipment purchase from aftermarket filtration media and validation support, compressing initial capex outlays while elongating vendor revenue cycles. This pattern is most visible among mid-scale dairy ingredient processors seeking operational flexibility without captive maintenance capability.
Sack Tip Stations Market Segmentation
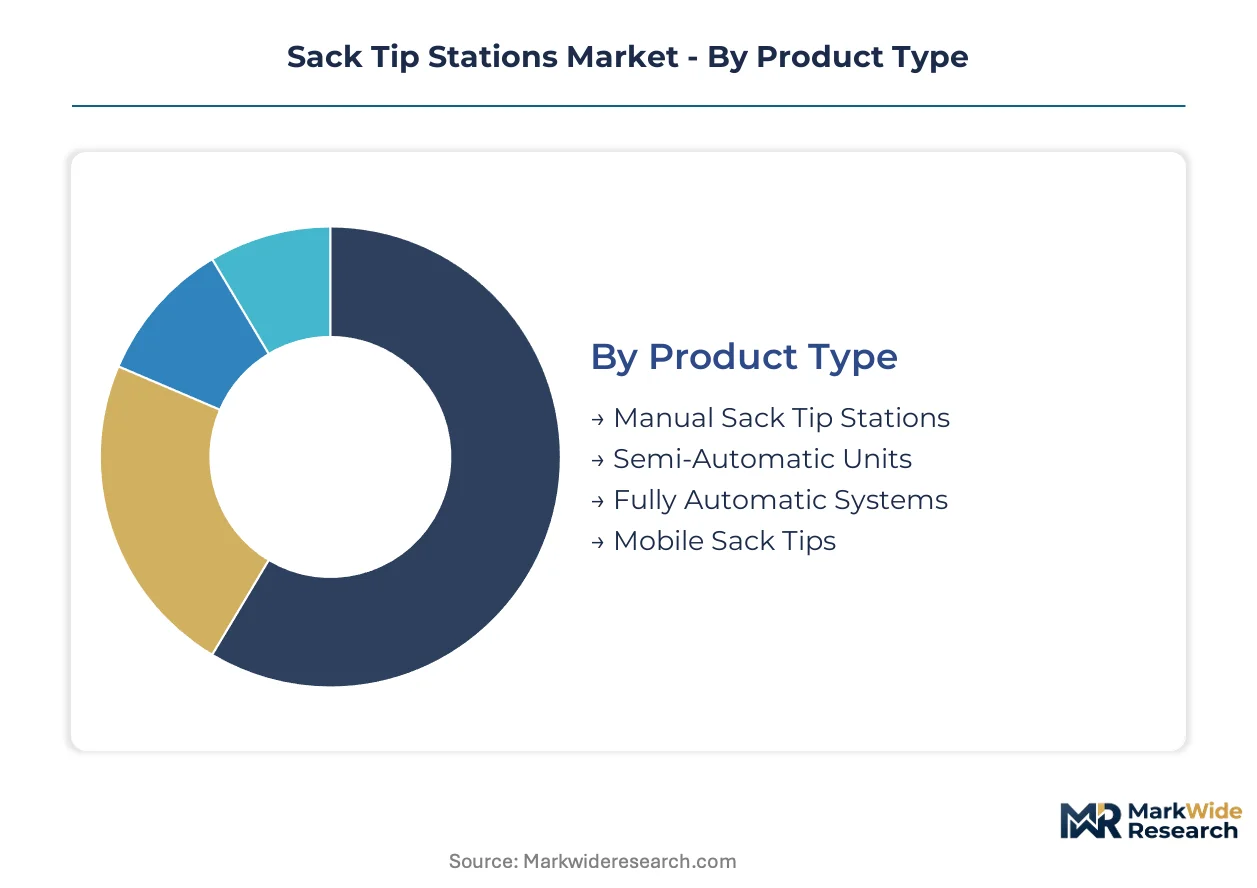
Sack tip stations fragment across four interlocking dimensions that shape procurement decisions. Product automation levels determine labor economics. Technology choices govern explosion safety and precision. Application verticals impose divergent containment standards. End-user scale dictates mobility versus fixed installation trade-offs.
Product Type:
Automation intensity separates capex-heavy permanent installations from flexible operational configurations.
- Fully Automatic Systems:Robotic sack handling with integrated conveying and filtration achieves throughputs exceeding manual stations by an order of magnitude. Chemical manufacturers in Germany's Rhine-Ruhr corridor specify these for solvent-adjacent operations where ATEX compliance and labor minimization converge.
- Mobile Sack Tips:Castor-mounted or forklift-transportable units enable rapid redeployment across contract manufacturing floor plans. Powder handling contractors in the United Kingdom and Ireland prioritize these for multi-product campaigns requiring frequent line reconfiguration.
- Semi-Automatic Units:Operator-assisted sack placement with automated discharge and dust capture balances capital constraints against throughput needs in mid-scale dairy ingredient processing.
- Manual Sack Tip Stations:Basic contained dumping with passive filtration serves low-volume applications in warehousing and small-batch nutraceutical compounding where automation economics fail.
Mature deployment sits with fully automatic systems. Newer deployment is concentrated in mobile sack tips.
Technology:
Actuation methodology determines explosion protection compatibility, energy efficiency, and discharge precision.
- Pneumatic Systems:Compressed-air-driven discharge integrated with vacuum conveying achieves gentle handling for fragile powders while satisfying ATEX Zone 21/22 requirements. Food processors in the Netherlands specify these for dairy and bakery ingredient transfer where dust ignition risks coexist with product integrity demands.
- Electro-Mechanical Solutions:Servo-actuated discharge coupled with gravimetric feeding delivers weighed-batch precision for nutraceutical and pharmaceutical excipient handling. Belgian compounders are adopting these for high-value ingredient dosing where pneumatic transport would cause segregation or attrition.
- Hydraulic Mechanisms:High-force lifting for dense construction materials and mineral aggregates in German quarrying and cement operations.
- Electric Drives:Standard motor-driven discharge for general industrial applications with moderate dust control requirements.
- Mechanical Lifting:Counterweighted or spring-assisted ergonomic aids for manual stations in low-throughput warehousing.
Pneumatic architectures dominate chemical and food installations. Electro-mechanical configurations are climbing the fastest in precision compounding.
Application:
Regulatory intensity and material hazards create divergent specification thresholds across verticals.
- Food Processing:Hygienic design with FDA-compliant surfaces and CIP capability dominates dairy, bakery, and powder ingredient installations. REACH and EU Green Deal procurement criteria are elevating stainless steel specifications and energy-efficient pneumatic integration.
- Chemical Handling:Sealed discharge with SMEPAC-validated containment performance serves high-potency pigments, additives, and active pharmaceutical ingredients. ECHA authorization timelines are accelerating replacement of open dumping in Rhine-Ruhr specialty chemical plants.
- Construction Materials:Heavy-duty abrasion-resistant designs for cement, lime, and mineral aggregate handling in German and French building materials sectors.
- Agriculture Feed Handling:Moderate containment for grain, meal, and premix discharge in compound feed manufacturing.
- Waste Management:Ruggedized units for contaminated sacking and hazardous powder recovery in industrial remediation.
Food processing commands the largest installed base. Chemical handling shows the steepest specification escalation.
End User:
Operational scale and captive versus outsourced processing determine mobility and service bundling preferences.
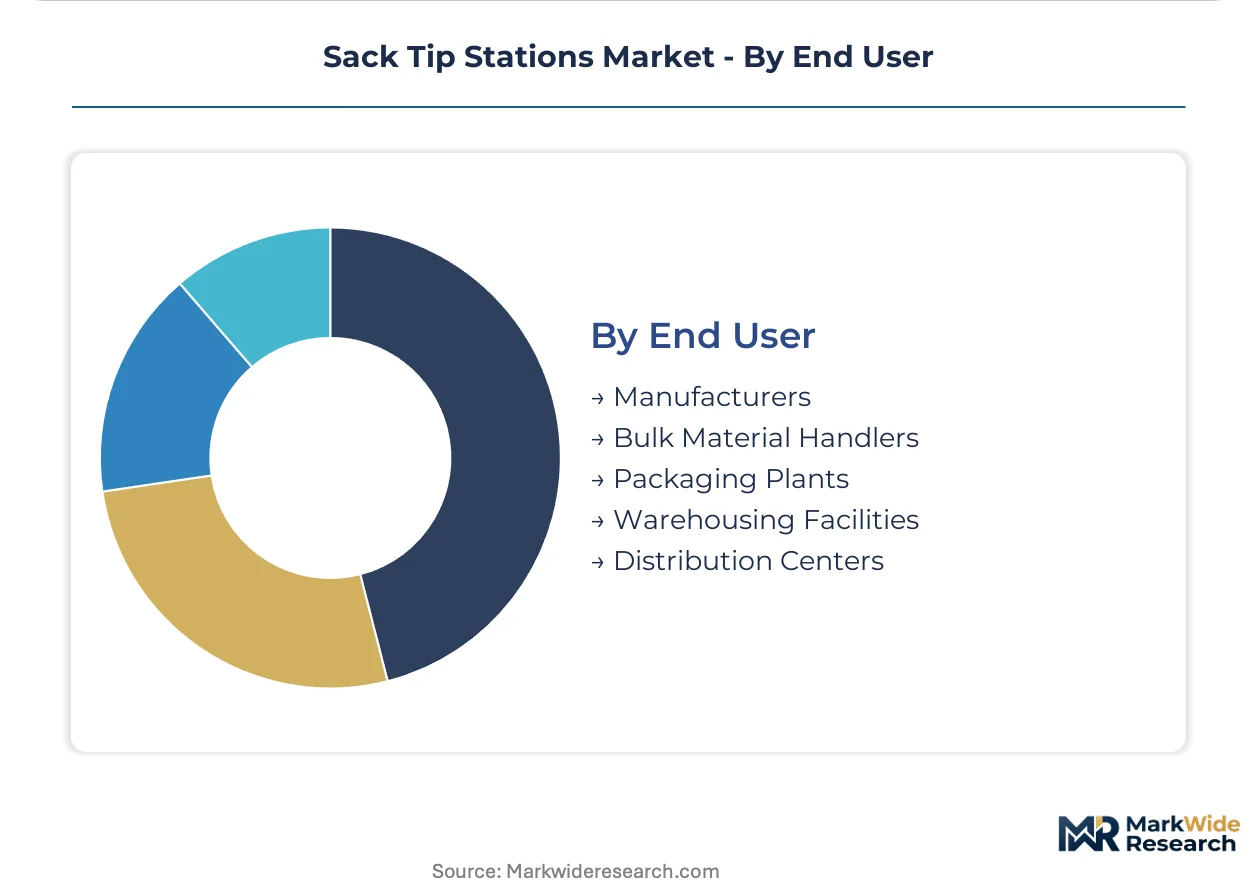
- Manufacturers:Integrated permanent installations with validated containment for pharmaceutical, food, and specialty chemical producers with dedicated product lines.
- Bulk Material Handlers:High-throughput multi-product facilities requiring rapid format changeover and flexible filtration media in port and logistics terminals.
- Packaging Plants:Intermediate discharge stations feeding form-fill-seal and bagging lines in powder ingredient repackaging operations.
- Warehousing Facilities:Basic mobile or fixed units for cross-docking and distribution of bagged goods with minimal processing.
- Distribution Centers:Low-specification manual stations for occasional sack breaking in third-party logistics operations.
Manufacturers anchor premium system demand. Bulk material handlers are expanding most quickly as contract processing fragments traditional captive operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the majority of engineered sack tip systems for European export, while demand concentrates in food processing clusters across the Netherlands and pharmaceutical-adjacent chemical corridors in Belgium. This production-consumption divide shapes regional vendor strategies and service bundling models.
Germany
Specialty chemical producers in the Rhine-Ruhr corridor are front-loading capital commitments for sealed discharge architectures ahead of ECHA authorization bottlenecks. REACH substance restrictions are compressing specification cycles for filtration performance validation. Bavarian hygienic-design fabricators serving pharmaceutical-adjacent food installations face margin pressure from Grade 316L stainless steel input volatility.
Netherlands
Pharmaceutical excipient processors in Rotterdam-Antwerp chemical clusters specify integrated cartridge-to-pneumatic transfer systems to eliminate intermediate handling steps. EMA occupational exposure guidelines are elevating containment performance thresholds for high-potency active pharmaceutical ingredient handling. Dutch dairy and bakery ingredient processors lead pneumatic system adoption where dust ignition risks coexist with product integrity demands.
Belgium
Compounders in the Antwerp-Ghent pharmaceutical corridor are adopting electro-mechanical configurations for high-value ingredient dosing where pneumatic transport would cause segregation or attrition. EU Green Deal procurement criteria are restructuring bulk material handling equipment specifications across food and chemical plants. Belgian nutraceutical manufacturers anchor precision weighed discharge demand.
United Kingdom
Powder handling contractors in the United Kingdom and Ireland prioritize mobile sack tip configurations for multi-product campaigns requiring frequent line reconfiguration. CSRD procurement alignment is elevating energy-efficient pneumatic systems in capital planning decisions. Contract manufacturing mobility requirements are fragmenting traditional turnkey supply relationships.
France
Mid-scale dairy ingredient processors are separating equipment purchase from aftermarket filtration media and validation support, compressing initial capex outlays. ANSM containment guidelines are tightening performance documentation requirements for chemical handling installations. French powder handling contractors are driving service unbundling trends across the regional vendor base.
Sack Tip Stations Market Competitive Landscape
The competitive structure tilts toward engineering-intensive specialists with deep pneumatic conveying integration capabilities. Vendor positioning fragments across three tiers: premium hygienic-design fabricators serving pharmaceutical-adjacent food installations, mid-market modular platform suppliers, and regional service-unbundled operators. Consolidation pressure concentrates among filter media specialists and validation service providers. Dominant competitive moves include backward integration into stainless steel fabrication capacity and geographic expansion through distributor partnerships in contract manufacturing hubs.
Among German-based engineering specialists, GEA Group and AZO GmbH exemplify divergent archetype positioning. GEA Group occupies a position representing hygienic design expertise for pharmaceutical-adjacent food installations. AZO GmbH anchors the pneumatic conveying integration archetype through deep network connectivity. Palamatic Process sits within the custom-engineered dust containment tier, exemplifying specialization for high-potency chemical applications. These three fabricators collectively represent the strategic positioning spectrum visible across the European vendor base.
| Leading Market Players |
|---|
| GEA Group |
| AZO GmbH |
| Palamatic Process |
| Gericke AG |
| Russell Finex |
| Flexicon Corporation |
| Engelsmann AG |
| RHEWUM |
| Tetra Pak |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in southern Germany anchor the engineered equipment tier, channeling captive stainless steel fabrication capacity into pricing discipline that resists commodity erosion. Their ownership structure insulates long-term supply contracts from quarterly margin pressure, while private-equity-rolled filtration specialists in Swiss industrial clusters extract premium positioning through cartridge media concentration.
Pricing Analysis
Margin tightening in hygienic-design tiers reflects Grade 316L stainless steel input volatility and REACH-driven revalidation costs. Three-tier pricing structure across hygienic-certified, standard industrial, and basic containment levels separates pharmaceutical-adjacent food installations from mid-scale dairy processors and warehouse operators. Pricing pressure accelerates in standard industrial tiers as Chinese electro-mechanical competitors enter European distribution networks. Contract manufacturers in the United Kingdom exhibit highest price sensitivity, while Belgian pharmaceutical compounders prioritize containment performance over capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss non-woven filter media suppliers concentrated in Baden-Württemberg and Basel-region industrial clusters. Equipment fabrication draws from Italian stainless steel forming specialists, German pneumatic component manufacturers, and Dutch controls integrators. Tariff exposure on Chinese electro-mechanical actuators threatens cost structures for precision weighing configurations. Distribution runs through OEM-direct specification in pharmaceutical corridors, regional distributor networks in food processing clusters, and unbundled service contracts in contract manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
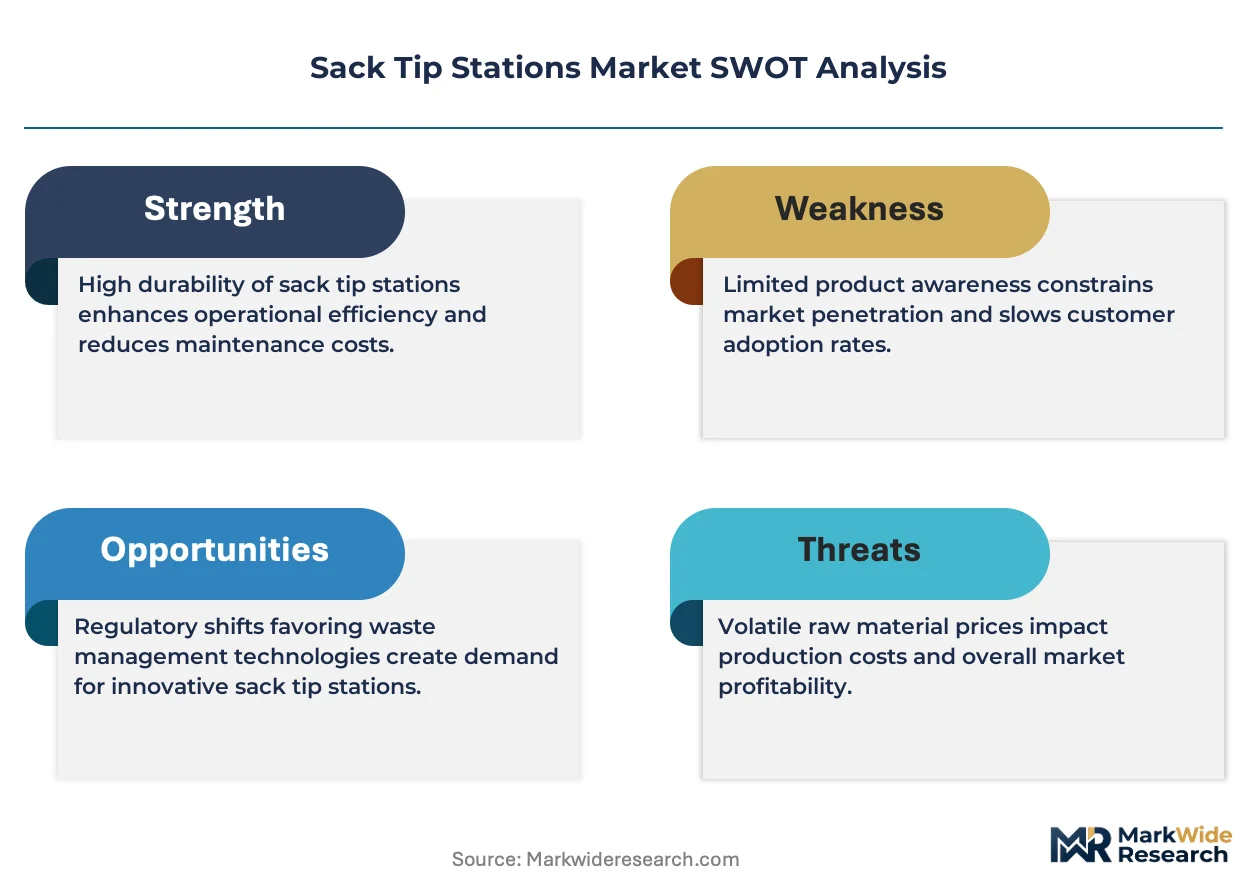
This market is a vertical-integration race where backward control over stainless steel fabrication and filter media supply determines margin durability. Players are pursuing captive production of Grade 316L components and cartridge assemblies to defend pricing power.
For Market Incumbents: Cement market position through backward integration into stainless steel fabrication capacity in Bavaria and Baden-Württemberg. Acquire filtration media specialists in Swiss industrial clusters to preempt supply concentration risks. Invest in simultaneous ATEX-CE-FDA certification pipelines to compress multi-standard validation timelines that delay product launches. For New Entrants and Emerging Players: Launch via mobile sack tip configurations targeting United Kingdom and Ireland contract manufacturing hubs where flexible floor layout requirements fragment incumbent turnkey relationships. Target mid-scale dairy ingredient processors in France seeking unbundled equipment purchase with separated aftermarket filtration support. Enter through electro-mechanical precision dosing architectures for Belgian nutraceutical compounders underserved by pneumatic-centric incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor filtration media specialists with ECHA REACH compliance documentation in German chemical corridors. Long-term viability hinges on containment validation expertise for high-potency active pharmaceutical ingredient handling. Watch EMA occupational exposure guideline revisions as the inflection signal for sealed discharge architecture replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive Grade 316L supply insulates margin from commodity volatility in pharmaceutical-adjacent food installations. |
| Cartridge-to-Pneumatic System Integration | Unified dust capture and gentle transport eliminates intermediate handling for Dutch pharmaceutical excipient processors. |
| Multi-Standard Certification Pipeline Investment | Parallel ATEX, CE machinery directive, and FDA food contact validation compresses cross-border product launch cycles. |
| Mobile Configuration Platform Development | Castor-mounted architectures address flexible floor layout requirements among United Kingdom powder handling contractors. |
| Service Unbundling and Aftermarket Separation | Decoupled filtration media and validation support contracts elongate vendor revenue cycles in French dairy processing. |
Research Methodology
Multi-period observation of ECHA substance authorization timelines, ATEX classification refinements, and stainless steel price indices anchored the trend analysis, supplemented by interviews with plant engineers at German chemical manufacturers, procurement leads at Dutch dairy processors, aftermarket service heads at French powder handling contractors, and technical R&D directors at Belgian pharmaceutical compounders. Secondary validation drew from EMA guideline publications, ECHA substance evaluation databases, EU Green Deal procurement criteria documents, and SEC filings of listed engineering conglomerates. Bottom-up equipment shipment tracking and top-down capital expenditure analysis were triangulated against containment performance specifications.
The input-output matrix framed demand modeling across automation intensity, actuation technology, application vertical regulatory tier, end-user operational scale, and regional procurement policy cluster. Volume and value trajectories were derived from installed base replacement cycles, greenfield capacity announcements, and REACH-driven specification escalations throughout the projection horizon. Industry-specific forecast inputs included ECHA authorization bottleneck projections and CSRD-aligned energy efficiency procurement mandates.
REACH substance restriction acceleration, EMA occupational exposure limit revisions, and stainless steel commodity price volatility are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory implementation timelines and capital commitment patterns among Rhine-Ruhr specialty chemical producers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Loading Spout Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Cannabis Packaging Equipment Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Powder Filling Equipment Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Packaging Equipment Market