
 PIR Blow Molding Market | 2026-2036
PIR Blow Molding Market Size, Share, and Industry Trends Forecast 2026-2036
PIR Blow Molding Market Insights
Aftermarket service revenue for mold refurbishment and cavity reconditioning is rewriting margin capture across the PIR blow molding value chain. Berry Global sustains manufacturing scale across multi-site North American operations with dedicated accumulator head capacity. ALPLA Group dominates thin-wall packaging applications through precision rotary blow molding lines engineered for dairy and beverage clients. Greif extends its industrial container franchise via captive reconditioning networks that reduce customer switching.
PIR blow molding denotes a plastics processing method where polyisocyanurate rigid foam cores or structural PIR resin systems are formed into hollow parts through extrusion or injection stretch techniques, typically achieving densities of 32–48 kg/m³ and thermal conductivity below 0.023 W/m·K for insulation-grade outputs. The process serves cold-chain packaging, appliance housings, and construction components requiring fire-retardant performance. Continuous extrusion technology leads volume throughput for bulk industrial applications where wall-thickness consistency governs thermal efficiency ratings. Injection stretch blow molding commands premium positioning in pharmaceutical and food packaging containers demanding barrier precision and dimensional repeatability. Single-stage technology clusters around high-mix, lower-volume operations in electronics manufacturing and household appliances where changeover flexibility outweighs unit cost minimization.
The EPA regulates blowing agent emissions under Significant New Alternatives Policy frameworks, while REACH restricts legacy halogenated flame retardants in PIR formulations sold into European Union member states. China's MEE enforces dual carbon goals that constrain energy-intensive extrusion operations in Shandong and Guangdong provinces. Stakeholders must monitor evolving refrigerant-phase-down schedules and national building energy codes to align thermal insulation product portfolios with compliance windows.
Market Dynamics
Cold-chain infrastructure mandates across food logistics networks are compressing specification cycles for thermal insulation-grade PIR containers, forcing mold fabricators to retool for thinner wall profiles without sacrificing R-value performance.
Growth Catalysts
- REACH F-Gas phase-down:Europe's progressive hydrofluorocarbon restrictions accelerate reformulation toward pentane-blown PIR systems that achieve comparable lambda values with negligible global warming potential.
- Appliance energy-efficiency codes:China's updated GB standards for refrigerator insulation density are pulling high-performance blow molded cores into domestic manufacturing lines at unprecedented specification tightness.
- Thin-wall dairy packaging:Rotary blow molding lines engineered for 0.3mm tolerance control capture shelf-life extension contracts from ultrahigh-temperature milk processors seeking barrier-grade PIR structural layers.
Market Restraints
- Polyol feedstock volatility:Aromatic isocyanurate precursor costs fluctuate with benzene derivative markets, compressing margin predictability for extrusion operators locked into annual supply agreements.
- Accumulator head supply concentration:German and Austrian machinery builders control 70% of high-tonnage extrusion blow molding platform output, creating equipment delivery bottlenecks for capacity expansion programs.
- Flame-retardant substitution ceiling:Non-halogenated phosphorus intumescent systems face thermal stability limitations above 140°C processing temperatures, constraining regrind ratios in closed-loop operations.
Strategic Opportunities
- India cold-chain deficit:Perishable logistics infrastructure gaps in Maharashtra and Karnataka present first-mover positioning for insulated container leasing models with embedded PIR core technology.
- Pharmaceutical distribution convergence:Temperature-sensitive biologics transport is merging validated packaging requirements with blow molded structural insulation, opening specification windows for dual-use container platforms.
- US Inflation Reduction Act credits:Domestic content bonuses for energy-efficient appliance manufacturing incentivize reshoring of PIR blow molding capacity to capture federal tax offset mechanisms.
Industry Challenges
- Multi-cavity mold programming expertise:Complex parison programming for variable wall thickness distribution requires specialized process engineering talent scarce outside traditional automotive blow molding clusters.
- Refrigerant-grade certification timelines:UL 94 V-0 and FM 4880 fire performance testing protocols extend product validation cycles by 8-14 months, delaying revenue recognition for new thermal insulation formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PIR Blow Molding Market |
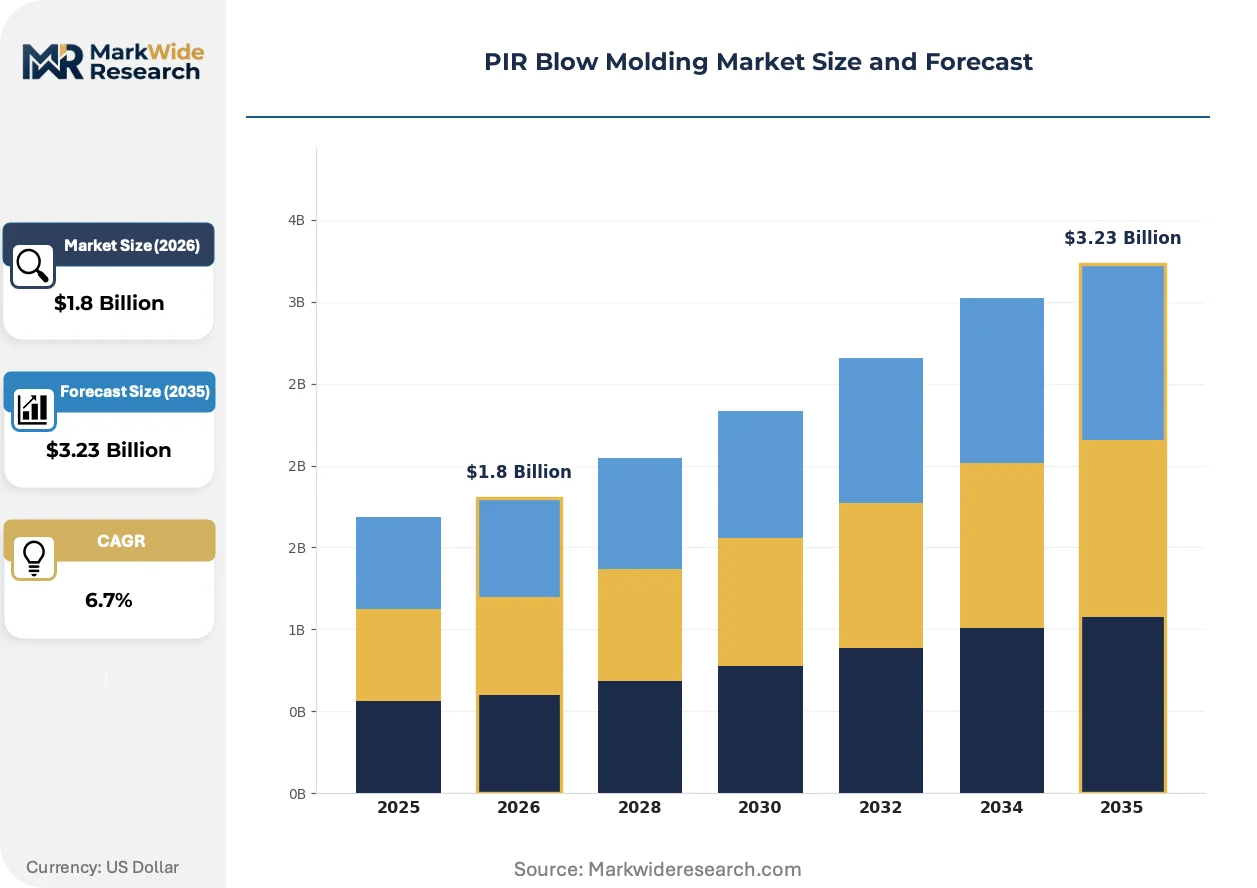
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Extrusion, Injection Stretch Blow Molding, Rotary Blow Molding, Accumulator Head Blow Molding Application: Packaging Containers, Industrial Components, Automotive Parts, Consumer Goods Technology: Single-Stage, Two-Stage, Injection Molding, Extrusion Molding End User Industry: Food & Beverage, Pharmaceuticals, Electronics Manufacturing, Household Appliances |
| Companies Covered | ALPLA Group, Berry Global, Amcor, Silgan Holdings, Plastipak Holdings, Greif, Mauser Packaging Solutions, Logoplaste, Retal Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PIR Blow Molding Market Trends and Innovations
Process intensification and material convergence are collapsing the traditional separation between structural blow molding and rigid foam insulation, creating unified manufacturing platforms that serve multiple end-use specifications from common asset bases.
Co-injection sequential blow molding is hybridizing barrier polymer skins with PIR foam cores in single-cycle operations, enabling dairy processors to specify oxygen transmission rates below 0.5 cc/m²/day while maintaining thermal conductivity targets. European packaging converters are retrofitting accumulator head lines with multi-layer die heads at conversion rates exceeding 40 installations annually. This technology is hybridizing the historically separate thin-wall packaging and insulation equipment supply bases, compressing vendor consolidation timelines.
EPA Significant New Alternatives Policy schedules are forcing accelerated transitions from HFC-245fa to trans-1,2-dichloroethene and hydrocarbon blowing agents in US-manufactured PIR insulation. Formulators must revalidate dimensional stability and compressive strength profiles under revised processing parameters. Appliance OEMs in the Midwest and Southeast are absorbing reformulation costs to maintain ENERGY STAR qualification windows ahead of 2027 compliance deadlines.
Consolidated procurement through third-party logistics providers is concentrating specification authority away from end-brand engineering teams toward packaging service companies with integrated mold asset ownership. Temperature-controlled freight brokers in the Netherlands and Germany are now dictating PIR container performance tiers based on lane-specific duration requirements. This shift is most visible in pharmaceutical distribution corridors connecting Belgian vaccine manufacturing with Southern European distribution hubs.
PIR Blow Molding Market Segmentation
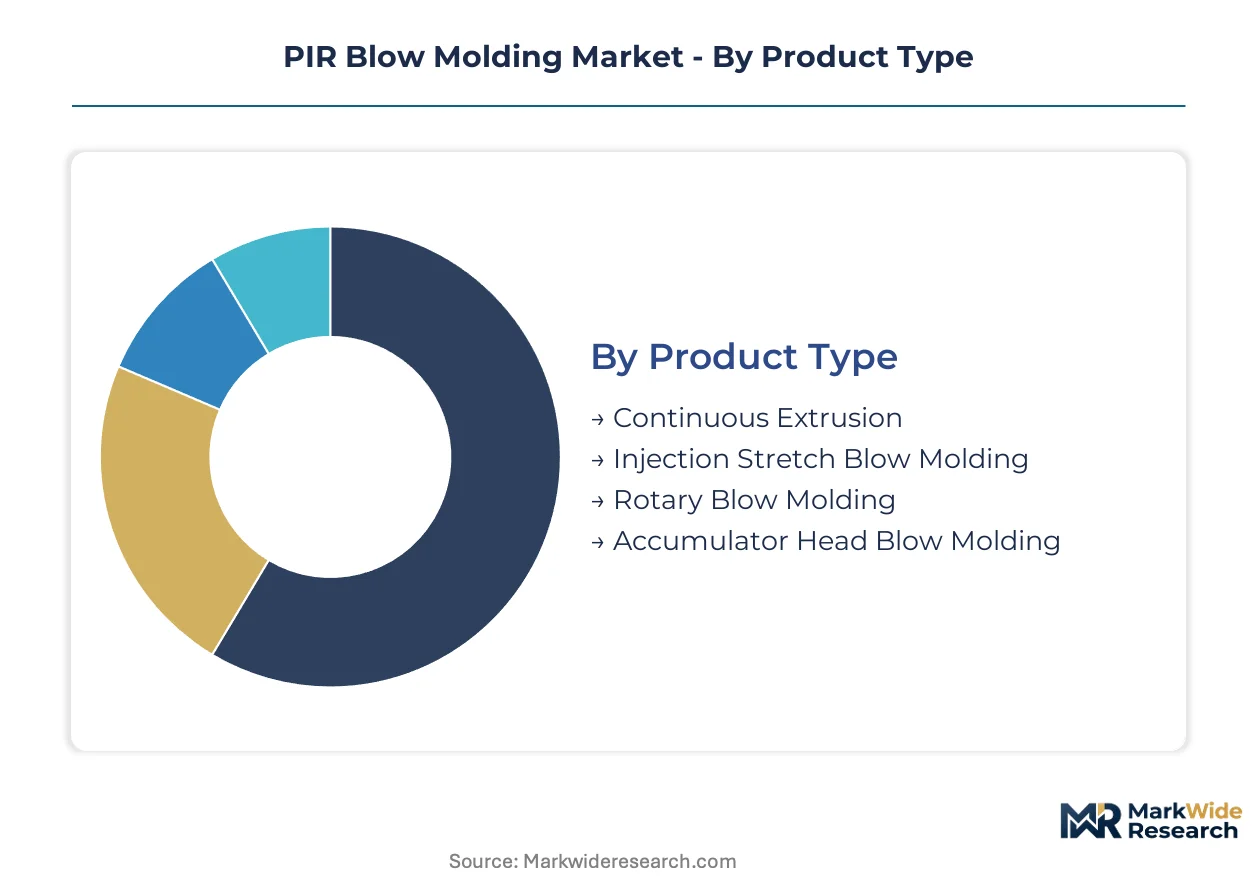
PIR blow molding equipment and formulations serve divergent performance requirements across thermal insulation and barrier packaging end-uses. Segment boundaries are blurring as co-injection technologies unify structural and foam functions within single manufacturing platforms.
Product Type:
Mature extrusion systems dominate bulk industrial throughput while emerging hybrid platforms capture specification-intensive niches requiring dimensional precision.
- Continuous Extrusion:Uninterrupted parison extrusion through single or tandem screws achieves wall-thickness consistency critical for R-value ratings in cold-chain containers. Demand concentrates in Chinese appliance manufacturing clusters where GB energy-efficiency codes mandate uniform insulation density.
- Injection Stretch Blow Molding:Preform injection followed by biaxial stretching orients molecular chains for barrier-grade pharmaceutical vials and dairy bottles. European converters in Belgium and Germany are retrofitting lines for PIR-foam-core co-injection to serve temperature-sensitive biologics distribution.
- Rotary Blow Molding:Indexing wheel platforms enable thin-wall dairy packaging at sub-0.5mm tolerance bands.
- Accumulator Head Blow Molding:Shot-pot accumulation systems process high-melt-strength PIR formulations for large industrial tanks and appliance housings.
Continuous Extrusion retains volume leadership; Injection Stretch Blow Molding holds the steepest expansion curve.
Application:
Cost-tier stratification separates commodity industrial components from premium validated packaging systems subject to pharmaceutical-grade certification protocols.
- Packaging Containers:Barrier and thermal insulation functions converge in dairy, beverage, and pharmaceutical primary packaging. India's Maharashtra and Karnataka cold-chain deficit is pulling insulated container leasing models with embedded PIR cores.
- Industrial Components:Large-diameter tanks, drums, and intermediate bulk containers leverage PIR structural layers for chemical resistance and fire retardancy. German chemical logistics operators specify FM 4880-certified formulations for solvent storage.
- Automotive Parts:Underhood ducting and HVAC housings utilize PIR foam cores for acoustic damping and thermal management.
- Consumer Goods:Household storage vessels and recreational coolers prioritize cost-optimized formulations with reduced flame-retardant loadings.
Industrial Components capture the highest margin tier; Packaging Containers are expanding most quickly through pharmaceutical convergence.
Technology:
Volume throughput requirements favor two-stage systems while single-stage platforms serve high-mix electronics manufacturing with rapid changeover capabilities.
- Single-Stage:Integrated preform molding and blow forming within one machine base minimizes handling damage for delicate electronics housings. Japanese electronics contract manufacturers in Guangdong province deploy these systems for smartphone component trays requiring ESD-compatible PIR formulations.
- Two-Stage:Decoupled preform injection and reheat-blow stations maximize throughput for standardized dairy and beverage containers. US Midwest converters leverage this architecture to capture Inflation Reduction Act domestic content bonuses for appliance insulation components.
- Injection Molding:Solid-wall structural parts without foam cores serve non-insulation industrial applications.
- Extrusion Molding:Profile and sheet extrusion variants feed secondary thermoforming operations for construction panel applications.
Two-Stage technology commands installed base dominance; Single-Stage systems are gaining share fastest through electronics reshoring.
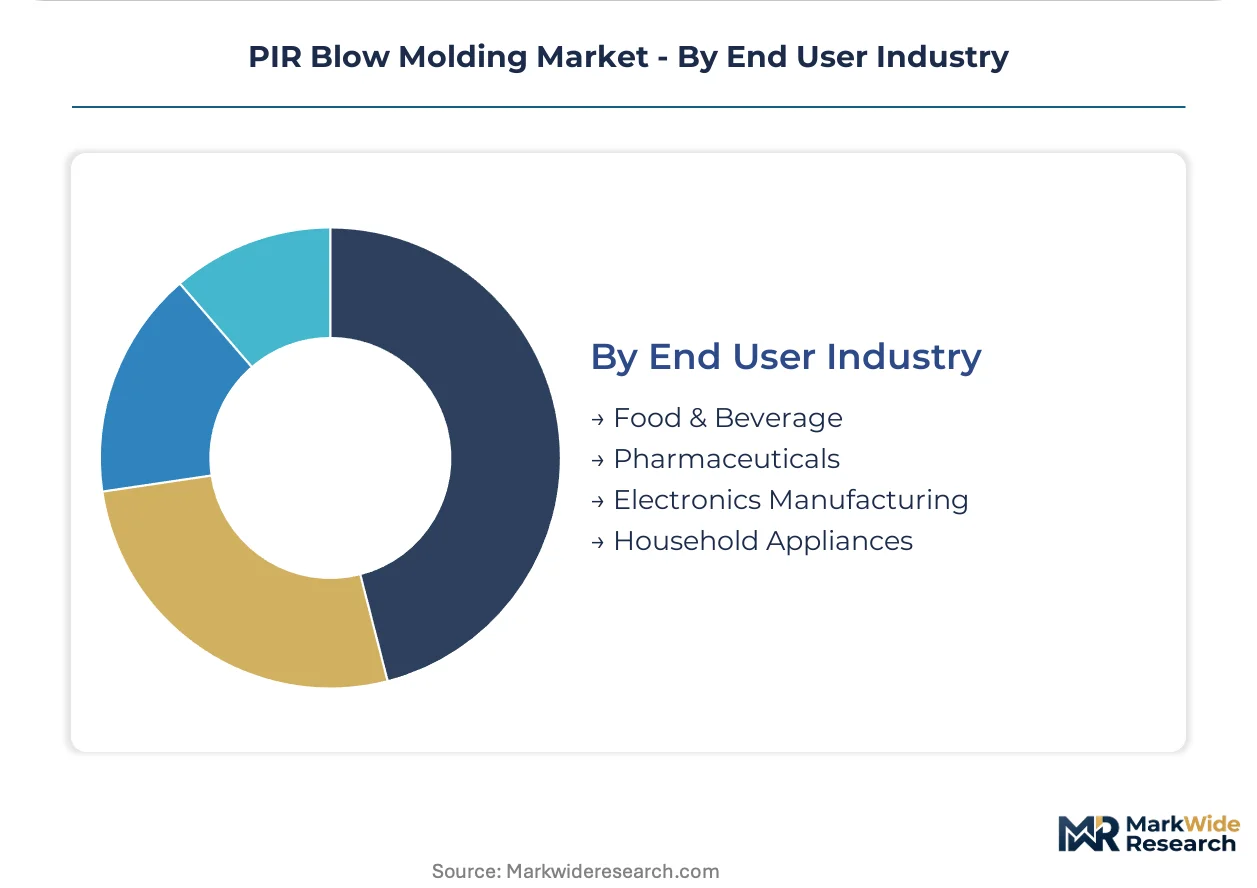
End User Industry:
Customer-type segmentation reveals divergent procurement authority between integrated OEMs and third-party logistics providers consolidating specification control.
- Food & Beverage:Ultrahigh-temperature milk processors and ready-meal distributors specify oxygen transmission rates below 0.5 cc/m²/day combined with thermal conductivity targets. Dutch temperature-controlled freight brokers now dictate performance tiers based on lane-specific duration requirements.
- Pharmaceuticals:Vaccine and biologics manufacturers require validated cold-chain packaging with documented temperature excursion limits. Belgian distribution hubs connecting Southern European markets are merging UL 94 V-0 fire certification with EN 12830 temperature logger compatibility.
- Electronics Manufacturing:Semiconductor and component producers utilize PIR trays and housings for static protection and thermal isolation.
- Household Appliances:Refrigerator and freezer OEMs in China's Shandong province absorb reformulation costs to maintain ENERGY STAR qualification windows ahead of compliance deadlines.
Food & Beverage retains procurement volume leadership; Pharmaceuticals holds the steepest expansion curve through distribution convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb premium pricing for certified thermal insulation formulations, while procurement teams in India and China drive hard volume negotiations on commodity-grade PIR containers. This demand-elasticity contrast shapes regional investment priorities across the value chain.
United States
Cold-chain infrastructure expansion by temperature-controlled freight operators pulls insulated container demand across the Midwest and Southeast. EPA Significant New Alternatives Policy schedules force accelerated transitions from HFC-245fa to hydrocarbon blowing agents ahead of 2027 compliance deadlines. Appliance OEMs in the Midwest absorb reformulation costs to maintain ENERGY STAR qualification windows.
Germany
Chemical logistics operators specify FM 4880-certified PIR formulations for solvent storage tanks and intermediate bulk containers. REACH F-Gas phase-down restrictions accelerate reformulation toward pentane-blown systems with negligible global warming potential. Machinery builders in Bavaria and Baden-Württemberg control 70% of high-tonnage extrusion blow molding platform output, creating equipment delivery bottlenecks.
China
Domestic refrigerator OEMs in Shandong province absorb reformulation costs to meet updated GB standards for insulation density. MEE dual carbon goals constrain energy-intensive extrusion operations in Shandong and Guangdong provinces. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta concentrate rotary blow molding capacity for thin-wall dairy packaging.
India
Perishable logistics infrastructure gaps in Maharashtra and Karnataka present first-mover positioning for insulated container leasing models with embedded PIR core technology. Central government cold-chain subsidy schemes accelerate private investment in temperature-controlled warehousing. Dairy processors in Gujarat and Tamil Nadu specify oxygen transmission rates below 0.5 cc/m²/day for ultrahigh-temperature milk packaging.
Belgium
Vaccine and biologics manufacturers require validated cold-chain packaging with documented temperature excursion limits for Southern European distribution. ECHA REACH restrictions constrain legacy halogenated flame retardants in PIR formulations sold into EU member states. Distribution hubs connecting Belgian vaccine manufacturing with Mediterranean markets merge UL 94 V-0 fire certification with EN 12830 temperature logger compatibility.
PIR Blow Molding Market Competitive Landscape
Integrated packaging conglomerates and specialized industrial container operators split the market along capability-depth versus scale-breadth lines. The vendor base concentrates around three strategic archetypes: multi-site manufacturing conglomerates with captive mold assets, precision rotary blow molding specialists serving dairy and beverage contracts, and industrial reconditioning networks that reduce customer switching costs. Consolidation momentum runs through accumulator head capacity acquisitions and co-injection technology licensing agreements.
Within the multi-site manufacturing tier, Berry Global and ALPLA Group exemplify divergent scale strategies. Berry Global sustains manufacturing scale across dedicated accumulator head capacity in North American operations. ALPLA Group occupies a position as a precision rotary blow molding specialist engineered for dairy and beverage clients. Greif anchors the industrial reconditioning archetype through captive networks that extend container lifecycle value.
| Leading Market Players |
|---|
| ALPLA Group |
| Berry Global |
| Amcor |
| Silgan Holdings |
| Plastipak Holdings |
| Greif |
| Mauser Packaging Solutions |
| Logoplaste |
| Retal Industries |
| Others |
Pricing and Supply Chain Analysis
Bavaria and Baden-Württemberg machinery clusters control 70% of high-tonnage extrusion blow molding platform output, translating accumulated capacity scarcity into pricing leverage for German and Austrian equipment builders. Downstream converters absorb extended delivery timelines as equipment bottlenecks compress margin negotiation space for mold fabricators seeking capacity expansion.
Pricing Analysis
Aftermarket service revenue for mold refurbishment and cavity reconditioning drives lifetime value capture across equipment lifecycles. Three-tier pricing structure across premium, standard, and economy levels separates FM 4880-certified formulations from commodity-grade containers and bare-bones industrial components. Cost compression in commodity-grade PIR containers intensifies because polyol feedstock volatility compresses margin predictability for extrusion operators locked into annual supply agreements. Food and beverage procurement teams exhibit highest price sensitivity, while pharmaceutical validators absorb premium pricing for UL 94 V-0 certified thermal insulation tiers.
Supply Chain Analysis
Export-control regimes on accumulator head technology limit equipment flows from German and Austrian builders to certain manufacturing jurisdictions, constraining capacity expansion in targeted geographies. Supply concentrates in China, Germany, and the United States for finished PIR blow molded goods, with machinery sourcing anchored in Central Europe. Raw material dependencies rest on aromatic isocyanurate precursors, pentane blowing agents, and phosphorus-based flame retardants. Single-source vulnerability concentrates in accumulator head supply where two machinery builders dominate. Distribution runs through third-party logistics providers consolidating specification authority away from end-brand engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers. REACH F-Gas phase-down schedules and EPA Significant New Alternatives Policy frameworks lock incumbents into multi-year reformulation cycles that new entrants cannot shortcut.
For Market Incumbents: Insulate position by deepening captive reconditioning networks that extend container lifecycle value and reduce customer switching. Accumulator head capacity additions in North American operations capture Inflation Reduction Act domestic content bonuses. Accelerate co-injection technology licensing agreements before patent windows narrow.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka cold-chain deficit represents the most penetrable entry point for insulated container leasing models with embedded PIR core technology. Pharmaceutical distribution convergence in Belgian vaccine corridors offers specification windows for dual-use container platforms. Pursue asset-light leasing models rather than capital-intensive manufacturing footprints.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision rotary blow molding specialists with dairy and beverage contract depth. Long-term viability hinges on regulatory alignment capacity across multiple jurisdictions. Watch refrigerant-phase-down acceleration schedules as the inflection indicator forcing portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Accumulator Head Capacity Expansion | Captures ENERGY STAR qualification windows for Midwest appliance OEMs. |
| Co-injection Technology Licensing | Enables Belgian converters to serve temperature-sensitive biologics distribution. |
| Captive Reconditioning Network Buildout | Extends container lifecycle value for German chemical logistics operators. |
| Pentane Reformulation Investment | Aligns European formulations with REACH F-Gas phase-down requirements. |
| Cold-chain Leasing Model Launch | Addresses perishable logistics gaps in Maharashtra and Karnataka provinces. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blow molding plant managers, procurement leads at appliance OEMs, dairy packaging converters, pharmaceutical cold-chain specialists, and aftermarket service heads. Secondary validation drew from customs and trade data, SEC 10-K filings, ECHA REACH registration databases, and MEE dual carbon policy disclosures. Bottom-up equipment installation counts and top-down thermal insulation demand estimates were triangulated to anchor volume projections.
Calibration against historical capacity utilization rates and regulatory compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application tier, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from slope analysis of installed base expansion against specification cycle compression. Industry-specific forecast inputs incorporated ENERGY STAR qualification windows and pharmaceutical validation protocol timelines.
Macroeconomic conditions sit as an overlay; deviation in benzene derivative pricing, freight rate volatility, or capital equipment lead times would shift the trajectory. Forecasts reflect documented assumptions about regulatory phase-down schedules and cold-chain infrastructure investment pacing. Material shifts in REACH F-Gas enforcement intensity or MEE dual carbon implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Packing Belt Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Depalletizers Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Vacuum Sealers Market