
 Self-Tanning Products Market | 2026-2036
Self-Tanning Products Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Tanning Products Market Analysis
REACH is pivoting the cost-of-entry calculus for self-tanning formulations, forcing manufacturers to reformulate around restricted dihydroxyacetone concentrations and preservative systems. LOréal SA leverages its dermatological research infrastructure to sustain compliance leadership across European markets. Bondi Sands Pty Ltd anchors its competitive position through salon-grade product specialization that navigates divergent regulatory thresholds between jurisdictions.
Self-tanning products comprise topical cosmetic formulations centered on dihydroxyacetone, a sugar-derived compound that reacts with amino acids in the stratum corneum to produce melanin-mimicking coloration without ultraviolet exposure, typically achieving visible results within two to four hours and lasting five to seven days. The primary commercial purpose spans cosmetic bronzing, seasonal skin-tone adjustment, and dermatologist-recommended sunless alternatives for UV-sensitive populations. Lotions occupy the largest volume share due to their accessibility and moisturizing dual-function, while mousses capture accelerating growth through their streak-resistant application and faster drying profiles that appeal to time-constrained consumers. Spray tan booths concentrate margin pools in professional service channels where appointment-based revenue models command premium pricing over retail equivalents.
The US FDA oversees cosmetic labeling and color additive approvals that constrain self-tanning product claims and ingredient disclosures, while the EU ECHA enforces REACH substance restrictions that periodically delist common bronzing agents. These frameworks collectively elevate R&D expenditure for multi-jurisdictional brands and create competitive moats for companies with dedicated regulatory affairs capacity. Stakeholders must monitor pending ingredient hazard reclassifications that could force portfolio-wide reformulations and recalibrate geographic prioritization based on divergent compliance timelines.
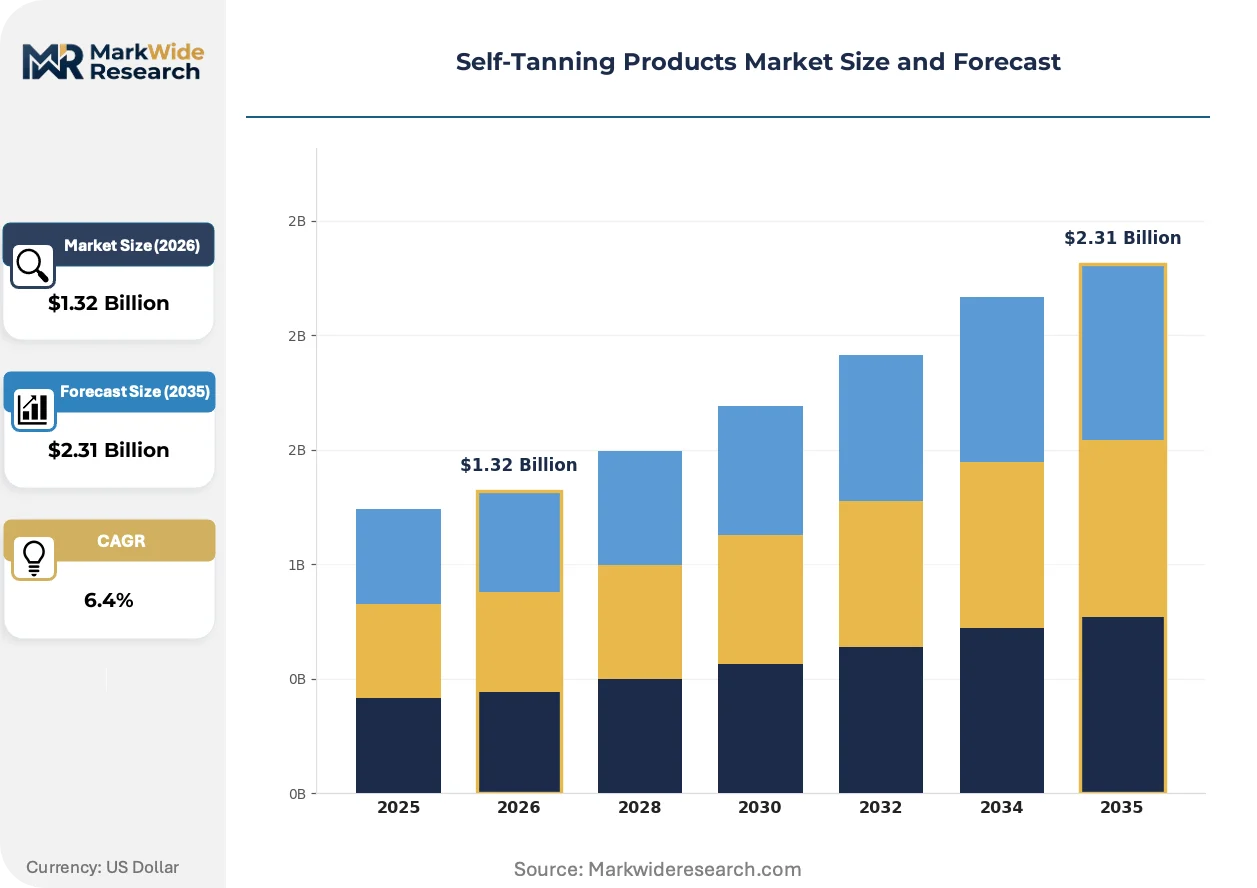
Market Dynamics
REACH substance restrictions on dihydroxyacetone concentrations and preservative systems are forcing manufacturers to rebuild formulation pipelines, elevating R&D spend as the primary barrier to market participation.
Growth Catalysts
- EU REACH compliance infrastructure:Dedicated regulatory affairs capacity creates competitive moats for established manufacturers while raising acquisition costs for new entrants.
- Professional salon channel expansion:Appointment-based revenue models in spray tan booths command premium pricing over retail equivalents and sustain margin pools.
- Influencer-driven beauty culture in the United States:Year-round tanning preferences sustain category momentum through content marketing and social proof mechanisms.
Market Restraints
- DHA supply concentration:Sugar-derived dihydroxyacetone production clusters among specialty chemical suppliers, exposing formulators to input cost volatility.
- FDA color additive approval timelines:Cosmetic labeling constraints delay new bronzing agent commercialization and compress innovation cycles.
- Natural sun exposure substitution:Seasonal UV tanning persists as a zero-cost alternative, capping price elasticity for premium self-tanning formulations.
Strategic Opportunities
- Mousse format acceleration:Streak-resistant application and faster drying profiles capture time-constrained consumers shifting from traditional lotions.
- Dermatologist-recommended sunless alternatives:UV-sensitive populations represent an underpenetrated clinical channel for medical-grade formulations.
- Dual-function moisturizing hybrids:Convergence of cosmetic bronzing with skincare actives opens premium positioning beyond coloration alone.
Industry Challenges
- Reformulation cycle compression:Pending ECHA hazard reclassifications force portfolio-wide adjustments with compressed compliance timelines.
- Multi-jurisdictional certification complexity:Divergent FDA and REACH disclosure requirements strain quality assurance functions and delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Tanning Products Market |
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotions, Sprays, Mousses, Gels Application Method: Manual, Airbrush, Spray Tan Booths, Home Use Skin Type: All Skin Types, Sensitive Skin, Oily Skin, Dry Skin Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Salons |
| Companies Covered | Bondi Sands Pty Ltd., Clarins Sdn Bhd, COOLA LLC, Coty Inc., Crown Laboratories Inc., Johnson and Johnson Services Inc., Kao Corp., LOréal SA, PZ Cussons Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Tanning Products Market Emerging Trajectories
Formulation chemistry and application technology are converging to address the core consumer pain point of uneven color development, while regulatory pressure accelerates investment in alternative bronzing mechanisms.
Micro-encapsulation technology is automating controlled-release delivery of dihydroxyacetone, extending color longevity from five days toward ten-day wear. Premium cosmetic brands are adopting these systems to justify tiered pricing separation from standard formulations. The structural consequence is compressing replenishment frequency and forcing volume-dependent brands to reformulate for retention.
REACH substance restrictions are tightening permissible preservative concentrations in cosmetic formulations, compelling manufacturers to validate alternative stabilization chemistries. ECHA's periodic delisting of common bronzing agents elevates R&D expenditure for multi-jurisdictional brands. European formulators are responding fastest, leveraging existing dermatological research infrastructure to pre-validate next-generation ingredients.
Social commerce platforms are displacing traditional retail discovery for self-tanning products, with tutorial-driven purchasing concentrated among 18-34 demographic cohorts. Direct-to-consumer subscription models are replacing intermittent drugstore replenishment in the United States, where influencer content sustains year-round category engagement. This channel rotation compresses brand loyalty cycles and elevates content production to a core competency.
Self-Tanning Products Market Segmentation
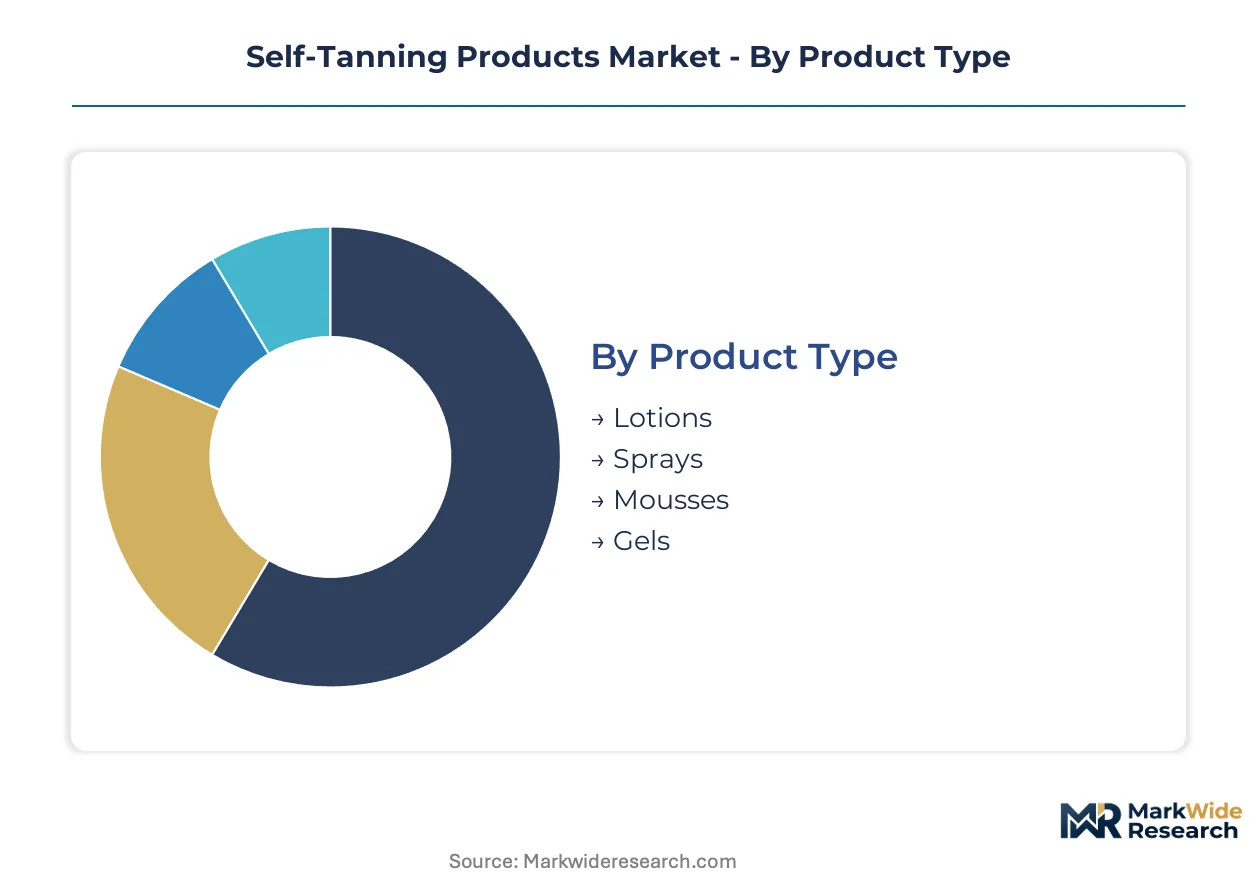
Self-tanning formulations diverge sharply across application physics and skin interaction chemistry, with each segment commanding distinct R&D investment profiles and margin structures. Manufacturers calibrate portfolio depth against reformulation risks from REACH substance restrictions and FDA color additive timelines.
Product Type:
Upgrade cycles accelerate where application convenience intersects with drying-time compression, pushing consumers toward formats that reduce streaking risk and extend wear duration.
- Lotions:Oil-in-water emulsions with 3-5% dihydroxyacetone concentration dominate mass-market shelves through dual-function moisturizing claims. Demand concentrates in US drugstore channels where replenishment frequency sustains volume leadership despite slower absorption rates.
- Mousses:Aerosolized foam structures with rapid-drying surfactant systems capture time-constrained consumers shifting from traditional creams. Professional salon adoption in France and Germany validates premium positioning above standard formulations.
- Sprays:Fine-mist delivery systems enable uniform coverage across hard-to-reach areas, with propellant-free pump formats gaining preference among EU sustainability-conscious buyers.
- Gels:Transparent hydro-alcoholic bases with accelerated dry-down properties target male grooming segments and tropical climate applications where sweat resistance matters.
Lotions sit at the top of the volume ranking, with mousses climbing the fastest as salon-grade formats penetrate home-use channels.
Application Method:
Cost-tier stratification separates appointment-based professional services from disposable at-home systems, with hybrid models emerging to capture intermediate willingness-to-pay.
- Manual:Direct hand-application using mitts or bare hands remains the default entry point for first-time users, with reusable applicator accessories driving accessory revenue attachment.
- Airbrush:Compressed-air atomization systems in professional studios deliver micron-level particle distribution for contouring effects, commanding session pricing multiples above retail product equivalents.
- Spray Tan Booths:Automated vertical misting enclosures with barrier cream protocols dominate US mall-based service locations, where throughput optimization determines location economics.
- Home Use:Consumer-grade devices with simplified nozzle mechanics and pre-measured cartridge systems expand repeat purchase rates through subscription replenishment models.
Spray tan booths anchor the premium pricing tier, while home-use devices expand most quickly through direct-to-consumer subscription channels.
Skin Type:
Formulation specialization deepens where dermatological endorsement creates clinical-channel access, with preservative-free and fragrance-free variants commanding measurable price premiums.
- All Skin Types:Standard pH-balanced bases with broad compatibility drive economies of scale in mass production, though this segment faces compression from targeted alternatives.
- Sensitive Skin:Hypoallergenic formulations with excluded formaldehyde-releasing preservatives and reduced DHA concentrations address EU ECHA hazard classifications, with validation testing conducted under German dermatological institute protocols.
- Oily Skin:Mattifying gel-to-water textures with sebum-absorbing silica particles target younger demographic cohorts in humid subtropical markets.
- Dry Skin:Emollient-rich cream bases with ceramide and hyaluronic acid fortification extend wear duration through stratum corneum hydration, capturing older consumer segments with higher disposable income.
All-skin-type formulations retain volume dominance, with sensitive-skin variants gaining share fastest on regulatory tailwinds and clinical recommendation networks.
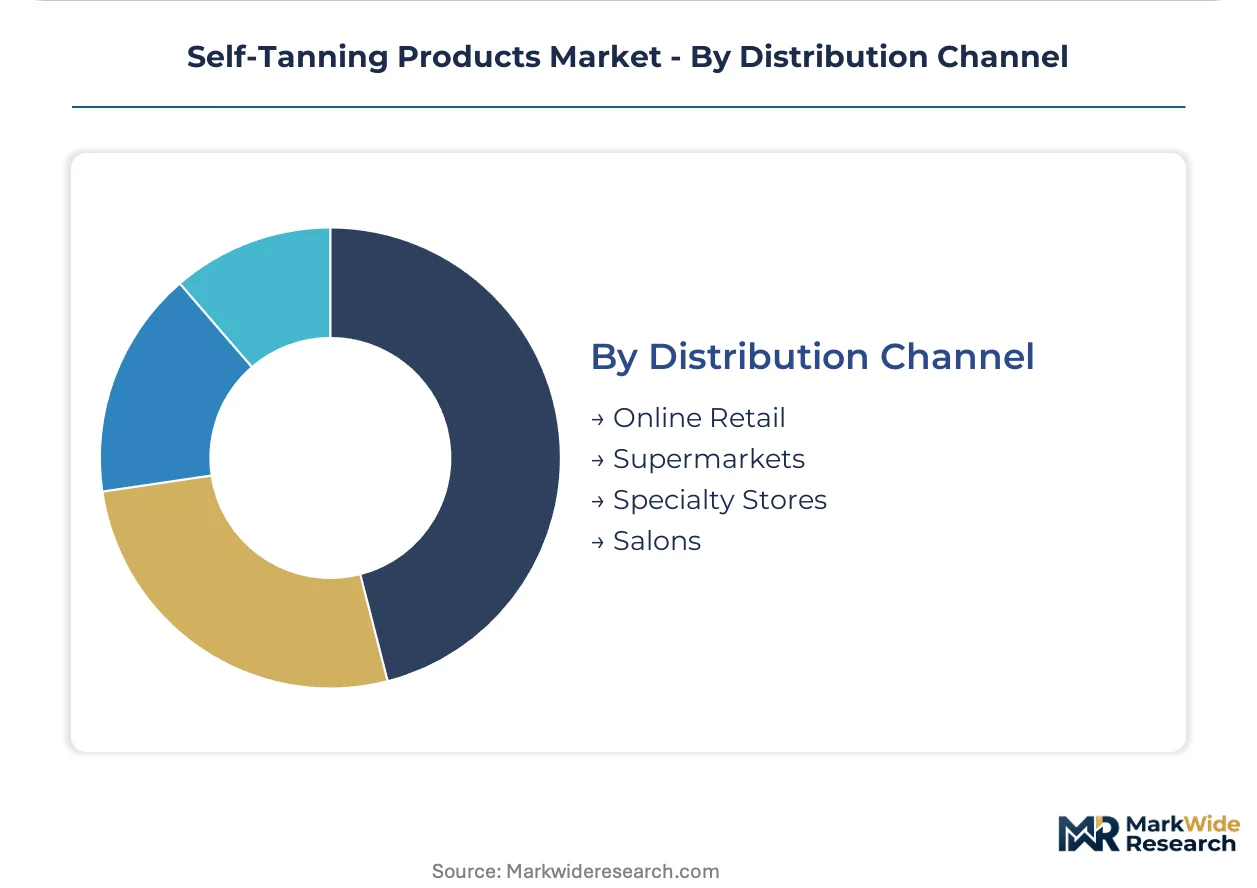
Distribution Channel:
Margin structures diverge where inventory risk and customer acquisition costs trade off, with digital-native brands capturing lifetime value through data-driven replenishment timing.
- Online Retail:Direct-to-consumer platforms with tutorial-integrated checkout flows capture 18-34 demographic concentration, with subscription models displacing intermittent purchase patterns.
- Supermarkets:Mass-market shelf placement with promotional circular dependency sustains volume for legacy brands, though slotting fee structures compress net margins.
- Specialty Stores:Sephora and equivalent beauty retailers provide discovery environment for premium and niche formulations, with trained staff consultation driving conversion above self-serve channels.
- Salons:Service-integrated product sales with professional endorsement leverage appointment traffic for attachment revenue, with exclusive SKUs preventing price transparency.
Supermarkets maintain volume leadership through impulse accessibility, with online retail expanding most quickly as social commerce displaces traditional discovery pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beauty chemists and formulation scientists cluster in Germany, France, and the United States, anchoring the geographic distribution of self-tanning product development and regulatory compliance expertise.
United States
Year-round tanning preferences among consumers sustain category momentum through influencer-driven content marketing and social commerce platforms. The FDA oversees cosmetic labeling and color additive approvals that constrain product claims and ingredient disclosures. Miami and Los Angeles host dense concentrations of professional spray tan studios where appointment-based service models command premium pricing over retail equivalents.
Germany
REACH compliance infrastructure elevates R&D expenditure as a barrier to market participation while creating competitive moats for established manufacturers. The ECHA enforces substance restrictions that periodically delist common bronzing agents and tighten permissible preservative concentrations. Düsseldorf and Hamburg anchor dermatological research networks where pre-validation of next-generation ingredients accelerates fastest among European formulators.
France
Luxury beauty heritage drives premium positioning for salon-grade formulations that penetrate home-use channels. ANSM and CNIL oversight intersect with EU-wide REACH frameworks to reshape disclosure requirements and cosmetic safety protocols. Paris concentrates headquarters functions for multinational beauty conglomerates with dedicated regulatory affairs capacity spanning multiple jurisdictions.
United Kingdom
Post-BREXIT regulatory divergence from EU REACH timelines creates parallel compliance tracks that strain quality assurance functions for brands serving both markets. The country's Medicines and Healthcare products Regulatory Agency maintains distinct cosmetic safety assessment pathways. London anchors direct-to-consumer brand incubators where subscription replenishment models displace traditional drugstore purchase patterns.
Australia
Tropical climate applications and outdoor lifestyle culture sustain demand for sweat-resistant gel formulations targeting male grooming segments. The TGA regulates therapeutic claims while aligning with international cosmetic safety standards. Sydney and Melbourne host professional salon chains that validate premium mousse formats before their migration into mass-market retail channels.
Self-Tanning Products Market Vendor Landscape
The competitive structure tilts toward multi-divisional beauty conglomerates with dedicated regulatory affairs capacity. Consolidation pressures elevate R&D spend as the primary barrier to market participation while fragmenting the mid-tier among niche and direct-to-consumer specialists. Three archetypes dominate: dermatological research-led formulators, salon-grade product specialists, and digital-native subscription brands. M&A activity concentrates on acquiring compliance infrastructure and geographic expansion through distribution partnerships.
Within the dermatological research tier, L'Oréal SA exemplifies multi-jurisdictional compliance leadership anchored by European formulation science. Bondi Sands Pty Ltd occupies a position as a salon-grade specialist navigating divergent regulatory thresholds between professional service and retail channels. Coty Inc. represents the scale-driven portfolio diversification archetype with mass-market shelf presence across multiple format categories.
| Leading Market Players |
|---|
| Bondi Sands Pty Ltd. |
| Clarins Sdn Bhd |
| COOLA LLC |
| Coty Inc. |
| Crown Laboratories Inc. |
| Johnson and Johnson Services Inc. |
| Kao Corp. |
| L'Oréal SA |
| PZ Cussons Plc |
| Others |
Supply Flow & Price Mechanics
Sugar futures volatility on commodity exchanges cascades through dihydroxyacetone procurement contracts into finished-product pricing tiers, compressing margins for volume-dependent brands while specialty manufacturers absorb fluctuations through long-term offtake agreements with fermentation-derived suppliers.
Pricing Analysis
Professional spray tan booth services versus at-home retail product purchases creates the fundamental pricing architecture. Three-tier pricing structure across premium salon-grade, standard mass-market, and economy private-label levels stratifies the market, with certification grade under EU REACH and FDA color additive tiers driving differentiation. Pricing pressure stems from DHA supply concentration among specialty chemical suppliers, exposing formulators to input cost volatility. Mass-market drugstore buyers exhibit highest price sensitivity, while professional salon clients demonstrate lowest elasticity due to appointment-based service bundling.
Supply Chain Analysis
Workforce availability constraints in German and French cosmetic chemistry clusters limit formulation capacity expansion despite accelerating demand. Manufacturing concentrates in Germany, France, and the United States, with raw material procurement drawing from Brazilian sugarcane fermentation facilities, Chinese specialty chemical intermediates, and Indian botanical extract suppliers. Single-source vulnerability pervades DHA supply, where three fermentation specialists control global output. Distribution runs through direct-to-consumer platforms, specialty beauty retailers, and professional salon networks with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as consumer preferences shift toward dermatologist-endorsed, preservative-free formulations that command measurable price premiums over standard alternatives.
For Market Incumbents: To counter REACH-driven reformulation cycle compression, incumbents should deepen captive supply of dihydroxyacetone through backward integration into fermentation partnerships, while accelerating pre-validation of next-generation bronzing agents through German dermatological institute networks to sustain multi-jurisdictional compliance leadership. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting the 18-34 demographic cohort with mousse-format specialization, exploiting white-space in male grooming gel segments and clinical-channel UV-sensitive populations where dermatologist recommendation networks remain underdeveloped. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory affairs capacity creates acquisition premiums for European formulators with REACH compliance infrastructure. Five-to-ten-year viability favors targets with dedicated dermatological research pipelines and salon-grade brand equity. The signal to watch is ECHA hazard reclassification timing that could force portfolio-wide reformulations and trigger distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DHA Supply | Captive fermentation capacity insulates margin structures from sugar commodity volatility. |
| REACH Pre-Validation Investment | Early ECHA engagement accelerates next-generation ingredient approval timelines. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models displace intermittent drugstore purchase patterns. |
| Clinical Channel Partnership | Dermatologist endorsement networks unlock UV-sensitive population segments. |
| Mousse Format Scale-Up | Salon-grade penetration into home-use channels captures time-constrained consumers. |
Methodological Framework
Bottom-up consumer segment modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with formulation chemists, regulatory affairs directors at multinational beauty conglomerates, procurement leads at specialty chemical suppliers, and category buyers at Sephora-equivalent retailers combine with secondary validation from FDA color additive filings, ECHA substance restriction registers, EU customs trade data, and Nielsen retail audit records. Triangulation across these sources ensures demand-side estimates align with supply-side production realities.
Historical trendline analysis of volume and value trajectories across the projection horizon informs growth rate derivation. Segmentation dimensions modeled include product format, application method, skin type specialization, and distribution channel, with regulatory compliance tier and influencer content engagement intensity as industry-specific forecast inputs. CAGRs emerge from curve-fitting against observed adoption patterns and capacity expansion announcements.
Several conditions sit outside the modeled scope, including pending ECHA hazard reclassifications, FDA color additive approval delays, and macroeconomic shocks affecting discretionary beauty expenditure. Forecasts reflect documented assumptions about regulatory timelines and consumer preference stability. Material deviation in REACH enforcement intensity or DHA supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Global Canes and Walking Sticks Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Smart Electric Toothbrush Market
Personal Grooming Products
Electric Hair Brush Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Global Aligner Sheet Market
Personal Grooming Products
Gel Socks Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
Global Posture Corrector Market
Personal Grooming Products
India Beard Trimmer Market