
 Europe Hair Styling Tools Market | 2026-2036
Europe Hair Styling Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hair Styling Tools Market Foresight
Subscription-based equipment leasing for professional salons is reconfiguring capital deployment across the value chain, lowering entry barriers for independent stylists and mid-tier salon chains. Dyson leverages its proprietary digital motor technology to command premium positioning in high-velocity hair dryers. Helen of Troy Ltd anchors its competitive stance through specialized curling iron and hot roller portfolios distributed via professional beauty supply channels. Panasonic Holdings Corp sustains manufacturing scale advantages across ceramic heating element production for straighteners and multi-styling platforms.
Europe hair styling tools encompass electrically powered devices engineered to alter hair structure through controlled thermal, ionic, or infrared energy delivery, typically operating at wattages between 1200W and 2300W with ceramic or tourmaline-coated surfaces to distribute heat evenly and minimize cuticle damage. These instruments serve commercial stylists and individual consumers seeking temporary shape modification, volume enhancement, or texture transformation without permanent chemical processing. Hair dryers occupy the largest revenue pool within product type segmentation, though straighteners generate superior per-unit margins due to precision temperature control requirements. Ionic technology leads technology adoption in professional channels where frizz reduction commands priority, while infrared applications represent the fastest-expanding segment as salon operators invest in gentler heat alternatives for chemically treated hair.
CE marking under the EU Low Voltage Directive and Ecodesign Framework mandates electrical safety and energy efficiency thresholds for all mains-powered styling devices sold across member states. REACH enforcement through ECHA restricts hazardous substance content in polymer housings and ceramic coatings, directly influencing supplier qualification and material substitution timelines. Germany's KBA-equivalent product safety authority and France's national consumer protection regulator conduct periodic market surveillance testing that shapes recall exposure and brand liability. Stakeholders must monitor evolving EU right-to-repair provisions and ecodesign expansion timelines that could mandate replaceable heating element architectures and extended warranty obligations.
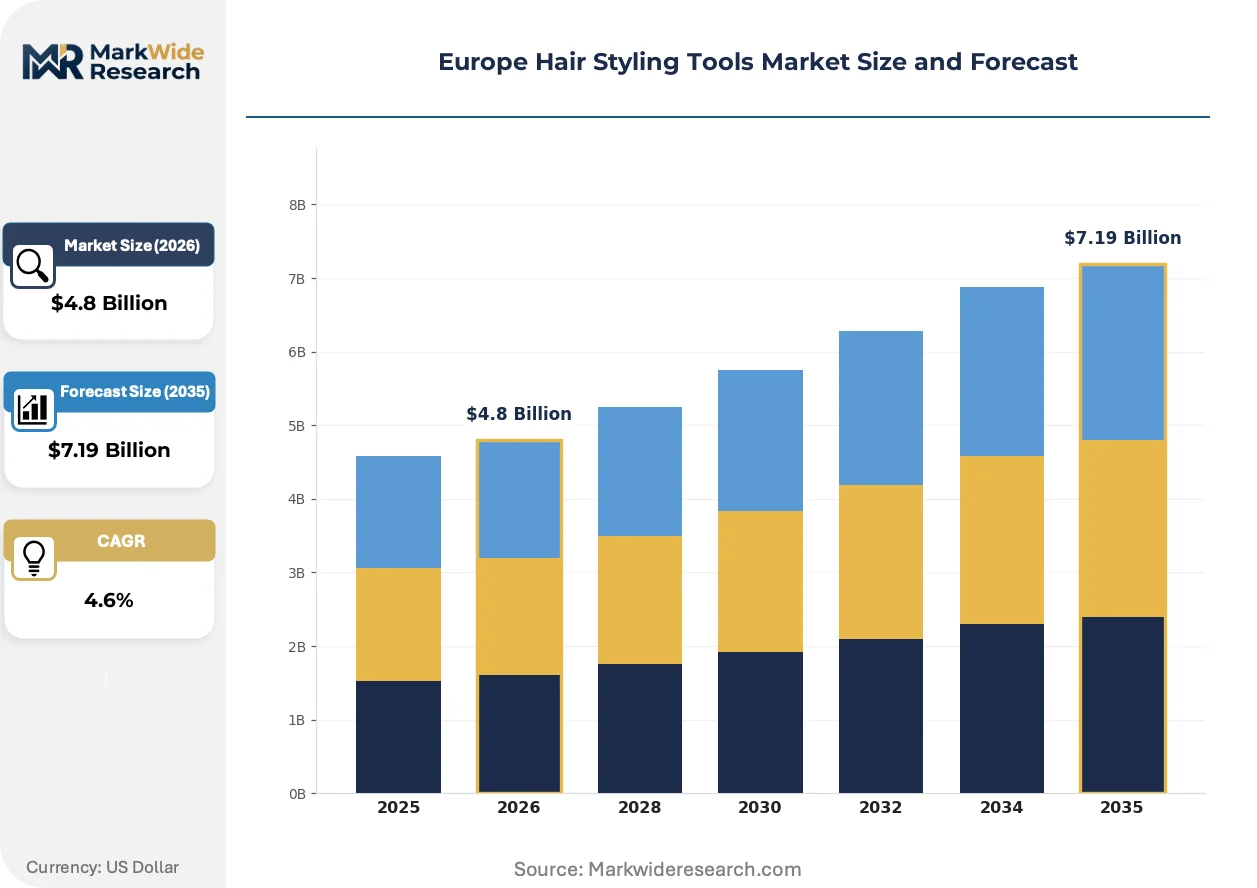
Market Dynamics
Subscription-based equipment leasing is compressing capital deployment cycles across professional salon networks, while REACH compliance and the EU Ecodesign Directive force ceramic heating element redesigns that extend R&D timelines by 12-18 months.
Growth Catalysts
- Heat-damage prevention technologies:Ionic and infrared systems reduce cuticle degradation, driving replacement demand in Paris, Milan, and London salon clusters where premium positioning commands sustained preference.
- EU Ecodesign Directive:Energy efficiency mandates accelerate adoption of lower-emission ceramic heating elements, creating technical differentiation for compliant manufacturers.
- Independent stylist expansion:Mid-tier salon chains and solo operators leverage leasing models to access professional-grade equipment without upfront capital burden.
Market Restraints
- Ceramic coating supply concentration:Tourmaline-infused ceramic substrate production concentrates among specialized East Asian suppliers, exposing European manufacturers to input volatility and extended qualification timelines.
- REACH substance restrictions:ECHA enforcement limits polymer housing formulations and coating chemistries, forcing material substitutions that compress margin structures.
- Heat-based substitution ceiling:Chemical straightening and keratin treatments retain cost advantages for permanent texture modification, capping addressable market expansion for thermal styling devices.
Strategic Opportunities
- Right-to-repair mandate preparation:Evolving EU provisions will mandate replaceable heating element architectures, rewarding early movers with modular platform designs and extended warranty revenue streams.
- Multi-styling platform convergence:Interchangeable barrel and plate systems hybridize dryer, straightener, and curler functions into single devices, reducing equipment footprint for space-constrained urban salons.
- Professional supply channel digitization:Direct-to-salon e-commerce platforms disintermediate traditional beauty supply distributors, enabling margin capture and usage-data collection.
Industry Challenges
- CE marking timeline compression:Notified body backlogs under the EU Low Voltage Directive extend product launch windows, delaying revenue recognition for seasonal styling tool releases.
- Heating element integration complexity:Precision temperature control firmware requires embedded systems expertise scarce among traditional appliance engineering teams, forcing partnership or acquisition decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hair Styling Tools Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Dryers, Straighteners, Curling Irons, Hot Rollers Technology: Ionic, Ceramic, Tourmaline, Infrared End User: Professional Salons, Individual Consumers, Hair Styling Schools, Retail Outlets Distribution Channel: Online Stores, Specialty Beauty Shops, Supermarkets, Other Retailers |
| Companies Covered | Procter & Gamble Co, Conair, Helen of Troy Ltd, Dyson, Koninklijke Philips NV, Panasonic Holdings Corp, Jemella Ltd, Wahl Clipper Corporation, Henkel AG & Co. KGaA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hair Styling Tools Market Shifts & Advancements
Digital motor and sensor technologies are converging with connected-device architectures to transform thermal delivery precision, while regulatory pressure on material safety and energy efficiency accelerates hardware redesign cycles across the value chain.
Infrared ceramic heating technology is hybridizing with traditional resistive elements to deliver gentler thermal profiles for chemically treated hair. High-end Paris and Milan salons are adopting these systems at twice the rate of standard ionic equipment. The convergence is compressing demand for single-technology devices and rewarding multi-modal platform engineering.
REACH enforcement through ECHA is tightening hazardous substance thresholds in polymer housings and ceramic coatings. Manufacturers face reformulation costs and supplier requalification that disproportionately burden mid-tier brands. German and French market surveillance authorities are conducting randomized testing that elevates recall exposure for non-compliant imports.
Salon procurement patterns are fragmenting as independent stylists bypass traditional beauty supply distributors through direct manufacturer relationships and subscription leasing. Equipment-as-a-service models are displacing outright purchase in London and Berlin metropolitan clusters. The shift concentrates volume with platform-capable vendors while squeezing regional distributor margins.
Europe Hair Styling Tools Market Segmentation
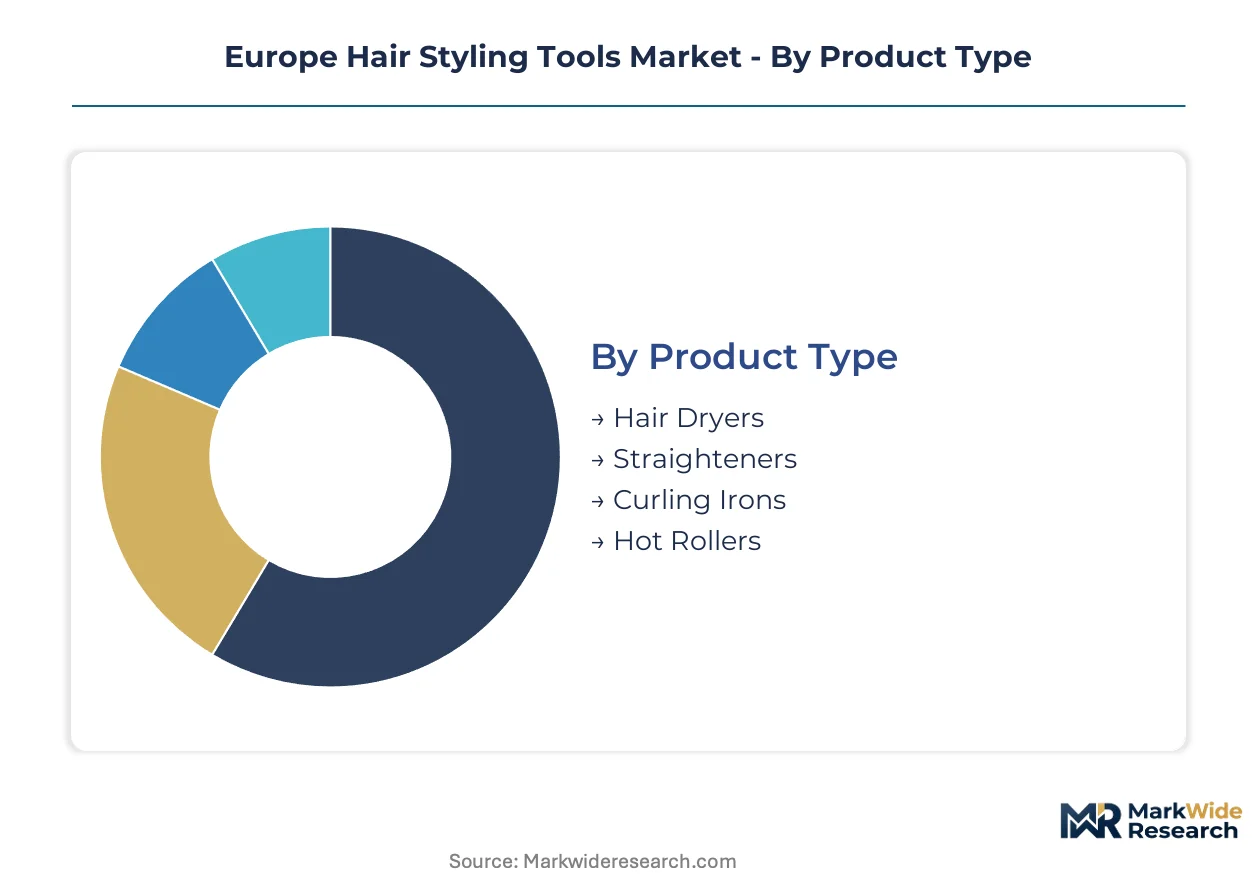
Segmentation in Europe hair styling tools reveals divergent technical requirements between professional and consumer channels, with regulatory compliance and heat-damage prevention technologies driving purchasing criteria across distinct use cases.
Product Type:
Professional stylists deploy equipment across the full use-case spectrum from rapid drying to precision curling, while individual consumers prioritize multi-function platforms that reduce storage footprint.
- Straighteners:Precision temperature control systems with ceramic or tourmaline-coated plates enable heat distribution uniformity for permanent shape modification. Paris and Milan salon clusters favor these devices for their superior per-unit margins and frizz reduction capabilities on chemically treated hair.
- Hair Dryers:Digital motor architectures operating between 1200W and 2300W deliver high-velocity airflow for volume enhancement and texture preparation. These units command the largest revenue pool within professional channels across London metropolitan networks where ionic technology integration drives replacement cycles.
- Curling Irons:Barrel-based thermal systems with interchangeable diameter options provide temporary curl formation for styling versatility.
- Hot Rollers:Heated roller sets deliver volume-building heat retention for salon blowout preparation and special occasion styling.
Established volume favors hair dryers; emerging adoption favors straighteners with precision control firmware.
Technology:
Cost tier differentiation separates premium thermal delivery systems from standard resistive elements, with regulatory pressure on energy efficiency accelerating hardware redesign timelines.
- Infrared:Ceramic heating elements emitting far-infrared wavelengths penetrate hair shafts with gentler thermal profiles that minimize cuticle degradation. High-end Paris and Milan salons adopt these systems at twice the rate of standard ionic equipment for chemically treated hair applications.
- Ionic:Negative ion generators neutralize static charge to reduce frizz and accelerate drying time through moisture molecule breakdown. Professional channels across Berlin and London prioritize this technology where frizz reduction commands purchasing priority.
- Ceramic:Aluminum oxide-coated heating surfaces distribute thermal energy evenly across contact zones to prevent localized heat damage.
- Tourmaline:Crystalline boron silicate mineral coatings enhance ionic emission and infrared radiation for combined smoothing effects.
Premium positioning clusters around infrared and tourmaline hybrid systems; volume deployment concentrates in ceramic and ionic platforms.
End User:
Customer type determines equipment specification intensity, with commercial operators requiring durability certifications and precision controls unavailable in consumer-grade alternatives.
- Professional Salons:Commercial-grade devices with extended duty cycles and replaceable component architectures serve high-throughput styling operations. German and French salon networks drive demand for CE-marked equipment with REACH-compliant polymer housings.
- Individual Consumers:Compact-form factor devices with simplified temperature presets address home styling needs without professional training requirements.
- Hair Styling Schools:Training institutions require durable demonstration equipment with visible safety certifications for instructional environments.
- Retail Outlets:Display and demonstration units with theft-deterrent fixtures and interactive sampling capabilities support point-of-sale engagement.
Commercial volume anchors professional salon procurement; individual consumer channels are expanding most quickly through subscription leasing models.
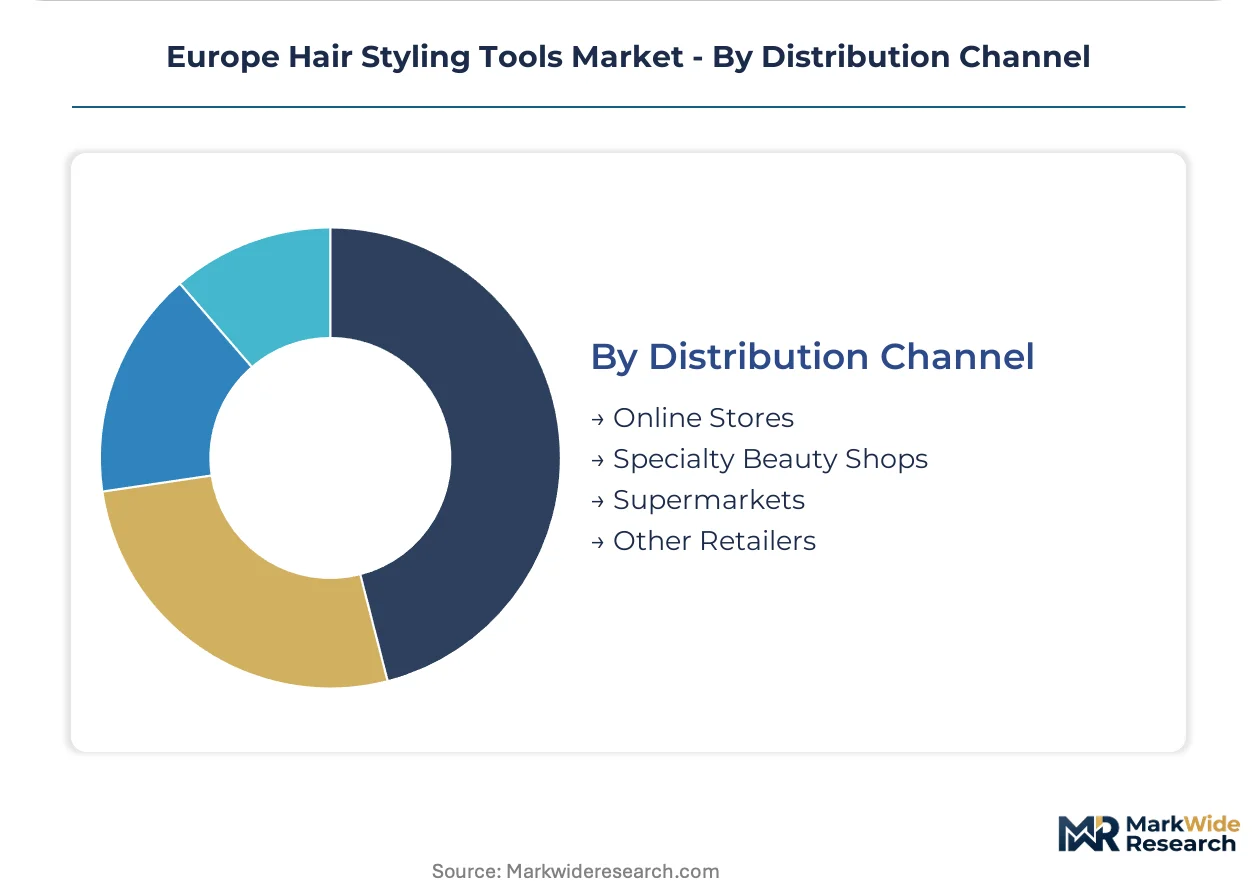
Distribution Channel:
Supply concentration in direct manufacturer relationships is displacing traditional beauty supply intermediaries, with digitization enabling margin capture and usage-data collection.
- Specialty Beauty Shops:Professional supply channels with trained staff provide equipment demonstration and technical specification guidance for salon purchasers. These outlets dominate procurement in Milan and Paris where stylist consultation influences capital deployment decisions.
- Online Stores:Direct-to-salon e-commerce platforms fragment procurement patterns and enable independent stylists to bypass traditional distributors. London and Berlin metropolitan clusters show accelerated adoption of digital purchasing for equipment-as-a-service models.
- Supermarkets:Mass-market retail placement addresses impulse purchases and gift-buying occasions for consumer-grade styling tools.
- Other Retailers:Department stores and general merchandise channels provide seasonal promotional visibility and bundled accessory offerings.
Digital channels gain share fastest in professional segments; established volume remains with specialty beauty supply networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Ecodesign Directive enforcement and REACH compliance requirements are redirecting manufacturing investment toward lower-emission ceramic heating architectures across member states. National regulators in Germany and France conduct randomized market surveillance testing that elevates recall exposure for non-compliant imports.
Germany
Professional salon networks in Berlin and Hamburg drive demand for CE-marked equipment with precision temperature control firmware. KBA-equivalent product safety authority testing protocols shape supplier qualification timelines for polymer housing formulations. Bavaria's industrial manufacturing corridor hosts specialized ceramic heating element producers serving premium tool brands.
France
Paris metropolitan salon clusters command sustained preference for ionic and infrared equipment with superior per-unit margins. ANSM and national consumer protection regulator surveillance testing elevates liability exposure for REACH-non-compliant ceramic coatings. Île-de-France beauty supply distributors face margin compression from direct-to-salon digital procurement channels.
United Kingdom
London professional networks prioritize high-velocity hair dryers with digital motor architectures for rapid styling throughput. Post-Brexit regulatory divergence from EU Ecodesign Framework creates dual compliance burdens for manufacturers serving both markets. Midlands manufacturing bases supply ceramic plate components to domestic tool assemblers.
Italy
Milan salon operators adopt infrared ceramic hybrid systems at twice the rate of standard ionic equipment for chemically treated hair applications. Regional beauty supply channels with trained staff dominate equipment demonstration and technical specification guidance. Lombardy's design-intensive industrial ecosystem supports premium tool aesthetics and ergonomic engineering.
Netherlands
Randstad logistics hubs facilitate distribution of REACH-compliant styling tools across Benelux professional channels. Dutch environmental regulators enforce extended producer responsibility frameworks that mandate replaceable heating element architectures. Eindhoven-region electronics specialists supply precision temperature control firmware to tool manufacturers.
Europe Hair Styling Tools Market Competitive Landscape
On the supply side, the industry is consolidating around platform-capable vendors with modular design architectures and subscription-leasing service capabilities. Mid-tier brands face margin compression from REACH reformulation costs and ceramic coating supply concentration among specialized East Asian suppliers. Three strategic archetypes dominate: premium technology licensors with proprietary motor systems, diversified consumer appliance conglomerates with professional supply channel access, and specialized beauty tool manufacturers with curling iron and hot roller portfolios. Competitive moves concentrate on direct-to-salon e-commerce platform development and multi-styling platform convergence that hybridizes dryer, straightener, and curler functions.
Within the premium technology tier, Dyson and Helen of Troy Ltd occupy positions anchored by proprietary engineering capabilities and professional channel relationships. Panasonic Holdings Corp represents the diversified industrial conglomerate archetype with manufacturing scale advantages across ceramic heating element production. Koninklijke Philips NV exemplifies the consumer appliance specialist with established CE marking expertise and EU regulatory compliance infrastructure. These three entities collectively illustrate the competitive stratification between technology-driven premium positioning and scale-driven component supply.
| Leading Market Players |
|---|
| Procter & Gamble Co |
| Conair |
| Helen of Troy Ltd |
| Dyson |
| Koninklijke Philips NV |
| Panasonic Holdings Corp |
| Jemella Ltd |
| Wahl Clipper Corporation |
| Henkel AG & Co. KGaA |
| Others |
Supply & Pricing Matrix
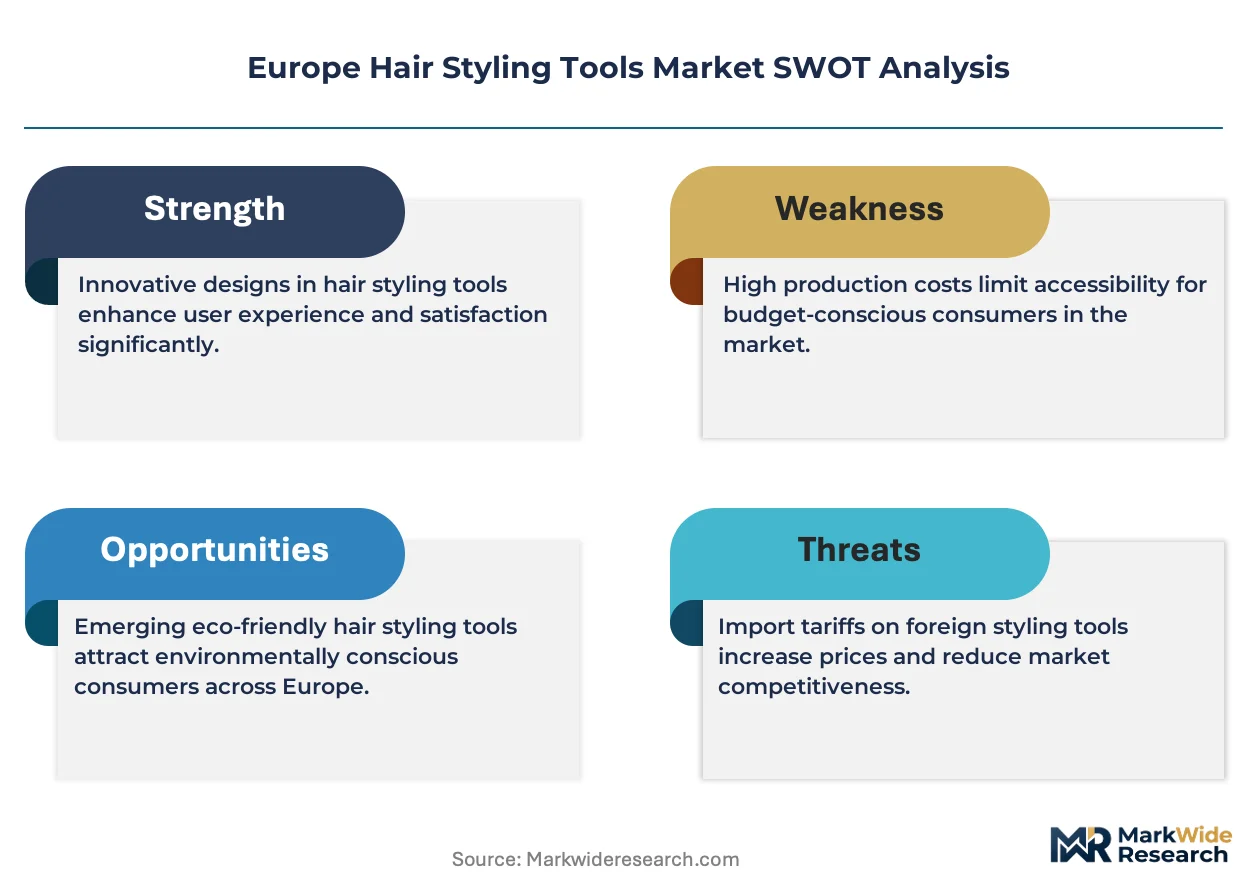
REACH substance restrictions on polymer housings and ceramic coatings function as a regulatory chokepoint that simultaneously widens pricing tier spreads between compliant and non-compliant equipment and forces supply chain restructuring toward qualified European material suppliers. This dynamic compresses margins for mid-tier brands unable to absorb reformulation costs while rewarding premium manufacturers with established ECHA-compliant supplier networks.
Pricing Analysis
Certification level creates the primary spread across CE-marked professional equipment, with REACH-compliant formulations commanding substantial premiums over standard consumer-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels separates modular platform devices with replaceable heating elements from fixed-architecture alternatives. Cost compression in the mid-tier is intensifying because ECHA enforcement timelines are accelerating faster than supplier requalification cycles. Independent stylists and small salon chains exhibit highest price sensitivity, while Paris and Milan metropolitan clusters demonstrate lowest sensitivity where brand reputation and heat-damage prevention technologies drive procurement decisions.
Supply Chain Analysis
Contract manufacturing for ceramic heating elements concentrates among specialized producers in Bavaria's industrial corridor and select East Asian facilities with tourmaline-infusion capabilities. Tourmaline-infused ceramic substrates, precision temperature control firmware from Eindhoven-region specialists, and REACH-compliant polymer housings constitute critical input dependencies. Single-source vulnerability around tourmaline supply exposes European assemblers to input volatility and extended qualification timelines. Distribution runs through specialty beauty supply channels in Milan and Paris, with direct-to-salon e-commerce platforms gaining share fastest in London and Berlin metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service platforms are reconfiguring this market toward subscription-economics where interoperability standards and modular component ecosystems determine competitive survival rather than standalone product performance.
For Market Incumbents: Entrench position through backward integration into ceramic heating element production and captive supply of REACH-compliant polymer formulations. Dyson's proprietary digital motor architecture and Panasonic's manufacturing scale advantages illustrate how in-house production of critical components defends against East Asian supplier concentration risk. Prioritize modular platform designs that accommodate forthcoming EU right-to-repair mandates for replaceable heating element architectures. For New Entrants and Emerging Players: Mid-market independent stylists in Berlin and Hamburg represent the most penetrable entry point, where subscription leasing models lower capital barriers and bypass established distributor relationships. Direct-to-salon e-commerce platforms with usage-data collection capabilities offer differentiated positioning against legacy beauty supply channels. Target professional styling schools with durable demonstration equipment bundles that build brand familiarity among future salon operators. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors platform-capable vendors with modular design architectures and established CE marking expertise. Long-term viability over the next decade hinges on compliance infrastructure rather than pure technology differentiation. Acquisition targets should demonstrate proven REACH-compliant supplier networks and firmware development partnerships with European embedded systems specialists. Watch ECHA enforcement acceleration and right-to-repair mandate finalization as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Development | Interchangeable barrel and plate systems reduce equipment footprint for space-constrained urban salons. |
| Direct-to-Salon E-Commerce Launch | Digital procurement platforms disintermediate traditional beauty supply distributors in London and Berlin clusters. |
| Ceramic Heating Element Backward Integration | In-house production of tourmaline-infused substrates mitigates East Asian supplier concentration risk. |
| REACH Compliance Certification Investment | ECHA-aligned polymer housing formulations defend against French and German market surveillance testing exposure. |
| Subscription Leasing Service Expansion | Equipment-as-a-service models capture recurring revenue from independent stylists and mid-tier salon chains. |
Research Methodology
Operator-level perspectives from salon owners, professional stylists, beauty supply distributors, and ceramic heating element manufacturers anchored the qualitative base for this analysis. Primary interviews across these stakeholder categories were cross-validated against secondary sources including ECHA substance restriction databases, CE marking compliance records, EU Ecodesign Directive implementation timelines, and professional beauty industry trade publications. Bottom-up equipment shipment estimates by product type and technology tier were triangulated with top-down market size assessments derived from regulatory filing analysis and distributor revenue disclosures.
Scenario-bracketing around REACH enforcement intensity and right-to-repair mandate timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and distribution channel, with regulatory compliance status as an additional industry-specific dimension. CAGRs were derived from trend extrapolation of replacement cycle compression and technology adoption curves, incorporating salon expansion rates in metropolitan clusters and independent stylist population growth as hair styling tools-specific forecast inputs.
Stress conditions across ECHA enforcement acceleration, ceramic raw material supply disruption, and subscription model adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and supplier qualification cycle durations. Quarterly review of ECHA substance restriction updates, notified body CE marking backlog reports, and salon equipment procurement survey data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Electric Hair Brush Market
Personal Grooming Products
Epilators Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
China Beard Trimmer Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Global Mobile Barber Shop Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Smart Electric Toothbrush Market