
 Marine Hyaluronic Water Cream Market | 2026-2036
Marine Hyaluronic Water Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Hyaluronic Water Cream Market Analytics
Aftermarket service revenue from personalized skin-analysis consultations is rewriting how premium skincare brands capture lifetime customer value. La Mer leverages its proprietary fermentation technology to sustain margin-rich exclusivity in marine-sourced actives. Shiseido Company Limited anchors its regional dominance through controlled distribution across Asian department store counters. CeraVe competes on derm-channel credibility with pharmacy-first placement and clinician endorsement programs.
Marine hyaluronic water cream is a lightweight, water-based emulsion incorporating biofermented marine polysaccharides and cross-linked hyaluronic acid fractions designed for transdermal hydration without occlusive residue. The formulation typically achieves a non-comedogenic rating through controlled molecular weight distribution of sodium hyaluronate combined with cold-processed seaweed extracts. Gel cream formats command the fastest-growing position within product type segmentation due to millennial and Gen Z preference for breathable textures in humid climates. Online retail channels capture expanding margin pools as direct-to-consumer subscription models displace traditional wholesale markups in North American and European markets.
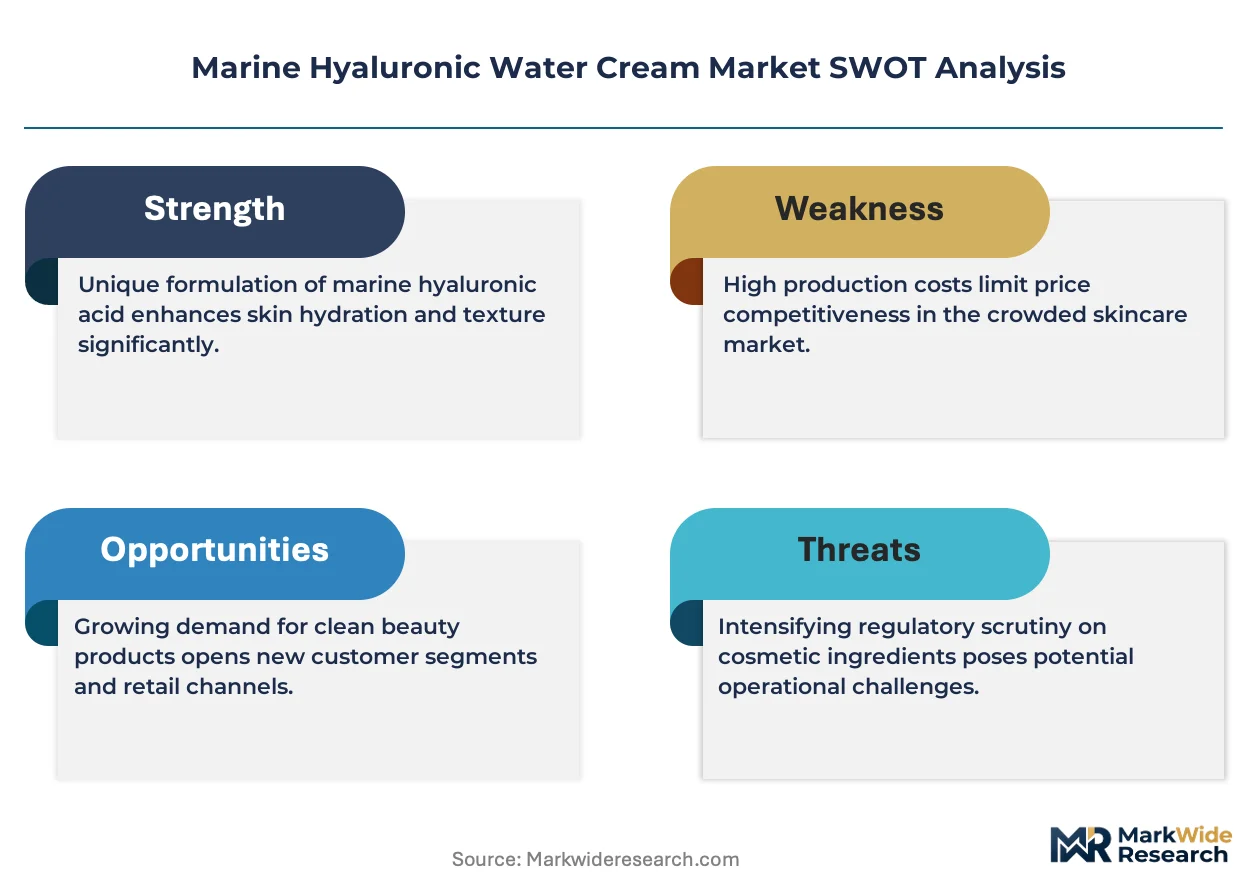
FDA cosmetic labeling requirements and the EU Cosmetics Regulation govern ingredient disclosure thresholds and substantiation of hydration claims across the United States and European markets. South Korea's MFDS maintains stringent safety evaluations for fermented marine extracts, creating compliance barriers that favor established manufacturers with dedicated regulatory affairs teams. ISO 16128 guidelines on natural and organic cosmetic ingredients increasingly influence raw material sourcing specifications for brands targeting clean beauty positioning. Stakeholders must monitor evolving state-level restrictions on microplastic-containing rinse-off products in California and New York, as these precedents threaten conventional thickening agents and drive reformulation investments toward marine-derived alternatives.
Market Dynamics
The EU Cosmetics Regulation's animal-testing ban is compressing formulator timelines as brands pivot toward marine-derived hyaluronic acid sources, while South Korea's MFDS fermentation standards concentrate supply among established manufacturers with dedicated regulatory infrastructure.
Growth Catalysts
- EU regulatory exclusion of animal-tested actives:The EU Cosmetics Regulation's marketing ban forces formulators toward biofermented marine polysaccharides, expanding addressable supply for cruelty-free positioning.
- Professional channel expansion:Dermatology clinics and medical spas in Germany and the United States now stock marine hyaluronic water creams as post-procedure hydrators, anchoring clinical credibility.
- Cold-processed extraction methods:Enzymatic hydrolysis of brown seaweed polysaccharides preserves bioactive integrity, enabling cleaner-label claims that resonate with millennial and Gen Z demographics.
Market Restraints
- Raw material concentration risk:Premium Laminaria and Undaria seaweed harvests concentrate in coastal regions of South Korea and France, exposing supply chains to climate-driven harvest volatility.
- Fermentation facility capex intensity:GMP-compliant bioreactor infrastructure for marine polysaccharide production requires substantial capital outlay, limiting new entrant participation.
- MFDS compliance timeline friction:South Korea's safety evaluation protocols for novel marine extracts extend product registration cycles by 12-18 months versus conventional hyaluronic acid.
Strategic Opportunities
- Direct-to-consumer subscription models:Online retail channels in North America and Europe are displacing wholesale markups, capturing recurring revenue pools previously lost to department store intermediaries.
- Men's grooming vertical penetration:Gender-neutral packaging and non-greasy gel cream textures open underdeveloped segments in Japan and the United States.
- California microplastic restrictions:State-level bans on synthetic thickeners create forced substitution demand for marine-derived rheology modifiers.
Industry Challenges
- Fermentation science talent scarcity:Industrial biotechnology programs produce insufficient specialists in marine microbiology, constraining scale-up velocity for bioactive extraction operations.
- Cross-border formulation standardization:Divergent ISO 16128 natural-content thresholds across jurisdictions force redundant SKU development, fragmenting production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Hyaluronic Water Cream Market |
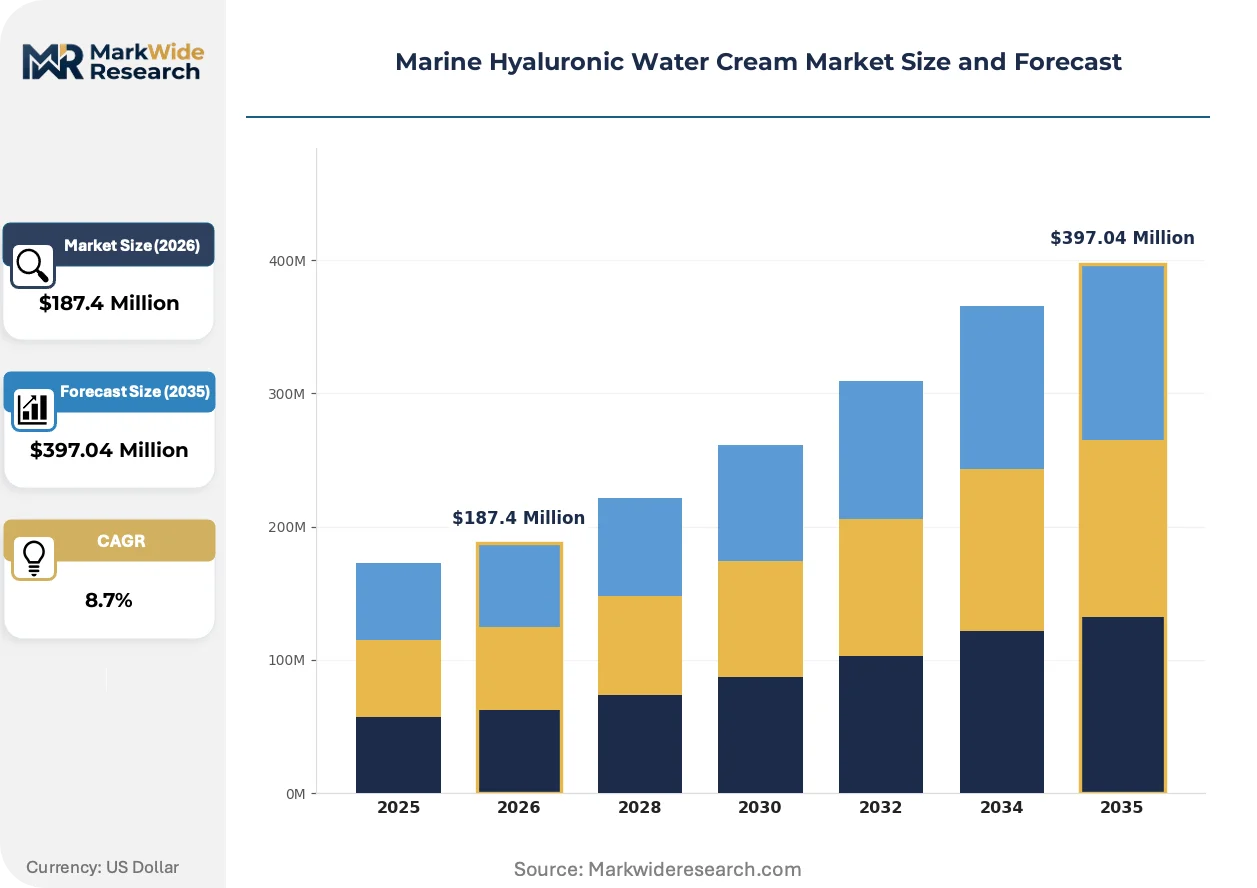
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Day Cream, Night Cream, Moisturizer, Gel Cream End User: Women, Men, Teens, Seniors Distribution Channel: Online Retail, Offline Retail, Specialty Stores, Pharmacies Ingredient Type: Botanical Extracts, Peptides, Antioxidants, Others |
| Companies Covered | L'Oréal, Estée Lauder, Neutrogena, La Mer, Clinique, Shiseido Company Limited, CeraVe, Dr. Jart+, Tatcha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Hyaluronic Water Cream Market Evolving Landscape
Formulation science is virtualizing hydration delivery mechanisms while regulatory pressure and channel disintermediation simultaneously compress go-to-market economics and expand margin capture for vertically integrated operators.
Biofermented low-molecular-weight hyaluronic acid is virtualizing traditional transdermal penetration limits. Korean contract manufacturers now deploy membrane filtration to isolate sub-50 kDa fractions that bypass stratum corneum resistance. Professional dermatology channels in Seoul-Incheon and Los Angeles are adopting these grades for post-laser recovery protocols, compressing reliance on invasive hydration delivery methods.
REACH registration requirements for novel marine-derived polymers are tightening substance dossier standards across European manufacturing. The European Chemicals Agency now demands extended aquatic toxicity data for polysaccharide extracts, extending compliance timelines for new ingredient introductions. German and French formulators are responding by consolidating supplier relationships with established fermentation houses that maintain pre-validated regulatory packages.
Clinician endorsement programs are displacing traditional celebrity marketing as the primary trust-building mechanism. Pharmacy-first brands now deploy sampling networks through dermatology practices in the United States and Germany, replacing department store counter presence. This channel pivot is most visible in humid climate metros like Houston and Singapore, where breathable gel cream textures address specific environmental stressors.
Marine Hyaluronic Water Cream Market Segmentation
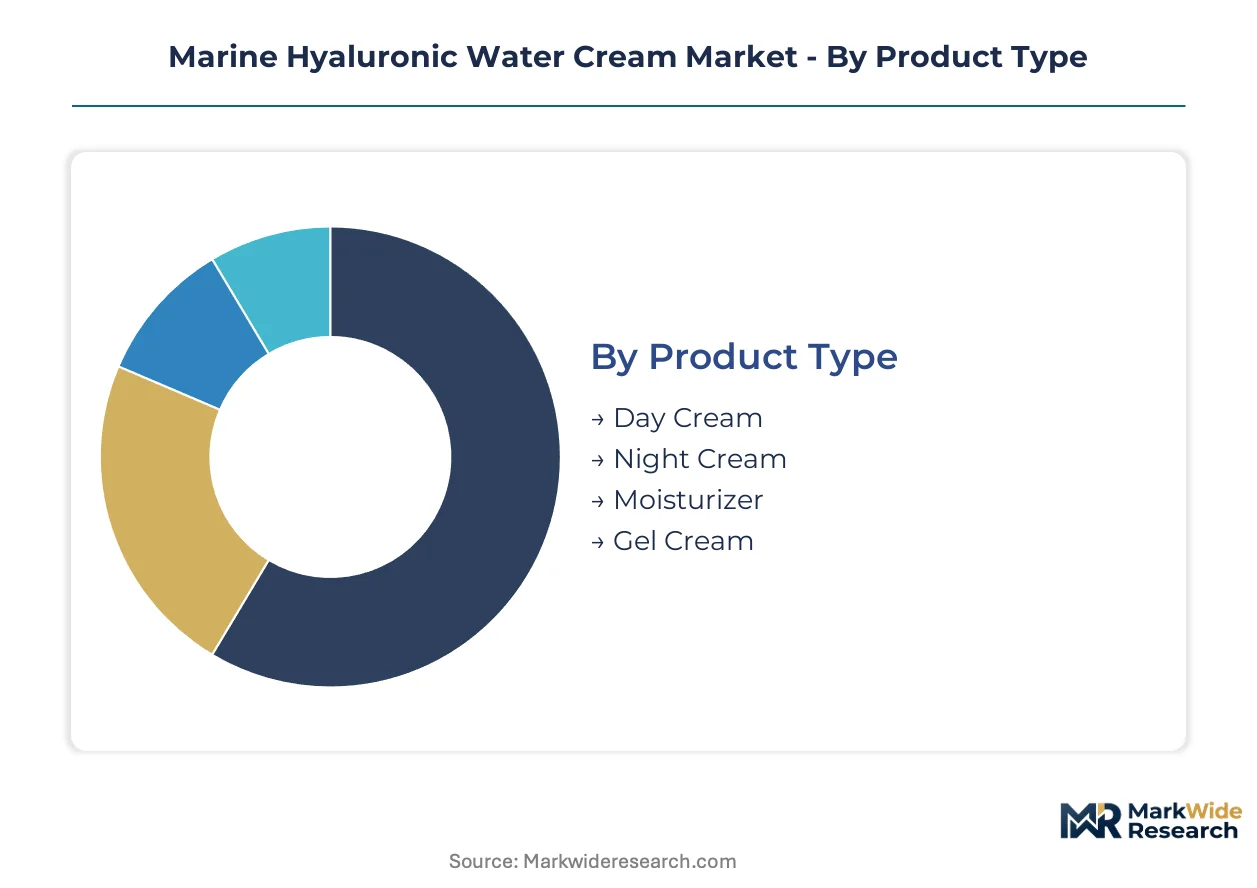
Segmentation in marine hyaluronic water cream markets reveals how formulation texture, demographic targeting, and channel economics interact to determine margin capture. Manufacturers optimize SKU portfolios across these dimensions to balance regulatory compliance costs against pricing power in premium hydrators.
Product Type:
Texture and wear-time specifications divide the market into distinct usage occasions and climate adaptations.
- Gel Cream:Water-based emulsions with cross-linked sodium hyaluronate fractions achieve non-comedogenic ratings through controlled molecular weight distribution. Demand concentrates in Seoul-Incheon manufacturing corridors and humid climate metros like Houston and Singapore where breathable textures address environmental stressors. Millennial and Gen Z preference for lightweight hydration accelerates adoption.
- Moisturizer:Standard emulsion formats with higher oil-phase content deliver sustained occlusion for drier skin types. German and United States dermatology clinics stock these grades for post-procedure recovery protocols.
- Day Cream:SPF-compatible bases with rapid absorption profiles suit morning application routines.
- Night Cream:Richer formulations with elevated polysaccharide density support overnight barrier repair cycles.
Gel Cream holds installed capacity. Moisturizer is rotating up the share rankings.
End User:
Demographic targeting reflects divergent price elasticity and channel access patterns across gender and age cohorts.
- Women:The established core segment drives premium positioning through department store and specialty retail channels. South Korean and French formulators prioritize this cohort with advanced fermentation-derived actives.
- Men:Gender-neutral packaging and non-greasy textures open underdeveloped segments in Japan and the United States. Pharmacy-first placement with clinician endorsement builds credibility.
- Teens:Acne-conscious formulations with oil-free claims capture early skincare adoption moments.
- Seniors:Barrier-support claims with ceramide co-formulation address age-related transepidermal water loss.
Women maintain volume concentration. Men is expanding most quickly as grooming routines professionalize.
Distribution Channel:
Channel selection determines margin retention and customer lifetime value mechanics.
- Online Retail:Direct-to-consumer subscription models displace wholesale markups in North American and European markets. Recurring revenue pools previously captured by department store intermediaries now flow to vertically integrated brands.
- Pharmacies:Clinician endorsement programs in the United States and Germany anchor trust through derm-channel credibility. Sampling networks through dermatology practices replace traditional counter presence.
- Specialty Stores:Curated assortments with skin-analysis services capture premium price points.
- Offline Retail:Mass-market placement competes on accessibility and promotional velocity.
Online Retail commands margin expansion. Pharmacies is climbing the fastest on clinical credibility transfer.
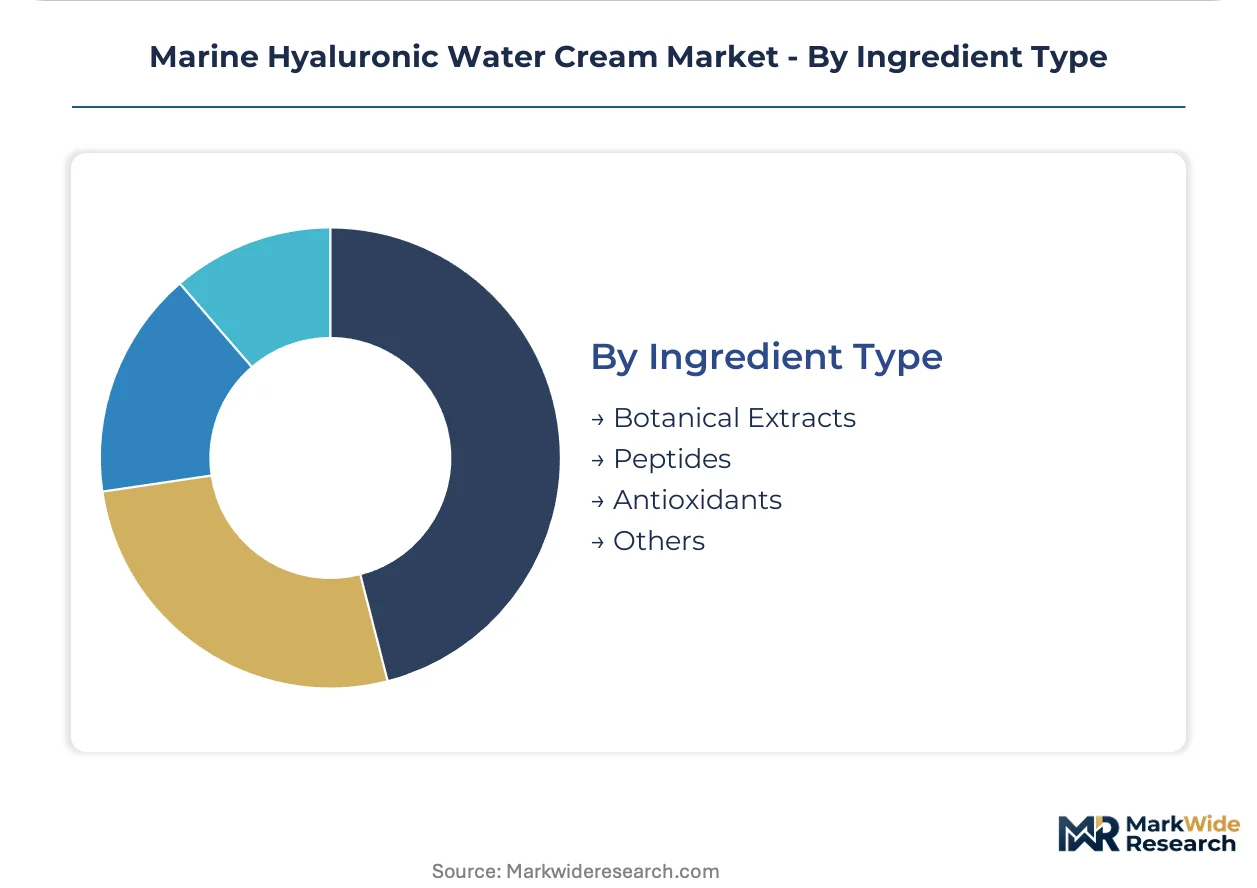
Ingredient Type:
Active classification shapes regulatory pathway complexity and clean beauty positioning.
- Botanical Extracts:Cold-processed brown seaweed polysaccharides from Laminaria and Undaria harvests preserve bioactive integrity. ISO 16128 natural-content thresholds influence sourcing specifications for clean beauty claims.
- Peptides:Signal molecules for collagen support command premium pricing in professional spa channels.
- Antioxidants:Marine-derived ferulic acid and fucoxanthin variants address oxidative stress positioning.
- Others:Niacinamide and ceramide co-actives round out barrier-repair formulations.
Botanical Extracts dominates raw material sourcing. Peptides is gaining share fastest on professional channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Japan demonstrate the lowest price elasticity for marine hyaluronic water cream, while consumers in India and Southeast Asia remain highly sensitive to premium positioning. This demand-elasticity contrast shapes where manufacturers concentrate fermentation capacity versus where they deploy mass-market SKUs.
South Korea
Seoul-Incheon manufacturing corridors anchor global supply for biofermented marine polysaccharides, with contract manufacturers deploying membrane filtration for sub-50 kDa hyaluronic acid fractions. MFDS maintains stringent safety evaluations for fermented marine extracts, extending registration cycles but concentrating production among established players with dedicated regulatory affairs teams. Busan-Ulsan clusters specialize in cold-processed Undaria and Laminaria harvesting for clean-label export formulations.
United States
Houston and Los Angeles dermatology practices drive professional-channel adoption of breathable gel cream textures for post-laser recovery protocols. FDA cosmetic labeling requirements govern ingredient disclosure thresholds and hydration claim substantiation, while California's state-level microplastic restrictions force reformulation toward marine-derived rheology modifiers. Pacific Northwest coastal regions supply cold-water seaweed biomass for domestic extraction operations.
Germany
Pharmacy-first placement with clinician endorsement programs anchors trust-building in Berlin and Munich medical spa channels. REACH registration requirements for novel marine-derived polymers tighten substance dossier standards, with ECHA demanding extended aquatic toxicity data that extends compliance timelines. Hamburg and North Rhine-Westphalia fermentation houses maintain pre-validated regulatory packages for EU market access.
France
Brittany coastal harvests concentrate premium Laminaria sourcing for luxury positioning, though climate-driven volatility exposes supply chains to harvest risk. ANSM enforces cosmetic safety standards aligned with EU Cosmetics Regulation animal-testing bans, pushing formulators toward marine-derived alternatives. Paris-Île-de-France headquarters anchor regional marketing and distribution control for premium department store channels.
Japan
Tokyo-Osaka metropolitan corridors sustain demand for barrier-repair night creams with elevated polysaccharide density targeting senior demographics. METI oversees industrial biotechnology standards for marine fermentation scale-up, while PMDA maintains pharmaceutical-grade oversight for clinical-channel products. Kansai region manufacturers specialize in gender-neutral packaging for professionalizing men's grooming segments.
Marine Hyaluronic Water Cream Market Competitive Landscape
Prestige heritage houses and derm-channel credibility builders split the market along price-architecture lines, with fermentation-science specialists occupying a third strategic position. Consolidation concentrates among conglomerate-owned portfolios that leverage shared bioreactor infrastructure across multiple skincare lines. The dominant competitive moves involve captive supply integration into seaweed harvesting operations and subscription-based direct-to-consumer channel displacement of wholesale intermediaries.
Within the prestige heritage tier, La Mer anchors positioning through proprietary fermentation technology claims, while Shiseido Company Limited exemplifies controlled distribution architecture across Asian department store counters. CeraVe occupies the derm-channel credibility position through pharmacy-first placement strategies. These three entities represent the archetypal split between exclusivity-driven, distribution-controlled, and clinician-endorsed market approaches.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder |
| Neutrogena |
| La Mer |
| Clinique |
| Shiseido Company Limited |
| CeraVe |
| Dr. Jart+ |
| Tatcha |
| Others |
Value Network & Pricing Analysis
Seoul-Incheon manufacturing corridors anchor global fermentation capacity for marine polysaccharides, with bioreactor utilization rates directly translating to downstream pricing power for premium hyaluronic acid fractions. Contract manufacturers with dedicated MFDS-compliant facilities command margin premiums over commodity hyaluronic acid suppliers, while capacity constraints in cold-processed seaweed extraction propagate through to finished product pricing tiers.
Pricing Analysis
Aftermarket service revenue from personalized skin-analysis consultations drives lifetime customer value capture for premium marine hyaluronic water cream brands. Three-tier pricing structure across prestige heritage, derm-channel credibility, and mass-market economy levels segments buyers by clinical endorsement access and fermentation technology provenance. Cost compression in mass-market tiers intensifies as private-label entrants replicate gel cream textures without biofermented active claims. Pharmacy-first clinician-endorsed brands exhibit lowest price elasticity, while online direct-to-consumer subscribers demonstrate moderate sensitivity to subscription frequency adjustments.
Supply Chain Analysis
Premium Laminaria and Undaria seaweed biomass feeds from coastal harvest zones in South Korea, France, and Japan into downstream fermentation and extraction operations. Cold-processed polysaccharide concentrates, GMP-compliant bioreactor infrastructure, and cross-linked sodium hyaluronate fractions constitute critical input dependencies. Single-source vulnerability concentrates in Seoul-Incheon contract manufacturing clusters, where dedicated regulatory affairs capabilities limit rapid supplier switching. Distribution runs through pharmacy networks in Germany and the United States, direct-to-consumer subscription platforms in North America, and department store counters across Asian metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine hyaluronic water cream markets track cyclical recovery patterns tied to professional dermatology channel expansion, with post-procedure hydration protocols driving recurring demand across economic phases.
For Market Incumbents: Entrench positioning through captive supply integration into Brittany and Busan-Ulsan seaweed harvesting operations, securing climate-resilient biomass access against harvest volatility. Deepen clinical credibility transfer by expanding sampling networks through Los Angeles and Houston dermatology practices, defending margin architecture against direct-to-consumer disintermediation threats. For New Entrants and Emerging Players: Pursue white-space penetration in professionalizing men's grooming segments across Japan and the United States, where gender-neutral packaging and non-greasy gel cream textures remain underdeveloped. Target pharmacy-first placement with clinician endorsement programs as the most penetrable channel architecture, leveraging ISO 16128 clean beauty positioning to differentiate from established fermentation-science specialists. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with proprietary fermentation capabilities and captive seaweed supply. Five-to-ten year viability rests on backward integration depth and regulatory package pre-validation across EU REACH and South Korean MFDS frameworks. Monitor California and New York state-level microplastic restriction enforcement as inflection indicators for forced substitution demand toward marine-derived rheology modifiers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Seaweed Supply Integration | Backward control over Brittany and Busan-Ulsan harvest zones insulates against climate-driven raw material volatility. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture displaces department store wholesale markups in North American and European markets. |
| Clinician Endorsement Program Expansion | Pharmacy-first sampling networks through German and US dermatology practices anchor trust-based pricing power. |
| Sub-50 kDa Hyaluronic Acid Fraction Development | Membrane filtration investment for post-laser recovery protocols captures professional channel premium positioning. |
| Gender-Neutral Packaging Repositioning | Non-greasy gel cream textures open underdeveloped men's grooming segments in Japan and the United States. |
Research Methodology
A standing panel of fermentation science directors, regulatory affairs leads at marine biotechnology firms, dermatology clinic procurement managers, and pharmacy category buyers provided ongoing calibration throughout the study. Primary interviews with contract manufacturers in Seoul-Incheon and Busan-Ulsan clusters combined with secondary validation from MFDS registration databases, EU REACH substance dossiers, FDA cosmetic labeling guidance, and ISO 16128 natural content standards. Bottom-up volume triangulation across product type, end user demographic, and distribution channel dimensions converged with top-down value estimates from trade flow analysis and retail audit data.
Scenario-bracketing around regulatory compliance timeline friction and climate-driven harvest volatility bounded the projection range across the analysis window. Segmentation dimensions modeled include formulation texture tier, demographic targeting archetype, channel economics structure, ingredient classification, and regional regulatory cluster. CAGRs derived from weighted average growth contributions across these segments, with specific inputs for professional channel adoption rates in Germany and the United States, and direct-to-consumer subscription penetration in North American markets.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and cross-border logistics cost trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding MFDS evaluation cycle durations and EU Cosmetics Regulation enforcement consistency. Cross-checking against customs trade data for marine polysaccharide concentrate flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Asia-Pacific Face Compact Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
Detox Face Oil Market
Cosmetics & Skincare
Cold Pressed Soap Market
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
Facial Serum Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Eye Shadow Stick Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market