
 Smart Electric Toothbrush Market | 2026-2036
Smart Electric Toothbrush Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Electric Toothbrush Market Insights
Retail pharmacy and dental clinic procurement is consolidating around fewer large-format buyers with national stocking agreements. Procter & Gamble leverages its shelf-space dominance in mass retail to sustain volume throughput across rechargeable lines. Colgate-Palmolive anchors its position through professional channel partnerships with dental practices. Xiaomi competes on manufacturing scale, shipping sonic units through direct-to-consumer platforms at price points that undercut Western incumbents.
A smart electric toothbrush integrates microprocessor-controlled brush heads with pressure sensors, accelerometers, and Bluetooth modules to capture brushing duration, coverage mapping, and gum pressure data for user feedback. These devices typically operate at sonic frequencies between 20,000 and 40,000 strokes per minute, with lithium-ion battery architectures supporting two- to four-week charge cycles. Rechargeable product types command the dominant margin pool due to higher replacement brush head attach rates and subscription attach potential. Sonic technology leads unit shipments while smart sensors represent the fastest-expanding value segment as AI-powered coaching algorithms mature. Adults constitute the core target user base, though children-oriented models with gamified compliance tracking are gaining traction among parents.
The FDA regulates smart electric toothbrushes as Class I medical devices, requiring 510(k) premarket notification for units claiming plaque removal efficacy, while the FCC governs wireless transmission protocols for Bluetooth-connected models. The EU Medical Device Regulation imposes additional clinical documentation burdens on manufacturers seeking CE marking for therapeutic claims, directly shaping R&D allocation and market access timelines. Stakeholders must monitor evolving cybersecurity standards for connected health devices as regulators in multiple jurisdictions draft mandatory vulnerability disclosure requirements.
Market Dynamics
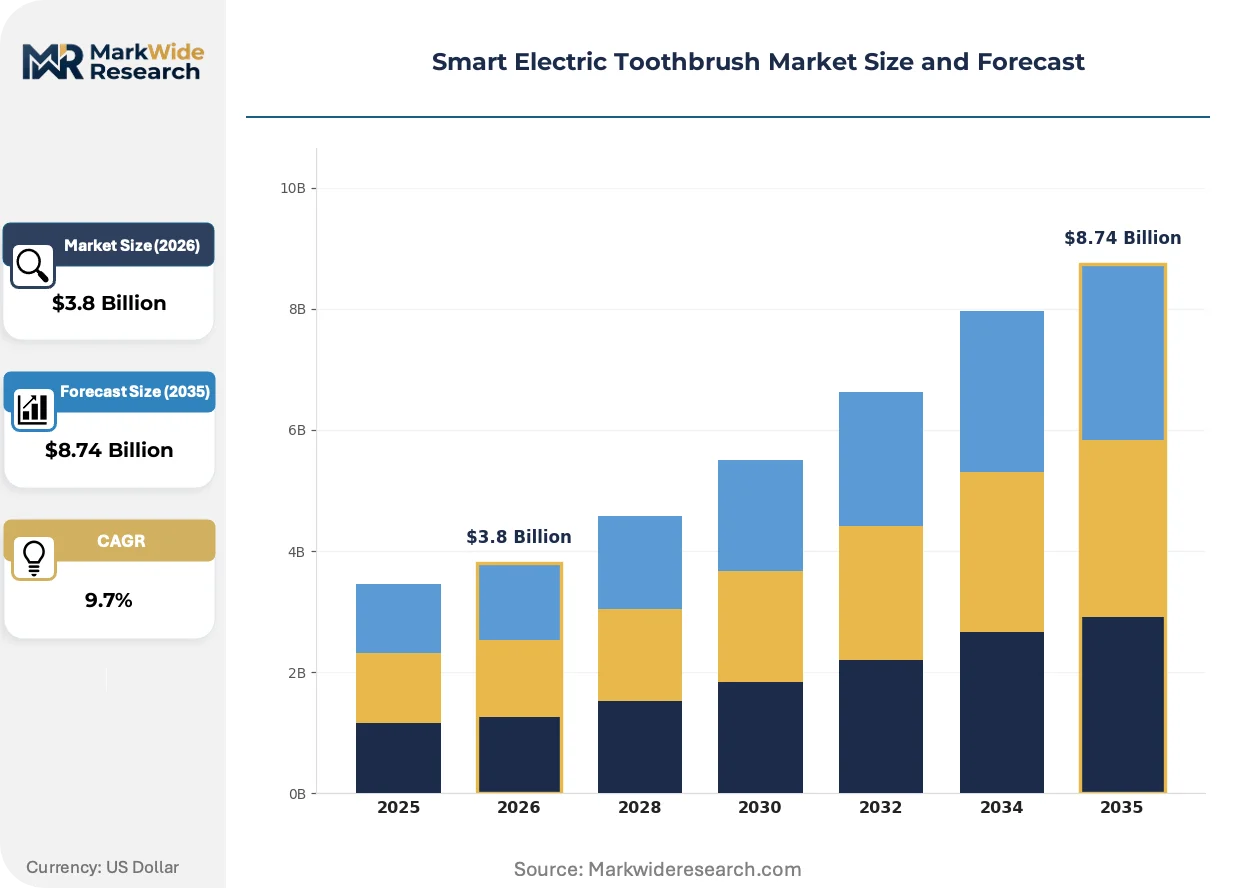
Dental clinic procurement consolidation and employer wellness program subsidy expansion are compressing price tolerance while accelerating volume throughput for connected oral care devices. The FDA's streamlined 510(k) pathways for Bluetooth-enabled Class I medical devices have lowered regulatory friction for sensor-integrated entrants.
Growth Catalysts
- Preventive care reimbursement:Employer-sponsored wellness programs in the United States now subsidize smart hygiene products, converting discretionary purchases into covered benefits.
- Bluetooth Low Energy maturation:FCC-cleared wireless modules enable real-time brushing feedback without hardware cost inflation, embedding coaching algorithms into mid-tier price bands.
- Orthodontic practice endorsement:Dental clinics increasingly prescribe connected devices to patients in post-treatment retention phases, creating professional channel pull-through.
Market Restraints
- Lithium-ion supply concentration:Battery cell sourcing clusters in East Asian manufacturing hubs expose brands to input volatility and logistics bottlenecks.
- EU MDR documentation burden:CE marking for therapeutic plaque-removal claims requires clinical evidence packages that extend R&D timelines and compress margin for smaller entrants.
- Manual brush substitution persistence:Price-sensitive households in emerging markets continue treating powered cleaning as non-essential, capping category penetration ceilings.
Strategic Opportunities
- Pediatric gamification segment:Children-oriented models with compliance-tracking apps address parental anxiety around brushing duration, opening household multi-unit purchasing.
- Subscription brush-head economics:Direct-to-consumer replenishment platforms capture recurring revenue streams while reducing retail margin leakage.
- AI coaching algorithm licensing:Sensor data analytics providers can white-label behavioral feedback engines to dental insurance platforms seeking engagement tools.
Industry Challenges
- Cybersecurity disclosure compliance:Draft mandatory vulnerability reporting requirements for connected health devices in multiple jurisdictions force firmware audit investments.
- Pressure sensor calibration precision:Manufacturing variance in gum-force detection algorithms risks false-positive feedback that erodes user trust and invites liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Electric Toothbrush Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-Powered, Rechargeable, Manual, Water-Resistant Technology: Sonic Technology, Oscillating-Rotating, Ultrasonic, Smart Sensors Target User: Adults, Children, Seniors, Individuals with Disabilities Distribution Channel: Online Retail, Supermarkets, Drugstores, Dental Clinics |
| Companies Covered | Koninklijke Philips N.V., Procter & Gamble, Colgate-Palmolive Company, Water Pik, Inc., FOREO AB, Oclean Technology Co., Ltd., Xiaomi Corporation, Fairywill Technology Co., Ltd., Quip NYC, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Electric Toothbrush Market Trends and Innovations
Sensor fusion and on-device inference are compressing the latency between brushing action and personalized feedback, shifting competitive advantage from hardware specifications to software coaching quality.
Accelerometer-gyroscope fusion combined with pressure transducers is automating real-time coverage mapping and stroke correction guidance. Dental clinics deploying these units for patient home-monitoring report higher compliance adherence than paper-based logging systems. The technology is automating the transition from passive brushing timers to active oral health coaching, collapsing the distinction between consumer appliance and preventive medical device.
The EU Medical Device Regulation's clinical documentation requirements for therapeutic claims are forcing manufacturers to either narrow marketing language or invest in controlled trials. Brands seeking CE marking for plaque-reduction assertions now face 12-18 month evidence compilation timelines. Sonic technology platforms with existing clinical dossiers are widening their regulatory moat against sensor-focused challengers lacking historical trial data.
Employer benefit administrators are unbundling smart toothbrush subsidies from traditional dental insurance, creating standalone preventive technology allowances. Large-format retail pharmacy chains are responding with dedicated connected oral care planogram sections, displacing general merchandise placement. The United States exhibits the clearest channel bifurcation, with mass retail serving price-conscious rechargeable buyers while dental clinics steer patients toward premium sensor-integrated models.
Smart Electric Toothbrush Market Segmentation
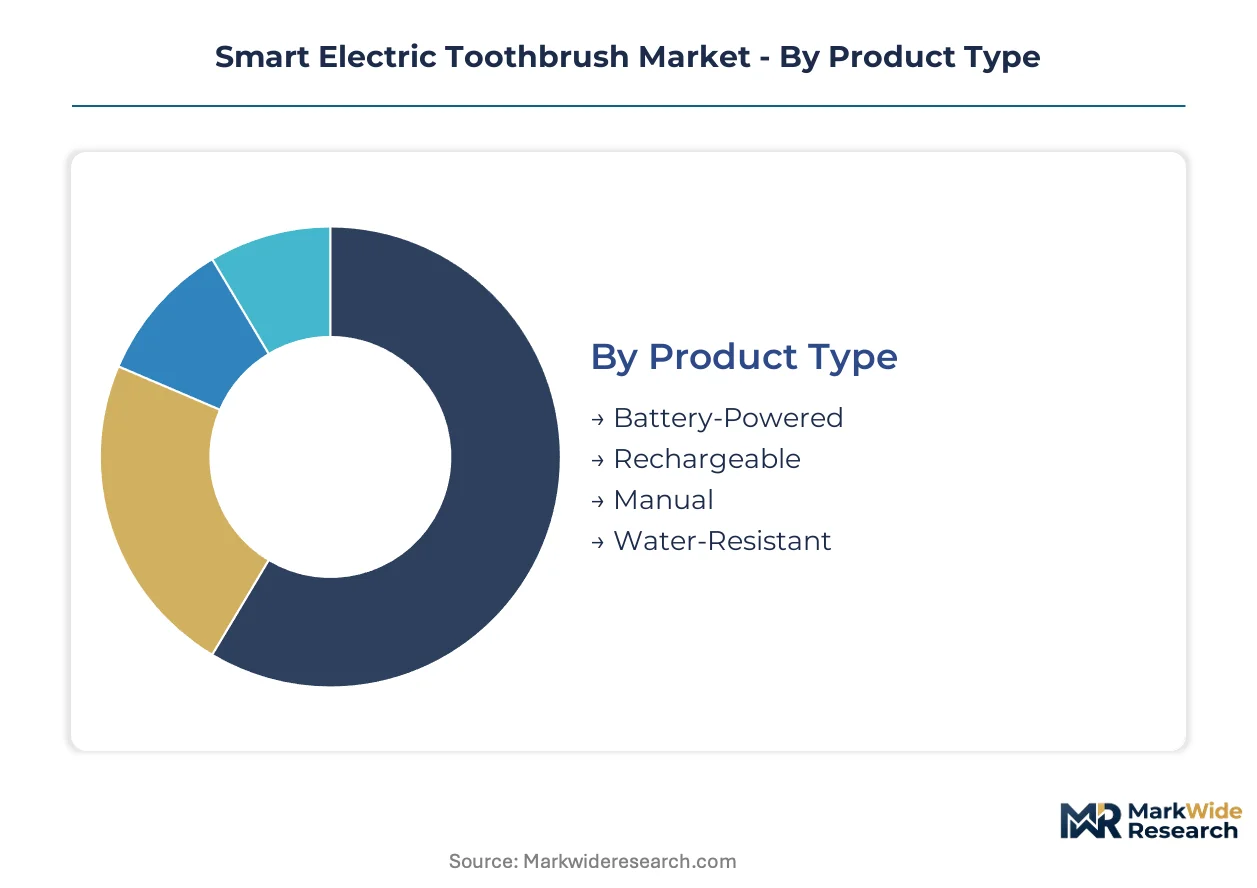
Segmentation in smart electric toothbrushes reveals how hardware specifications, user physiology, and channel economics create distinct margin pools. Manufacturers calibrate sensor density, battery architecture, and coaching software to match procurement patterns across retail and professional channels.
Product Type:
Rechargeable lithium-ion architectures dominate engineering roadmaps due to replacement attach economics and subscription potential.
- Rechargeable:Lithium-ion battery systems support two- to four-week charge cycles and generate recurring revenue through replacement brush head subscriptions. Dental clinics in the United States prescribe these units for post-orthodontic retention patients, driving professional channel volume.
- Battery-Powered:Disposable cell configurations trade operating longevity for lower entry price points, appealing to travel-oriented users and emerging market first-time buyers facing lithium-ion supply volatility.
- Manual:Non-powered designs retain share in price-sensitive households and regions with unreliable electricity infrastructure, though they lack data capture capabilities.
- Water-Resistant:IPX7-rated sealing enables shower use and reduces warranty claims from moisture ingress, a specification dental insurance platforms increasingly require for subsidy eligibility.
Mature deployment sits with Rechargeable. Newer deployment is concentrated in Water-Resistant as durability standards tighten.
Technology:
Frequency generation methods and sensor fusion capabilities determine clinical credibility and pricing authority.
- Sonic Technology:Generates 20,000 to 40,000 strokes per minute through magnetic drive systems, with existing clinical dossiers satisfying FDA 510(k) and EU MDR requirements for plaque-removal claims. Established trial data widens regulatory moats against sensor-focused challengers.
- Smart Sensors:Accelerometer-gyroscope fusion with pressure transducers automates real-time coverage mapping and stroke correction, collapsing latency between brushing action and personalized feedback. AI coaching algorithm maturation is expanding this segment fastest.
- Oscillating-Rotating:Mechanical brush head rotation remains prevalent in value-tier retail placements, though it lacks the data capture capabilities driving employer wellness program subsidies.
- Ultrasonic:Piezoelectric transducers operate above audible frequencies, requiring specialized manufacturing that limits supplier diversity and concentrates production in East Asian electronics clusters.
Volume leadership belongs to Sonic Technology. Steepest expansion trajectory is Smart Sensors as behavioral feedback engines mature.
Target User:
Physiological and cognitive factors shape interface design, compliance mechanisms, and parental purchasing triggers.
- Adults:Constitute the core revenue base, with demand concentrating among employer-sponsored wellness program participants in the United States seeking subsidized preventive devices.
- Children:Gamified compliance tracking with smartphone app integration addresses parental anxiety around brushing duration, opening household multi-unit purchasing opportunities.
- Seniors:Arthritis-friendly grip geometries and simplified interfaces serve aging populations, though Medicare reimbursement gaps limit penetration.
- Individuals with Disabilities:Adaptive handle designs and voice-coaching integration address motor control limitations, a segment dental practices increasingly serve through accessibility-focused procurement.
Revenue concentration sits with Adults. Emerging deployment is concentrated in Children as parental monitoring demand intensifies.
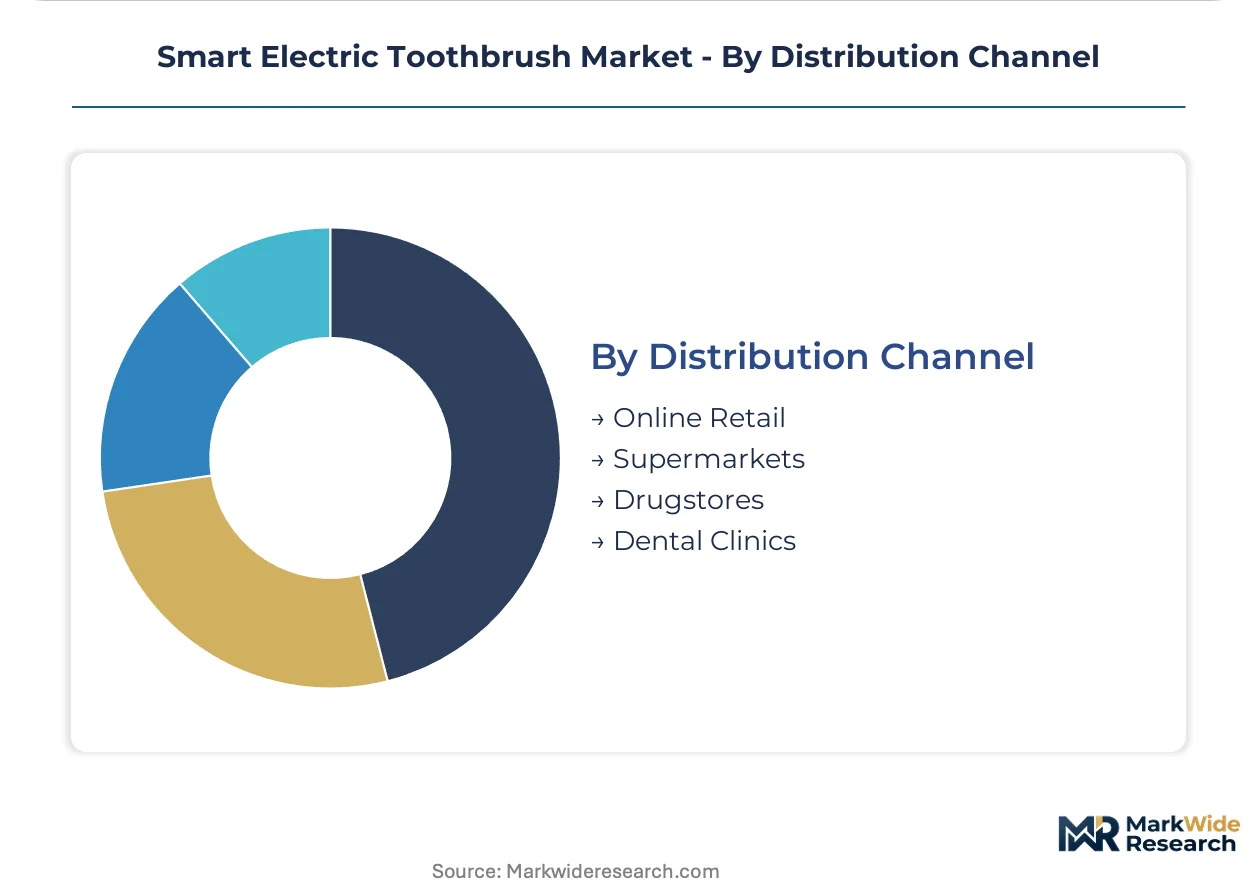
Distribution Channel:
Channel selection determines margin capture, customer acquisition cost, and regulatory documentation burden.
- Dental Clinics:Professional endorsement generates patient pull-through for premium sensor-integrated models, with orthodontic practices prescribing connected devices for retention-phase compliance monitoring.
- Online Retail:Direct-to-consumer platforms enable subscription brush-head economics and bypass retail margin leakage, though cybersecurity disclosure requirements for connected health devices raise firmware audit costs.
- Supermarkets:Mass retail serves price-conscious rechargeable buyers through shelf-space dominance, with dedicated connected oral care planogram sections displacing general merchandise placement.
- Drugstores:Pharmacy chains consolidate procurement around national stocking agreements, compressing price tolerance while accelerating volume throughput for mid-tier Bluetooth-enabled units.
Margin capture sits with Dental Clinics. Volume scaling is concentrated in Online Retail as replenishment platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer wellness program subsidies in the United States concentrate demand for connected oral care devices, while dental clinic procurement networks in Germany and China extend professional channel reach for sensor-integrated models.
United States
Employer-sponsored wellness programs subsidize smart hygiene products through standalone preventive technology allowances, converting discretionary purchases into covered benefits. The FDA's streamlined 510(k) pathways for Bluetooth-enabled Class I medical devices reduce regulatory friction for sensor-integrated entrants. Greater Boston hosts dental technology clusters where orthodontic practices prescribe connected devices for post-treatment retention compliance monitoring.
Germany
EU MDR documentation requirements for therapeutic plaque-removal claims compress margin for smaller entrants lacking historical clinical dossiers. CE marking mandates 12-18 month evidence compilation timelines that widen regulatory moats for established sonic technology platforms. Bavaria's precision manufacturing base supplies pressure sensor calibration components to brands seeking gum-force detection accuracy.
China
Direct-to-consumer platforms ship sonic units at price points undercutting Western incumbents, capturing volume in emerging market first-time buyer segments. MIIT governs wireless transmission standards for Bluetooth-connected models while GB standards address lithium-ion battery safety. Shenzhen's electronics manufacturing clusters concentrate toothbrush motor and sensor module production.
Japan
PMDA medical device regulations align with international standards while METI promotes connected health device adoption through aging population initiatives. Tokyo's dental clinic networks increasingly prescribe smart sensors for senior patients requiring arthritis-friendly grip geometries. Kansai manufacturing bases supply piezoelectric transducers for ultrasonic frequency platforms.
United Kingdom
NHS dental contract reforms create procurement opportunities for preventive technology in public health settings. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR documentation burdens for therapeutic claims. London's employer benefit administrators unbundle smart toothbrush subsidies from traditional dental insurance, creating standalone allowances.
Smart Electric Toothbrush Market Competitive Landscape
United States and Western European producers anchor the premium sensor-integrated tier; East Asian specialists hold manufacturing scale advantages in sonic frequency platforms. The vendor base stratifies across three tiers: multinational consumer health conglomerates with dental clinic partnerships, direct-to-consumer platforms with subscription economics, and contract manufacturers supplying private-label retail placements. Two dominant competitive moves define current positioning: dental practice endorsement programs that generate professional channel pull-through, and direct-to-consumer replenishment platforms that capture recurring brush-head revenue while bypassing retail margin leakage.
Within the multinational conglomerate tier, Koninklijke Philips N.V. and Procter & Gamble exemplify established regulatory dossiers and shelf-space dominance. Among East Asian scale producers, Xiaomi Corporation occupies a position representing manufacturing cost advantages through direct-to-consumer distribution. Colgate-Palmolive Company anchors the professional channel partnership archetype, with dental clinic relationships generating patient prescription pull-through for premium models.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Procter & Gamble |
| Colgate-Palmolive Company |
| Water Pik, Inc. |
| FOREO AB |
| Oclean Technology Co., Ltd. |
| Xiaomi Corporation |
| Fairywill Technology Co., Ltd. |
| Quip NYC, Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive production of lithium-ion battery cells and pressure sensor modules in Shenzhen and Dongguan manufacturing clusters anchors both cost structures and pricing power for smart toothbrush producers. East Asian vertical integration into sonic motor and Bluetooth module fabrication compresses input costs for scale players while exposing Western brands to logistics volatility and tariff exposure.
Pricing Analysis
Volume leadership concentrates in mid-tier rechargeable sonic units while margin capture sits with premium sensor-integrated models prescribed through dental clinics. Three-tier pricing structure across premium, standard, and economy levels separates subscription-enabled coaching platforms from basic timer-equipped devices. Cost compression in the battery-powered tier is intensifying because lithium-ion supply volatility pushes emerging-market buyers toward disposable cell alternatives. Price-sensitive households in developing economies exhibit highest elasticity, while employer-subsidized wellness program participants in the United States show lowest sensitivity to sticker price.
Supply Chain Analysis
Dual-sourcing requirements for pressure sensor calibration components and lithium-ion battery cells are becoming standard procurement policy among large-format retail pharmacy chains and dental clinic networks. Manufacturing gravity centers on China for toothbrush motors and sensor modules, South Korea for advanced battery cell chemistry, and Japan for piezoelectric transducers in ultrasonic platforms. Supply chain risk concentrates in single-source vulnerability for Bluetooth Low Energy chipsets subject to FCC and MIIT certification delays. Distribution runs through direct-to-consumer platforms capturing subscription brush-head economics alongside dental clinic professional channels generating prescription pull-through.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory dossier depth and subscription platform scale, with EU MDR documentation burdens and cybersecurity audit costs forcing subscale sensor-integrated entrants toward acquisition or exit.
For Market Incumbents: Acquire clinical trial data assets and existing 510(k) clearances to widen regulatory moats against sensor-focused challengers lacking historical plaque-reduction evidence. Deepen backward integration into pressure sensor calibration component production to reduce manufacturing variance liability. Anchor channel control through exclusive dental clinic partnership agreements that generate patient prescription lock-in for premium models.
For New Entrants and Emerging Players: Begin with white-label manufacturing partnerships supplying private-label retail placements for supermarket and drugstore chains seeking mid-tier Bluetooth-enabled units. Target the pediatric gamification segment where parental anxiety around brushing compliance creates household multi-unit purchasing opportunities with lower regulatory documentation burdens than therapeutic claims. Pursue direct-to-consumer launch with subscription brush-head replenishment economics bypassing retail margin leakage.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational consumer health conglomerates seeking sensor data analytics capabilities and dental clinic channel relationships. Long-term viability favors targets with existing FDA 510(k) clearances and proven AI coaching algorithm engagement metrics over hardware-only manufacturers. Watch employer wellness program subsidy expansion rates as the inflection indicator for category conversion from discretionary to covered benefit status.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Development | Direct-to-consumer replenishment captures recurring revenue while reducing retail margin leakage to pharmacy chains. |
| Dental Clinic Partnership Program | Professional endorsement generates patient prescription pull-through for premium sensor-integrated models in post-orthodontic retention. |
| AI Coaching Algorithm Licensing | White-label behavioral feedback engines enable penetration of dental insurance platforms seeking member engagement tools. |
| EU MDR Clinical Documentation Investment | Controlled trial data packages satisfy CE marking requirements for therapeutic plaque-removal claims in European markets. |
| Cybersecurity Firmware Audit Compliance | Mandatory vulnerability disclosure preparation for connected health devices reduces liability exposure across multiple jurisdictions. |
Research Methodology
Regulatory filings with the FDA and FCC, EU Medical Device Regulation documentation databases, and customs trade records formed the secondary backbone for supply chain and competitive positioning analysis. Primary interviews with dental clinic procurement managers, orthodontic practice administrators, employer benefits directors, and connected device firmware engineers were combined with secondary validation from hospital procurement databases and GPO contracts. Bottom-up unit shipment modeling and top-down wellness program subsidy allocation data were triangulated to verify market size estimates.
Historical trendline analysis of rechargeable unit attach rates and replacement brush head subscription conversion informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, technology platform, target user physiology, and distribution channel economics. CAGRs were derived from regression analysis of employer subsidy expansion curves and Bluetooth module cost decline trajectories. Forecast inputs incorporated lithium-ion battery supply volatility indices and dental clinic procurement consolidation patterns.
Cybersecurity disclosure mandate timing, EU MDR evidence compilation timeline extensions, and employer wellness program subsidy eligibility criteria changes are the dominant revision risks to the outlook. Deviation in regulatory audit intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
Global Canes and Walking Sticks Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Shaving Care Market
Personal Grooming Products
Shoe Deodorizer Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
Electric Hair Brush Market
Personal Grooming Products
Latin America Hand Soap Market
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Baby Grooming Kits Market