
 Wet Shave Market | 2026-2036
Wet Shave Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Shave Market Analysis
Mass retail shelf space allocation is reconfiguring as e-commerce subscription models capture recurring revenue from younger male demographics. Procter & Gamble leverages its Gillette manufacturing scale to defend broad retail presence across North American big-box chains. Harry's differentiates through vertical control over blade production and direct digital relationships with subscribers. Edgewell Personal Care anchors the Schick and Wilkinson Sword portfolios in European pharmacies and Asian travel retail corridors.
Wet shaving denotes the practice of removing facial or body hair using water-activated lubrication, typically with a handheld razor featuring one or more exposed blades mounted at a controlled angle to the skin surface. Blade cartridges incorporate polymer lubrication strips containing polyethylene glycol and aloe vera that hydrate upon water contact, reducing friction coefficients below dry shaving alternatives by an order of magnitude. Safety razors and double-edge blades occupy the premium tier of the product type segmentation, where stainless steel construction commands higher per-unit margins and attracts artisanal grooming enthusiasts. Shaving soaps sustain steady demand among professional barbers and salon channels, where lather quality and skin conditioning properties determine repurchase rates.
REACH in Europe mandates full material disclosure for blade coatings and lubrication polymers, while the FDA in the United States regulates razor devices as cosmetic instruments with specific sharpness and corrosion-resistance standards. BIS certification in India enforces dimensional tolerances for imported blade assemblies, creating compliance costs for multinational suppliers. Stakeholders must monitor evolving plastic packaging regulations across multiple jurisdictions, as blade cartridge disposal volumes attract extended producer responsibility frameworks that will reshape cost structures and material substitution timelines.
Market Dynamics
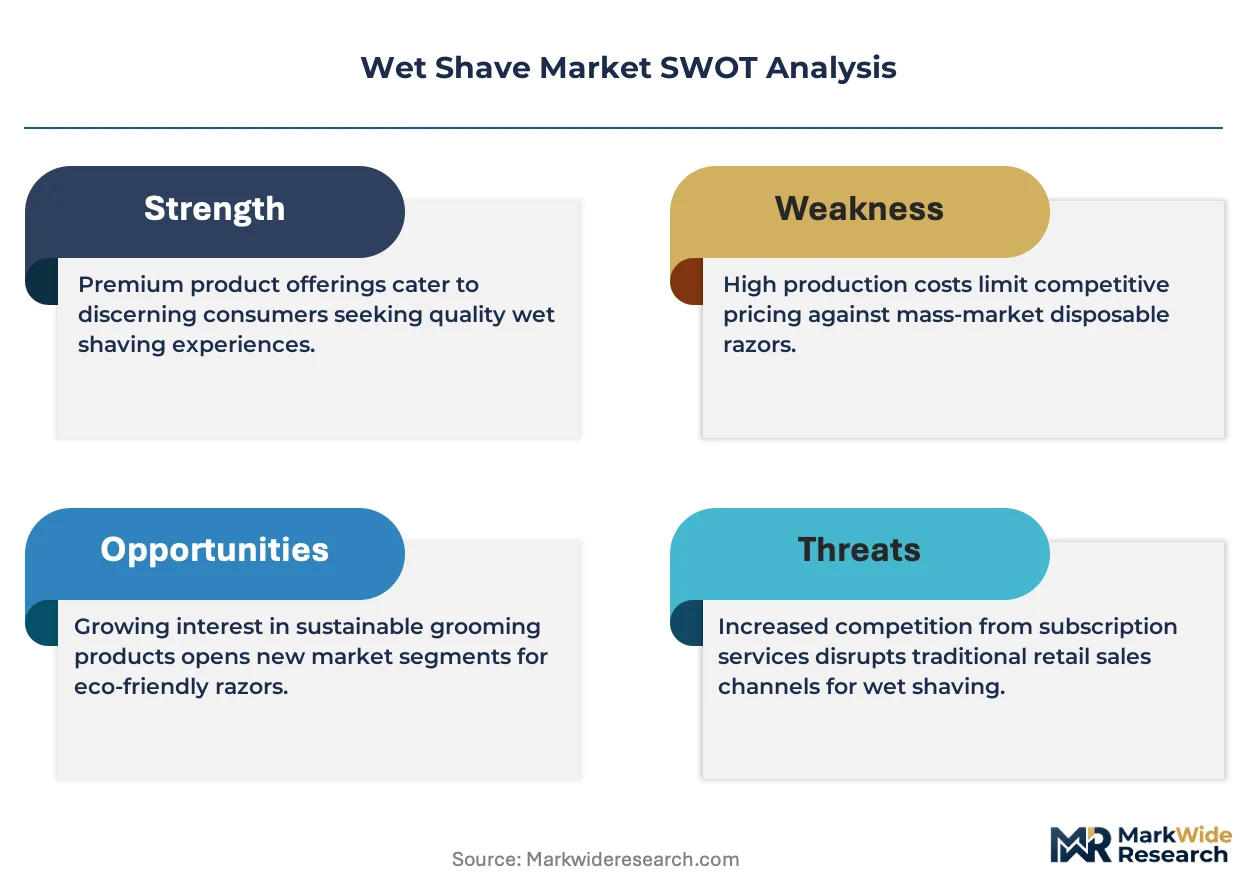
Direct-to-consumer subscription models are compressing traditional retail shelf space allocation, forcing incumbent manufacturers to restructure distribution economics and customer acquisition costs around recurring revenue mechanics rather than point-of-sale velocity.
Growth Catalysts
- REACH compliance mandates:European material disclosure requirements for blade coatings and lubrication polymers are accelerating R&D investment in compliant formulations, creating first-mover advantages for suppliers with pre-certified product lines.
- Barbershop channel expansion:Specialty grooming establishments in the United States are elevating safety razor and shaving soap consumption through experiential service bundling that converts trial into habitual repurchase.
- Stainless steel blade construction:Artisanal wet shave enthusiasts are driving premium tier demand for double-edge blades with superior corrosion resistance and per-unit margin profiles.
Market Restraints
- Polymer input cost volatility:Polyethylene glycol and aloe vera extract prices fluctuate with agricultural commodity cycles, squeezing lubrication strip manufacturing economics.
- Cartridge disposal volume regulation:Extended producer responsibility frameworks across multiple jurisdictions are imposing compliance costs and material substitution timelines on plastic-intensive blade cartridge designs.
- Electric shaving substitution:Battery-powered dry shave devices capture convenience-seeking segments, particularly among younger demographics with lower grooming ritual attachment.
Strategic Opportunities
- Indian BIS certification pathway:Dimensional tolerance enforcement for imported blade assemblies creates localization incentives for manufacturing investment serving South Asian demand concentration.
- Shaving soap formulation innovation:Professional salon channels reward skin-conditioning properties and lather stability, opening premium positioning for specialty chemical suppliers.
- Biodegradable lubrication polymers:Regulatory tailwinds from EU Green Deal packaging directives favor water-activated strips with compostable structural matrices.
Industry Challenges
- Coating chemistry talent scarcity:Blade edge treatment expertise concentrates among aging specialists in Solingen and Sheffield manufacturing clusters, constraining quality replication.
- Multi-jurisdiction packaging compliance:Divergent extended producer responsibility timelines across European member states fragment supply chain standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Shave Market |
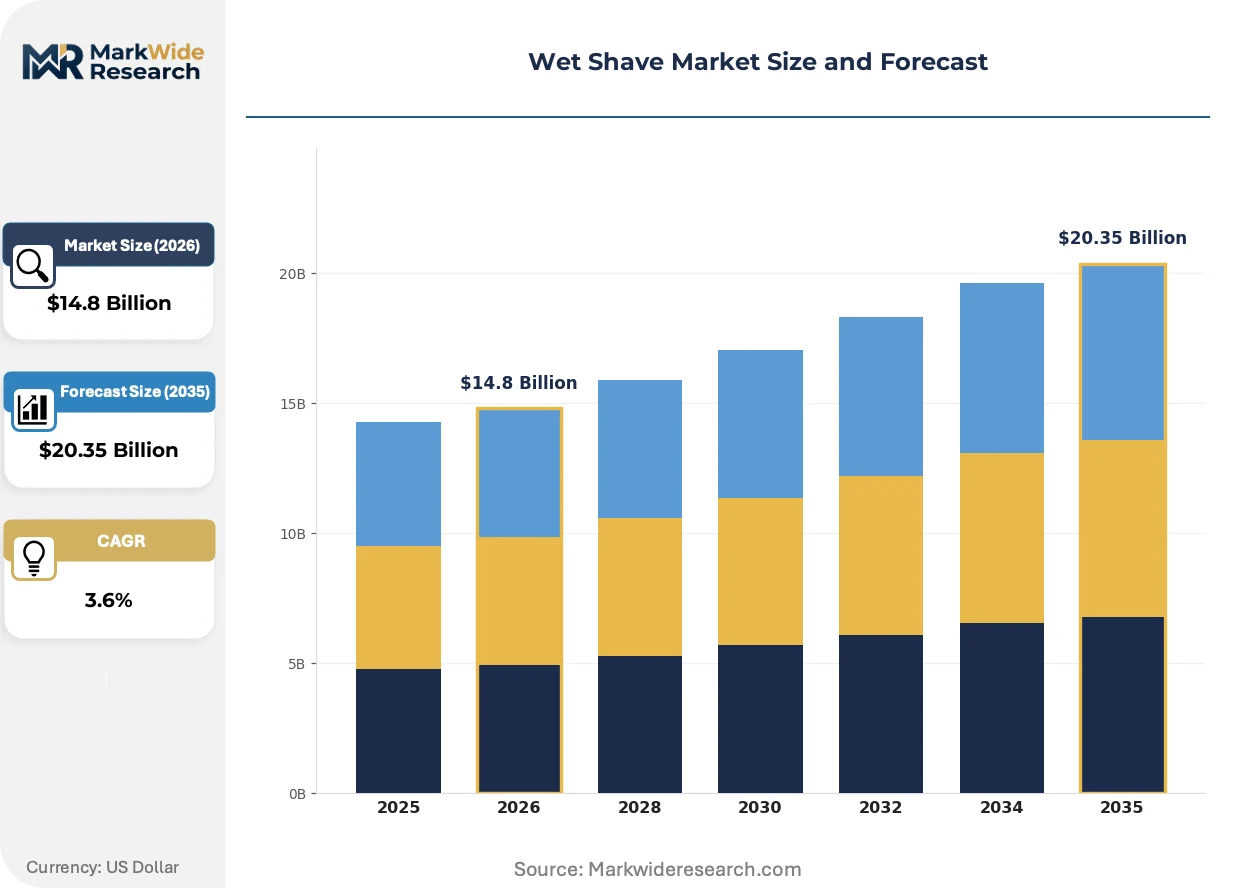
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20.35 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Razors, Straight Razors, Double Edge Blades, Shaving Soaps Material: Stainless Steel, Ceramic, Plastic, Carbon Steel Customer Type: Men, Women, Barbers, Salons Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Philips, Beiersdorf, Procter & Gamble, L'Oreal, Johnson & Johnson, Unilever, Panasonic, Harry's, Edgewell Personal Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Shave Market Emerging Trajectories
Water-activated lubrication chemistry and digital subscription infrastructure are converging to redefine customer lifetime value calculations, while regulatory pressure on material transparency accelerates substitution timelines across the value chain.
Precision-coated ceramic blade edges are rendering obsolete traditional carbon steel constructions in high-frequency professional use environments. Barbershop chains in London and New York are adopting these inserts to reduce replacement cycles and service interruption. The technology is rendering obsolete legacy sharpening maintenance contracts that previously anchored supplier revenue streams.
ECHA enforcement of REACH substance disclosure is tightening documentation requirements for chromium and nickel content in stainless steel alloys. Manufacturers must now submit full supply chain chemical inventories or face market withdrawal penalties. European pharmacy distribution channels are most affected, with several suppliers accelerating reformulation programs to maintain shelf placement.
Subscription box curation is replacing mass retail browsing as the dominant trial mechanism for cartridge razor converts. Direct-to-consumer brands capture demographic cohorts through personalized shipment algorithms and refill timing optimization. This behavioral shift concentrates most visibly among male professionals aged 25-34 in United States metropolitan markets where convenience premium tolerance runs highest.
Wet Shave Market Segmentation
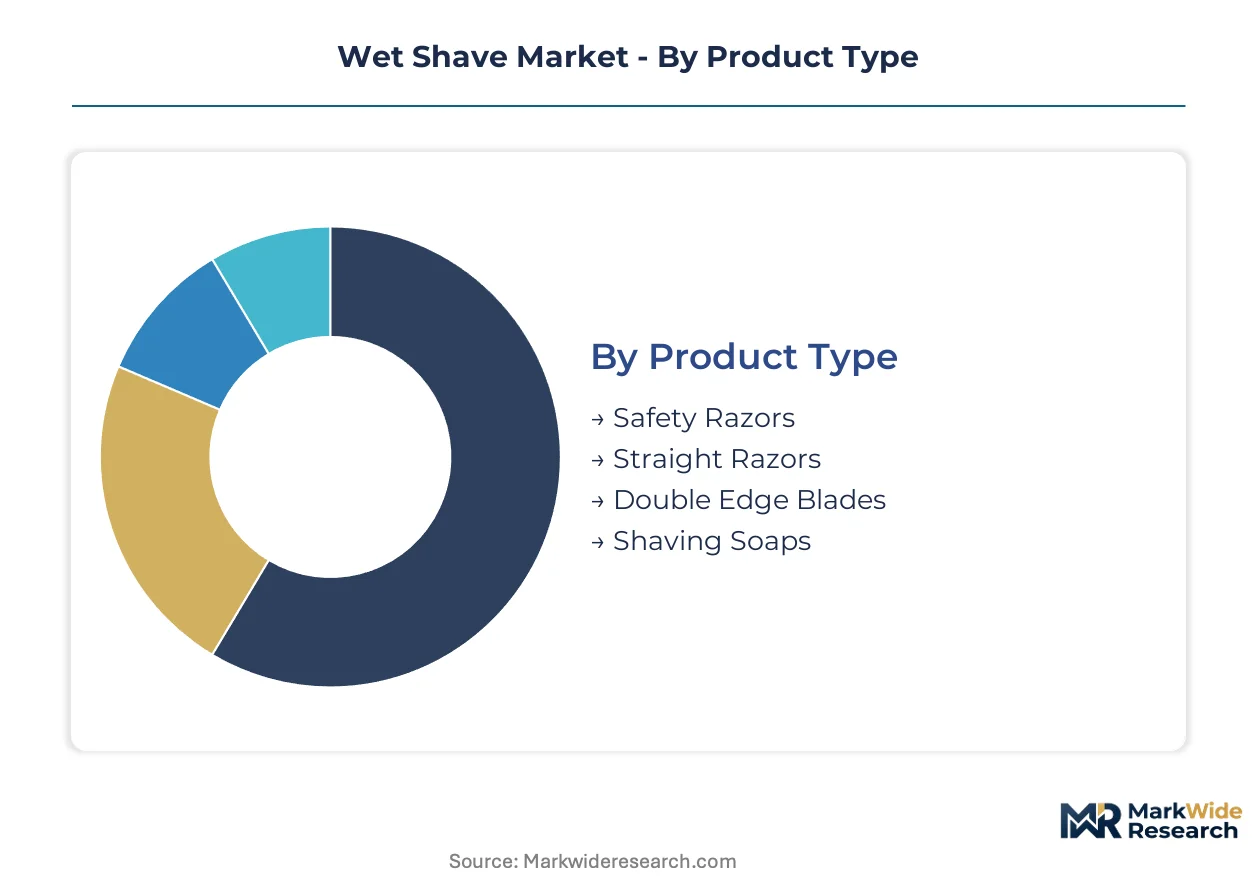
Wet shave segmentation reveals distinct performance tiers across materials and channels. Product architecture and customer ritual intensity determine margin capture and regulatory exposure.
Product Type:
Use-case intensity spans from daily home grooming to professional service environments, with blade geometry and handle ergonomics calibrated to each ritual context.
- Safety Razors:Double-edge blade architecture with butterfly or three-piece head mechanisms dominates artisanal home use. Demand concentrates among United States metropolitan professionals aged 25-40, where subscription curation and barbershop education convert trial into habitual repurchase.
- Double Edge Blades:Stainless steel strips with platinum or chromium coatings deliver 5-7 shaves per edge in controlled-angle holders. German and Japanese manufacturing clusters supply professional barbers in London and New York, where corrosion resistance reduces replacement frequency and service interruption.
- Straight Razors:Hollow-ground carbon steel blades requiring stropping maintenance serve traditional barbershop rituals.
- Shaving Soaps:Tallow or glycerin-based lathering formulations sustain steady professional channel demand.
The dominant share belongs to safety razors, while double edge blades are closing the gap fastest.
Material:
Cost tier stratification separates premium corrosion-resistant alloys from disposable polymer assemblies.
- Stainless Steel:Chromium-nickel alloys meeting ECHA REACH disclosure mandates for blade edges and razor frames command premium positioning. European pharmacy and professional barbershop channels enforce material certification, accelerating supplier consolidation around pre-compliant Solingen and Sheffield producers.
- Ceramic:Zirconium dioxide edges with Rockwell hardness exceeding 90 deliver extended cutting cycles in high-frequency commercial environments. London and New York barbershop chains adopt these inserts to eliminate legacy sharpening contracts and reduce blade replacement labor.
- Carbon Steel:High-carbon alloys requiring oil maintenance serve straight razor traditionalists.
- Plastic:Glass-filled nylon handles and cartridge bodies face mounting extended producer responsibility compliance costs.
Stainless steel holds volume leadership, though ceramic is expanding most quickly in professional tiers.
Customer Type:
Application setting determines product specification, with professional channels demanding instrument-grade durability versus home-use convenience tolerance.
- Men:Facial hair removal rituals drive cartridge and safety razor volume, with digital subscription capture strongest among United States urban professionals.
- Barbers:Service-based consumption elevates double-edge blade and shaving soap demand through experiential bundling that converts client trial into supply repurchase.
- Women:Body hair applications favor cartridge systems with pivoting heads for contour adaptation.
- Salons:Full-service grooming establishments mirror barbershop procurement patterns with added skin-conditioning formulation requirements.
Men constitute the largest addressable base, while barbers are gaining share fastest through service-model expansion.
Distribution Channel:
Channel economics diverge between recurring revenue subscription infrastructure and point-of-sale velocity models.
- Online Retail:Direct-to-consumer platforms with algorithmic replenishment timing capture United States male professionals aged 25-34, where convenience premium tolerance supports subscription lifetime value calculations.
- Specialty Stores:Barbershop supply chains and grooming boutiques curate artisanal safety razors and shaving soaps, with staff expertise converting trial into premium tier adoption.
- Supermarkets:Mass retail shelf space faces compression as e-commerce recurring models erode point-of-sale economics.
- Pharmacies:European pharmacy distribution enforces REACH compliance documentation, filtering supplier access.
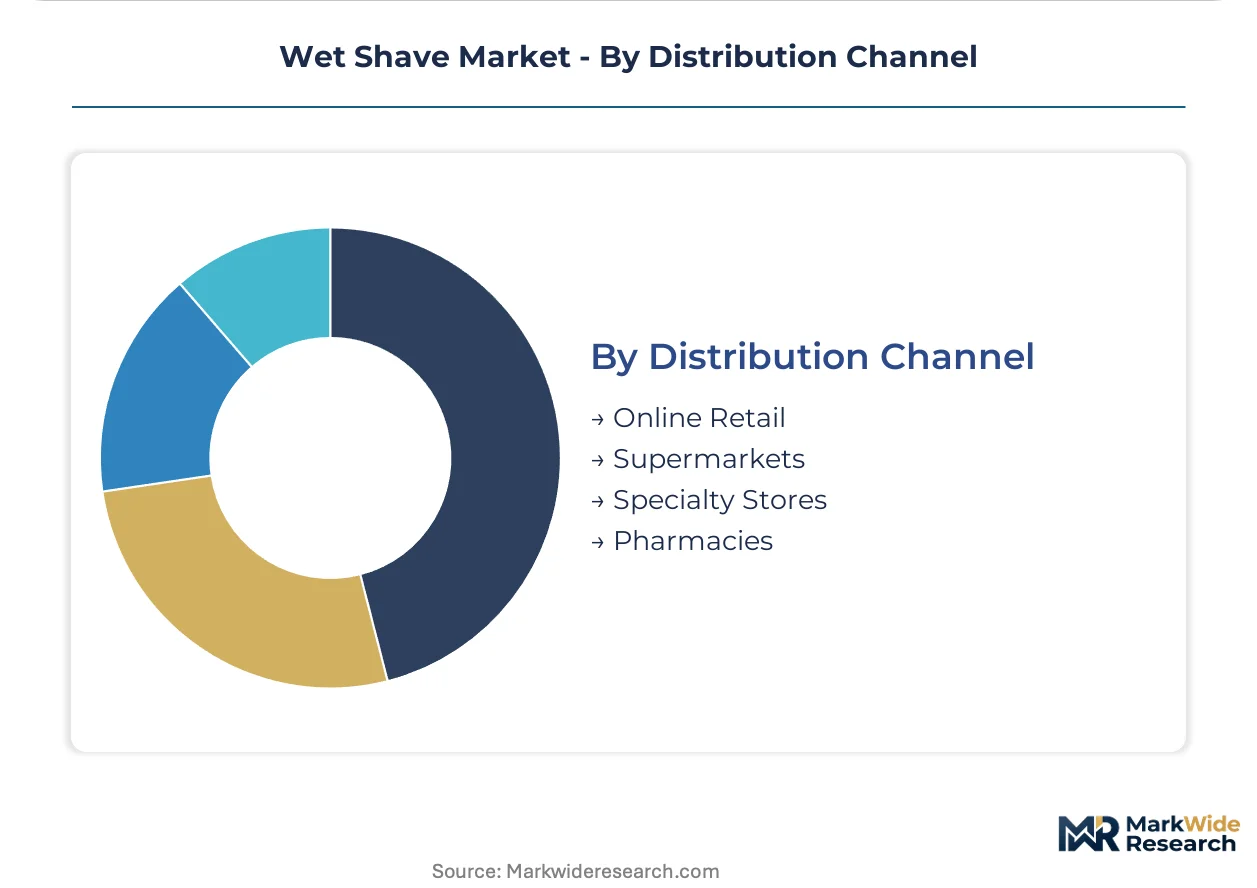
Online retail commands the dominant position, while specialty stores are climbing the fastest through professional channel deepening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance mandates across the European Union are accelerating material certification investments, while direct-to-consumer subscription infrastructure concentrates in United States metropolitan corridors. Asian manufacturing clusters face divergent regulatory timelines as India enforces dimensional standards and China advances dual carbon packaging goals.
United States
Subscription algorithm platforms capture male professionals aged 25-34 in New York and Los Angeles, where convenience premiums sustain recurring revenue models. FDA cosmetic instrument standards govern razor sharpness and corrosion resistance, creating compliance barriers for imported blade assemblies. Chicago and Austin barbershop chains drive safety razor adoption through experiential service bundling that converts client trial into supply repurchase.
Germany
Artisanal wet shave enthusiasts in Berlin and Munich sustain premium demand for double-edge blades with platinum coatings. ECHA enforcement of REACH substance disclosure tightens documentation for chromium and nickel content in Solingen-manufactured stainless steel alloys. The Solingen industrial cluster anchors blade edge treatment expertise, though aging specialist concentrations constrain quality replication for new market entrants.
United Kingdom
Professional barbers in London elevate ceramic blade insert adoption to eliminate legacy sharpening contracts and reduce service interruption. CE marking requirements align with REACH material transparency mandates for European market access. Sheffield retains corrosion-resistant alloy production capacity, with local manufacturers accelerating reformulation programs to maintain pharmacy distribution placement.
India
BIS certification enforces dimensional tolerances for imported blade assemblies, creating localization incentives for manufacturing investment serving South Asian demand. The central government's PLI scheme for consumer goods manufacturing attracts multinational suppliers seeking tariff-advantaged production. Maharashtra and Gujarat industrial corridors concentrate assembly operations for both domestic consumption and regional export.
Japan
Precision manufacturing heritage sustains high-frequency commercial blade production for professional barbershop chains in Tokyo and Osaka. METI standards for product safety and quality certification govern domestic distribution. The Chubu region around Nagoya hosts advanced ceramic processing facilities supplying zirconium dioxide edges with Rockwell hardness exceeding 90 for extended cutting cycles.
Wet Shave Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational consumer goods conglomerates with broad retail presence, direct-to-consumer specialists with vertical production control, and regional pharmacy anchors with compliance-certified portfolios. Incumbents defend position through manufacturing scale and shelf space allocation, while insurgents capture younger demographics via subscription algorithms and digital relationship infrastructure. Dominant competitive moves include backward integration into blade production and geographic expansion through compliance pre-certification in regulated European corridors.
Within the multinational tier, Procter & Gamble and Unilever exemplify scale-driven portfolio breadth across mass retail and pharmacy channels. Harry's occupies a position as the direct-to-consumer archetype, representing vertical control over manufacturing and algorithmic subscriber retention. Edgewell Personal Care anchors the mid-tier specialist vector with European pharmacy and Asian travel retail concentration.
| Leading Market Players |
|---|
| Philips |
| Beiersdorf |
| Procter & Gamble |
| L'Oreal |
| Johnson & Johnson |
| Unilever |
| Panasonic |
| Harry's |
| Edgewell Personal Care |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Singapore container corridor channels stainless steel strip shipments from Solingen and Sheffield to Asian assembly plants, with freight cost volatility transmitting directly into blade cartridge landed costs and reinforcing price stratification between REACH-certified European supply and lower-tier alternatives.
Pricing Analysis
Certification level creates the primary spread, with ECHA REACH-compliant stainless steel alloys commanding premium positioning against uncertified imports. Subscription-based recurring models dominate the United States channel, while European pharmacy distribution enforces documentation premiums. Cost compression in polymer lubrication strips intensifies as polyethylene glycol prices fluctuate with agricultural cycles. Mass retail buyers exhibit highest price sensitivity, whereas professional barbershop procurement tolerates premium tiers for corrosion-resistant ceramic inserts.
Supply Chain Analysis
Tariff exposure between Germany and India dominates supply chain risk calculus as BIS dimensional mandates force localization decisions. Blade edge treatment expertise concentrates in Solingen, Sheffield, and Seki manufacturing clusters. Raw material feeds draw from chromium-nickel alloy suppliers, zirconium dioxide ceramic processors, and polymer formulation specialists. Single-source vulnerability persists in platinum coating chemistry. Distribution runs through direct-to-consumer platforms, specialty barbershop supply chains, and European pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wet shave market is recovering from pandemic-era grooming habit disruption as professional service sector employment rebounds and barbershop channel visitation normalizes.
For Market Incumbents: Insulate manufacturing scale advantages by accelerating REACH pre-certification for blade coating formulations ahead of ECHA enforcement tightening. Capture barbershop channel deepening through experiential service bundling that converts client trial into supply repurchase. Counter electric shaving substitution threat with ceramic blade insert innovation for professional high-frequency environments. For New Entrants and Emerging Players: Pursue Indian BIS certification pathway as localization incentives reshape South Asian supply economics. Target Maharashtra and Gujarat industrial corridors for tariff-advantaged assembly investment. Leverage direct-to-consumer algorithmic replenishment to capture United States metropolitan male professionals aged 25-34 with convenience premium tolerance. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer goods conglomerates seeking portfolio rationalization away from plastic-intensive cartridge designs. Five-to-ten year viability hinges on biodegradability transition execution and subscription retention mechanics. Watch ceramic blade adoption rates in London and New York barbershop chains as inflection indicator for professional tier displacement.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Certification Investment | ECHA enforcement tightening in European pharmacy channels filters supplier access to premium tier. |
| Direct-to-Consumer Platform Launch | Algorithmic replenishment timing captures convenience-premium tolerance among United States urban professionals. |
| Ceramic Blade Manufacturing Scale-Up | Rockwell hardness exceeding 90 eliminates legacy sharpening contracts in high-frequency barbershop environments. |
| Indian Localization Partnership | BIS dimensional mandates and PLI scheme incentives align tariff-advantaged production with South Asian demand. |
| Biodegradable Polymer Reformulation | EU Green Deal packaging directives favor compostable lubrication strip matrices with water-activation chemistry. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with blade manufacturing executives, barbershop procurement managers, European pharmacy category buyers, and polymer formulation specialists; and secondary validation against ECHA substance disclosure databases, BIS certification registries, FDA cosmetic instrument standards, customs trade records, and SEC filings from publicly traded consumer goods conglomerates. Bottom-up segmentation modeling triangulated against top-down market sizing.
Forecast inputs span product type, material grade, customer application setting, and distribution channel architecture across the projection horizon. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory inflection points and channel shift elasticity. Industry-specific inputs include REACH compliance timeline acceleration, subscription retention rate assumptions, and ceramic blade replacement cycle compression in professional environments.
Sensitivities concentrate around ECHA enforcement intensity, polymer input cost volatility, and electric shaving substitution elasticity among younger demographics. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or technology disruption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Horsehair Clippers Market
Personal Grooming Products
Shoe Deodorizer Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
China Beard Trimmer Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
Feminine Hygiene Products Market
Personal Grooming Products
Gel Socks Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Shoe Care Market