
 Global Aligner Sheet Market | 2026-2036
Global Aligner Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aligner Sheet Market Foresight
East Asian thermoplastic resin producers is restructuring aligner sheet feedstock availability as regional petrochemical capacity expands. Angelalign leverages vertical integration from polymer sourcing through finished appliance fabrication to control cost architecture. SCHEU Group anchors European supply through specialized extrusion expertise calibrated to orthodontic biomechanics. Straumann Group differentiates via high-transparency polyurethane formulations engineered for extended wear protocols.
Aligner sheets are multilayer thermoplastic membranes, typically 0.5–1.0 mm in thickness, thermoformed over dental models to generate sequential orthodontic devices with programmed tooth movement vectors. Their primary purpose is delivering controlled, removable force systems for arch expansion, rotation correction, and vertical control in lieu of fixed appliances. Thermoplastic and polyurethane categories dominate value capture given superior stress relaxation properties and optical clarity thresholds demanded by cosmetic dentistry applications. Orthodontic teeth correction remains the volume anchor, while pediatric dentistry represents an emerging margin pool as early interceptive protocols gain clinical acceptance.
FDA 510(k) clearance requirements and EU MDR biocompatibility testing (ISO 10993 series) shape material selection and validation timelines for sheet manufacturers seeking market access. BIS certification in India and NMPA registration in China impose additional jurisdiction-specific conformity burdens that fragment compliance investment. Stakeholders must monitor evolving regulatory harmonization between notified body frameworks and emerging economy standards to anticipate certificate migration costs and competitive qualification gaps.
Market Dynamics
Biomechanical performance standardization is compressing supplier differentiation as orthodontic networks consolidate procurement specifications around ISO 10993-certified multilayer formulations. This force concentrates volume among extrusion specialists capable of validating consistent stress-relaxation curves across production lots.
Growth Catalysts
- EU MDR biocompatibility mandates:Stricter ISO 10993 testing requirements for long-term oral contact devices are disqualifying uncertified resin suppliers and elevating compliant sheet manufacturers to preferred-vendor status.
- Adult orthodontic demand:Patients aged 25-45 seeking aesthetic alternatives to fixed appliances are expanding addressable case volumes beyond traditional adolescent segments.
- Polyurethane clarity thresholds:Optical-grade thermoplastic formulations meeting 90%+ light transmission standards are capturing premium positioning in cosmetic dentistry applications.
Market Restraints
- Petrochemical feedstock volatility:Thermoplastic polyurethane precursor costs fluctuate with regional propylene oxide supply disruptions, compressing extrusion margins unpredictably.
- East Asian resin concentration:Over 60% of medical-grade polycarbonate and TPU feedstock originates from integrated petrochemical complexes in China and South Korea, creating geographic supply vulnerability.
- Force-system predictability limits:Current multilayer sheets exhibit variable stress relaxation after 14-day wear cycles, constraining treatment planning confidence for complex rotation movements.
Strategic Opportunities
- India BIS certification pathway:Early compliance with Bureau of Indian Standards medical device regulations positions suppliers for procurement contracts as domestic orthodontic manufacturing scales.
- Pediatric interceptive protocols:Early-phase aligner therapy for mixed dentition cases represents an underserved application with higher reimbursement tolerance.
- AI-driven treatment simulation:Integration of machine learning platforms with sheet specification databases enables predictive biomechanical matching, reducing remanufacturing rates.
Industry Challenges
- Biomechanical engineering talent scarcity:Cross-functional expertise combining polymer science with orthodontic force-system design resides in fewer than twelve specialized centers worldwide.
- FDA 510(k) timeline compression:Average clearance durations for novel multilayer formulations have extended, delaying revenue recognition for R&D-intensive product lines.
- Legacy thermoforming equipment incompatibility:Next-generation high-clarity sheets require pressure-temperature profiles that obsolete installed base machinery in smaller dental laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aligner Sheet Market |
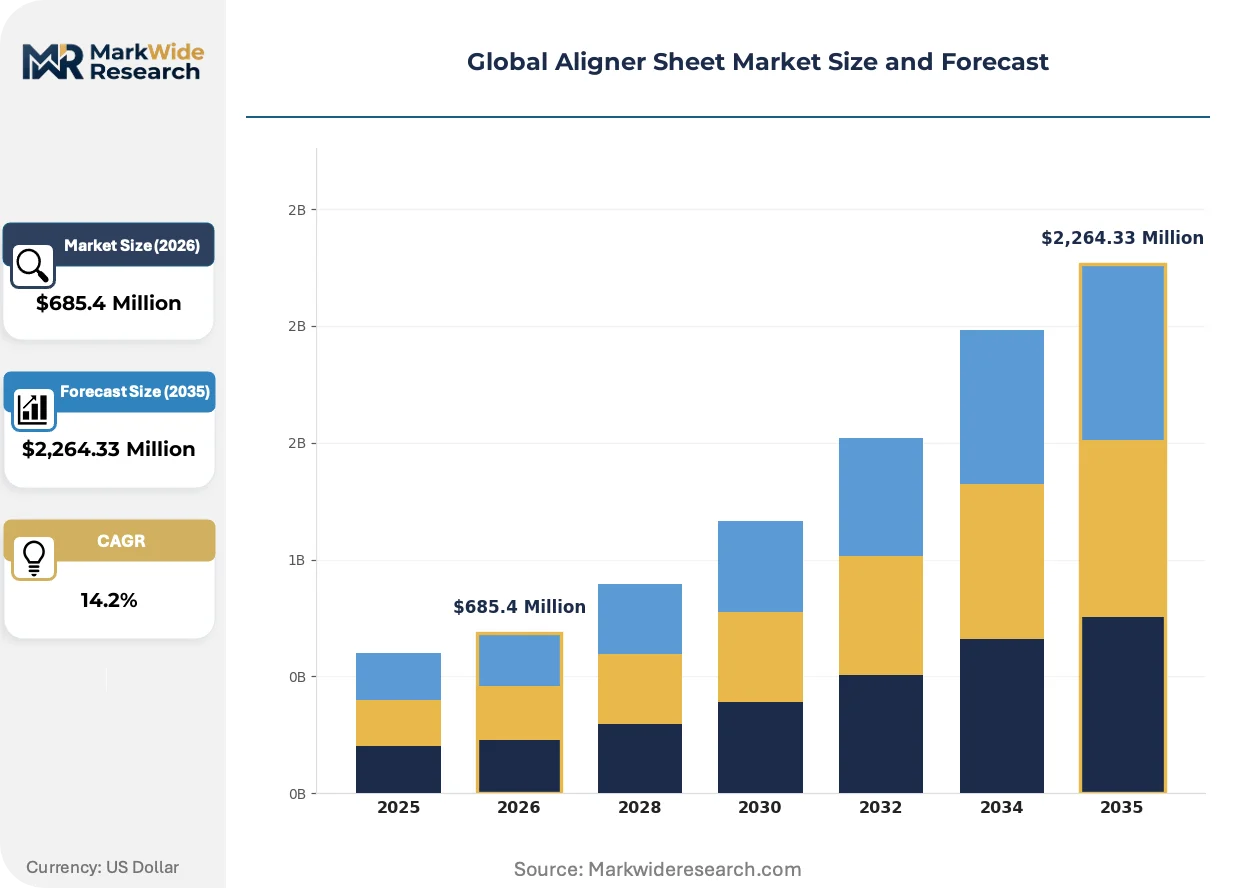
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,264.33 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Polyurethane, Polyethylene Terephthalate, Composite, Polycarbonate Application: Orthodontic Teeth Correction, Post-Orthodontic Retention, Cosmetic Dentistry, Pediatric Dentistry, Prosthodontics End User: Orthodontists, Dental Clinics, Dental Laboratories, Dental Schools, Cosmetic Dental Centers Distribution Channel: Direct Sales, Dental Distributors, Online Platforms, Specialty Stores, Wholesalers |
| Companies Covered | Angelalign, Ormco, Align Technology, SCHEU Group, TAGLUS, Straumann Group, 3M, Erkodent Erich Kopp GmbH, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aligner Sheet Market Shifts & Advancements
Digital workflow integration is reconfiguring how aligner sheets are specified, validated, and procured across orthodontic value chains. Three concurrent developments are compressing traditional supplier-buyer relationships.
Multilayer co-extrusion technology is modularizing how orthodontic force systems are engineered into sheet architectures. Sequential-layer deposition enables programmed stiffness gradients that match tooth movement stages precisely. Mid-sized orthodontic networks in Germany and the United States are adopting these specifications for complex case protocols, collapsing the distinction between standard and premium appliance tiers.
EU MDR Annex XVI expansion is reclassifying certain aesthetic orthodontic devices as medical products requiring notified body oversight. This regulatory elevation is extending validation timelines for sheet suppliers serving European orthodontic laboratories. Manufacturers are responding by consolidating polymer sourcing under single-documented supply chains to streamline technical file preparation.
Direct-to-consumer channel compression is altering how thermoplastic sheets reach end-appliance fabricators. Brand-owned aligner companies are bypassing traditional dental laboratory distributors to contract directly with extrusion specialists. This disintermediation is most pronounced in North American markets where DTC orthodontic volume concentrates procurement power among three major buyers.
Global Aligner Sheet Market Segmentation
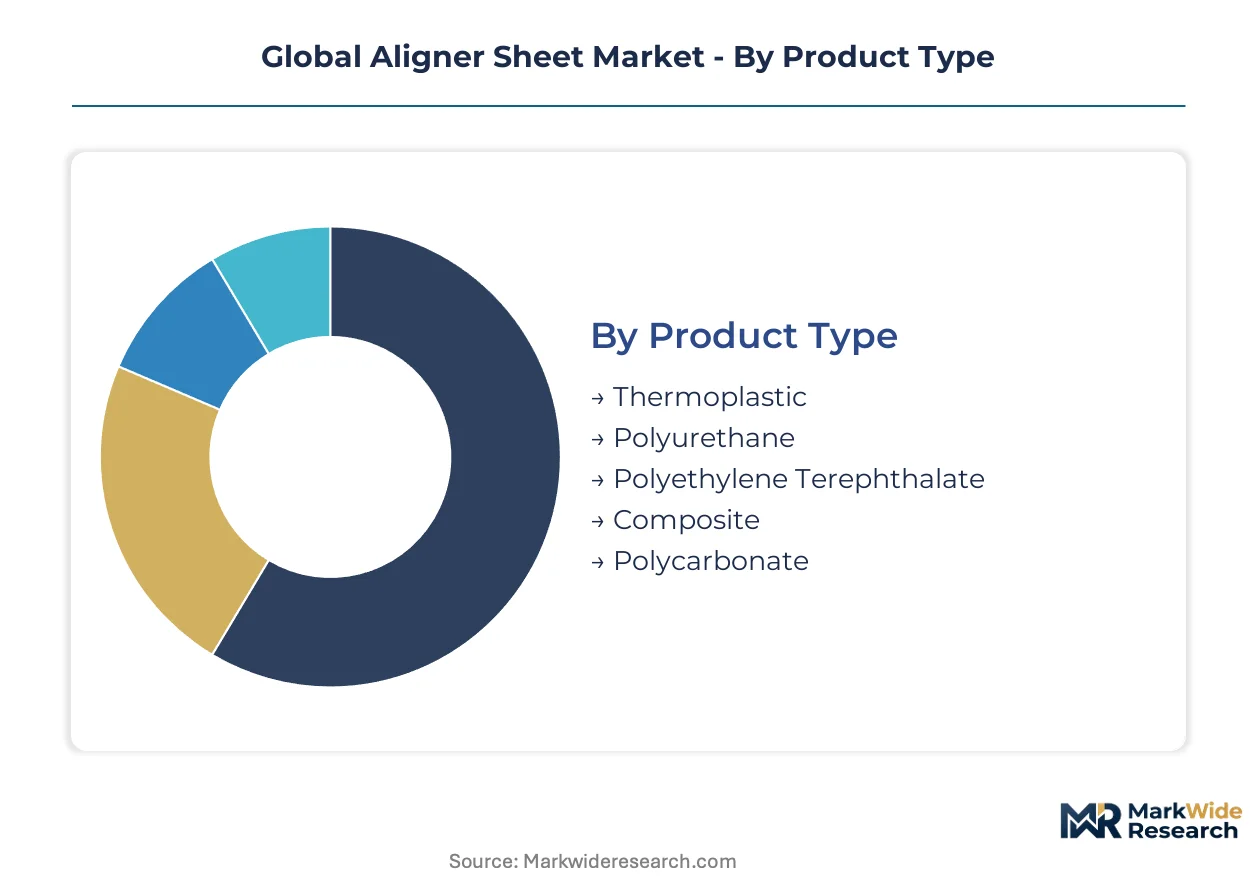
Aligner sheet procurement patterns diverge sharply across material grades, clinical applications, and buyer sophistication levels. Understanding these segmentation boundaries enables suppliers to calibrate extrusion capacity, certification investments, and channel strategy to specific revenue pools.
Product Type:
Material selection determines force-system predictability, optical performance, and regulatory pathway complexity for sheet manufacturers.
- Thermoplastic:Multilayer co-extruded membranes dominate current procurement volumes due to established thermoforming compatibility and ISO 10993 certification infrastructure. Demand concentrates among orthodontic networks in the United States and Germany seeking consistent stress-relaxation curves for complex rotation protocols.
- Polyurethane:High-transparency formulations achieve 90%+ light transmission thresholds required for extended-wear cosmetic applications. Japanese and South Korean dental laboratories specify these grades for adult aesthetic cases where discretion determines patient acceptance.
- Polyethylene Terephthalate:Lower-cost alternative for standard retention appliances with shorter wear cycles.
- Composite:Hybrid architectures blending stiffness gradients for specialized pediatric interceptive protocols.
- Polycarbonate:Legacy material retained for budget-tier orthodontic programs in emerging markets.
Thermoplastic leads volumes today; polyurethane is gaining share fastest.
Application:
Clinical use case defines force-system requirements, wear duration, and reimbursement tolerance.
- Orthodontic Teeth Correction:Primary volume anchor requiring programmed sequential stiffness for arch expansion, rotation correction, and vertical control. North American direct-to-consumer brands and established orthodontic networks drive specification consolidation around validated multilayer formulations.
- Cosmetic Dentistry:Premium positioning for adult patients aged 25-45 seeking aesthetic alternatives to fixed appliances. EU MDR Annex XVI reclassification is elevating validation requirements for sheet suppliers serving European aesthetic-focused practices.
- Post-Orthodontic Retention:Standardized lower-force applications with simpler material requirements and compressed margins.
- Pediatric Dentistry:Early interceptive protocols for mixed dentition cases represent underserved expansion opportunity with higher reimbursement tolerance.
- Prosthodontics:Niche alignment support for restorative treatment sequencing in specialized dental centers.
Orthodontic teeth correction commands absolute volume; pediatric dentistry climbs the fastest.
End User:
Buyer technical capability and procurement scale determine specification complexity and channel access.
- Orthodontists:Specialized practitioners with direct aligner fabrication capability or network purchasing power. United States and German orthodontic groups consolidate procurement around ISO 10993-certified multilayer specifications with validated biomechanical performance.
- Dental Laboratories:Centralized fabrication hubs serving multiple practitioner accounts. Indian and Chinese laboratories are scaling domestic manufacturing capacity, creating demand for BIS and NMPA-compliant sheet supply.
- Dental Clinics:General practice settings outsourcing aligner production to specialized laboratories or brand partners.
- Dental Schools:Educational institutions with research-focused procurement and extended validation timelines.
- Cosmetic Dental Centers:Aesthetic-focused practices prioritizing optical clarity and premium positioning over cost optimization.
Orthodontists anchor current procurement; dental laboratories are expanding most quickly.
Distribution Channel:
Channel structure is compressing as direct-to-consumer brands bypass traditional intermediaries.
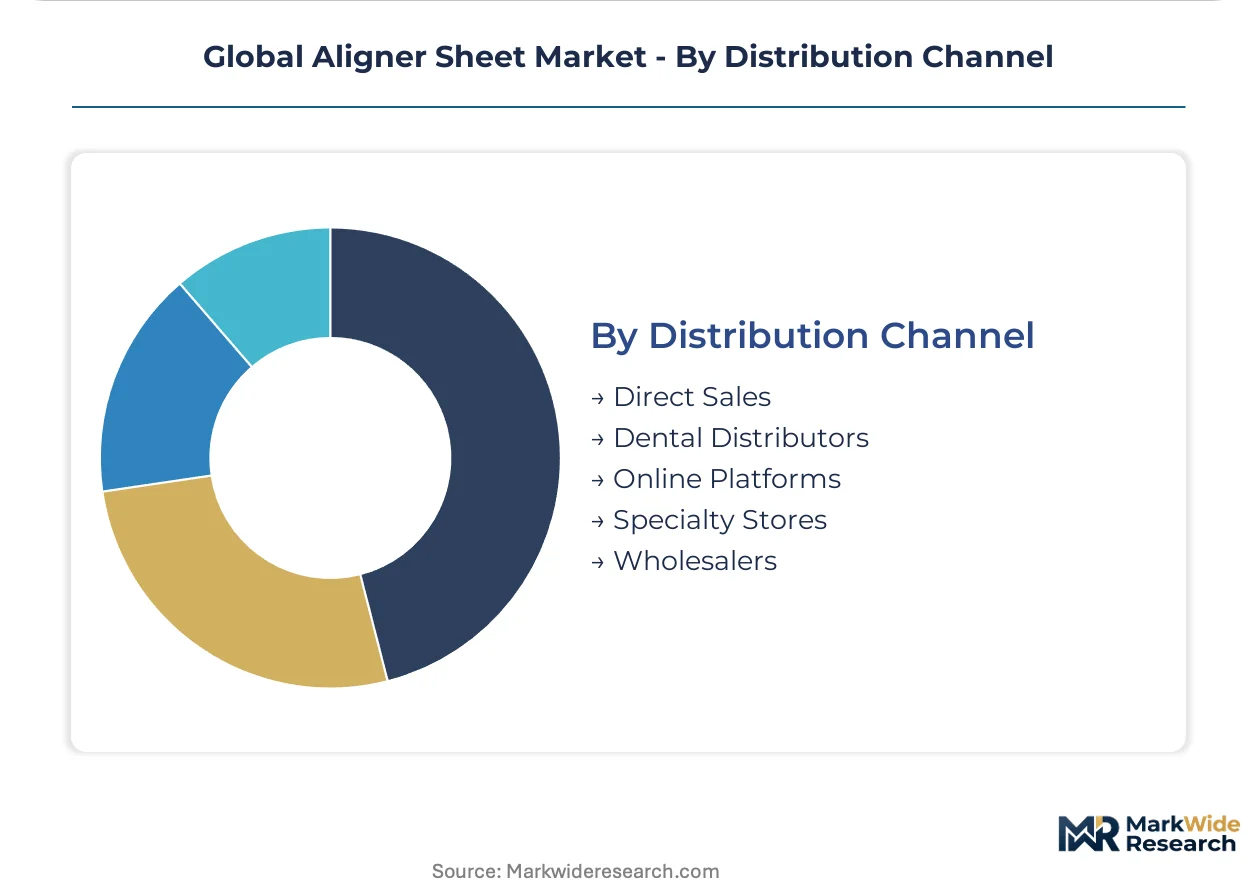
- Direct Sales:Extrusion specialists contracting directly with large orthodontic networks and brand-owned aligner companies. North American DTC volume concentrates procurement power among three major buyers, disintermediating dental laboratory distributors.
- Dental Distributors:Traditional intermediaries serving fragmented small-laboratory and clinic accounts with consolidated logistics and technical support.
- Online Platforms:Emerging procurement channel for mid-sized orthodontic practices seeking specification transparency and competitive pricing.
- Specialty Stores:Regional suppliers with localized inventory and rapid fulfillment for urgent fabrication needs.
- Wholesalers:Volume aggregators serving price-sensitive markets with standardized commodity-grade sheet products.
Direct sales leads transaction value today; online platforms show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting aligner sheet procurement as manufacturers seek jurisdictions with streamlined biocompatibility certification pathways. Production migration patterns favor countries where ISO 10993 testing infrastructure intersects with favorable duty structures on medical-grade thermoplastic imports.
United States
Direct-to-consumer aligner brands concentrate procurement power among three major buyers, consolidating thermoplastic sheet demand around validated multilayer formulations. FDA 510(k) clearance timelines shape supplier qualification priorities, with extended durations favoring established extrusion specialists over novel entrants. The Dallas-Fort Worth metroplex hosts specialized dental manufacturing clusters where orthodontic laboratories scale fabrication capacity for national distribution networks.
Germany
Orthodontic networks in Bavaria and North Rhine-Westphalia drive specification consolidation around EU MDR-compliant sheet architectures with programmed stiffness gradients. ECHA REACH registration requirements for polyurethane precursors elevate material traceability standards across the supply base. The SCHEU Group anchors regional production through specialized extrusion expertise calibrated to orthodontic biomechanics in the Ruhr industrial corridor.
China
Angelalign leverages vertical integration from polymer sourcing through finished appliance fabrication to control cost architecture across domestic and export markets. NMPA registration requirements impose jurisdiction-specific conformity burdens that fragment compliance investment for foreign sheet suppliers. The Yangtze River Delta petrochemical complex supplies over sixty percent of medical-grade polycarbonate and TPU feedstock for regional aligner manufacturing.
India
Dental laboratories in Maharashtra and Gujarat are scaling domestic manufacturing capacity, creating demand for BIS-certified sheet supply as orthodontic case volumes expand. Bureau of Indian Standards medical device regulations position early-compliant suppliers for procurement contracts in emerging domestic production networks. Mumbai-Pune industrial corridor clusters concentrate thermoforming equipment distribution and technical service capabilities for mid-sized orthodontic practices.
Japan
Adult aesthetic cases in Tokyo and Osaka dental laboratories specify high-transparency polyurethane grades achieving ninety-percent-plus light transmission thresholds. PMDA consultation procedures for novel multilayer formulations extend validation timelines, compressing competitive windows for imported sheet products. The Kansai region maintains specialized polymer compounding expertise serving premium cosmetic dentistry applications with extended-wear protocols.
Global Aligner Sheet Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pediatric interceptive protocols and AI-integrated biomechanical matching systems. The vendor base stratifies across three capability tiers: extrusion specialists with validated ISO 10993 certification infrastructure, regional distributors serving fragmented laboratory accounts, and brand-owned aligner companies with captive sheet procurement. Strategic archetypes include backward-integrated polymer-to-appliance manufacturers, pure-play extrusion specialists, and orthodontic network-integrated fabricators. Dominant competitive moves center on M&A consolidation of certification assets and capacity expansion in India and Southeast Asia to capture BIS and NMPA pathway advantages.
Among Asia-Pacific-based fabricators, Angelalign exemplifies the backward-integrated archetype controlling polymer sourcing through finished appliance production. The SCHEU Group and Straumann Group occupy positions within the European premium-tier vector, representing specialized extrusion expertise and high-transparency polyurethane formulation capabilities respectively. These three anchors illustrate how competitive positioning diverges between cost-architecture control and optical-performance differentiation.
| Leading Market Players |
|---|
| Angelalign |
| Ormco |
| Align Technology |
| SCHEU Group |
| TAGLUS |
| Straumann Group |
| 3M |
| Erkodent Erich Kopp GmbH |
| Dentsply Sirona |
| Others |
Supply & Pricing Matrix
Propylene oxide feedstock volatility propagates through thermoplastic polyurethane precursor costs into tiered sheet pricing structures, compressing extrusion margins unpredictably while channel-margin layers absorb residual pressure across distributor, laboratory, and direct-to-consumer procurement tiers.
Pricing Analysis
Distributor margin compression defines the dominant pricing architecture, with three-tier pricing structure across premium, standard, and economy levels separating ISO 10993-certified multilayer formulations from uncertified commodity grades. Price differentiation hinges on certification tier and volume scale, with orthodontic network consolidation driving aggressive direct-contract discounts. Pricing pressure stems from East Asian resin concentration and petrochemical feedstock instability, squeezing mid-tier suppliers most severely. Direct-to-consumer brands exhibit lowest price sensitivity given captive volume, while independent dental laboratories face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta petrochemical complexes supplying over sixty percent of medical-grade polycarbonate and TPU feedstock. Raw material dependencies center on propylene oxide, methylene diphenyl diisocyanate, and specialty polyester polyols. Supply chain risk concentrates in tariff exposure on Chinese-origin resin imports and regulatory restriction under EU MDR documentation requirements. Distribution runs through direct sales contracts with large orthodontic networks, bypassing traditional dental laboratory intermediaries in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR Annex XVI reclassification and FDA 510(k) timeline extensions continuously elevate entry barriers and consolidate procurement around certified suppliers.
For Market Incumbents: Acquire ISO 10993 certification infrastructure and notified body relationships to defend against emerging Asian extrusion specialists with cost-architecture advantages. Prioritize capacity addition in India to capture BIS pathway first-mover positioning. Deepen backward integration into polymer sourcing to offset propylene oxide volatility. For New Entrants and Emerging Players: Capture pediatric interceptive protocol segments where reimbursement tolerance exceeds adult aesthetic cases and incumbent specification lock-in remains incomplete. Target Indian dental laboratory scaling demand with BIS-compliant sheet supply. Pursue AI-driven biomechanical matching as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 10993 certification scarcity intersects with orthodontic network procurement consolidation, favoring acquisition of extrusion specialists with validated multilayer formulation capabilities. Long-term viability frames around regulatory harmonization completion and direct-to-consumer channel maturation. Monitor FDA 510(k) clearance duration trends as inflection indicator for R&D-intensive product line viability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Notified body relationships under EU MDR Annex XVI secure preferred-vendor status with European orthodontic networks. |
| Backward Integration into Polymer Sourcing | Captive resin supply from Yangtze River Delta complexes insulates margin architecture from propylene oxide volatility. |
| AI-Driven Biomechanical Matching Platform | Machine learning integration with sheet specification databases reduces remanufacturing rates for complex rotation protocols. |
| BIS Certification Pathway Compliance | Early Bureau of Indian Standards medical device registration positions suppliers for Maharashtra and Gujarat laboratory procurement contracts. |
| Pediatric Interceptive Protocol Development | Mixed dentition case specialization captures higher reimbursement tolerance in underserved early-phase aligner therapy segments. |
Research Methodology
Bottom-up orthodontic teeth correction and pediatric dentistry modeling reconciled against top-down thermoplastic and polyurethane extrusion capacity tracking forms the analytical core. Primary interviews with orthodontic network procurement directors, dental laboratory technical managers, extrusion specialist R&D leads, and notified body certification officers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and BIS medical device compliance registries. Trade data from customs authorities and petrochemical feedstock import records anchored supply-side triangulation.
Input-output matrices mapped sheet specification requirements across clinical application segments against regional production capacity and certification infrastructure availability over the projection horizon. Modeled dimensions spanned material grade tier, clinical use case, buyer sophistication level, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific forecast inputs incorporated orthodontic case volume growth trajectories and EU MDR implementation timeline phasing.
Regulatory harmonization delays, petrochemical feedstock supply disruptions, and force-system predictability breakthroughs are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding certification pathway durations and orthodontic network consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Global Sex Toys Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market
Personal Grooming Products
Epilators Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
China Beard Trimmer Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
North America Mosquito Repellent Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
Razor Market
Personal Grooming Products
Handheld Massager Market