
 Gel Socks Market | 2026-2036
Gel Socks Market Size, Share, and Industry Trends Forecast 2026-2036
Gel Socks Market Foresight
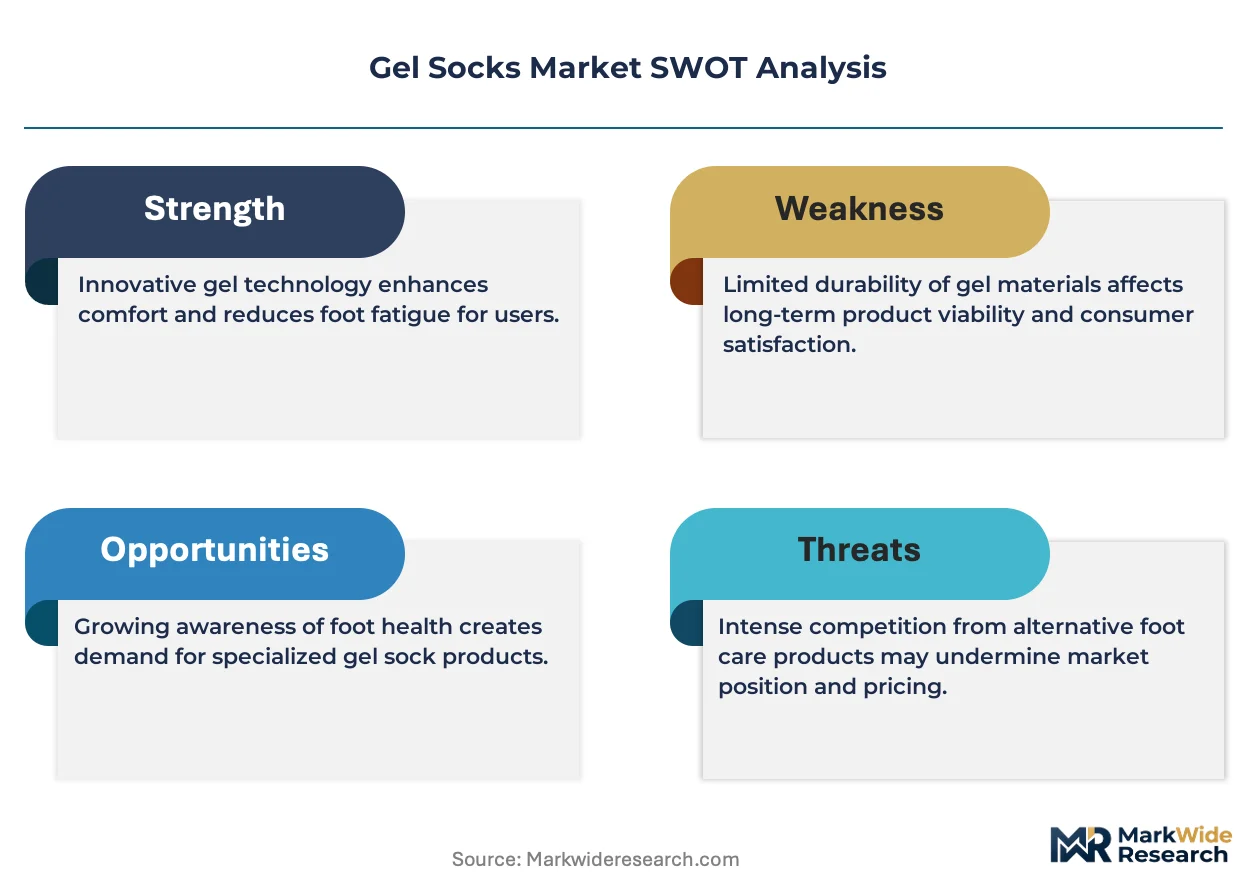
Asset-light contract manufacturing and third-party fulfillment is narrowing the capital barrier for new entrants in gel socks. PolyGel LLC leverages captive silicone compounding to sustain margin control across moisturizing and medical-grade lines. Dr. Scholl's Wellness anchors shelf presence in mass retail through decades of foot-care brand equity. XIAMEN ZHAOTAI INDUSTRIAL CORP competes on export scale, supplying private-label programs across North America and Europe.
Gel socks are wearable textile devices integrating polymer or botanical gel matrices into knitted or woven sock constructions, designed to deliver sustained thermal, moisture, or therapeutic agent transfer to the foot surface. Manufacturing employs multi-layer lamination or injection-molding of gel pads into textile pockets, with gel viscosity and release kinetics calibrated to application duration. Moisturizing gel socks lead volume due to recurring consumer replenishment cycles in home and spa channels, while medical therapy applications command premium pricing through clinical validation requirements. Cooling gel socks represent the fastest-expanding structural segment, driven by post-workout recovery protocols in athletic and rehabilitation settings.
The FDA regulates medical therapy claims for gel socks marketed for conditions such as neuropathy or diabetic foot care, requiring 510(k) clearance or device classification before interstate commerce. REACH compliance in Europe restricts certain plasticizers and fragrance compounds in gel matrices, redirecting formulation R&D toward bio-based alternatives. Home users and wellness centers must monitor evolving dermatological safety standards and ingredient disclosure mandates across their supplier bases to avoid compliance-driven stock disruptions.
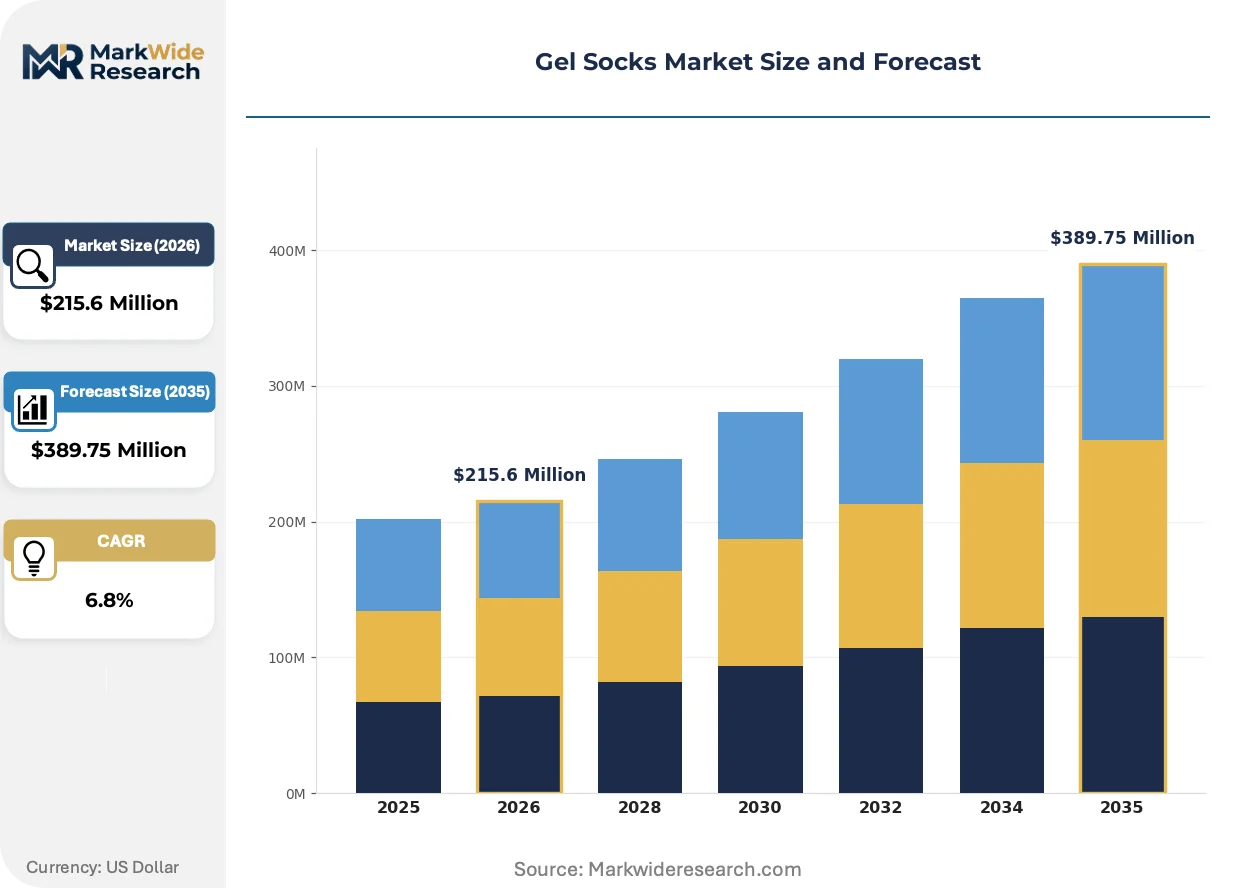
Market Dynamics
Athletic recovery protocols are compressing replenishment cycles for cooling gel socks while tightening FDA scrutiny on medical-grade therapeutic claims reshapes competitive entry barriers.
Growth Catalysts
- REACH compliance redirection:ECHA restrictions on phthalate plasticizers force reformulation toward bio-based gel matrices, opening premium positioning for European suppliers with certified green chemistry pipelines.
- Post-workout recovery normalization:Fitness center chains and sports medicine clinics now stock cooling variants as standard equipment, embedding gel socks into institutional procurement workflows.
- China manufacturing cluster density:Xiamen and Quanzhou textile-gel integration hubs achieve 72-hour prototype-to-sample turnaround, accelerating private-label program velocity for North American distributors.
Market Restraints
- Silicone feedstock volatility:Medical-grade silicone gel costs fluctuate with semiconductor sector demand cycles, squeezing margin predictability for moisturizing and therapy lines.
- Single-source gel formulation dependency:Captive silicone compounding capabilities concentrate among three domestic Chinese suppliers, creating geographic concentration risk for contract manufacturers.
- 510(k) clearance timelines:FDA medical device classification for neuropathy claims extends market entry by 18-24 months versus cosmetic positioning, freezing capital in regulatory limbo.
Strategic Opportunities
- Diabetic foot care protocol integration:Medicare Advantage plans in the United States increasingly reimburse Class I medical devices, creating reimbursement tailwinds for clinical-grade gel sock prescriptions.
- Spa-channel professionalization:Wellness centers in South Korea and Japan adopt gel socks as standardized pedicure add-ons, displacing disposable paraffin treatments with reusable therapeutic alternatives.
- Smart textile convergence:Integration of temperature-monitoring filaments with gel matrices enables real-time recovery analytics, appealing to quantified-self athletes and physical therapy chains.
Industry Challenges
- Cross-functional formulation expertise scarcity:Chemists combining polymer rheology with dermatological safety testing command premium compensation, constraining R&D team scaling for mid-tier manufacturers.
- Multi-jurisdiction labeling complexity:Simultaneous FDA, REACH, and NMPA compliance requires parallel documentation streams, extending product launch timelines and legal review costs.
- Legacy textile-gel bonding equipment:Conventional heat-press machinery produces inconsistent pad adhesion, forcing capital-intensive migration to ultrasonic welding or injection-molding lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gel Socks Market |
| Market Size in 2026 | $215.6 Million |
| Market Size in 2035 | $389.75 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizing Gel Socks, Cooling Gel Socks, Heating Gel Socks, Aromatherapy Gel Socks, Exfoliating Gel Socks Material: Silicone Gel, Aloe Vera Infused Gel, Collagen Gel, Charcoal Gel, Shea Butter Gel Application: Foot Care, Athletic Recovery, Skin Hydration, Medical Therapy, Stress Relief End User: Beauty Clinics, Spas, Wellness Centers, Home Users, Rehabilitation Facilities |
| Companies Covered | PolyGel LLC, Dr. Scholl's Wellness, Bath Accessories Co. Inc., XIAMEN ZHAOTAI INDUSTRIAL CORP, Armstrong Amerika, Earth Therapeutics Direct, Silipos Holding LLC, Mediheal Corporation, Donnamax Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gel Socks Market Shifts & Advancements
Material science advances and regulatory chemistry mandates are actively restructuring how gel matrices get specified, manufactured, and positioned across consumer and clinical channels.
Botanical-infused hydrogels is migrating from niche spa positioning toward mass-market moisturizing lines. Clean-beauty retailers and direct-to-consumer wellness brands specify aloe-vera and shea-butter matrices as default formulations. This shift compresses synthetic silicone volumes in the home-use segment while elevating ingredient transparency as a purchasing filter.
REACH Annex XVII restrictions on fragrance allergens and plasticizers are forcing European formulators to rebuild gel recipes from base polymers. Manufacturers serving EU distribution channels now maintain separate formulation libraries versus North American or Asian production runs. Medical therapy applications face the steepest compliance burden, as clinical validation must be repeated for each reformulated matrix.
Subscription-based replenishment models are displacing single-unit pharmacy and big-box retail purchases for moisturizing variants. Direct-to-consumer brands capture recurring revenue through quarterly sock replacements, while traditional retail footprints shrink to trial-size and gift-set formats. This channel rotation is most advanced in United States urban markets with established wellness subscription infrastructure.
Gel Socks Market Segmentation
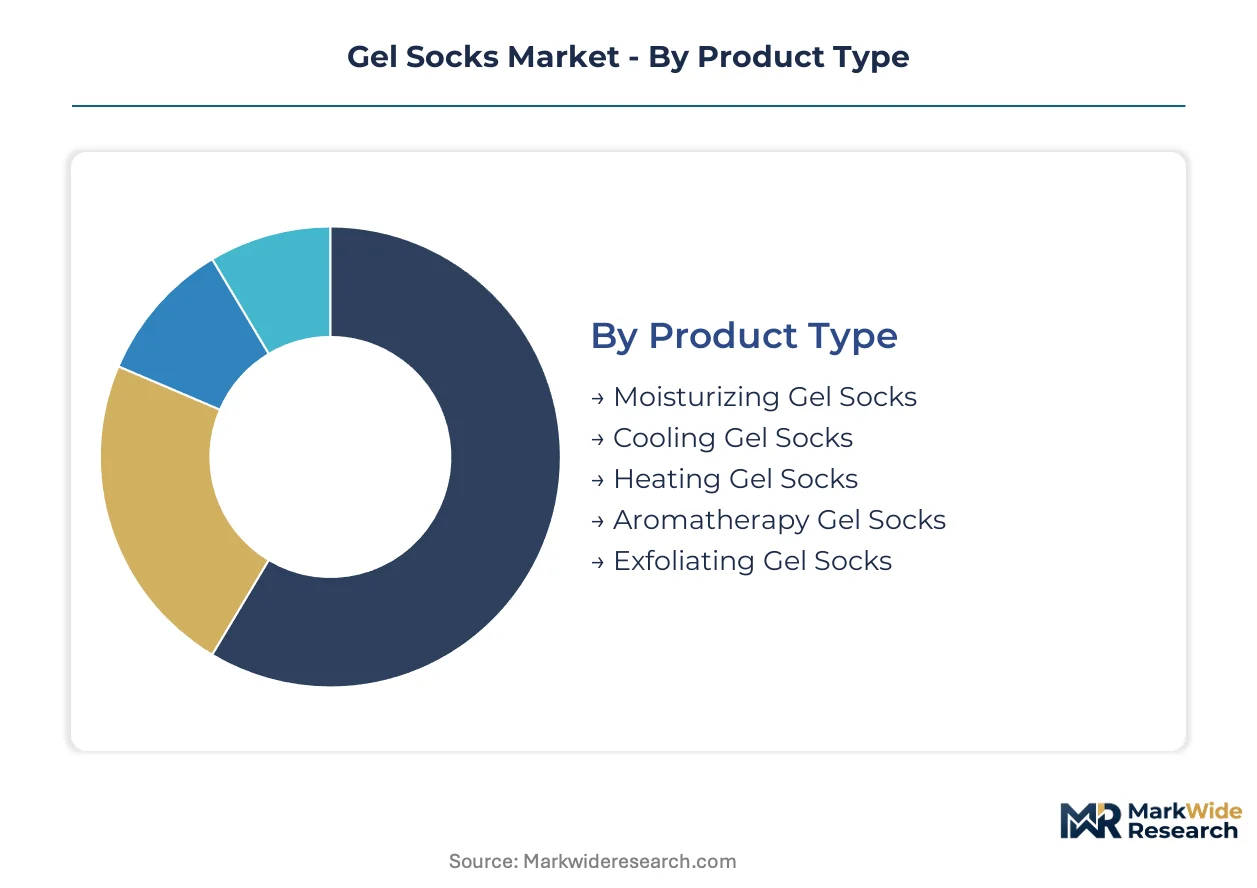
Gel socks fragment across four functional dimensions that dictate manufacturing complexity, regulatory pathway, and replenishment cadence. Each segmentation axis carries distinct margin profiles and channel dependencies that shape supplier strategy.
Product Type:
Moisturizing variants turn inventory fastest through spa-channel replenishment cycles, while medical-grade therapy lines sit longest in regulatory review before commercial release.
- Moisturizing Gel Socks:Silicone or botanical gel matrices deliver sustained emollient transfer during overnight wear. Home users in South Korea and Japan drive repeat purchase velocity through subscription programs, compressing replenishment cycles to 60-90 days.
- Cooling Gel Socks:Phase-change gel pads activate post-freezing to reduce inflammation. Athletic recovery protocols at United States sports medicine clinics embed these into standard equipment procurement, with fitness center chains now specifying reusable alternatives to disposable ice packs.
- Heating Gel Socks:Microwave-activated thermal gels target arthritic foot conditions. Germany's elderly care facilities represent concentrated institutional demand.
- Aromatherapy Gel Socks:Essential oil-infused matrices pair scent diffusion with moisture delivery. Boutique spa channels in France and Italy favor these for premium service tiers.
- Exfoliating Gel Socks:Alpha-hydroxy acid gels combined with textured surfaces remove dead skin. Professional pedicure studios in urban United States markets specify these as upsell treatments.
Moisturizing Gel Socks dominate installed base. Cooling Gel Socks is where expansion concentrates.
Material:
Cost tiers separate medical-grade silicone formulations from commodity botanical alternatives, with REACH-compliant bio-based gels commanding 40-60% price premiums.
- Silicone Gel:Medical-grade polydimethylsiloxane matrices offer thermal stability and hypoallergenic certification. FDA 510(k) clearance requirements for neuropathy claims restrict supply to three domestic Chinese compounders with validated manufacturing.
- Aloe Vera Infused Gel:Botanical hydrogels migrate from niche spa positioning toward mass-market default specifications. Clean-beauty retailers in California and New York now require ingredient transparency down to cultivation source.
- Collagen Gel:Marine-derived protein matrices target anti-aging positioning. South Korean cosmetic regulators enforce stricter animal-source documentation than North American counterparts.
- Charcoal Gel:Activated carbon suspensions absorb odor and moisture. Southeast Asian manufacturing clusters exploit regional activated carbon supply density.
- Shea Butter Gel:West African butter bases appeal to ethical-sourcing narratives. European Union due diligence regulations on deforestation-free supply chains constrain West African sourcing.
Silicone Gel captures the highest value per kilogram. Aloe Vera Infused Gel is climbing the fastest as clean-beauty specifications harden.
Application:
Volume concentrates in cosmetic foot care, while margin concentrates in reimbursable medical indications.
- Foot Care:General moisturizing and callus management for non-clinical users. United States big-box retail and pharmacy channels drive volume through seasonal gift-set promotions.
- Athletic Recovery:Post-workout cooling and compression protocols. Professional sports teams in Germany and the United Kingdom now specify gel socks in equipment budgets.
- Skin Hydration:Dermatological moisture retention for diabetic and elderly patients. Japan's aging population supports premium pricing for hospital-dispensed variants.
- Medical Therapy:Neuropathy pain management and circulatory stimulation. Medicare Advantage reimbursement tailwinds in the United States attract device manufacturers seeking Class I classification.
- Stress Relief:Aromatherapy and thermal relaxation for wellness tourism. Thai and Indonesian resort spas integrate these into multi-day treatment packages.
Foot Care dominates installed base. Medical Therapy is where expansion concentrates.
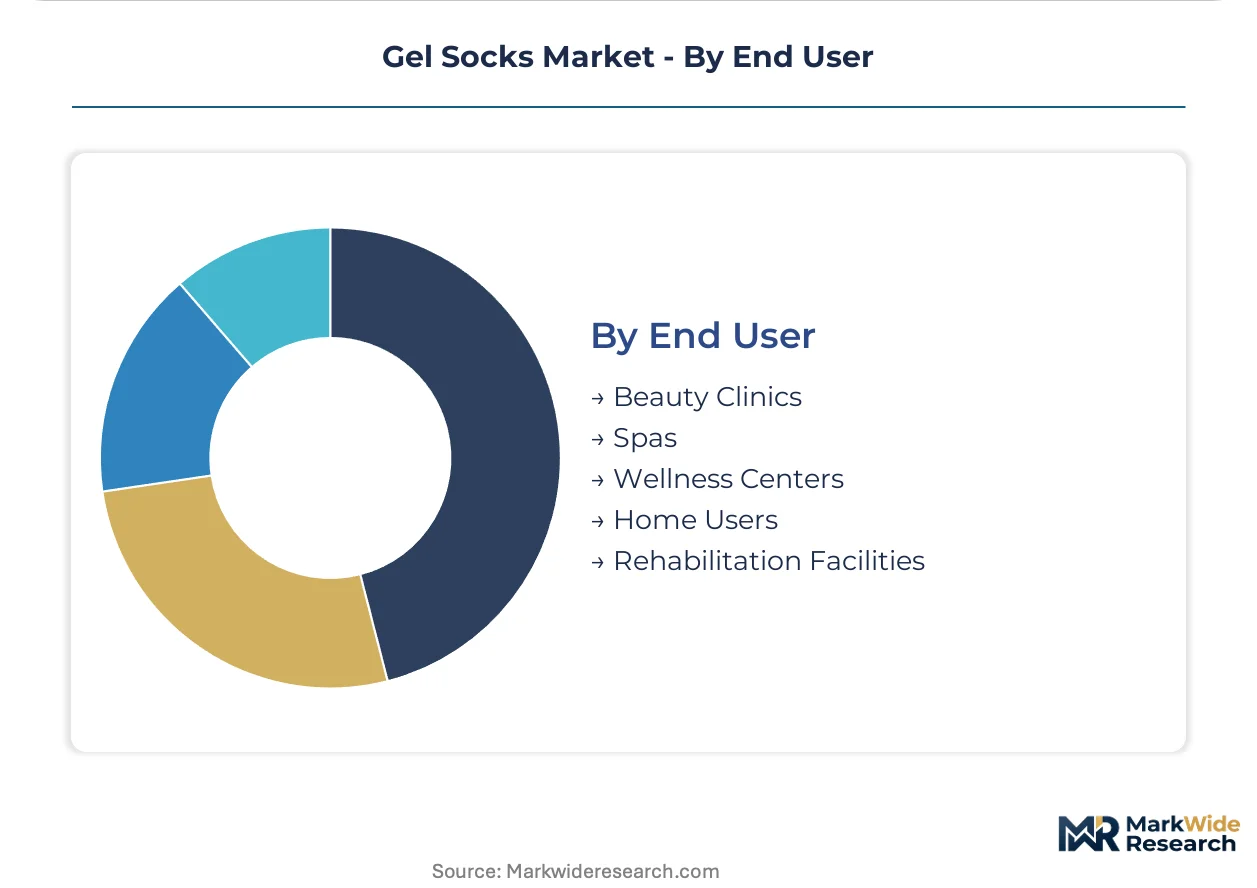
End User:
Channel professionalization separates reusable therapeutic adoption from disposable commodity procurement.
- Beauty Clinics:Medical-aesthetic facilities combine gel socks with laser and peel protocols. Brazilian ANVISA regulates these as cosmetic accessories rather than medical devices.
- Spas:Traditional wellness centers displace paraffin treatments with reusable gel alternatives. South Korean jjimjilbang chains standardize these across hundreds of locations.
- Wellness Centers:Corporate and residential fitness complexes. United Arab Emirates luxury residential developments specify these in amenity packages.
- Home Users:Direct-to-consumer subscription models. United States urban markets with established wellness infrastructure show highest quarterly replenishment rates.
- Rehabilitation Facilities:Physical therapy chains and post-surgical recovery centers. Germany's statutory health insurance system reimburses prescribed therapeutic variants.
Home Users dominate installed base. Rehabilitation Facilities is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy shifts in Medicare Advantage plans and REACH Annex XVII chemical restrictions are redrawing competitive boundaries across the United States and European Union respectively, while manufacturing cluster density in Fujian Province compresses prototype-to-production timelines for private-label distributors.
United States
FDA 510(k) clearance requirements for neuropathy claims extend market entry timelines by 18-24 months versus cosmetic positioning, freezing capital in regulatory review. Medicare Advantage plans increasingly reimburse Class I medical devices, creating reimbursement tailwinds for clinical-grade gel sock prescriptions. Sports medicine clinics in Arizona and Florida embed cooling variants into standard equipment procurement workflows.
Germany
Statutory health insurance reimbursement for prescribed therapeutic variants drives institutional demand from elderly care facilities and rehabilitation centers. ECHA REACH restrictions on phthalate plasticizers force reformulation toward bio-based gel matrices, elevating compliance costs for imported silicone formulations. Bavarian textile-gel integration specialists serve as technical consultants to mid-tier manufacturers navigating MDR device classification.
China
NMPA medical device classification for diabetic foot care applications requires domestic clinical trial data, favoring local manufacturers with established hospital relationships. Xiamen and Quanzhou textile-gel integration hubs achieve 72-hour prototype-to-sample turnaround, accelerating private-label program velocity for North American distributors. Domestic manufacturing clusters supply both regional consumers and export channels with cost-optimized formulations.
South Korea
MFDS cosmetic regulations enforce stricter animal-source documentation for collagen-derived matrices than North American counterparts, constraining marine protein supply chains. Jjimjilbang wellness chains standardize reusable gel socks across hundreds of locations, displacing disposable paraffin treatments. Seoul-based clean-beauty retailers now require ingredient transparency down to cultivation source for botanical hydrogels.
Japan
METI aging-population initiatives support premium pricing for hospital-dispensed skin hydration variants targeting diabetic and elderly patients. PMDA dermatological safety standards mandate extended patch-testing protocols for new gel matrix introductions, extending product launch timelines. Osaka textile manufacturers specialize in multi-layer lamination equipment for precision gel pad integration.
Gel Socks Market Competitive Landscape
On the supply side, the industry is bifurcated between asset-light contract manufacturers and vertically integrated compounders with captive silicone production. Three strategic archetypes dominate: medical-grade specialists navigating FDA clearance pathways, mass-market brands leveraging decades of foot-care shelf presence, and export-scale Chinese fabricators serving private-label programs. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into adjacent wearable therapy categories.
Among North American medical-grade specialists, Silipos Holding LLC exemplifies the regulatory-navigation archetype, while Dr. Scholl's Wellness anchors mass retail channels through established foot-care brand equity. XIAMEN ZHAOTAI INDUSTRIAL CORP occupies the export-scale fabrication tier, supplying private-label programs across North America and Europe from Fujian Province manufacturing clusters.
| Leading Market Players |
|---|
| PolyGel LLC |
| Dr. Scholl's Wellness |
| Bath Accessories Co. Inc. |
| XIAMEN ZHAOTAI INDUSTRIAL CORP |
| Armstrong Amerika |
| Earth Therapeutics Direct |
| Silipos Holding LLC |
| Mediheal Corporation |
| Donnamax Inc. |
| Others |
Supply & Pricing Matrix
Single-source silicone compounding dependency in Fujian Province determines both premium-mid-economy pricing differentiation and supply chain vulnerability for North American distributors. FDA 510(k) clearance timelines for medical-grade claims extend capital lockup periods, compressing margins for therapy lines while cosmetic-positioned variants capture faster inventory turns.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared therapy lines and economy-grade moisturizing variants. Three-tier pricing structure across premium, standard, and economy levels reflects gel matrix composition, with REACH-compliant bio-based formulations commanding 40-60% premiums over commodity silicone. Price differentiation stems from clinical validation investment and dermatological safety testing depth. Cost compression in standard-tier botanical gels is intensifying because South Korean clean-beauty retailers now mandate cultivation-source transparency. Home users through subscription programs show lowest price sensitivity, while mass retail pharmacy channels exhibit highest elasticity to promotional discounting.
Supply Chain Analysis
Asset-light contract manufacturers in Xiamen, Quanzhou, and Dongguan hold dominant capacity for textile-gel integration. Medical-grade silicone feedstock draws from three domestic Chinese compounders with validated manufacturing, while botanical hydrogels source from West African shea butter cooperatives and Southeast Asian activated carbon processors. Single-source vulnerability concentrates in semiconductor-correlated silicone price cycles. Distribution runs through North American private-label distributors, European wellness retail chains, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gel socks demand follows fitness center capital expenditure cycles, with post-pandemic athletic recovery protocol standardization now driving institutional replenishment. Subscription-model normalization in United States urban markets indicates residential demand stabilization.
For Market Incumbents:Harden regulatory-navigation capabilities against tightening FDA scrutiny on neuropathy claims by maintaining parallel cosmetic-positioned SKUs for faster market entry. Deepen captive silicone compounding relationships with Fujian Province suppliers to offset feedstock volatility. Channel control through exclusive wellness center partnerships protects margin position against private-label encroachment.
For New Entrants and Emerging Players:Pursue diabetic foot care protocol integration as Medicare Advantage reimbursement expands Class I medical device coverage. Target rehabilitation facilities in Germany's statutory health insurance system where prescribed therapeutic variants command premium pricing. Clean-beauty certification alignment with South Korean cultivation-source mandates offers differentiated go-to-market positioning.
For Investors and Strategic Acquirers:FDA 510(k) clearance backlogs reshapes the acquisition landscape toward asset-light contract manufacturers with established regulatory dossiers. Five-to-ten year viability favors manufacturers with dual cosmetic-medical positioning flexibility. Watch NMPA domestic clinical trial requirements in China as inflection indicator for local manufacturer valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation | ECHA restrictions force bio-based gel matrix R&D investment, elevating European supplier competitiveness. |
| Smart Textile Integration | Temperature-monitoring filament convergence enables real-time recovery analytics for physical therapy chains. |
| Subscription Model Expansion | Quarterly replenishment programs capture recurring revenue from United States wellness infrastructure markets. |
| Private-Label Program Velocity | Seventy-two-hour prototype turnaround in Xiamen accelerates North American distributor speed-to-market. |
| Reimbursement Strategy Development | Medicare Advantage Class I device coverage creates prescription channel access for clinical-grade variants. |
Research Methodology
Operator-level perspectives from gel sock manufacturers, wellness center procurement directors, sports medicine clinic equipment managers, and FDA regulatory consultants anchored the qualitative base. Primary interview data combined with secondary validation from NMPA medical device filings, ECHA REACH restriction updates, and CMS Medicare Advantage reimbursement bulletins. Bottom-up demand modeling across consumer replenishment cycles triangulated with top-down manufacturing capacity assessments.
Scenario-bracketing around regulatory clearance timelines and silicone feedstock volatility shaped the analytical framework. Segmentation dimensions spanned product type, gel matrix composition, application indication, and end-user channel across the analysis window. CAGRs derived from fitted growth curves against historical replenishment velocity and institutional procurement adoption rates. Forecast inputs incorporated fitness center chain expansion plans and diabetic foot care protocol integration timelines.
Sensitivities concentrate around FDA 510(k) backlog fluctuations, REACH Annex XVII expansion scope, and semiconductor sector demand spillovers into medical-grade silicone pricing. Forecasts embed assumptions regarding reimbursement policy continuity and clean-beauty certification hardening. Quarterly review of NMPA clinical trial enrollment rates and ECHA substance restriction proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Epilators Market
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Hand Massager Market
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
Global Aligner Sheet Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Hand Hygienic Product Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
Shoe Insert Market