
 Male Grooming Products Market | 2026-2036
Male Grooming Products Market Size, Share, and Industry Trends Forecast 2026-2036
Male Grooming Products Market Intelligence
Biotechnology integration into skincare formulation is tilting competitive advantage toward brands with in-house fermentation capabilities. Procter & Gamble Company leverages its Cincinnati-based R&D campus to develop precision peptides for post-shave recovery. Beiersdorf AG anchors its position through Hamburg laboratories that specialize in barrier-repair ceramides for sensitive male skin. L'Oréal S.A. competes via Paris-based dermatological testing protocols that validate claims across diverse ethnic skin profiles.
Male grooming products encompass topical preparations designed for hair management, skin conditioning, and odor control, typically formulated with emollients, active botanicals, or antimicrobial agents at pH ranges between 4.5 and 6.0 to maintain epidermal homeostasis. Their commercial purpose centers on personal hygiene maintenance and aesthetic self-presentation within professional and social contexts. Shaving cream and beard oil categories command established volume bases, while deodorant segments extract premium pricing through clinical-strength antiperspirant technologies. Online retail channels expand fastest among distribution pathways, though specialty stores retain margin concentration through consultation-driven basket building.
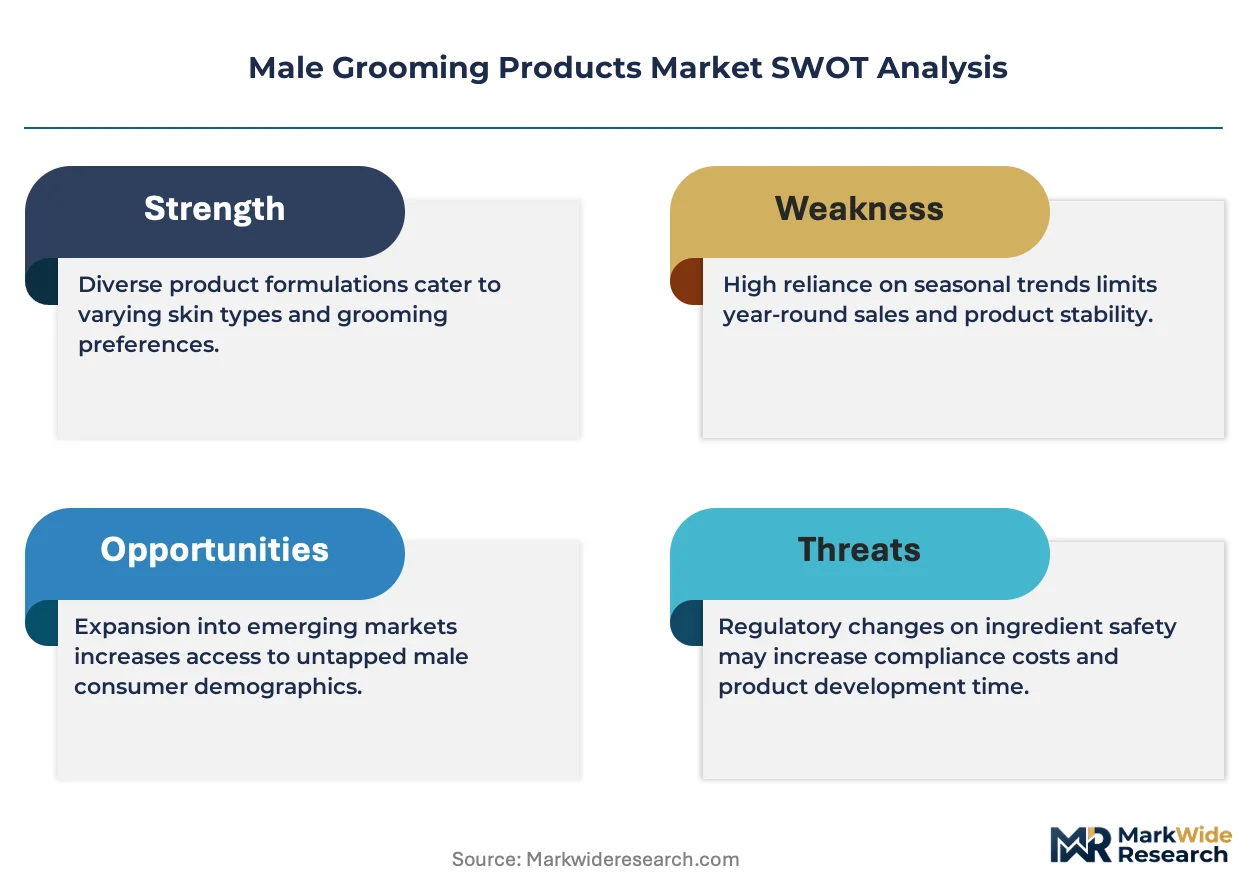
EU REACH restrictions on sensitizing preservatives compel reformulation investments across export-oriented suppliers. The US FDA monograph system governs antiperspirant active concentrations, creating compliance thresholds that filter market entrants. India's BIS certification requirements for cosmetic imports add testing layers that favor manufacturers with Mumbai or Delhi-based quality infrastructure. Stakeholders must monitor regulatory divergence between preservative permissibility regimes and channel-specific labeling mandates to align portfolio planning with enforcement trajectories.
Market Dynamics
Microbiome-conscious formulation chemistry is forcing wholesale reformulation cycles across preservative-dependent product lines, as EU REACH restrictions on isothiazolinones and formaldehyde-releasing compounds cascade through global supply chains.
Growth Catalysts
- Urban professional cohorts:Men aged 25-34 in metropolitan employment clusters normalize multi-step skincare routines, expanding addressable demand beyond traditional shaving and deodorant categories.
- REACH compliance investments:Reformulation mandates for preservative safety create first-mover advantages for suppliers with established green-chemistry pipelines and dermatological testing infrastructure.
- Barbershop channel elevation:Premium service-oriented retail formats in the United States and Germany bundle consultation with product recommendation, lifting basket values and brand loyalty simultaneously.
Market Restraints
- Biotech input cost volatility:Precision peptides and fermented actives face price instability due to concentrated fermentation capacity in contract manufacturing organizations.
- Certification timeline friction:India's BIS import testing requirements add 8-14 week delays for new product introductions, disadvantaging smaller suppliers without Delhi or Mumbai quality infrastructure.
- Waterless formulation limitations:Solid and anhydrous formats struggle to deliver comparable sensorial experience and active stability in antiperspirant and serum applications.
Strategic Opportunities
- Secondary city penetration in India:Tier-2 and Tier-3 urban centers exhibit rising disposable income with underdeveloped organized retail presence for male-specific skincare.
- AI-driven skin diagnostics:Smartphone-based sebum analysis and concern mapping converge with personalized subscription models to capture trial-resistant consumers.
- PLI scheme alignment:India's production-linked incentive framework for personal care manufacturing rewards domestic formulation and packaging investment with tax offsets.
Industry Challenges
- Fermentation specialist scarcity:Industrial microbiology and scale-up process engineering talent pools remain shallow relative to biotech ingredient demand growth.
- Legacy ERP integration:Batch record digitization and environmental monitoring system upgrades impose capital burdens on mid-tier contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Male Grooming Products Market |
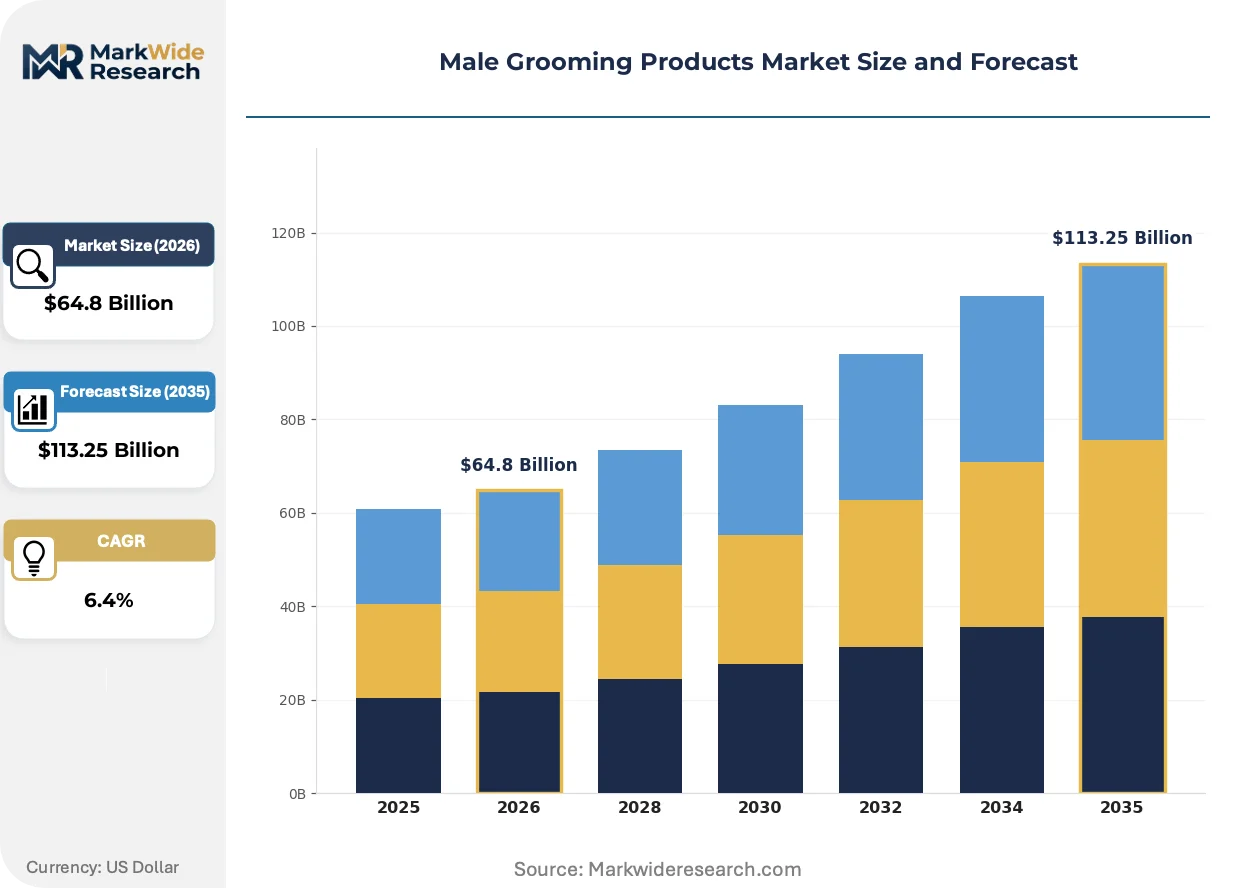
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $113.25 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shaving Cream, Beard Oil, Hair Gel, Deodorant Usage Frequency: Daily, Weekly, Occasional, Seasonal Target Demographic: Teenagers, Young Adults, Middle-Aged, Seniors Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Salons |
| Companies Covered | Procter & Gamble Company, Beiersdorf AG, L'Oréal S.A., Unilever PLC, Colgate-Palmolive Company, Coty Inc., Edgewell Personal Care Company, Shiseido Company Limited, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Male Grooming Products Market Strategic Shifts & Innovations
Active ingredient delivery systems are converging with digital skin assessment tools, compressing the traditional trial-and-error cycle that previously governed male consumer purchase behavior.
Fermentation-derived postbiotics is hybridizing conventional preservative systems, enabling brands to maintain shelf stability while marketing microbiome-friendly claims. Urban professionals in Seoul and New York adopt these formats fastest, drawn by dermatologist endorsement and social proof. The technology is hybridizing competitive positioning between heritage mass-market brands and emerging biotech-native entrants, forcing legacy suppliers to retrofit R&D infrastructure.
EU REACH Annex XVII restrictions on methylisothiazolinone concentrations compel preservative system redesigns across export-oriented suppliers. The regulation compresses formulation flexibility for multi-market SKUs, particularly affecting leave-on products like moisturizers and serums. German and French manufacturers respond by accelerating phenoxyethanol-free and organic acid-based alternatives through stability testing protocols.
Subscription-based replenishment models displace traditional retail trial for core grooming categories, locking in recurring revenue but raising customer acquisition costs. Direct-to-consumer channels in the United States and United Kingdom capture this shift most aggressively, while Indian consumers remain anchored to physical verification for shade and texture matching. Barbershop retail counters the trend through experiential sampling that online formats cannot replicate.
Male Grooming Products Market Segmentation
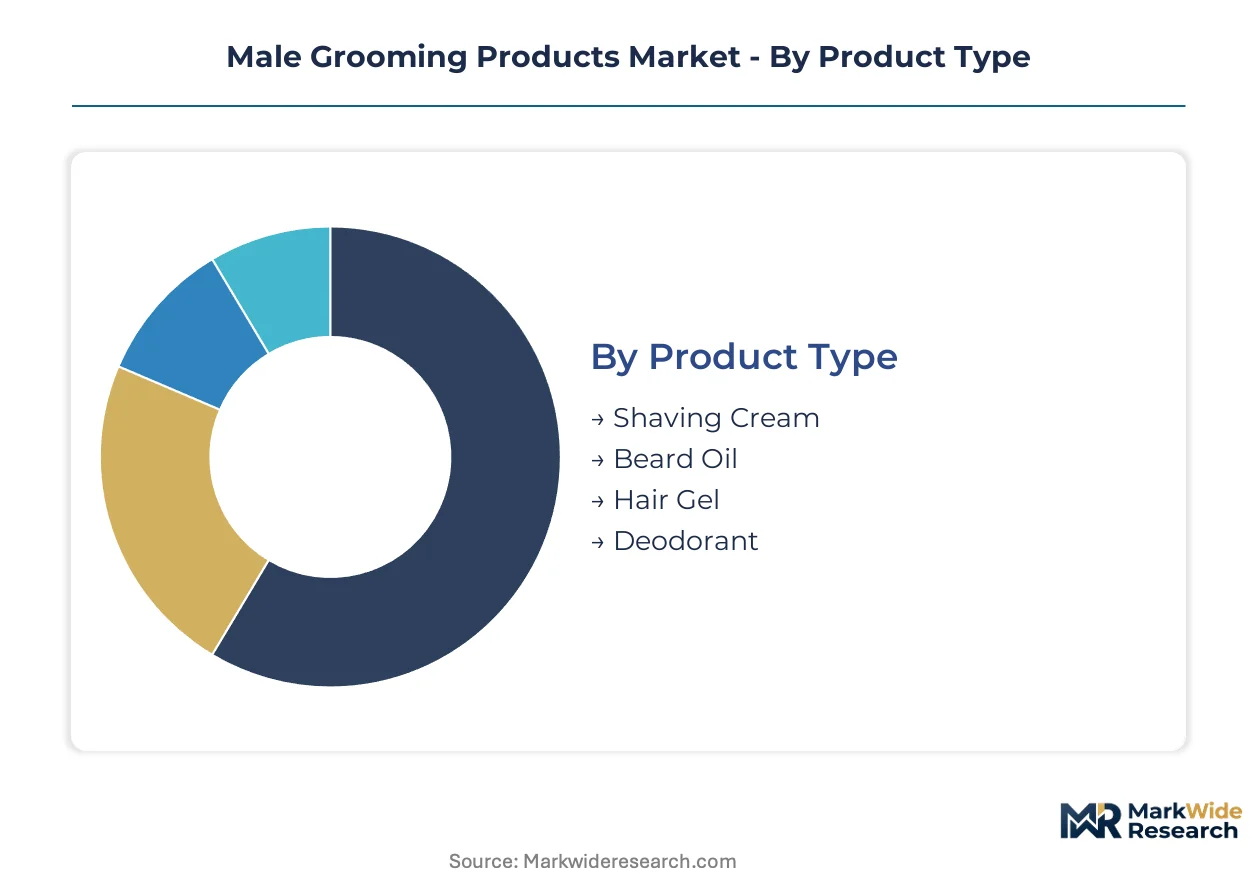
Segmentation in male grooming reveals distinct formulation requirements and channel behaviors that separate mass-market volume plays from premium margin capture. Understanding these divides enables portfolio positioning against divergent consumer willingness-to-pay and regulatory exposure profiles.
Product Type:
Mature categories anchor cash flow while emerging formats reshape R&D investment priorities across supplier laboratories.
- Shaving Cream:Emulsion-based formulations with stearic acid and glycerin bases dominate bathroom counter presence. United States mass retail channels move highest unit volumes, though German consumers increasingly favor brush-applied lather formats that command shelf space premiums.
- Beard Oil:Carrier oil blends with jojoba, argan, and precision-dosed essential oils target the 25-34 urban professional cohort. India exhibits concentrated demand acceleration as facial hair styling normalizes in metropolitan employment clusters.
- Hair Gel:Polymer-thickened aqueous systems deliver hold and shine control through PVP or carbomer matrices.
- Deodorant:Antiperspirant sticks and sprays with aluminum-based actives face EU REACH-driven reformulation pressure.
Shaving cream retains volume leadership; beard oil holds the steepest expansion curve.
Usage Frequency:
Cost tier stratification separates replenishment-driven subscription models from discretionary trial purchases.
- Daily:Core hygiene products including deodorant and facial cleansers sustain predictable replenishment cycles. Subscription channels in the United States and United Kingdom capture recurring revenue through automated replenishment algorithms.
- Weekly:Deep-conditioning treatments and exfoliating scrubs occupy intermittent usage slots. Indian consumers favor physical verification at specialty stores before committing to these higher-ticket items.
- Occasional:Pre-event styling products and specialized treatments generate impulse-driven purchase patterns.
- Seasonal:SPF-enhanced moisturizers and winter barrier creams align with climatic demand fluctuations.
Daily usage commands the largest installed base; weekly applications are climbing the fastest as multi-step routines proliferate.
Target Demographic:
Application intensity varies sharply across life-stage segments with divergent skin biology and social signaling needs.
- Young Adults:Men aged 25-34 drive beard oil and skin serum adoption through professional identity construction. Seoul and New York metropolitan clusters normalize 4-7 step routines fastest.
- Teenagers:Entry-level acne control and basic hygiene formats dominate first purchase occasions. Price sensitivity and social media influence concentrate demand in mass-market retail channels.
- Middle-Aged:Anti-aging actives and hair retention treatments command premium pricing through dermatologist endorsement.
- Seniors:Fragrance-free and sensitive-skin formulations address epidermal barrier degradation.
Young adults represent the primary volume engine; teenagers are gaining share fastest as early routine establishment becomes normalized.
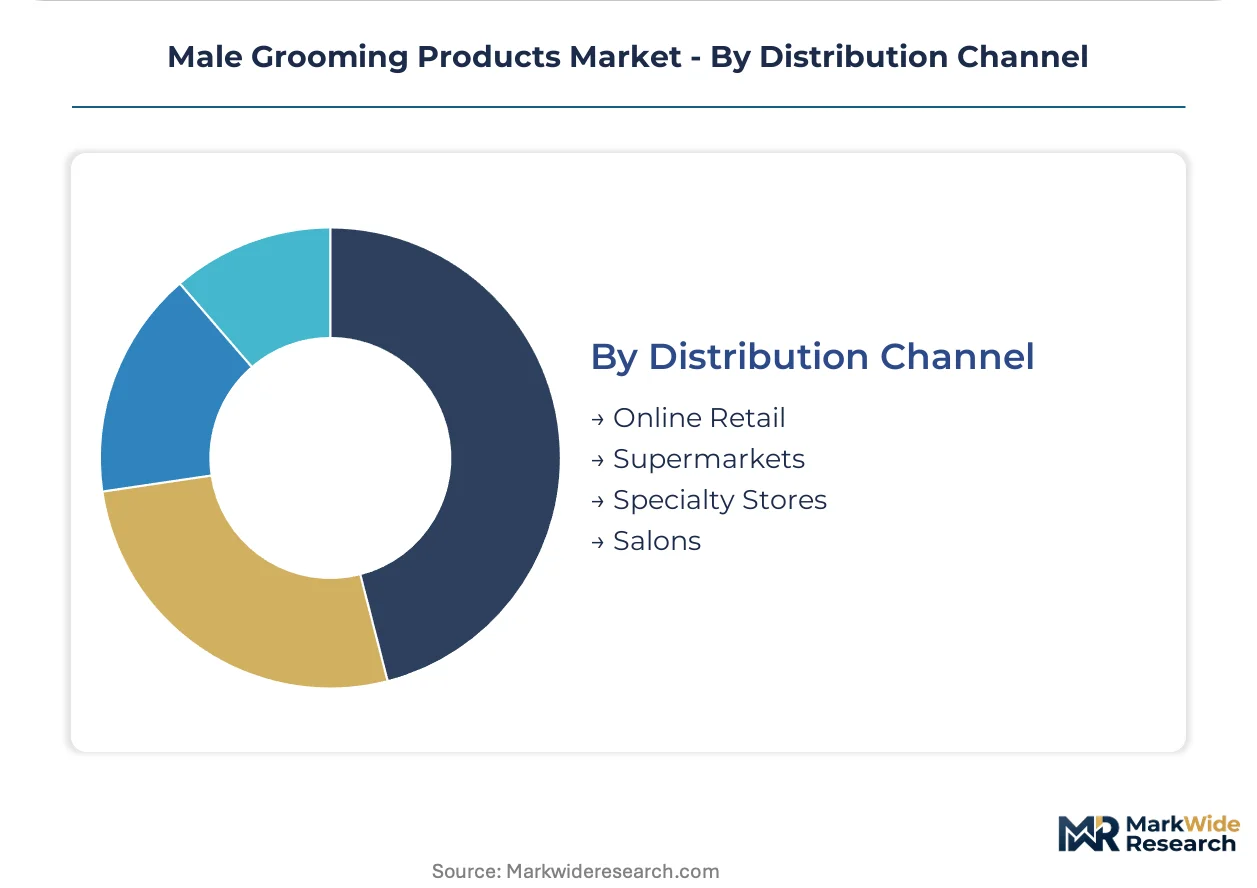
Distribution Channel:
Geography of purchase determines margin structure and consumer education intensity required at point of sale.
- Online Retail:Direct-to-consumer platforms enable AI-driven skin diagnostics and personalized subscription bundling. United States and United Kingdom consumers show highest comfort with texture-matching through digital channels.
- Specialty Stores:Consultation-driven environments in Germany and France build basket value through trained staff recommendations. These formats retain margin concentration despite slower inventory turns.
- Supermarkets:Mass-market deodorant and shaving cream categories depend on promotional velocity and shelf placement economics.
- Salons:Barbershop retail in the United States bundles service experience with product trial, generating loyalty lock-in unavailable through digital formats.
Online retail is expanding most quickly; specialty stores maintain the steepest margin profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-formulated beard oils and barrier-repair serums to United States professional barbershop networks, establishing a transatlantic trade corridor that channels EU REACH-compliant formulations into North American premium retail.
United States
Urban professionals in New York and Los Angeles normalize 4-7 step skincare routines, driving serum and postbiotic moisturizer demand through direct-to-consumer subscription channels. FDA monograph compliance governs antiperspirant active concentrations, filtering market entrants without dermatological testing infrastructure. Cincinnati hosts Procter & Gamble's R&D campus, where precision peptide development for post-shave recovery anchors domestic formulation leadership.
Germany
Brush-applied shaving lather formats command shelf space premiums in Hamburg and Berlin specialty retail, while Hamburg-based Beiersdorf laboratories specialize in barrier-repair ceramides for sensitive male skin. ECHA REACH Annex XVII restrictions on methylisothiazolinone accelerate phenoxyethanol-free alternative development through German stability testing protocols. Bavarian contract manufacturers retrofit fermentation capacity to supply biotech-derived actives across European export markets.
India
Facial hair styling normalizes in Mumbai and Delhi metropolitan employment clusters, concentrating beard oil demand acceleration among men aged 25-34. BIS certification requirements for cosmetic imports impose 8-14 week testing delays that favor suppliers with Delhi or Mumbai quality infrastructure. The PLI scheme for personal care manufacturing rewards domestic formulation investment with tax offsets, drawing packaging and blending capacity to Gujarat and Maharashtra industrial corridors.
South Korea
Seoul metropolitan consumers adopt microbiome-friendly formats fastest, drawn by dermatologist endorsement and social proof validation. MFDS cosmetic safety standards enforce rigorous preservative documentation that aligns with EU REACH stringency. Pangyo Techno Valley clusters digital skin diagnostic startups converging AI-based sebum analysis with personalized subscription bundling.
Japan
Tokyo and Osaka professionals sustain premium pricing for fragrance-free sensitive-skin formulations addressing epidermal barrier degradation in middle-aged demographics. METI industrial policy supports fermentation-derived ingredient scale-up through public-private R&D partnerships. Kao Corporation anchors domestic market presence through dermatological testing protocols validated across diverse ethnic skin profiles.
Male Grooming Products Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where mass-market scale advantages collide with premium consultation-driven retail formats. The vendor base organizes around three strategic archetypes: multinational conglomerates with captive R&D infrastructure, regional specialists with barbershop channel depth, and biotech-native entrants leveraging fermentation-derived differentiation. Dominant competitive moves include backward integration into active ingredient production and geographic expansion through acquisition of Mumbai or Delhi-based quality infrastructure.
Within the multinational conglomerate tier, Procter & Gamble Company, Beiersdorf AG, and L'Oréal S.A. exemplify divergent R&D anchoring strategies. Cincinnati-based Procter & Gamble represents the precision peptide development archetype through captive fermentation capabilities. Hamburg-anchored Beiersdorf occupies a position emphasizing barrier-repair ceramide specialization for sensitive skin applications. Paris-headquartered L'Oréal exemplifies dermatological testing protocol scale across diverse ethnic skin validation requirements.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Beiersdorf AG |
| L'Oréal S.A. |
| Unilever PLC |
| Colgate-Palmolive Company |
| Coty Inc. |
| Edgewell Personal Care Company |
| Shiseido Company Limited |
| Kao Corporation |
| Others |
Cost & Logistics Intelligence
Cincinnati-based fermentation capacity expansion by precision peptide suppliers tilts pricing power toward captive R&D infrastructure holders, compressing margins for contract-dependent brands while elevating premiums for microbiome-certified formulations. EU REACH-driven reformulation cycles add compliance cost layers that concentrate margin extraction among suppliers with Hamburg or Paris-based dermatological testing protocols.
Pricing Analysis
Next-generation biotech-actives command 40-60% premiums over conventional preservative-dependent formulations, while legacy mass-market SKUs face cost compression from aluminum-active antiperspirant reformulation mandates. Three-tier pricing structure across premium, standard, and economy levels separates dermatologist-endorsed serums from mass retail deodorants and entry-level shaving creams. Pricing pressure stems from concentrated fermentation capacity in contract manufacturing organizations. Teenage entry-level buyers exhibit highest price sensitivity; middle-aged anti-aging segments show lowest.
Supply Chain Analysis
EU REACH Annex XVII restrictions on methylisothiazolinone limit preservative system flows into export-oriented formulations, forcing redesigns across leave-on product lines. Germany, France, and India anchor supply concentration for barrier-repair ceramides and beard oil carrier blends. Raw material dependencies center on jojoba oil, argan oil, and precision-dosed essential oil inputs. Single-source vulnerability concentrates in fermentation-derived postbiotic actives. Distribution runs through direct-to-consumer platforms and barbershop retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment models generate recurring revenue streams expanding faster than hardware-centric trial purchases, positioning service-attach layers as the primary value capture mechanism.
For Market Incumbents: Build captive fermentation moats through backward integration into precision peptide production, insulating margin structures from biotech input cost volatility. Acquire Delhi or Mumbai-based quality infrastructure to compress BIS certification timelines. Defend against biotech-native entrants by accelerating phenoxyethanol-free alternative development through Hamburg or Paris laboratories. For New Entrants and Emerging Players: Tier-2 and Tier-3 Indian urban centers present underpenetrated white space with rising disposable income and underdeveloped organized retail presence. Target AI-driven skin diagnostics convergence with personalized subscription bundling as the most penetrable entry vector. Deploy smartphone-based sebum analysis tools to capture trial-resistant consumers before physical verification requirements anchor channel preference. For Investors and Strategic Acquirers: Long-term, this sits as a biotech-capability play because fermentation-derived differentiation will separate margin winners from commodity losers across the analysis window. Target contract manufacturers with retrofit fermentation capacity and established dermatological testing protocols. Watch EU REACH enforcement trajectories on preservative safety as the signal for reformulation investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Buildout | Cincinnati and Hamburg laboratories anchor precision peptide supply security for post-shave recovery formulations. |
| Regulatory Compliance Investment | EU REACH-aligned preservative system redesigns enable continued access to German and French export markets. |
| Direct-to-Consumer Platform Launch | AI-driven skin diagnostics in Seoul and New York compress trial-and-error purchase cycles for urban professionals. |
| Barbershop Channel Expansion | United States service-oriented retail formats bundle consultation with product trial, generating loyalty lock-in. |
| Secondary City Penetration | India's PLI scheme rewards Gujarat and Maharashtra manufacturing investment with tax offsets for domestic formulation. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with formulation chemists, brand managers at grooming multinationals, barbershop retail operators, and BIS certification consultants; and secondary validation through EU REACH regulatory filings, FDA antiperspirant monograph updates, and Indian customs import records. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates from retail audit databases.
Forecast inputs span product type, usage frequency, target demographic, and distribution channel dimensions across the analysis window. CAGRs derive from segment-level growth rate blending anchored to observed urban professional adoption curves and regulatory compliance investment trajectories. Modeling incorporates microbiome-friendly formulation penetration rates and subscription channel shift velocities as industry-specific variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biotech-native entrants or accelerated EU REACH enforcement would shift outcomes. Material shifts in fermentation capacity concentration or preservative permissibility regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Facial Care Products Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Intimate Wash Care Products Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Cosmetology Market
Beauty & Personal Care
Nail Care Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Bath and Body Products Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
India Antibacterial Soap Market
Beauty & Personal Care
South Korea Beauty and Personal Care Products Market
Beauty & Personal Care
Beauty Oils Market