
 Portable Massage Devices Market | 2026-2036
Portable Massage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Massage Devices Market Analytics
Corporate wellness buyers is rotating toward portable massage devices as employee retention tools, displacing traditional ergonomic furniture budgets. Therabody leverages direct-to-consumer subscription models to sustain recurring revenue streams. Hyperice anchors professional sports partnerships that differentiate its brand in athletic recovery. Beurer GmbH competes through European pharmacy channel control, occupying shelf space that limits competitor access.
Portable massage devices are electromechanical or battery-operated instruments designed to deliver percussive, vibratory, or thermal therapy to soft tissue, typically operating at frequencies between 20-60 Hz and amplitudes of 10-16 mm for percussive models. Massage guns lead product type revenue due to athletic adoption and social media visibility, while heating pads represent a mature segment with stable household penetration. Battery-powered units are the fastest-growing power source category as lithium-ion energy density improvements enable cordless operation at higher stall forces.
FDA oversight of therapeutic claims shapes product labeling and marketing boundaries in the United States, while CE marking under the EU MDR governs electrical safety and electromagnetic compatibility for European market access. Japan's PMDA and METI coordinate on household medical device classifications that determine reimbursement eligibility and retail channel permissions. Stakeholders must monitor evolving battery transportation regulations and medical device software validation requirements as products integrate app-connected prescription protocols.
Market Dynamics
Corporate wellness procurement is displacing traditional ergonomic furniture budgets with portable massage device allocations, while USB-C charging standardization and lithium-ion energy density gains compress cordless unit development cycles.
Growth Catalysts
- Employee Retention Programs:Human resources departments in United States technology firms now specify percussive therapy units for on-site recovery rooms. This procurement category was absent five years ago.
- FDA Therapeutic Claims Pathway:Clear labeling boundaries for percussive and vibratory devices enable marketing that distinguishes wellness from medical applications. Manufacturers gain pricing power through compliant positioning.
- Lithium-Ion Energy Density:Battery chemistry improvements extend cordless massage gun runtime above 300 minutes at stall forces exceeding 60 pounds. This specification threshold unlocks professional athletic trainer adoption.
Market Restraints
- Raw Material Concentration:Rare earth elements for high-torque brushless motors concentrate in Chinese processing facilities. Supply disruption risk elevates inventory carrying costs for cordless unit assemblers.
- CE Marking Under EU MDR:Electromagnetic compatibility testing timelines for European market access now exceed fourteen months. Small manufacturers lack capital reserves to bridge revenue gaps during certification.
- Heating Pad Substitution:Mature electric warming products occupy established retail shelf space in German pharmacy channels. Price-sensitive household buyers perceive functional overlap with thermal massage devices.
Strategic Opportunities
- Japan's Aging Demographics:METI household medical device classifications create reimbursement pathways for thermal therapy units targeting elderly home care. Retail channel permissions follow certification achievement.
- App-Connected Prescription Protocols:Software validation requirements under FDA digital health guidance are converging with Bluetooth Low Energy hardware integration. This technology pairing enables remote therapist monitoring.
- Direct-to-Consumer Subscription:Attachment replenishment and firmware upgrade services bypass traditional sporting goods retail. Recurring revenue models reduce customer acquisition cost dependence.
Industry Challenges
- Battery Transportation Regulations:IATA lithium-ion shipping restrictions complicate cross-border fulfillment for direct-to-consumer brands. Warehouse network expansion becomes mandatory for market access.
- Software Validation Timelines:FDA 510(k) requirements for app-connected therapeutic protocols extend product development cycles. Engineering teams must integrate quality management systems early.
- Professional Sports Team Procurement:Athletic trainer certification requirements vary across United States collegiate conferences. Sales cycles fragment as institutional buyers demand customized compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Massage Devices Market |
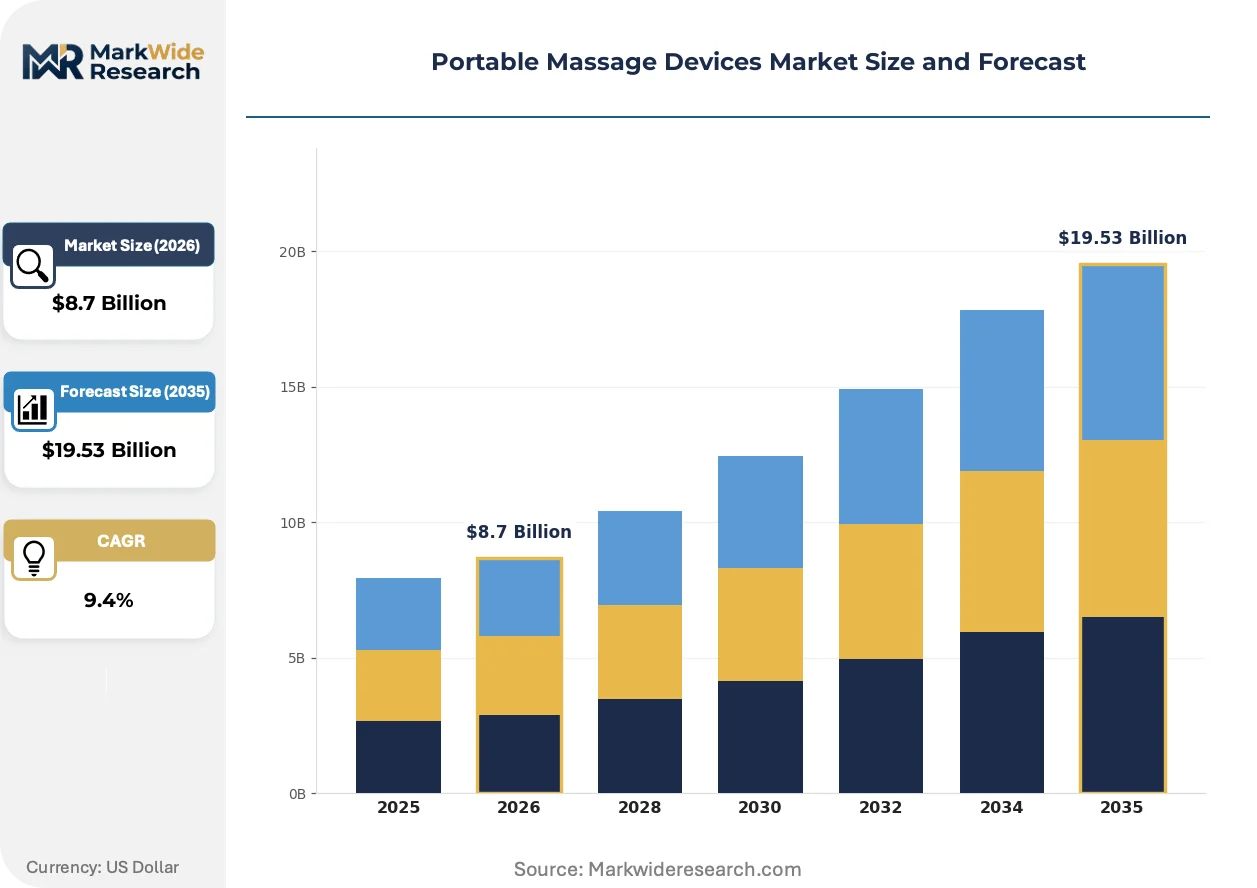
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Massagers, Massage Guns, Heating Pads, Shiatsu Devices End User: Consumers, Athletes, Rehabilitation Specialists, Wellness Centers Power Source: Battery-Powered, Rechargeable, Plug-in, Solar-Powered Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Therabody, Hyperice, Beurer GmbH, Homedics, OSIM International Pte. Ltd., Luraco Technologies, Panasonic, Conair Corp., Thumper Massager Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Massage Devices Market Evolving Landscape
Percussive therapy hardware is fragmenting into distinct performance tiers while regulatory software requirements and buyer procurement patterns simultaneously reshape competitive positioning across distribution channels.
Thermal-mechanical hybrid units are bifurcating the premium segment from pure percussive devices. Professional athletic trainers in National Football League and National Basketball Association facilities now specify combined heat-vibration protocols for post-game recovery. This specification convergence is compressing standalone heating pad margins while elevating average selling prices for multi-modal units above four hundred dollars.
CE marking under EU MDR now requires electromagnetic compatibility testing for all battery-operated therapeutic devices. German manufacturers face fourteen-month certification timelines that delay product launches. European pharmacy chains respond by consolidating shelf space around established brands with existing MDR documentation, raising barriers for new entrants.
Corporate procurement departments now bundle portable massage devices with mental health stipends and fitness subsidies. United States technology sector human resources teams issue quarterly wellness credits redeemable through direct-to-consumer platforms. This purchasing pattern disintermediates traditional sporting goods retail in coastal metropolitan markets where employer concentration exceeds national averages.
Portable Massage Devices Market Segmentation
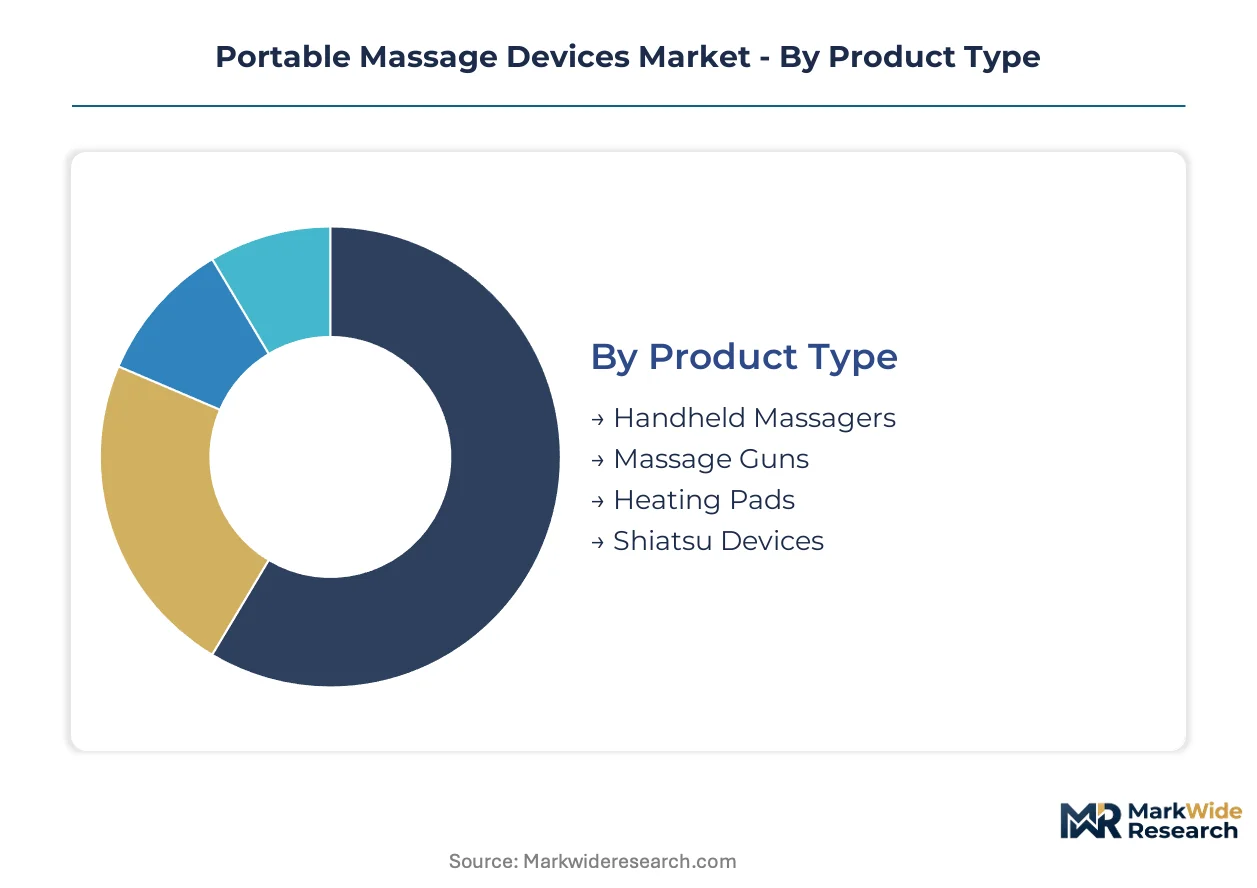
Portable massage device manufacturers face divergent substitution threats across product architectures, with electromechanical innovations threatening thermal legacy lines while cordless mobility reshapes power source hierarchies. Segment boundaries are hardening around certification requirements and channel access permissions rather than pure technical specifications.
Product Type:
Heating pads confront the most acute substitution pressure as thermal-mechanical hybrids capture premium positioning in professional athletic recovery rooms.
- Handheld Massagers:Vibratory mechanisms operating at 20-60 Hz target household penetration with ergonomic grips and variable intensity settings. Demand concentrates in German pharmacy channels where Beurer GmbH controls shelf access, though price-sensitive buyers perceive functional overlap with massage guns.
- Massage Guns:Percussive units deliver 10-16 mm amplitude at stall forces exceeding 60 pounds, enabled by lithium-ion energy density improvements above 300-minute runtime. United States technology firms now specify these for on-site employee recovery rooms, displacing traditional ergonomic furniture allocations.
- Heating Pads:Mature electric warming products with stable household penetration face margin compression from multi-modal competitors.
- Shiatsu Devices:Rotating node mechanisms simulate manual pressure techniques for seated or lying applications.
Massage guns retain volume leadership; handheld massagers hold the steepest expansion curve.
End User:
Cost tier stratification separates institutional procurement with compliance documentation requirements from direct-to-consumer simplicity.
- Consumers:Household purchasers prioritize USB-C charging standardization and cordless convenience for intermittent muscle tension relief. Online retail platforms capture this volume through subscription attachment replenishment models that reduce customer acquisition cost dependence.
- Athletes:Professional and amateur competitors demand percussive therapy protocols validated by National Football League and National Basketball Association athletic trainers. This segment commands average selling prices above four hundred dollars for thermal-mechanical hybrid specifications.
- Rehabilitation Specialists:Clinical users require FDA 510(k) documentation for therapeutic claims and app-connected prescription protocol integration.
- Wellness Centers:Corporate and hospitality procurement departments bundle devices with mental health stipends and fitness subsidies.
Consumers dominate absolute volume; athletes generate the highest per-unit margin capture.
Power Source:
Supply concentration in Chinese rare earth processing facilities elevates inventory carrying costs for cordless motor assemblers.
- Battery-Powered:Lithium-ion cells with improved energy density enable professional-grade stall forces without cord constraint. IATA shipping restrictions complicate cross-border fulfillment, forcing warehouse network expansion for direct-to-consumer brands.
- Rechargeable:Nickel-metal hydride and older lithium chemistries serve price-sensitive segments with shorter runtime expectations.
- Plug-in:AC-powered units retain clinical and stationary applications where mobility is secondary to sustained output.
- Solar-Powered:Photovoltaic integration targets outdoor athletic and emergency preparedness niches with limited commercial penetration.
Battery-powered units are gaining share fastest; plug-in configurations retain institutional preference.
Distribution Channel:
Geographic clustering of employer concentration in coastal United States metropolitan markets accelerates procurement pattern divergence from traditional sporting goods retail.
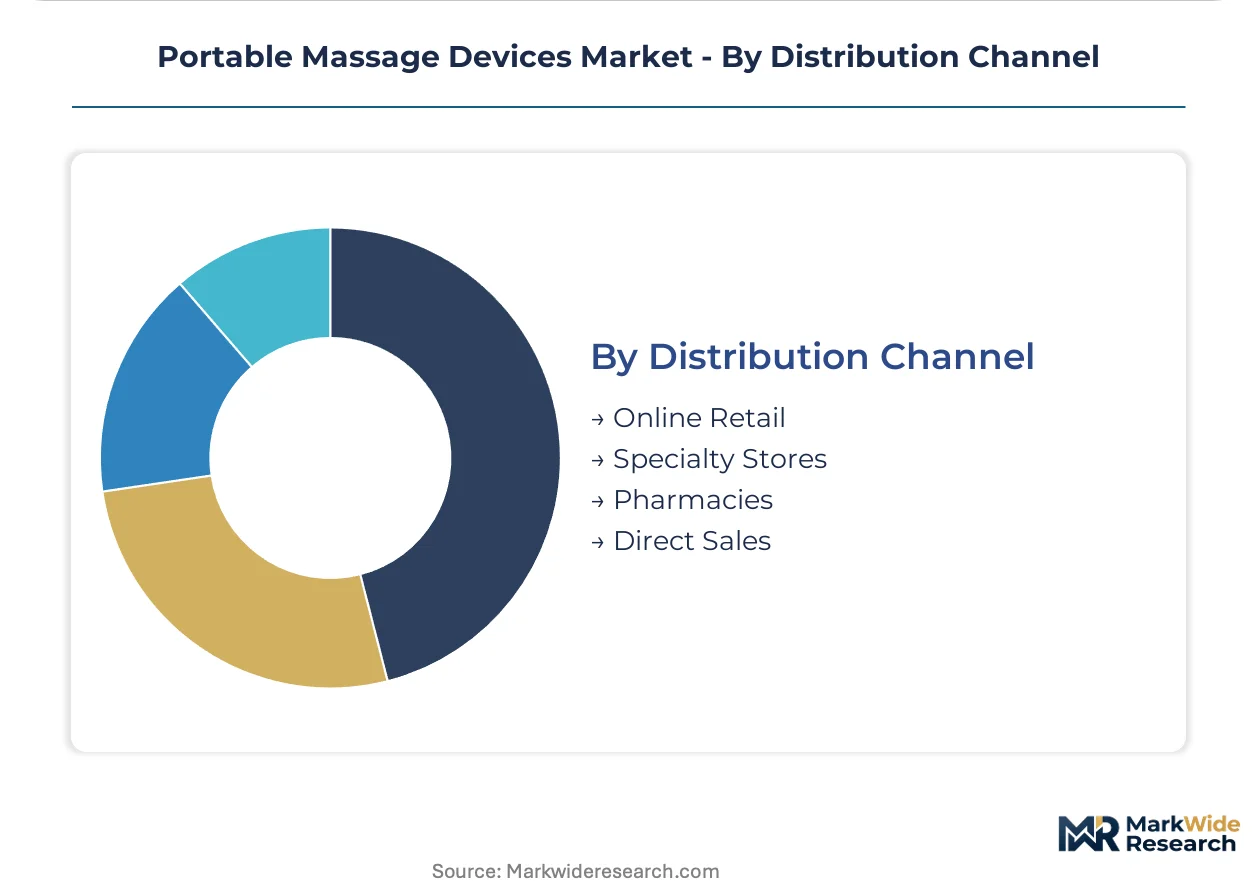
- Online Retail:Direct-to-consumer platforms bypass fourteen-month EU MDR certification delays by shipping from regional fulfillment centers. Firmware upgrade services and attachment replenishment subscriptions sustain recurring revenue streams independent of physical shelf access.
- Specialty Stores:Sporting goods and fitness equipment retailers face disintermediation as corporate wellness credits flow through employer-integrated digital platforms.
- Pharmacies:German and Japanese drugstore chains consolidate around established brands with existing CE marking and METI household medical device classifications, raising barriers for new entrants.
- Direct Sales:Institutional procurement through athletic trainer networks and corporate human resources departments requires customized compliance documentation varying across United States collegiate conferences.
Online retail captures the fastest volume growth; pharmacies defend the highest margin stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export percussive therapy hardware to United States corporate wellness buyers and German pharmacy distributors, establishing the dominant trade corridor for cordless massage device assembly.
United States
Technology sector human resources departments in San Francisco and Seattle metropolitan areas now specify massage guns for on-site employee recovery rooms, displacing traditional ergonomic furniture budgets. FDA therapeutic claims pathways enable compliant marketing that distinguishes wellness from medical applications. Corporate procurement clusters in coastal metropolitan markets accelerate direct-to-consumer platform adoption through employer-integrated wellness credits.
Germany
Pharmacy chains consolidate shelf space around established brands with existing CE marking documentation under EU MDR electromagnetic compatibility requirements. Beurer GmbH maintains channel control through existing MDR certification that limits competitor access. Manufacturing concentration in Baden-Württemberg and Bavaria supports electromechanical component supply for thermal-mechanical hybrid units.
Japan
METI household medical device classifications create reimbursement pathways for thermal therapy units targeting elderly home care demographics in Tokyo and Osaka metropolitan corridors. PMDA coordination with METI determines retail channel permissions following certification achievement. Aging population concentration in Kanto and Kansai regions sustains demand for prescription-integrated massage protocols.
China
Rare earth element processing for high-torque brushless motors concentrates in Jiangxi and Inner Mongolia facilities, elevating inventory carrying costs for cordless unit assemblers. MIIT battery transportation regulations intersect with IATA lithium-ion shipping restrictions for cross-border fulfillment. Shenzhen and Dongguan manufacturing clusters supply percussive therapy hardware to North American and European buyers.
Portable Massage Devices Market Competitive Landscape
Player mix skews toward vertically integrated wellness technology specialists and electromechanical component fabricators with pharmacy channel relationships. Market structure consolidates around three performance tiers: premium athletic recovery brands, mid-market direct-to-consumer platforms, and established European pharmacy incumbents. Strategic archetypes include subscription-model operators, professional sports partnership anchors, and regulatory certification specialists. Dominant competitive moves encompass M&A activity targeting software validation capabilities and warehouse network expansion to bypass IATA lithium-ion shipping restrictions.
Among United States-based wellness technology operators, Therabody and Hyperice exemplify divergent archetype positioning within the premium athletic recovery tier. Therabody represents the subscription-model operator archetype through direct-to-consumer recurring revenue structures. Hyperice anchors the professional sports partnership strategy that differentiates brand positioning in athletic recovery channels. Beurer GmbH occupies the European pharmacy incumbent position, with its German GmbH structure reflecting the regulatory certification specialist archetype that controls shelf access through existing CE marking documentation.
| Leading Market Players |
|---|
| Therabody |
| Hyperice |
| Beurer GmbH |
| Homedics |
| OSIM International Pte. Ltd. |
| Luraco Technologies |
| Panasonic |
| Conair Corp. |
| Thumper Massager Inc. |
| Others |
Value Network & Pricing Analysis
CE marking under EU MDR gates both supply qualification and price differentiation simultaneously, as fourteen-month electromagnetic compatibility timelines force manufacturers to pre-commit capital before revenue generation while pharmacy chains reward compliant incumbents with shelf access premiums. Battery chemistry improvements and USB-C standardization compress development cycles unevenly across tiers, concentrating pricing power with firms that amortize certification costs across volume.
Pricing Analysis
Current-generation thermal-mechanical hybrid units command four-hundred-dollar-plus price points against prior-generation pure percussive devices and next-generation app-connected prescription protocols still in validation. Three-tier pricing structure across premium, standard, and economy levels separates professional athletic trainer specifications from corporate wellness procurement and price-sensitive household buyers. Cost compression in the standard tier intensifies because lithium-ion energy density improvements democratize cordless stall-force performance. Corporate wellness buyers exhibit lowest price sensitivity due to employee retention budget displacement, while German pharmacy price-sensitive households perceive functional overlap between heating pads and thermal massage devices.
Supply Chain Analysis
Rare earth element processing in Jiangxi and Inner Mongolia facilities underwrites high-torque brushless motor availability for cordless massage gun assemblers. Chinese rare earth concentration, Japanese lithium-ion cell production, and German electromechanical component fabrication feed finished goods assembly in Shenzhen and Dongguan clusters. Single-source vulnerability concentrates in Chinese rare earth processing, elevating inventory carrying costs for cordless unit manufacturers. Distribution runs through direct-to-consumer platforms, pharmacy chains with existing CE marking, and corporate procurement departments bypassing traditional sporting goods retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Attachment replenishment and firmware upgrade subscriptions expand faster than hardware unit sales, transforming one-time transactions into recurring revenue streams that reduce customer acquisition cost dependence across the analysis window.
For Market Incumbents: Fortify pharmacy channel control through preemptive EU MDR recertification investment before fourteen-month timelines extend further. Deepen backward integration into lithium-ion cell supply through offtake agreements with South Korean and Japanese producers, neutralizing rare earth concentration risk that elevates inventory carrying costs for cordless motor assemblers.
For New Entrants and Emerging Players: Anchor in Japan's METI household medical device classification pathway for thermal therapy units targeting elderly home care reimbursement eligibility. Corporate wellness procurement in United States coastal metropolitan markets offers the most penetrable segment, with employer-integrated digital platforms enabling direct-to-consumer bypass of traditional sporting goods retail shelf access barriers.
For Investors and Strategic Acquirers: FDA 510(k) software validation requirements for app-connected prescription protocols reshape the acquisition landscape toward targets with embedded quality management systems and Bluetooth Low Energy hardware integration capabilities. Five-to-ten-year viability favors firms with recurring revenue attachment models over pure hardware transactional players. Monitor IATA lithium-ion shipping restriction enforcement as the inflection signal forcing warehouse network expansion among direct-to-consumer brands.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Fourteen-month EU MDR electromagnetic compatibility timelines gate pharmacy shelf access for European market entry. |
| Software Companion Development | FDA 510(k) validation requirements for app-connected prescription protocols enable remote therapist monitoring revenue. |
| Reimbursement Strategy | METI household medical device classifications unlock Japanese elderly home care procurement channels. |
| Hospital System Partnership | NFL and NBA athletic trainer specifications validate premium thermal-mechanical hybrid protocols for institutional adoption. |
| Direct-to-Consumer Launch | Employer-integrated wellness credits in United States technology firms disintermediate traditional sporting goods retail. |
Research Methodology
Initial hypotheses were tested against primary input from product development executives at wellness technology firms, athletic trainers at professional sports franchises, corporate human resources procurement leads, pharmacy category buyers, and biomedical engineers at rehabilitation clinics and refined through secondary validation against FDA 510(k) filings, METI household medical device classification databases, EU MDR CE marking documentation, customs trade data for lithium-ion battery shipments, and SEC filings of publicly traded wellness technology operators. Bottom-up unit economics and top-down macroeconomic triangulation converged on segment-level outputs.
Variance decomposition across product type, power source architecture, end-user application, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from modeled adoption curves incorporating battery energy density improvement trajectories, USB-C charging standardization penetration, and corporate wellness program budget reallocation patterns. Industry-specific forecast inputs included lithium-ion cell cost curves and athletic trainer certification requirement fragmentation across United States collegiate conferences.
Material uncertainties — IATA lithium-ion shipping restriction enforcement intensity, EU MDR electromagnetic compatibility timeline extensions, and rare earth element export policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions about continued employer wellness budget expansion and battery chemistry improvement trajectories. Practitioners should keep alternative scenarios live as METI reimbursement pathway expansions and FDA digital health guidance evolutions reshape market access conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Hand Massager Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Feminine Hygiene Products Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Shaving Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market