
 Global Canes and Walking Sticks Market | 2026-2036
Global Canes and Walking Sticks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Canes and Walking Sticks Market Foresight
Modular cane systems that separate grip, shaft, and tip components is rebalancing how buyers evaluate lifetime value against upfront cost. Carex Health Brands leverages broad pharmacy distribution to sustain volume leadership in North American retail channels. Drive DeVilbiss Healthcare anchors its position through vertical control over aluminum forging operations. Medline Industries competes by dominating hospital procurement contracts with standardized adjustable cane configurations.
Canes and walking sticks are assistive mobility devices engineered with load-bearing shafts typically rated for 113–136 kilograms, paired with anti-slip ferrules and ergonomically angled grips to redistribute upper-body weight during ambulation. Their primary purpose spans post-injury rehabilitation, chronic balance impairment management, and preventive fall reduction in aging populations. Folding and adjustable canes lead volume sales due to travel portability and height customization, while carbon fiber variants command premium positioning through superior strength-to-weight ratios. Aluminum remains the dominant material segment by unit economics, though wood persists in ceremonial and heritage product lines.
FDA clearance pathways for Class I durable medical equipment govern US market access, while the EU Medical Device Regulation imposes clinical evaluation requirements on cane systems marketed for rehabilitation claims. Japan's Ministry of Economy, Trade and Industry reimbursement codes directly shape domestic demand by subsidizing prescribed mobility aids for home-bound elderly patients. Stakeholders must monitor evolving ISO 11199 durability standards and anticipate how carbon fiber supply constraints will reshape material sourcing strategies across manufacturing networks.
Market Dynamics
Carbon fiber supply concentration in Asian forging networks is compressing margin structures for premium cane manufacturers while simultaneously enabling sub-250-gram product categories that redefine portability standards.
Growth Catalysts
- Japan METI Reimbursement Codes:Home-care equipment subsidies for prescribed mobility aids channel institutional procurement toward certified adjustable models, expanding the reimbursable device pool for elderly patients.
- ISO 11199 Durability Certification:Rehabilitation centers in Germany now mandate ISO-certified canes for post-operative protocols, creating procurement filters that favor standardized load-bearing specifications.
- Carbon Fiber Weight Thresholds:Manufacturing advances have driven premium folding models below 250 grams, opening travel-portable segments previously constrained by aluminum bulk.
Market Restraints
- Raw Material Concentration:Precursor carbon fiber supply clusters in China and Japan, exposing manufacturers to geopolitical friction and export licensing volatility.
- EU MDR Clinical Evaluation:Rehabilitation claims now trigger clinical data requirements under the EU Medical Device Regulation, extending time-to-market for functional positioning.
- Aluminum Price Volatility:Energy-intensive smelting costs fluctuate with European natural gas benchmarks, compressing margins on volume-standard economy segments.
Strategic Opportunities
- Modular Component Systems:Separable grip-shaft-tip architectures enable lifetime value propositions that shift buyer calculus from upfront cost to replacement-part economics.
- India PLI Scheme Alignment:Medical device production incentives under India's Performance-Linked Incentive scheme attract contract manufacturing for export-oriented aluminum forging.
- Telehealth Integration:Remote gait assessment protocols create direct-to-patient channels that bypass traditional pharmacy and hospital procurement hierarchies.
Industry Challenges
- ISO 11199 Testing Backlogs:Certification queue delays at accredited laboratories extend product launch timelines for durability-rated models.
- Ergonomic Design Talent Scarcity:Biomechanical engineering expertise for anthropometric grip development concentrates in German and Japanese research clusters.
- Legacy Hospital Procurement Systems:ERP integration friction with standardized adjustable cane configurations slows adoption of modular inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Canes and Walking Sticks Market |
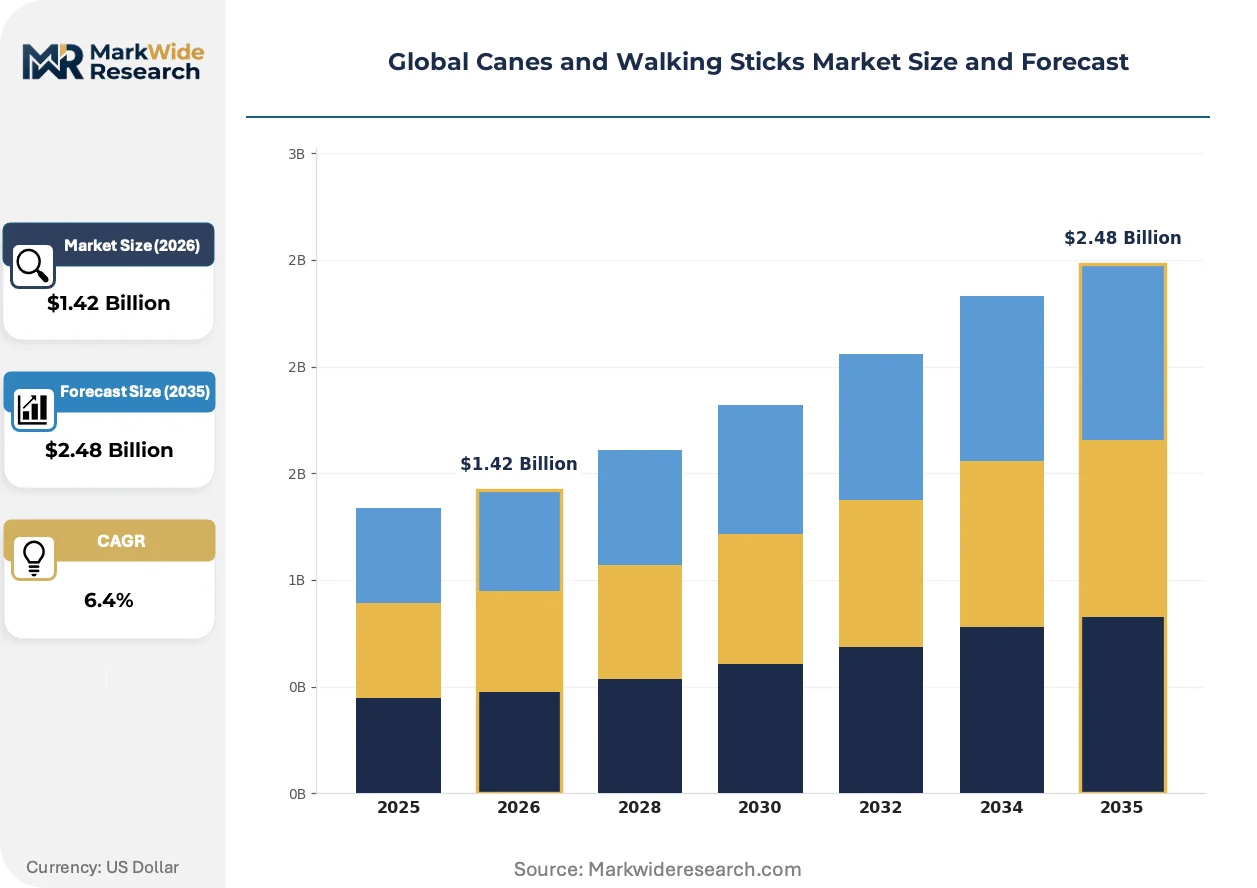
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Cane, Quad Cane, Adjustable Cane, Derby Cane, Offset Cane Material: Wood, Aluminum, Carbon Fiber, Steel, Plastic End User: Elderly Individuals, Physically Challenged, Rehabilitation Patients, Outdoor Enthusiasts Distribution Channel: Pharmacies, Medical Stores, Online Retailers, Specialized Mobility Equipment Stores |
| Companies Covered | Cardinal Health, Carex Health Brands, Invacare Corporation, Royal Canes, NOVA Medical Products, Drive DeVilbiss Healthcare, Sunrise Medical, Hugo Mobility, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Canes and Walking Sticks Market Shifts & Advancements
Active reshaping in this market centers on material science breakthroughs, regulatory recalibration of medical claims, and the disintermediation of traditional durable medical equipment distribution channels.
Carbon fiber composite architecture is modularizing how manufacturers approach product lifecycle design. The material enables separable shaft segments that maintain torsional rigidity across folding joints. Rehabilitation specialists in Japanese geriatric care facilities are adopting these systems for patient-specific height adjustment. The technology is modularizing supply chain relationships, as grip specialists and ferrule manufacturers now integrate with carbon fiber shaft suppliers through standardized interface specifications rather than captive vertical production.
REACH substance restrictions on certain polymer additives are forcing reformulation of rubber ferrule compounds across EU-bound product lines. The European Chemicals Agency's candidate list expansion now covers several legacy anti-slip polymerizers used in high-friction tips. German and French distributors are accelerating qualification of alternative silicone-based formulations ahead of sunset dates. This regulatory pressure compresses formulation R&D cycles while creating compliance differentiation between EU-certified and non-certified inventory pools.
Hospital procurement departments are consolidating mobility aid purchasing through group purchasing organizations that bundle canes with orthopedic braces and wound care supplies. This concentration shifts vendor selection criteria toward contract breadth rather than product-specific performance metrics. Drive DeVilbiss Healthcare and Medline Industries have reorganized sales structures to address GPO contracting committees directly. The United States acute care channel exhibits the most pronounced consolidation, with three national GPOs controlling access to the majority of inpatient rehabilitation units.
Global Canes and Walking Sticks Market Segmentation
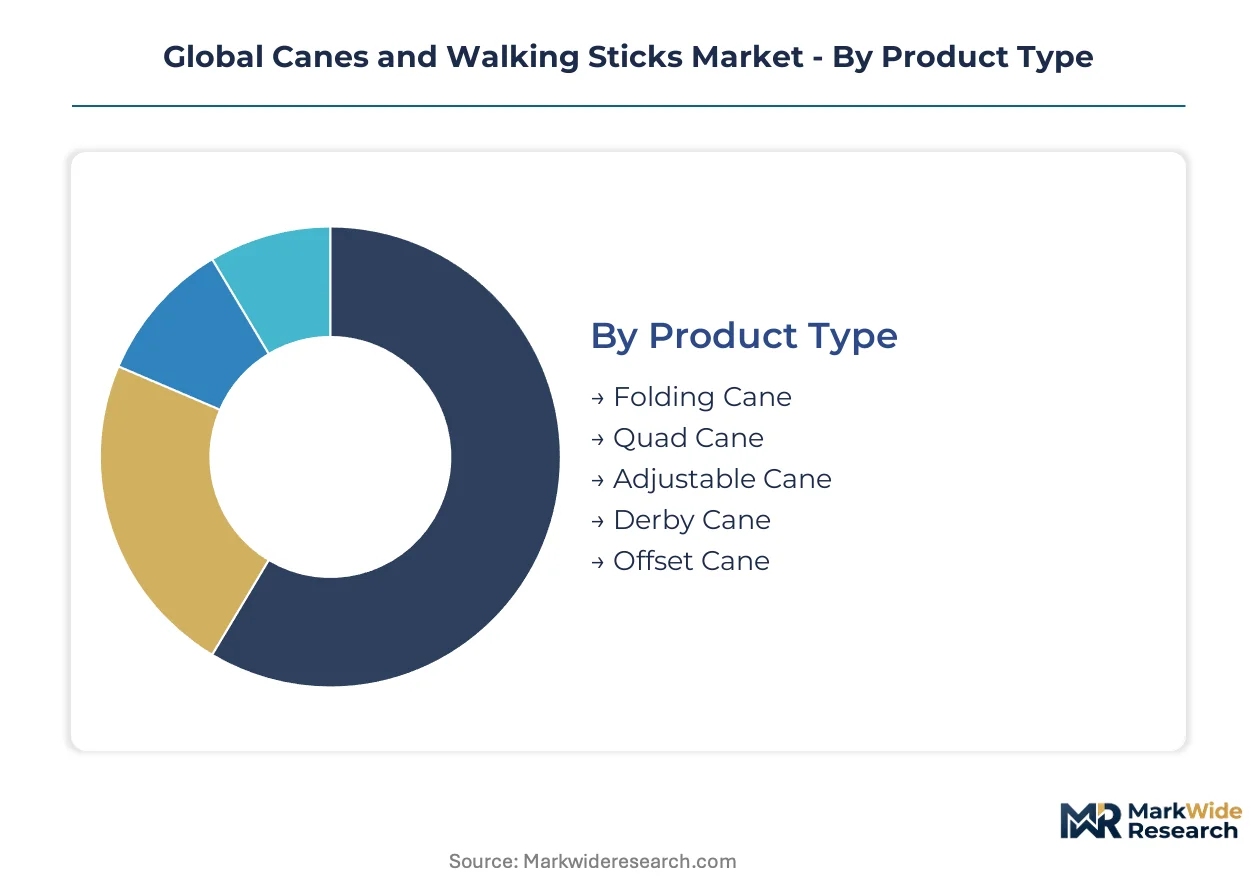
Segmentation in canes and walking sticks reveals how material science, clinical protocols, and retail channel evolution create distinct value pools. Manufacturers must align product architectures with reimbursement pathways, durability certifications, and patient mobility profiles to capture margin across divergent buyer segments.
Product Type:
Customization potential spans fixed-form ceremonial designs through multi-joint adjustable systems, with portability requirements and clinical use cases determining standardization trade-offs.
- Folding Cane:Multi-segment shaft designs with internal elastic cords or push-button locking mechanisms enable collapse to 12-15 inch lengths. Demand concentrates among Japanese elderly patients qualifying for METI-subsidized home-care equipment, driven by travel portability mandates in urban transit-dependent populations.
- Adjustable Cane:Telescoping aluminum or carbon fiber shafts with push-pin height selectors accommodate user populations from 4'6" to 6'4". German rehabilitation centers now mandate ISO 11199-certified adjustable models for post-operative protocols, creating procurement standardization around load-bearing verification.
- Quad Cane:Four-point ferrule bases with 6-8 inch stance widths provide mediolateral stability for hemiplegic patients. Compact treatment: Bariatric-rated variants with reinforced aluminum shafts address 136+ kilogram user requirements in US inpatient rehabilitation settings.
- Derby Cane:Curved grip handles with integrated wrist loops distribute palm pressure across broader contact surfaces. Compact treatment: Heritage wood variants persist in UK ceremonial applications despite declining clinical relevance.
- Offset Cane:Angled shaft-to-grip geometry centers body weight over the shaft axis for wrist-neutral positioning. Compact treatment: Ergonomic specialists in Japanese geriatric facilities favor these for osteoarthritis patients requiring reduced ulnar deviation.
Leading the category by volume: Adjustable Cane. Growing fastest: Folding Cane.
Material:
Cost tier stratification separates commodity aluminum forging from aerospace-grade carbon fiber composites, with margin compression and supply concentration reshaping sourcing strategies.
- Aluminum:6061-T6 or 7005-series alloys deliver 113-136 kilogram load ratings at 300-400 gram finished weights. Demand concentrates in North American pharmacy retail channels where Carex Health Brands and Drive DeVililbiss Healthcare compete on unit economics, constrained by European natural gas price volatility affecting smelting costs.
- Carbon Fiber:Unidirectional prepreg layups with epoxy resin matrices achieve sub-250 gram weights with superior vibration damping. Japanese and Chinese precursor supply concentration exposes manufacturers to export licensing friction, though manufacturing advances continue opening premium travel-portable segments.
- Wood:Hardwood shafts from ash, oak, or exotic imports serve ceremonial and heritage product lines. Compact treatment: UK and Italian craftsmen maintain artisanal production for non-reimbursable consumer segments despite clinical obsolescence.
- Steel:Chromoly or stainless constructions provide maximum durability for bariatric applications. Compact treatment: Institutional procurement in Indian government hospitals favors steel for cost-minimization over weight considerations.
- Plastic:Glass-filled nylon or polycarbonate components appear in injection-molded grips and ferrule housings. Compact treatment: REACH substance restrictions on legacy polymer additives are forcing EU-bound reformulation of rubber-ferrule compounds.
Dominating volume: Aluminum. Steepest expansion trajectory: Carbon Fiber.
End User:
Application specificity ranges from acute rehabilitation protocols through preventive wellness positioning, with reimbursement eligibility determining addressable market boundaries.
- Elderly Individuals:Geriatric users aged 65+ represent the primary volume segment, with fall-risk assessment protocols in Japanese community care systems driving prescribed mobility aid adoption. METI reimbursement codes directly subsidize certified adjustable models for home-bound patients, expanding institutional procurement channels.
- Rehabilitation Patients:Post-operative orthopedic and neurological recovery protocols specify ISO 11199 durability ratings and height-adjustable configurations. German rehabilitation centers now mandate certified canes for discharge planning, creating procurement filters that favor standardized specifications over consumer preference.
- Physically Challenged:Permanent mobility impairment populations require customized anthropometric fitting and specialized grip geometries. Compact treatment: Biomechanical engineering expertise for anthropometric development concentrates in German and Japanese research clusters.
- Outdoor Enthusiasts:Trekking and Nordic walking applications demand collapsible carbon fiber constructions with carbide-tipped ferrules. Compact treatment: This segment bypasses medical reimbursement channels entirely, competing in sporting goods retail against dedicated hiking pole manufacturers.
Largest addressable population: Elderly Individuals. Fastest clinical protocol integration: Rehabilitation Patients.
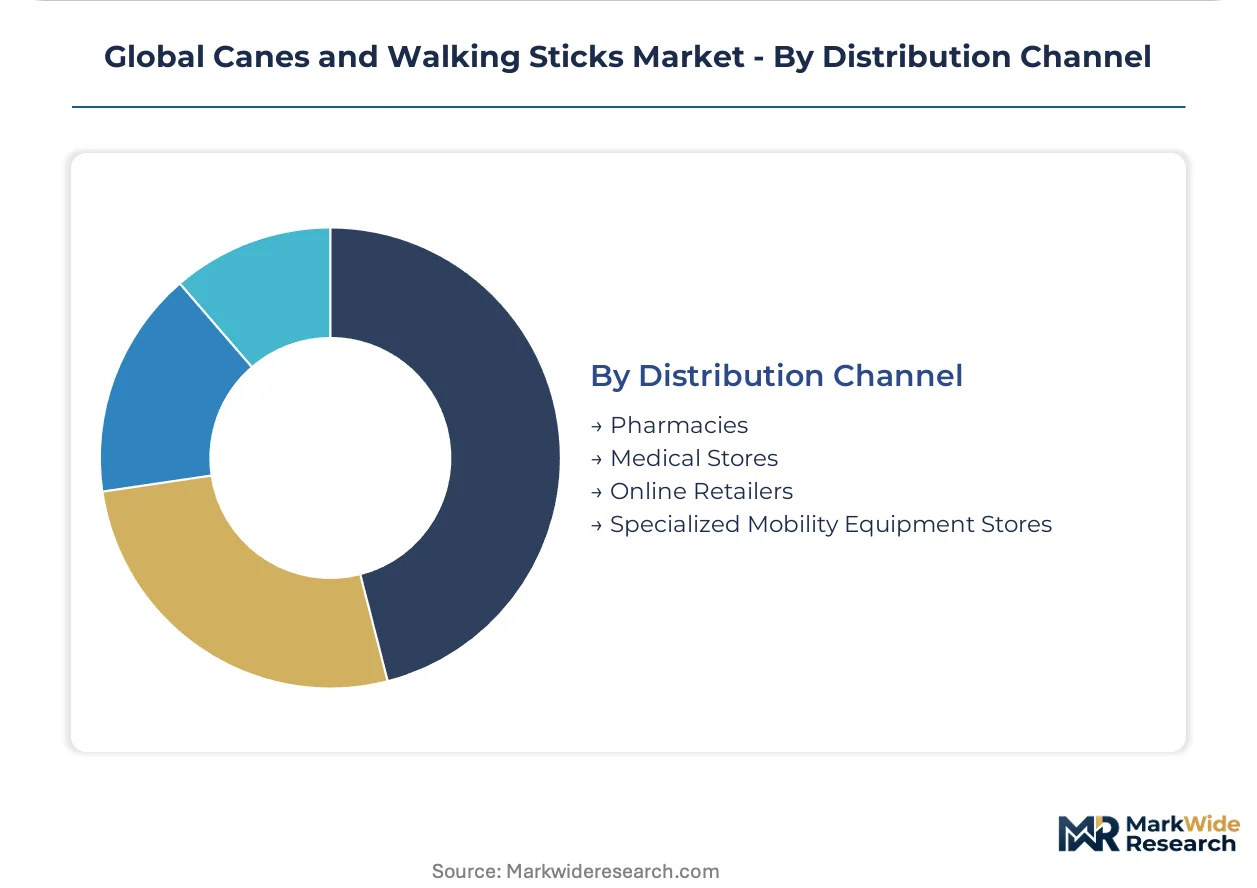
Distribution Channel:
Channel control separates pharmacy-driven volume from direct-to-patient disintermediation, with group purchasing organization consolidation reshaping vendor selection criteria.
- Pharmacies:Chain and independent pharmacy networks provide immediate accessibility for acute need situations. Carex Health Brands leverages broad pharmacy distribution to sustain volume leadership in North American retail, though margin structures compress against private-label competition.
- Medical Stores:Durable medical equipment suppliers serve Medicare and Medicaid reimbursement pathways with certified inventory pools. US hospital procurement departments are consolidating mobility aid purchasing through group purchasing organizations that bundle canes with orthopedic braces and wound care supplies.
- Online Retailers:Direct-to-patient platforms bypass traditional pharmacy hierarchies, enabled by remote gait assessment protocols. Compact treatment: Telehealth integration creates channels for modular component systems with replacement-part economics.
- Specialized Mobility Equipment Stores:Orthotic and prosthetic clinics provide professional fitting services for complex anthropometric requirements. Compact treatment: These outlets command premium positioning through clinical credibility rather than price competition.
Highest transaction volume: Pharmacies. Fastest channel shift: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Performance-Linked Incentive scheme for medical device manufacturing has concentrated export-oriented aluminum forging capacity in Gujarat and Maharashtra special economic zones, reshaping regional supply patterns for mobility aid components.
United States
Medicare Part B durable medical equipment reimbursement codes drive institutional procurement volume through hospital group purchasing organizations. FDA Class I device clearance pathways govern market access for rehabilitation-positioned cane systems. Manufacturing concentrates in Ohio and Indiana industrial corridors where aluminum component suppliers serve contract assembly networks.
Germany
Rehabilitation centers in Bavaria and North Rhine-Westphalia mandate ISO 11199-certified adjustable canes for post-operative discharge protocols. EU Medical Device Regulation clinical evaluation requirements filter functional positioning claims. The Black Forest region hosts specialized grip ergonomics research clusters developing anthropometric fitting systems.
Japan
METI reimbursement codes subsidize prescribed mobility aids for home-bound elderly patients in Tokyo and Osaka metropolitan areas. Carbon fiber precursor supply concentrates in Nagoya industrial zones, enabling sub-250-gram premium folding models. Community care systems in Kanagawa Prefecture drive prescribed adoption through fall-risk assessment protocols.
China
Carbon fiber forging networks in Jiangsu and Zhejiang provinces supply shaft components to global assembly operations. Export licensing volatility affects precursor availability for premium manufacturers. Shenzhen medical device industrial parks host contract manufacturers serving North American pharmacy retail channels.
United Kingdom
Heritage wood cane craftsmanship persists in Yorkshire and Cotswolds artisanal workshops despite clinical obsolescence. NHS procurement standardization favors aluminum adjustable models for cost containment. REACH substance restrictions on rubber ferrule additives force reformulation of EU-bound product lines through British distributors.
Global Canes and Walking Sticks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning bands. The vendor base separates into three strategic archetypes: diversified health systems suppliers with broad durable medical equipment portfolios, vertically integrated metal fabricators controlling upstream forging operations, and modular component specialists assembling grip-shaft-tip systems from distributed suppliers. Competitive moves concentrate on GPO contract consolidation and carbon fiber supply security through Asian precursor partnerships.
Among North American health systems suppliers, Cardinal Health and Medline Industries occupy positions within hospital procurement hierarchies, while Drive DeVilbiss Healthcare exemplifies the vertically integrated fabricator archetype with in-house aluminum forging capabilities. Carex Health Brands anchors pharmacy retail channel presence through broad distribution networks. These three entities represent distinct competitive positioning vectors: procurement scale, manufacturing control, and retail accessibility respectively.
| Leading Market Players |
|---|
| Cardinal Health |
| Carex Health Brands |
| Invacare Corporation |
| Royal Canes |
| NOVA Medical Products |
| Drive DeVilbiss Healthcare |
| Sunrise Medical |
| Hugo Mobility |
| Medline Industries |
| Others |
Supply & Pricing Matrix
REACH substance restrictions on rubber ferrule polymerizers now gate qualified supply access for EU-bound manufacturers while simultaneously segmenting premium-tier pricing eligibility around compliant inventory pools. This regulatory filter compresses formulation R&D cycles and forces distributors to maintain parallel certified and non-certified stock, directly shaping how pricing power concentrates among REACH-compliant suppliers.
Pricing Analysis
Margin tightening in economy aluminum segments reflects European natural gas price volatility driving energy-intensive smelting cost fluctuations. Three-tier pricing structure across premium carbon fiber, standard aluminum, and economy steel levels separates ISO 11199-certified rehabilitation models from pharmacy retail commodity units. Pricing pressure stems from Chinese precursor export licensing friction constraining premium carbon fiber availability. Hospital group purchasing organizations exhibit lowest price sensitivity due to bundled contract economics, while independent pharmacy channels face highest sensitivity against private-label competition.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in this sector due to product disposability norms, though modular grip-shaft-tip architectures are creating nascent replacement-part reverse logistics channels. Manufacturing concentrates in China for carbon fiber forging, India for aluminum component production under PLI scheme incentives, and Germany for precision grip ergonomics. Supply chains draw from unidirectional carbon fiber prepreg, 6061-T6 aluminum billets, and REACH-compliant silicone ferrule compounds. Single-source vulnerability concentrates in Japanese and Chinese precursor supply for premium shafts. Distribution runs through hospital group purchasing organizations, pharmacy retail networks, and direct-to-patient telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive control over carbon fiber precursor supply to defend margin structures against Asian export licensing volatility.
For Market Incumbents: Deploy ISO 11199 certification investment to lock in German rehabilitation center procurement mandates before competitor qualification completes. Consolidate position through backward integration into aluminum forging operations in India PLI zones to offset European energy cost exposure. Carbon fiber supply concentration in Nagoya and Jiangsu poses substitution threat from emerging modular component specialists.
For New Entrants and Emerging Players: Launch via direct-to-patient telehealth channels bypassing entrenched pharmacy and hospital procurement hierarchies. White-space concentrates in modular component systems with replacement-part economics targeting Japanese METI-reimbursed elderly populations. Nordic walking and trekking applications outside medical reimbursement channels offer penetrable sporting goods retail entry.
For Investors and Strategic Acquirers: METI reimbursement code expansions for home-care equipment are the leading indicator that institutional procurement volumes will shift toward certified adjustable models over commodity alternatives. Five-to-ten-year viability favors vertically integrated fabricators with captive forging or carbon fiber supply. Monitor REACH substance list updates for rubber ferrule polymerizers as compliance differentiation signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Precursor Supply Agreement | Secures Nagoya or Jiangsu forging capacity against export licensing volatility for premium folding models. |
| ISO 11199 Certification Investment | Unlocks German rehabilitation center procurement mandates and METI reimbursement eligibility in Japan. |
| India PLI Scheme Manufacturing Alignment | Positions export-oriented aluminum forging in Gujarat SEZs to capture cost advantage over European smelting. |
| Telehealth Gait Assessment Platform | Creates direct-to-patient channel bypassing pharmacy retail margin compression and GPO bundling. |
| Modular Component System Launch | Shifts buyer calculus from upfront cost to lifetime replacement-part economics in Japanese geriatric care. |
Research Methodology
Trade databases, regulatory filing repositories, and hospital procurement contract records formed the secondary backbone for this analysis. Primary interviews with rehabilitation clinicians, biomedical engineers, GPO contracts managers, and carbon fiber forging operations heads validated demand assumptions and supply constraints. Bottom-up triangulation across product-level volume estimates and top-down reconciliation against national reimbursement expenditure data anchored forecast integrity.
Historical trendline analysis across material cost indices, certification adoption curves, and channel shift patterns informed projection modeling. Segmentation dimensions span product type, material grade, end-user mobility profile, and distribution channel structure. CAGRs derive from fitted growth curves adjusted for regulatory inflection points and reimbursement policy changes. Carbon fiber weight threshold advances and METI code expansion schedules served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for carbon fiber composite modularization would alter the outlook if forging cost curves flatten faster than anticipated. Forecasts reflect assumptions around REACH compliance timelines and precursor supply licensing stability. Practitioners should monitor ECHA candidate list updates, METI reimbursement code revisions, and Indian PLI scheme capacity commissioning for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Global Sex Toys Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Global Hairbrush Market
Personal Grooming Products
Organic and Natural Tampons Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
North America Hair Styling Tools Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
Insoles Market