
 Tattoo Accessories Market | 2026-2036
Tattoo Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Tattoo Accessories Market Analysis
China is reshaping manufacturing scale for coil and rotary machine components, with Guangdong province hosting the densest supplier cluster outside traditional European centers. FK Irons leverages vertical integration into precision-machined grips to sustain margin capture in premium machine sales. Cheyenne Professional Tattoo Equipment anchors German engineering credibility through cartridge needle standardization. Dragonhawk competes on cost-optimized rotary systems for emerging studio formations across Southeast Asia.
Tattoo accessories comprise consumables and durable equipment used to deposit pigment into dermal layers, with needle configurations ranging from 0.25mm to 0.35mm diameter and ink formulations requiring ASTM F136-compliant carrier fluids for biocompatibility. The product type dimension shows machine and power supply categories capturing the highest margin pools as studios upgrade to wireless, battery-integrated systems, while needle cartridges generate recurring revenue density through single-use protocols. Application segmentation reveals cosmetic and medical tattooing outpacing traditional body art growth as paramedical reconstruction and permanent makeup expand the addressable client base beyond conventional demographics.
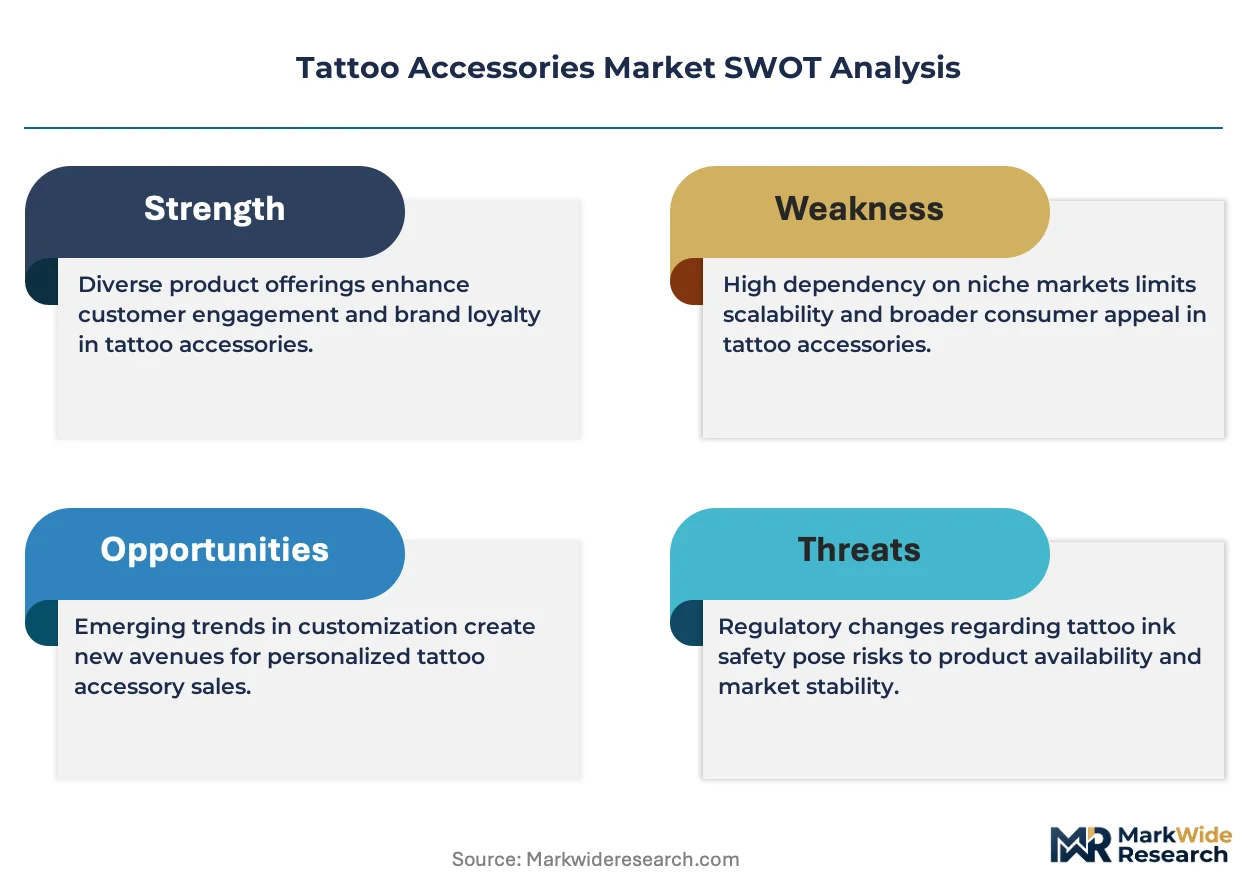
FDA pigment oversight and REACH chemical restrictions in Europe constrain ink formulation portfolios, compelling suppliers to maintain dual-registration documentation for transatlantic distribution. Germany's MPK regulation and Spain's regional health authority licensing frameworks mandate sterilization equipment pairing, directly lifting power supply and autoclave accessory attachment rates. Stakeholders must monitor pending FDA color additive petitions and EU ECHA microplastic restrictions to anticipate reformulation timelines and inventory transition costs.
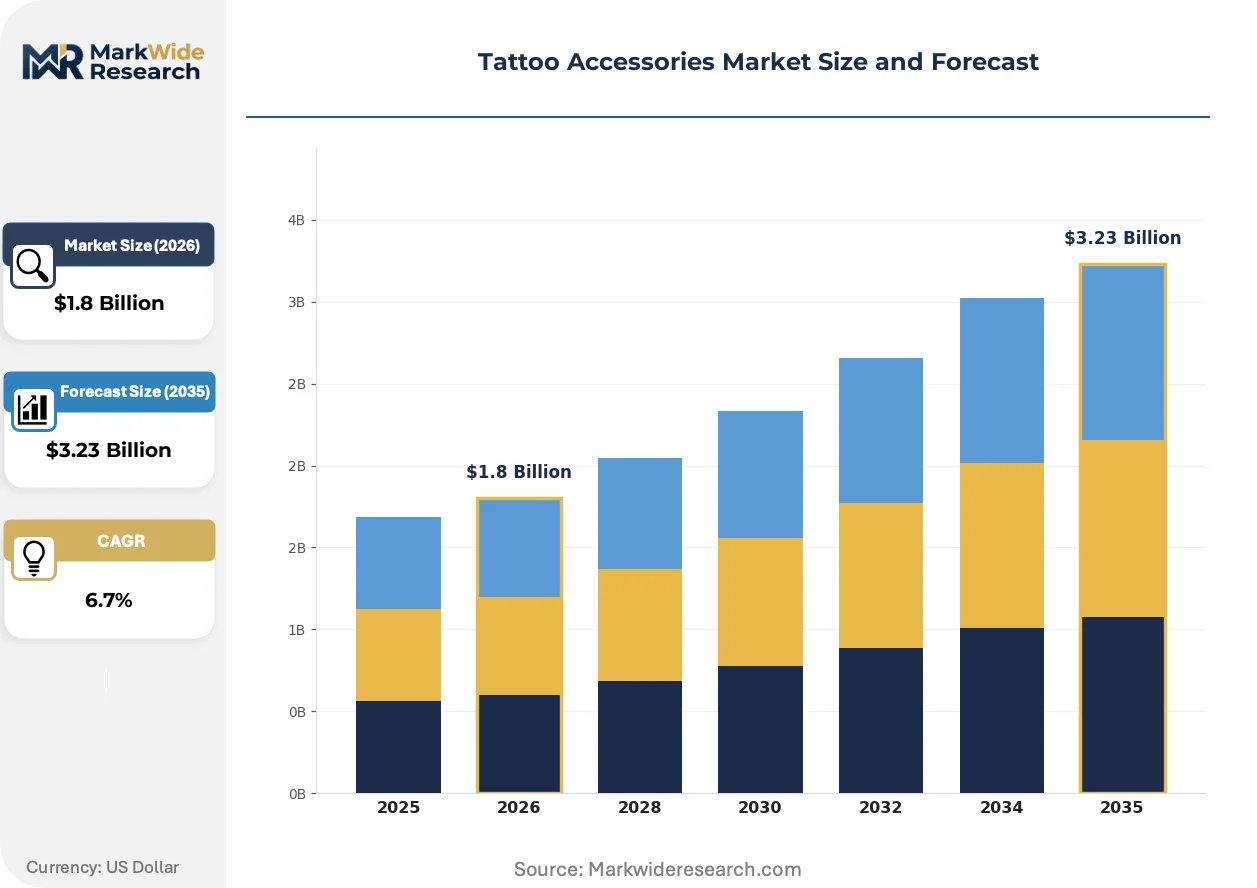
Market Dynamics
Professional tattoo studios are accelerating equipment replacement cycles as hygiene protocols tighten across jurisdictions, forcing suppliers to recertify power supplies and needle cartridges under evolving medical device classifications.
Growth Catalysts
- EU Medical Device Regulation:Reclassification of permanent makeup devices as Class IIa medical equipment is compelling studios to upgrade sterilization equipment and cartridge systems, expanding the addressable base for compliant suppliers.
- Paramedical reconstruction demand:Oncology and trauma recovery clinics are integrating areola and scalp micropigmentation services, creating institutional procurement channels distinct from traditional studio retail.
- Guangdong manufacturing cluster:Precision machining capabilities for coil assemblies and rotary motors are concentrating in this province, reducing component lead times for global machine assemblers.
Market Restraints
- Pigment input volatility:Titanium dioxide and carbon black feedstocks face REACH authorization bottlenecks and supply rationing, compressing ink formulation margins and forcing dual-sourcing strategies.
- German supply concentration:Cheyenne and FK Irons anchor premium cartridge and machine production in Baden-Württemberg and Bavaria, creating geographic vulnerability for distributors dependent on single-origin precision components.
- Biocompatibility testing timelines:ASTM F136 carrier fluid validation requires 18-24 month certification windows, delaying new ink line introductions and trapping inventory in reformulation cycles.
Strategic Opportunities
- Brazilian regulatory opening:ANVISA is harmonizing tattoo equipment standards with ISO 13485, reducing import friction for European and North American suppliers in a historically informal market.
- Wireless power convergence:Battery-integrated machine systems are merging with Bluetooth voltage monitoring, enabling subscription-based firmware updates and recurring revenue attachment.
- Permanent makeup channel expansion:Medical spas and dermatology clinics are adopting cosmetic tattooing services, bypassing traditional distributor networks through direct GPO contracting.
Industry Challenges
- Apprenticeship pipeline gaps:Germany's MPK-mandated training hours and Spain's regional health authority licensing create multi-year certification backlogs, constraining qualified technician supply and studio expansion capacity.
- Dual-registration documentation burden:Suppliers must maintain parallel FDA color additive petitions and ECHA microplastic restriction compliance files, fragmenting product portfolios and inflating regulatory affairs headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tattoo Accessories Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ink, Needle, Machine, Power Supply Application: Body Art, Medical, Cosmetic, Professional Use End User: Tattoo Artists, Studios, Enthusiasts, Collectors Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | FK Irons, Cheyenne Professional Tattoo Equipment, Dragonhawk, EZ Tattoo Supply, Sabre Tattoo Supplies, Inkjecta International, Bishop Tattoo Supply, Eikon Device, Technical Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tattoo Accessories Market Emerging Trajectories
Wireless battery integration and cartridge standardization are compressing equipment replacement cycles while regulatory reclassification is redrawing competitive boundaries between medical device and cosmetic suppliers.
Rotary tattoo machines is migrating from studio-grade equipment to entry-level apprentice kits as Chinese manufacturers in Guangdong province scale precision-machined motor production. Budget-conscious studio formations across Southeast Asia are adopting these systems at three-year replacement intervals versus seven-year cycles for coil machines. This technology diffusion is compressing average selling prices in the mid-tier segment while expanding unit volumes.
REACH chemical restrictions and pending EU ECHA microplastic regulations are forcing ink suppliers to eliminate synthetic glitter pigments and reformulate carrier fluids with bio-based alternatives. The industrial consequence is a bifurcation between legacy portfolios serving non-EU markets and reformulated lines carrying premium positioning for European distribution. Germany's MPK enforcement and France's ANSM oversight are most affected, with studios pre-ordering compliant inventory ahead of 2025 transition deadlines.
Studio procurement patterns are consolidating around single-source cartridge contracts as needle standardization reduces switching costs between machine brands. Distributors are responding with private-label cartridge lines that interoperate across Cheyenne, FK Irons, and Dragonhawk grip specifications. This behavior is most visible in Germany and the Netherlands, where purchasing cooperatives negotiate volume commitments in exchange for technical training and sterilization equipment bundling.
Tattoo Accessories Market Segmentation
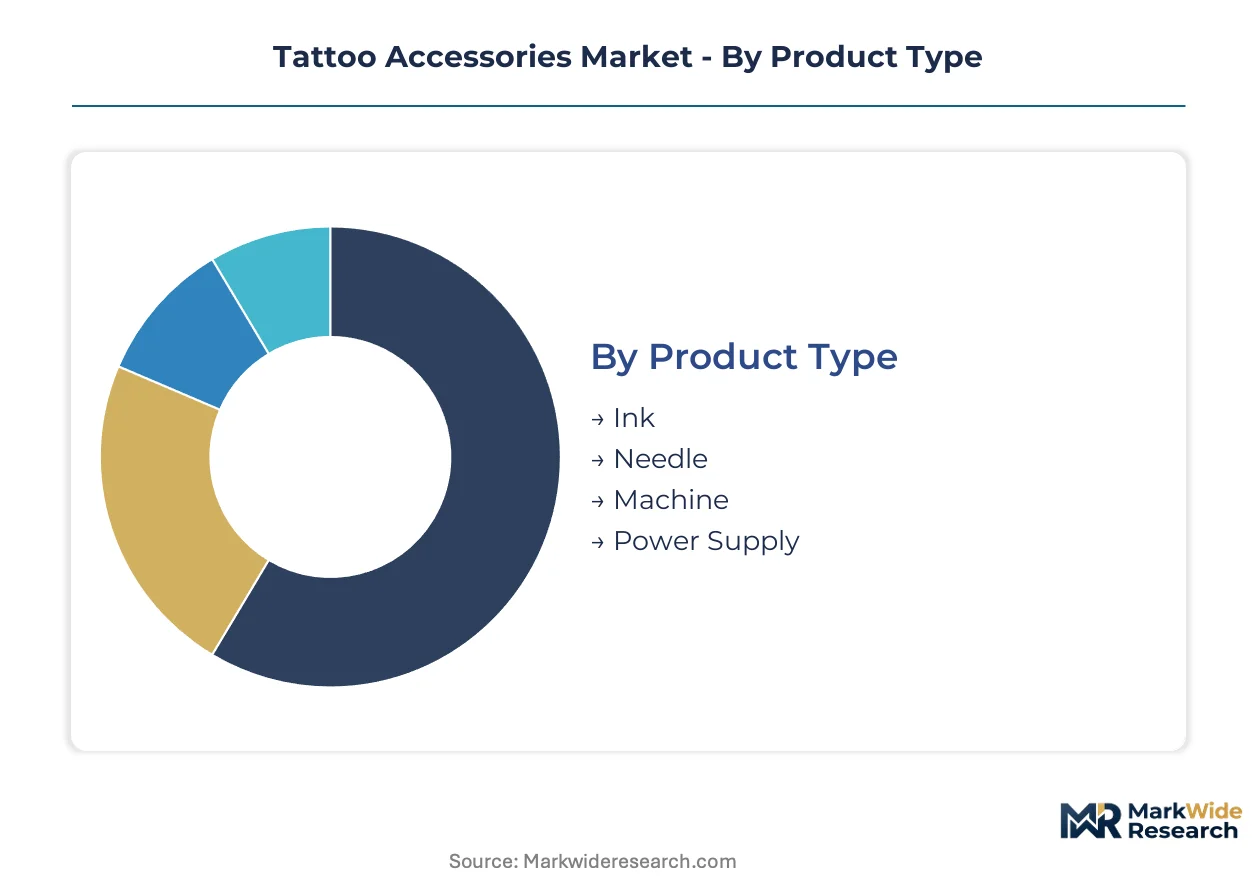
Segmentation in tattoo accessories reveals how regulatory pressure, hygiene protocols, and professionalization reshape purchasing behavior across equipment categories. Each dimension exposes distinct margin structures and compliance burdens that suppliers must navigate.
Product Type:
The use-case spectrum spans single-use consumables demanding sterile logistics through capital equipment requiring technical service attachment.
- Machine:Rotary and coil assemblies deposit pigment through electromagnetic or motor-driven needle oscillation. Wireless battery-integrated systems are capturing premium positioning in Germany and the Netherlands as studios replace legacy power-supply-dependent units. Studios in Baden-Württemberg and Bavaria drive specification standards through apprenticeship-linked procurement.
- Ink:Pigment suspensions in ASTM F136-compliant carrier fluids require dual-registration documentation for transatlantic distribution. REACH chemical restrictions and pending ECHA microplastic regulations are forcing reformulation cycles that bifurcate portfolios between legacy and European-compliant lines.
- Needle:Cartridge configurations range from 0.25mm to 0.35mm diameter with standardized grip interfaces.
- Power Supply:Voltage regulation units and wireless battery systems complete machine ecosystems.
The dominant share belongs to Machine, while Ink is closing the gap fastest through recurring consumable revenue density.
Application:
Cost tier differentiation separates institutional procurement from retail studio purchasing with divergent certification requirements.
- Cosmetic:Permanent makeup and paramedical micropigmentation services are expanding the addressable client base beyond traditional body art demographics. Oncology and trauma recovery clinics in Germany and France are integrating areola and scalp procedures, creating institutional procurement channels with sterilization equipment bundling requirements.
- Medical:Reconstructive tattooing for burn scars and surgical revision operates under stricter device classifications. The EU Medical Device Regulation reclassification of permanent makeup devices as Class IIa equipment is compelling upgrade cycles in regulated jurisdictions.
- Body Art:Traditional decorative tattooing remains volume-dominant across apprentice and professional tiers.
- Professional Use:Studio-grade equipment and consumables carry certification premiums over enthusiast-grade alternatives.
Cosmetic holds the largest revenue concentration, with Medical expanding most quickly through clinic channel development.
End User:
Customer type determines specification intensity, with licensed professionals demanding traceable sterilization documentation that hobbyists bypass.
- Studios:Professional tattoo studios represent the fastest-expanding buyer segment as hygiene protocols tighten across jurisdictions. Germany's MPK regulation and Spain's regional health authority licensing frameworks mandate sterilization equipment pairing, directly lifting power supply and autoclave accessory attachment rates.
- Tattoo Artists:Individual practitioners purchase through distributor networks or direct manufacturer relationships based on cartridge interoperability.
- Enthusiasts:Apprentice kits and entry-level rotary systems from Guangdong manufacturers serve training-phase demand.
- Collectors:Limited-edition machine builds and heritage grip designs command premium positioning in secondary markets.
Studios command the dominant procurement volume, while Cosmetic clinics are gaining share fastest through medical spa channel expansion.
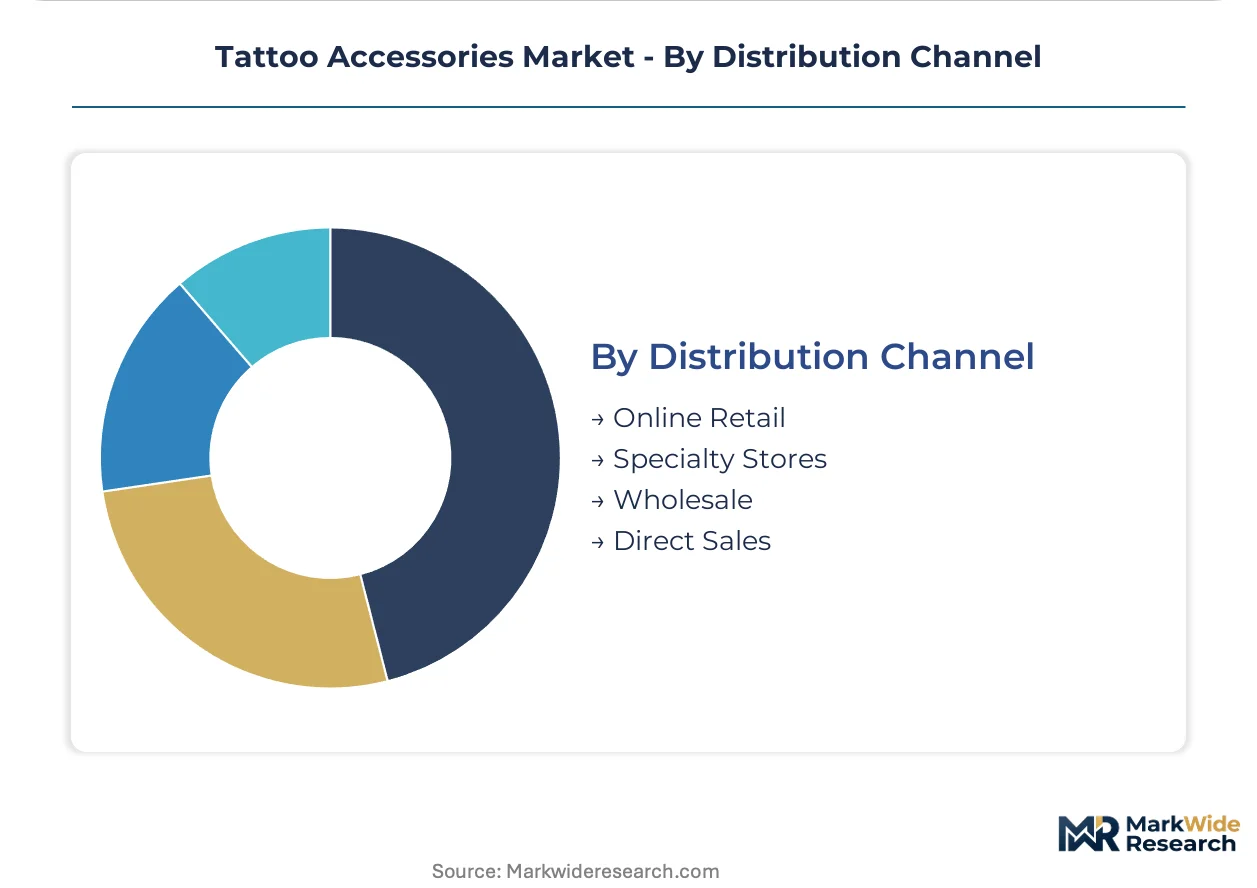
Distribution Channel:
Supply concentration in manufacturing clusters shapes channel economics, with Guangdong component sourcing enabling direct-to-studio disintermediation.
- Wholesale:Distributor networks aggregate volume commitments from purchasing cooperatives in exchange for technical training and sterilization equipment bundling. German and Dutch cooperatives negotiate cartridge standardization agreements that interoperate across machine brands.
- Online Retail:E-commerce platforms serve enthusiast and apprentice segments with cost-optimized rotary systems from Southeast Asian manufacturers.
- Specialty Stores:Physical showrooms support machine testing and grip specification consultation for professional buyers.
- Direct Sales:Manufacturers bypass distributors for institutional contracts with medical spas and dermatology clinics adopting GPO procurement.
Wholesale retains the largest transaction volume, with Direct Sales climbing the fastest through medical channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's MPK regulation anchors European compliance standards for tattoo equipment, while manufacturing gravity pulls toward Guangdong province and demand expansion concentrates in Brazil's regulatory opening. The report maps five countries where supply chain configuration, regulatory frameworks, and end-use professionalization intersect most intensively.
Germany
Baden-Württemberg and Bavaria host the densest concentration of precision-machined grip and cartridge needle production. The MPK regulation mandates sterilization equipment pairing and apprenticeship-linked procurement, directly lifting power supply and autoclave attachment rates. Cheyenne Professional Tattoo Equipment anchors engineering credibility through cartridge standardization from its Bavarian base.
United States
FDA pigment oversight and pending color additive petitions constrain ink formulation portfolios for transatlantic suppliers. Wireless battery-integrated machine systems capture premium positioning as studios replace legacy power-supply-dependent units. The regulatory timeline forces dual-registration documentation that fragments product portfolios.
China
Guangdong province concentrates precision machining capabilities for coil assemblies and rotary motors outside traditional European centers. Cost-optimized rotary systems from this cluster serve emerging studio formations across Southeast Asia at compressed replacement intervals. Manufacturing scale is displacing legacy supply relationships for entry-level and apprentice-tier equipment.
Brazil
ANVISA harmonization with ISO 13485 standards reduces import friction for European and North American suppliers in a historically informal market. São Paulo and Rio de Janeiro drive institutional procurement channel development for paramedical reconstruction services. The regulatory opening creates first-mover advantage for compliant sterilization equipment and cartridge system vendors.
France
ANSM oversight enforces REACH chemical restrictions and pending ECHA microplastic regulations on ink formulations. Studios in Île-de-France and Provence-Alpes-Côte d'Azur pre-order compliant inventory ahead of transition deadlines. Permanent makeup channel expansion through medical spas and dermatology clinics bypasses traditional distributor networks.
Tattoo Accessories Market Vendor Landscape
Capability concentration sits with German precision-engineering specialists; scale advantage sits with Guangdong manufacturing clusters. The market structures around three tiers: premium European manufacturers commanding certification premiums, mid-tier interoperable suppliers capturing cooperative purchasing volumes, and cost-optimized Asian fabricators saturating apprentice and enthusiast segments. Dominant competitive moves include backward integration into precision-machined components and cartridge standardization alliances that reduce switching costs between machine brands.
Within the premium-engineering tier, FK Irons and Cheyenne Professional Tattoo Equipment exemplify geographic anchoring in German industrial regions, while Dragonhawk occupies a position at the scale-driven end of rotary system production. FK Irons represents backward integration strategy through captive supply of precision-machined grips. Cheyenne Professional Tattoo Equipment GmbH exemplifies standardization-driven market architecture. Dragonhawk sits within the Guangdong manufacturing cluster that is compressing mid-tier pricing through three-year replacement cycle penetration.
| Leading Market Players |
|---|
| FK Irons |
| Cheyenne Professional Tattoo Equipment |
| Dragonhawk |
| EZ Tattoo Supply |
| Sabre Tattoo Supplies |
| Inkjecta International |
| Bishop Tattoo Supply |
| Eikon Device |
| Technical Worldwide |
| Others |
Supply Flow & Price Mechanics
REACH authorization bottlenecks for titanium dioxide and carbon black feedstocks determine both the spread between European-compliant and legacy ink lines and the geographic clustering of formulation capacity. This single-source chemical dependency forces dual-sourcing strategies that inflate working capital requirements while compressing margins across the mid-tier cartridge segment.
Pricing Analysis
German studios pay certification premiums of 40-60% over Southeast Asian pricing for identical machine specifications. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked medical device classifications from enthusiast-grade imports. Pricing pressure stems from Guangdong manufacturers compressing rotary system costs through scaled motor production. Apprentice-tier buyers in emerging markets exhibit highest price sensitivity, while German purchasing cooperatives prioritize sterilization documentation over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for machine assemblers. Component sourcing concentrates in Guangdong province for precision-machined motors, Baden-Württemberg for cartridge needle assemblies, and Bavaria for sterilization equipment. Raw material dependencies rest on titanium dioxide pigments, ASTM F136-compliant carrier fluids, and surgical-grade stainless steel. Distribution runs through purchasing cooperatives in Germany and the Netherlands that negotiate volume commitments against technical training bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as paramedical reconstruction services penetrate oncology and trauma recovery clinics beyond traditional studio demographics.
For Market Incumbents: Build certification moats through preemptive EU MDR Class IIa registration for permanent makeup devices before 2025 enforcement deadlines. Captive supply of precision-machined grips defends margin position against Guangdong cost compression. Invest in sterilization equipment bundling to lock purchasing cooperative contracts in Germany and the Netherlands. For New Entrants and Emerging Players: Build out white-space presence in Brazil's ANVISA-harmonized market before European incumbents establish distributor relationships. São Paulo clinic channels offer lowest competitive density for paramedical reconstruction equipment. Pursue direct GPO contracting with medical spas in France bypassing traditional wholesale networks. For Investors and Strategic Acquirers: The market sits at a professionalization phase that favors precision-engineering specialists with captive component production. Five-to-ten year viability hinges on regulatory compliance capabilities rather than scale economics. Acquisition targets should demonstrate backward integration into cartridge needle manufacturing. Monitor FDA color additive petition timelines as inflection indicator for ink formulation portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification | Unlocks institutional procurement channels in Germany and France for permanent makeup devices. |
| Cartridge Standardization Alliance | Reduces switching costs between Cheyenne, FK Irons, and Dragonhawk grip specifications. |
| Wireless Battery Integration | Enables subscription firmware revenue attachment through Bluetooth voltage monitoring systems. |
| Guangdong Manufacturing Scale-Up | Compresses three-year replacement cycles for entry-level rotary systems in Southeast Asia. |
| Direct GPO Contracting | Bypasses distributor networks for medical spa and dermatology clinic procurement in France. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA color additive petitions, ECHA microplastic restriction filings, and EU MDR device registration databases. Interviews with tattoo studio owners, biomedical engineers at paramedical clinics, sterilization equipment distributors, and regulatory affairs specialists at ink manufacturers informed demand-side assumptions. Secondary sources include REACH authorization status reports, German MPK apprenticeship records, and ANVISA harmonization documentation. Bottom-up equipment shipment data triangulates against top-down studio licensing counts.
Forecast inputs incorporate machine replacement cycle compression, cartridge single-use protocol adoption, and regulatory reclassification timelines. Segmentation dimensions span product type, application, end user, and distribution channel with geographic regulatory cluster overlays. CAGRs derive from installed base growth coupled with average selling price trajectories across premium and economy tiers. Industry-specific inputs include ASTM F136 certification timelines and REACH chemical restriction phase-in schedules.
Sensitivities concentrate around FDA pigment oversight decisions and ECHA microplastic regulation enforcement dates that could accelerate inventory write-downs. Forecasts reflect assumptions about apprenticeship pipeline expansion in Germany and Spain. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Pre-Shave Products Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
Global Mobile Barber Shop Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Smart Electric Toothbrush Market
Personal Grooming Products
Global Hairbrush Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
Global Sex Toys Market
Personal Grooming Products
Cotton Pads Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
Disposable Shower Caps Market
Personal Grooming Products
Self-Tanning Products Market