
 United States Electric Toothbrush Market | 2026-2036
United States Electric Toothbrush Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Toothbrush Market Intelligence
Dental professional channel recommendations is restructuring how consumers select oral care appliances, shifting purchase authority from retail aisles toward clinical endorsement. Procter & Gamble Company leverages its Colgate partnership network to sustain pharmacy shelf dominance across major metropolitan markets. Koninklijke Philips N.V. anchors the premium sonic segment through extensive dental professional sampling programs. Church & Dwight Co., Inc. competes aggressively in value-tier retail placements with battery-operated alternatives.
An electric toothbrush is a motorized oral hygiene instrument employing oscillating, rotating, or sonic vibration mechanisms typically operating between 20,000 and 40,000 strokes per minute to disrupt dental plaque and stimulate gingival tissue. Sonic and oscillating product types capture the dominant revenue share as consumers demonstrate willingness to pay premium prices for clinically validated vibration technologies. The online retail distribution channel expands fastest, though pharmacies retain the highest margin pool through professional recommendation tie-ins and insurance-adjacent purchasing.
The FDA regulates electric toothbrushes as Class I or Class II medical devices depending on intended therapeutic claims, while ADA Seal of Acceptance requirements enforce rigorous clinical validation standards for market credibility. FTC advertising guidelines constrain unsubstantiated efficacy claims, particularly for emerging ultrasonic technologies targeting periodontal health applications. Stakeholders must monitor evolving dental insurance reimbursement policies for connected brush systems and the potential integration of oral health data into broader preventive care frameworks.
Market Dynamics
Dental professional endorsement networks are restructuring purchase authority away from retail shelf placement toward clinical recommendation channels, compressing traditional brand loyalty cycles and elevating ADA Seal validation as a gatekeeper credential.
Growth Catalysts
- ADA Seal of Acceptance:The program's clinical validation requirements create a trusted quality signal that accelerates consumer willingness to upgrade from manual brushing systems.
- Preventive care spending concentration:Affluent suburban households and urban coastal corridors allocate disproportionate oral health budgets toward powered hygiene instruments.
- Connected brush data integration:Bluetooth-enabled usage tracking aligns with dental insurance wellness incentive programs, expanding reimbursable preventive care categories.
Market Restraints
- Lithium-ion battery supply concentration:Dependence on East Asian cell manufacturers exposes production schedules to raw material allocation volatility and shipping lane disruptions.
- FDA Class II device pathway:Therapeutic claim submissions trigger extended 510(k) review timelines that delay product launches by 12-18 months versus cosmetic positioning routes.
- Manual brush substitution persistence:Price-sensitive consumer segments in rural and lower-income markets resist premium conversion despite clinical efficacy documentation.
Strategic Opportunities
- Underpenetrated Medicare Advantage integration:Oral health data from connected brushes offers payers measurable preventive outcomes, creating reimbursement pathway expansion in senior demographics.
- Sonic-ultrasonic technology convergence:Hybrid vibration platforms targeting periodontal applications open professional channel placement beyond retail consumer segments.
- Subscription direct-to-consumer replenishment:Automated brush head replacement programs capture recurring revenue streams while bypassing pharmacy margin compression.
Industry Challenges
- Firmware cybersecurity certification:Connected device HIPAA compliance requirements demand specialized engineering talent scarce among traditional appliance manufacturers.
- ISO 13485 quality management implementation:Medical device-grade manufacturing standards require capital-intensive cleanroom assembly retrofits for facilities historically optimized for consumer electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Toothbrush Market |
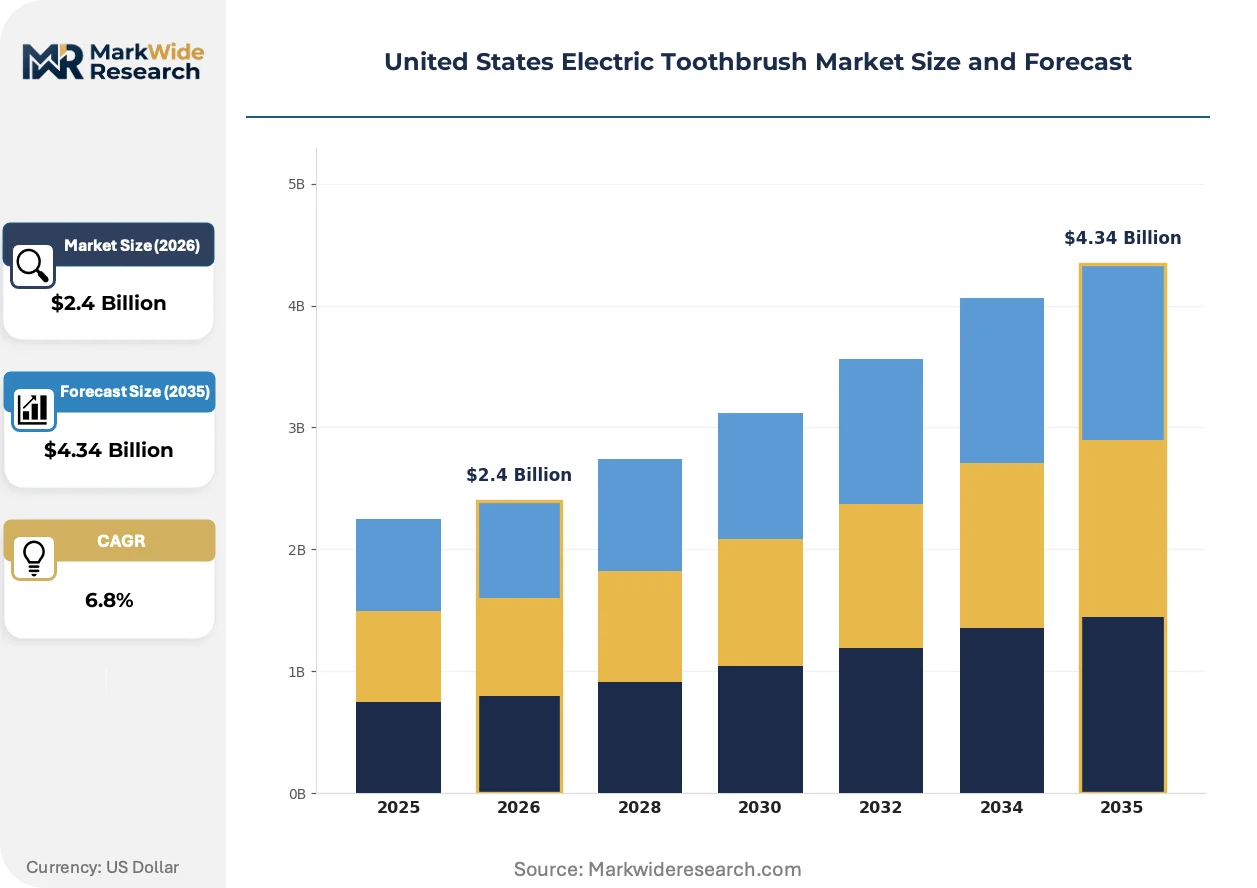
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary, Ultrasonic, Sonic, Oscillating Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores End User: Children, Adults, Seniors, Dental Professionals Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Church & Dwight Co., Inc., FOREO, Procter & Gamble Company, Quip Inc., Water Pik, Inc., Colgate-Palmolive Company, Panasonic Corporation, Shenzhen Risun Technology Co., Ltd., Koninklijke Philips N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Toothbrush Market Strategic Shifts & Innovations
Smart sensor integration and AI-driven brushing feedback are compressing the gap between consumer appliances and clinical-grade oral hygiene instruments, reshaping how manufacturers validate efficacy claims and distribute through professional channels.
Pressure mapping arrays embedded in brush heads now detect excessive force application and gingival contact patterns, transmitting real-time haptic feedback to users. Dental practices in California and New York are piloting these systems for patient home-care compliance monitoring. The technology is modularizing hardware platforms into upgradeable sensor-software bundles rather than fixed-feature appliances.
FDA guidance documents on software-as-a-medical-device are tightening validation requirements for algorithmic brushing coaching systems, particularly those claiming periodontal health outcomes. Manufacturers must now submit clinical evidence for AI recommendation engines separately from hardware clearances. Premium sonic product lines face the steepest compliance cost escalation as they pursue therapeutic positioning.
Younger consumers in metropolitan markets increasingly research electric toothbrush efficacy through dental professional social media channels before retail purchase, compressing the traditional awareness-to-decision cycle. Pharmacy chains are responding by co-locating oral care aisles with in-store telehealth consultation pods. This behavioral shift concentrates highest-velocity demand in urban corridors where professional endorsement access is immediate.
United States Electric Toothbrush Market Segmentation
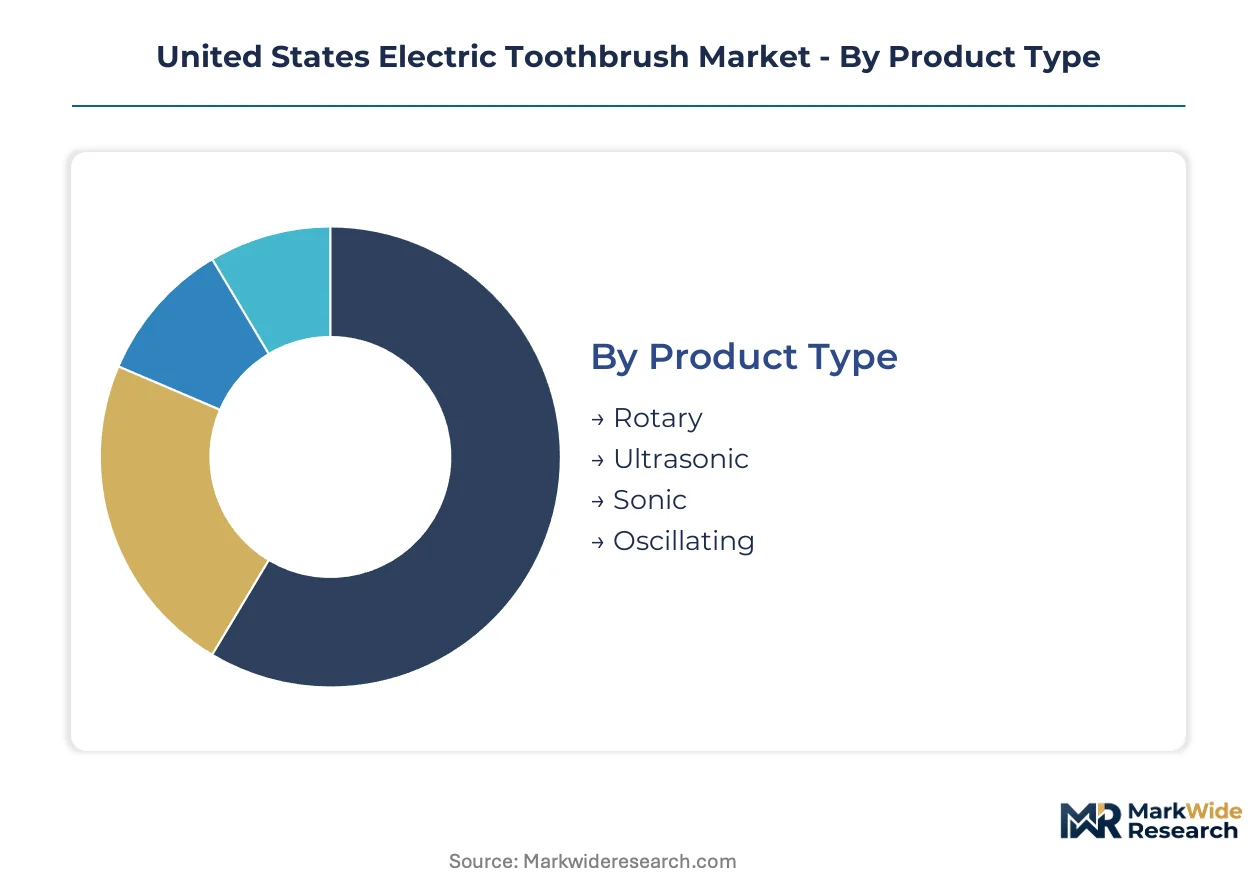
Electric toothbrush segmentation reveals how clinical validation, purchase channel authority, and demographic-specific design requirements fragment demand across distinct commercial battlegrounds. Manufacturers must align product architectures with the specific decision-making logic governing each segment's purchase pathway.
Product Type:
Standalone countertop units dominate premium positioning, while embedded sensor-integrated systems are penetrating professional recommendation channels through dental practice partnerships.
- Sonic:High-frequency vibration platforms operating at 31,000 strokes per minute deliver fluid dynamics that disrupt plaque beyond bristle contact. Coastal metropolitan households in California and New York concentrate demand for these clinically validated systems where dental professional endorsement carries highest purchase influence.
- Oscillating:Rotating-oscillating mechanisms combine 8,800 rotations with 20,000 pulsations per minute for mechanical plaque removal. Suburban markets across Texas and Florida show strongest adoption where pharmacy chain recommendation programs anchor consumer selection.
- Rotary:Simple circular brush head rotation at lower frequency targets entry-level conversion from manual brushing.
- Ultrasonic:Beyond-sonic frequencies claim therapeutic periodontal applications but face extended FDA 510(k) review timelines.
Sonic and oscillating platforms lead volumes today; ultrasonic systems are gaining share fastest among periodontal-focused professional channels.
Distribution Channel:
Channel segmentation tracks the shifting locus of purchase authority from retail shelf placement toward digital-native discovery and clinical endorsement integration.
- Pharmacies:CVS Health and Walgreens maintain highest-margin oral care placements through co-located dental professional recommendation programs and insurance-adjacent purchasing workflows. Urban coastal corridors concentrate pharmacy channel velocity where immediate professional access accelerates upgrade decisions.
- Online Retail:Amazon and direct-to-consumer platforms capture subscription replenishment demand and younger demographic research-to-purchase pathways. The channel expands most quickly as Bluetooth-enabled brush data integration supports telehealth-adjacent purchasing workflows.
- Supermarkets:Mass-market placements target price-sensitive household penetration with battery-operated entry-tier alternatives.
- Specialty Stores:Beauty and personal care retailers stock design-forward premium positioning for gift-purchase occasions.
Pharmacies retain margin leadership today; online retail is climbing the fastest as subscription models bypass traditional margin compression.
End User:
User segmentation aligns product form factors, interface design, and clinical messaging with developmental stage-specific oral health priorities and purchase decision authority.
- Adults:The core volume segment encompasses working-age consumers with discretionary preventive care spending and employer-sponsored dental insurance coverage. Affluent suburban households allocate disproportionate budgets toward connected brush systems with usage tracking.
- Seniors:Medicare Advantage integration opportunities concentrate demand among managed care enrollees where oral health data offers measurable preventive outcomes. Florida and Arizona retirement corridors show highest per-capita electric toothbrush penetration.
- Children:Gamification features and parental monitoring apps address compliance challenges in pediatric home care.
- Dental Professionals:Practice-dispensed systems for patient home-care compliance monitoring represent an emerging B2B channel.
Adult users dominate volume today; senior segments show steepest expansion trajectory as Medicare Advantage oral health integration matures.
Price Tier:
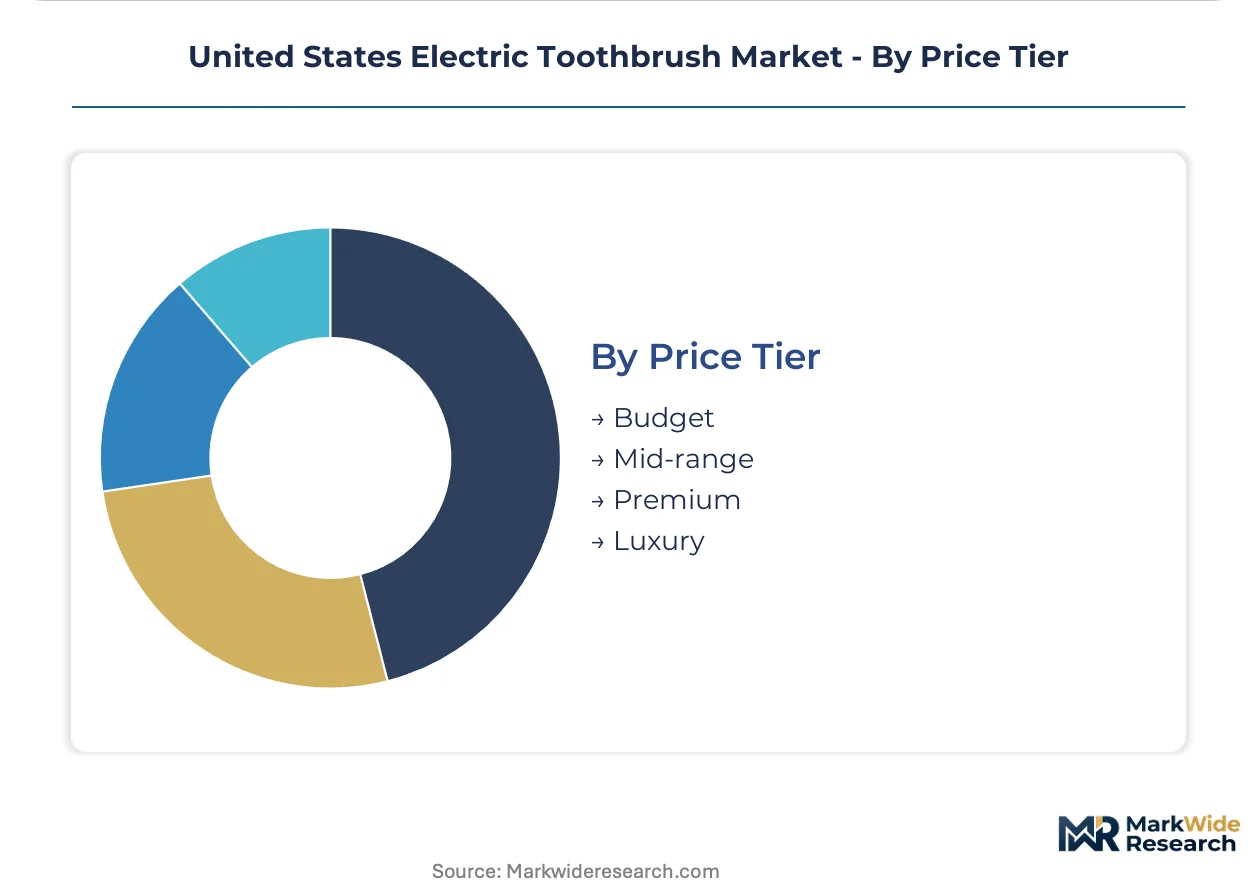
Pricing stratification mirrors the divergence between clinical validation requirements and cosmetic positioning routes, with FDA device classification thresholds creating distinct compliance cost structures.
- Premium:Sonic and connected brush systems with ADA Seal validation occupy the $150-$250 range where dental professional recommendation justifies price elevation. FDA Class II therapeutic claim pathways add 12-18 month clearance timelines that compress competitive entry.
- Mid-range:Established oscillating platforms without connectivity features target pharmacy channel dominance through proven efficacy documentation.
- Budget:Battery-operated alternatives from Church & Dwight and similar competitors capture price-sensitive rural and lower-income market resistance to premium conversion.
- Luxury:Design-forward limited editions and precious-metal finishes target gift-purchase occasions with minimal clinical positioning.
Premium tier leads value capture today; budget tier maintains volume leadership in underpenetrated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers face divergent compliance costs across US sub-regions, with FDA Class II pathway expenses pushing production toward states offering medical device tax incentives and specialized workforce pools.
California
Silicon Valley-connected brush startups concentrate in San Francisco and San Jose, leveraging proximity to sensor engineering talent and digital health investors. FDA's Center for Devices and Radiological Health maintains active pre-submission programs for Bay Area developers seeking 510(k) clearances. Los Angeles anchors premium sonic manufacturing through dental professional sampling networks serving coastal metropolitan households.
Texas
Dallas-Fort Worth corridor hosts battery-operated assembly operations benefiting from lower facility costs and central logistics positioning. State economic development incentives target medical device manufacturing through the Texas Enterprise Fund. Houston's dental school partnerships create clinical validation pipelines for oscillating platform manufacturers targeting pharmacy channel placement.
New York Metro
Manhattan and Brooklyn concentrate direct-to-consumer brand headquarters and subscription fulfillment operations. New York State Department of Health enforces connected device cybersecurity standards beyond baseline FDA requirements. Rochester's precision manufacturing heritage supports brush head molding and sensor component fabrication for premium product lines.
Florida
Retirement corridor demand from Medicare Advantage enrollees concentrates in Miami, Tampa, and Orlando metropolitan areas. State dental board regulations influence professional recommendation channel structures for senior-focused oral care devices. Jacksonville distribution centers serve Southeast pharmacy replenishment networks with inventory positioned for hurricane-season supply continuity.
Illinois/Ohio/Michigan
Chicago and Cleveland house legacy oscillating platform engineering centers with deep ties to pharmacy retail headquarters. Midwest manufacturing tax credits under federal CHIPS-adjacent programs support lithium-ion battery pack assembly retrofits. Detroit-area automotive electronics suppliers pivot brush motor and control module production toward oral care appliance contracts.
United States Electric Toothbrush Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with pharmacy channel dominance requiring ADA Seal validation while online retail rewards direct-to-consumer agility. The vendor base concentrates around three strategic archetypes: multinational consumer health conglomerates with dental professional networks, digital-native subscription brands with telehealth integrations, and Asian contract manufacturers supplying private-label retail programs. Consolidation pressure intensifies as FDA software-as-medical-device guidance raises compliance costs beyond mid-tier capital capacity. Dominant competitive moves include strategic partnerships with dental practice management platforms and backward integration into brush head molding operations.
Within the multinational tier, Procter & Gamble Company and Koninklijke Philips N.V. occupy positions defined by decades of professional channel cultivation and clinical validation investment. Church & Dwight Co., Inc. exemplifies the value-tier archetype through pharmacy shelf presence and battery-operated alternatives. Shenzhen Risun Technology Co., Ltd. represents contract manufacturing specialization serving private-label and direct-to-consumer brands with cost-optimized production platforms.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| FOREO |
| Procter & Gamble Company |
| Quip Inc. |
| Water Pik, Inc. |
| Colgate-Palmolive Company |
| Panasonic Corporation |
| Shenzhen Risun Technology Co., Ltd. |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Lithium carbonate price volatility cascades through brush motor and battery pack manufacturing, compressing margins in the premium connected segment while forcing tiered pricing stratification across pharmacy and direct-to-consumer channels.
Pricing Analysis
Pharmacy channel markup layers concentrate pricing power with CVS Health and Walgreens, where professional recommendation tie-ins justify premium positioning for ADA Seal-validated sonic systems. Three-tier pricing structure across premium, standard, and economy levels segments buyers by clinical validation intensity and connectivity features. Cost compression in the budget tier intensifies as Church & Dwight and private-label competitors race for rural market penetration. Price-sensitive consumers in lower-income demographics and rural geographies resist premium conversion despite documented efficacy, while affluent suburban households absorb connected brush price points with minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Jacksonville anchor hub-and-spoke replenishment patterns serving pharmacy chains and hurricane-season inventory pre-positioning. Manufacturing concentration in China, South Korea, and Vietnam supplies lithium-ion cells, precision motors, and sensor modules. Brush head nylon filaments and microprocessor controllers constitute critical single-source dependencies. Tariff exposure on Chinese electronics assemblies threatens margin stability for mid-range oscillating platforms. Distribution runs through pharmacy headquarters procurement, Amazon fulfillment networks, and direct-to-consumer subscription operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Electric Toothbrush Market functions as a stable compounder, with dental professional endorsement networks generating persistent upgrade demand from manual brush users.
For Market Incumbents: Hedge lithium-ion supply exposure through dual-sourcing agreements with South Korean cell manufacturers and domestic assembly partnerships in Texas. Pursue backward integration into brush head molding operations to capture recurring replenishment revenue streams. FDA software-as-medical-device guidance elevates compliance costs that threaten mid-tier competitors, creating consolidation opportunities for capital-rich leaders.
For New Entrants and Emerging Players: AI-driven pressure mapping sensors offer a technology-first wedge into dental practice dispensing channels beyond saturated retail shelves. Target Medicare Advantage integration in Florida and Arizona retirement corridors where oral health data reimbursement pathways remain underdeveloped. Deploy telehealth-adjacent subscription models that bypass pharmacy margin compression.
For Investors and Strategic Acquirers: Asymmetric upside sits with digital-native brands possessing HIPAA-compliant firmware architectures and dental practice management platform partnerships. Long-term viability favors acquirers with five-to-ten year holding capacity for reimbursement ecosystem maturation. Monitor FDA 510(k) clearance velocity for ultrasonic therapeutic claim submissions as inflection indicator for professional channel displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| ADA Seal Certification Investment | Clinical validation accelerates pharmacy channel placement and professional recommendation authority. |
| Subscription Direct-to-Consumer Launch | Automated brush head replenishment captures recurring revenue while bypassing retailer margin extraction. |
| Bluetooth Companion App Development | Usage tracking integration aligns with dental insurance wellness incentive program expansion. |
| Medicare Advantage Data Partnership | Oral health metrics offer payers measurable preventive outcomes for senior demographic reimbursement. |
| Domestic Battery Assembly Scale-Up | Texas and Midwest tax incentives reduce tariff exposure and shipping lane disruption vulnerability. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental practice managers, pharmacy category buyers, biomedical engineers at brush manufacturers, and GPO contracts administrators with secondary validation against FDA 510(k) filings, ADA Seal acceptance records, CMS Medicare Advantage oral health integration data, and Nielsen retail audit metrics. Bottom-up shipment modeling and top-down dental professional survey data triangulated volume estimates across product tiers.
Segment-weighting approaches distributed value projections across sonic, oscillating, rotary, and ultrasonic product types; pharmacy, online retail, supermarket, and specialty store channels; and adult, senior, children, and dental professional end-user categories. CAGRs derived from historical penetration curves, replacement cycle analysis, and professional recommendation intensity indices. Forecast inputs incorporated lithium-ion cost trajectories and dental insurance reimbursement policy evolution across the projection horizon.
The model holds under stable FDA device classification frameworks and continued employer-sponsored dental coverage prevalence; deviation in Medicare Advantage oral health data integration timelines or lithium supply chain disruptions would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Electric Shavers Market
Personal Grooming Products
Smart Electric Toothbrush Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Shaving Market
Personal Grooming Products
Pre-Shave Products Market
Personal Grooming Products
Disposable Razor Market
Personal Grooming Products
Gel Socks Market
Personal Grooming Products
360 Degree Toothbrush Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Cotton Buds Market
Personal Grooming Products
Organic and Natural Tampons Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
Underarm Sweat Pads Market