
 Back Massager Market | 2026-2036
Back Massager Market Size, Share, and Industry Trends Forecast 2026-2036
Back Massager Market Analytics
The EU Medical Device Regulation is repositioning compliance costs for manufacturers seeking CE marking across European markets. Panasonic Corporation leverages its vertical integration in motor and sensor technology to sustain premium positioning in massage chair systems. HoMedics anchors its competitive stance through broad retail distribution across North American big-box channels. OSIM International dominates the premium segment in Southeast Asian markets with dedicated flagship store networks.
Back massagers encompass electromechanical and manually operated devices engineered to deliver therapeutic pressure, vibration, or thermal treatment to musculature, typically operating at frequencies between 20-60 Hz for percussion units and incorporating heating elements reaching 40-45 degrees Celsius for thermal therapy models. Electric massagers and massage chairs command the dominant revenue share due to higher unit economics and replacement part ecosystems, while shiatsu massagers represent the fastest-expanding product category as consumers seek Japanese-inspired deep-tissue functionality. Vibration and heat therapy technologies lead installed base volumes, though percussion systems are gaining traction among physiotherapy clinic purchasers seeking clinical-grade myofascial release.
The US FDA oversees electrical safety and therapeutic claims for powered massage devices, while Japan's Ministry of Economy, Trade and Industry (METI) administers PSE certification mandates for domestic appliance sales, and China's State Administration for Market Regulation (SAMR) enforces GB standards for electromagnetic compatibility in household electronics. These frameworks collectively raise engineering barriers for new entrants while steering incumbent investment toward certified component supply chains and documented clinical efficacy testing. Stakeholders must monitor evolving classification thresholds that could reclassify certain massage devices from consumer wellness to regulated medical equipment, fundamentally altering reimbursement pathways and channel access.
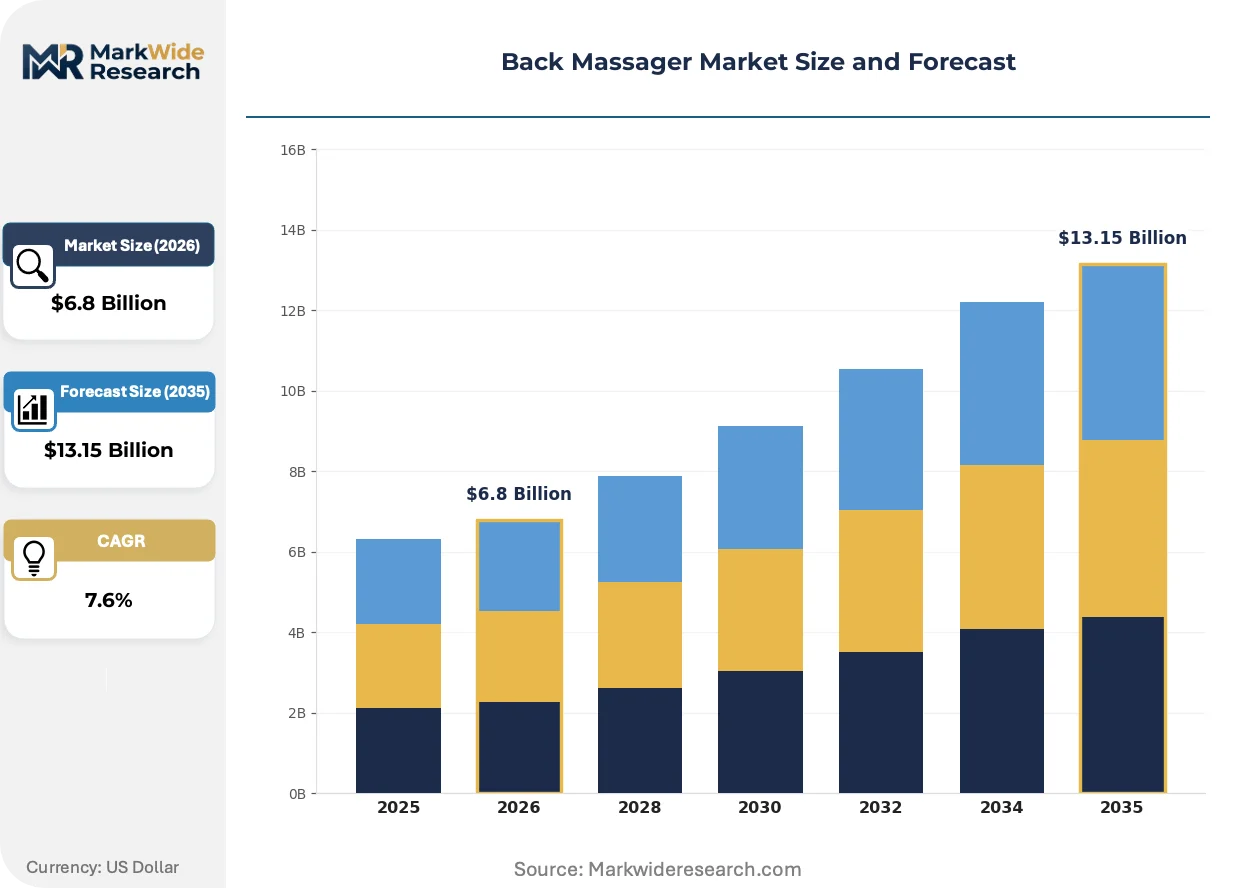
Market Dynamics
The EU MDR is forcing manufacturers to recertify massage devices under stricter electrical safety and clinical documentation thresholds, compressing margins for mid-tier producers while creating compliance moats for incumbents with dedicated regulatory affairs teams.
Growth Catalysts
- Corporate wellness mandates:Large employers in Germany and the United States now subsidize ergonomic equipment including back massagers as deductible wellness expenditures under occupational health frameworks.
- Percussion frequency engineering:Advances in brushless motor control enable precise 20-60 Hz modulation for myofascial release, attracting physiotherapy clinic procurement committees seeking clinical-grade devices.
- CE marking pathway expansion:The EU MDR's clarified classification criteria for wellness-to-medical device thresholds is opening reimbursement channels for certified therapeutic massagers in France and Italy.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electric motor cores depend on neodymium and copper windings, with price swings in Chinese processing facilities transmitting directly to BOM costs.
- Shenzhen component concentration:PCB assemblies and heating element controllers cluster in Pearl River Delta manufacturing zones, exposing supply continuity to regional logistics disruptions.
- Battery thermal runaway limitations:Lithium-ion cell safety constraints cap heating element duration in cordless models, restricting session length versus corded alternatives.
Strategic Opportunities
- Telehealth integration:Remote physical therapy platforms in the United States are prescribing connected massagers with usage telemetry, creating subscription revenue streams alongside hardware sales.
- India BIS certification acceleration:Streamlined appliance testing protocols under the Bureau of Indian Standards are reducing time-to-market for premium massage chair entrants targeting Mumbai and Delhi NCR households.
- AI pressure mapping convergence:Sensor fusion between capacitive touch arrays and machine learning algorithms enables real-time muscle tension detection, differentiating next-generation shiatsu systems.
Industry Challenges
- Biomedical engineering talent scarcity:Device firms struggle to recruit firmware developers capable of integrating ISO 13485-compliant software lifecycle documentation with consumer electronics release cycles.
- CE marking timeline compression:EU MDR notified body backlogs extend certification reviews to 18-24 months, delaying product launches and freezing R&D amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Back Massager Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Massagers, Manual Massagers, Massage Chairs, Shiatsu Massagers End User: Home Users, Physiotherapy Clinics, Health Clubs, Spa Centers Technology: Vibration, Heat Therapy, Kneading, Percussion Distribution Channel: Online Retailers, Specialty Stores, E-commerce Platforms, Supermarkets |
| Companies Covered | Panasonic Corporation, HoMedics, OSIM International, Beurer GmbH, Human Touch, Family Inada, Fujiiryoki, OGAWA, Breo International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Back Massager Market Evolving Landscape
Wearable form factors and AI-driven personalization are displacing static massage chairs as the primary innovation frontier, with manufacturers racing to miniaturize percussion mechanisms without sacrificing therapeutic depth.
Brushless DC motor architectures with integrated Hall-effect sensors are electrifying precision control in handheld percussion devices. Physiotherapy clinics across Australia and Canada are adopting these units for in-session myofascial protocols. The technology is electrifying the boundary between consumer wellness and clinical-grade equipment, forcing traditional manufacturers to retool motor supply chains.
The EU Medical Device Regulation's 2021 enforcement cascade continues tightening electrical safety documentation for heated massage devices sold across France, Germany, and Italy. Manufacturers must now submit biocompatibility testing for skin-contact materials and electromagnetic compatibility verification under harmonized EN standards. Premium massage chair producers with dedicated regulatory affairs teams in Stuttgart and Milan are absorbing these costs while smaller importers exit the market.
Subscription-based equipment access is displacing outright purchase in United States corporate wellness channels. Employers in Texas and California now lease connected massage devices with usage analytics rather than capitalizing hardware. This model concentrates procurement authority with benefits administrators, compressing vendor margins but securing multi-year revenue visibility for compliant suppliers.
Back Massager Market Segmentation
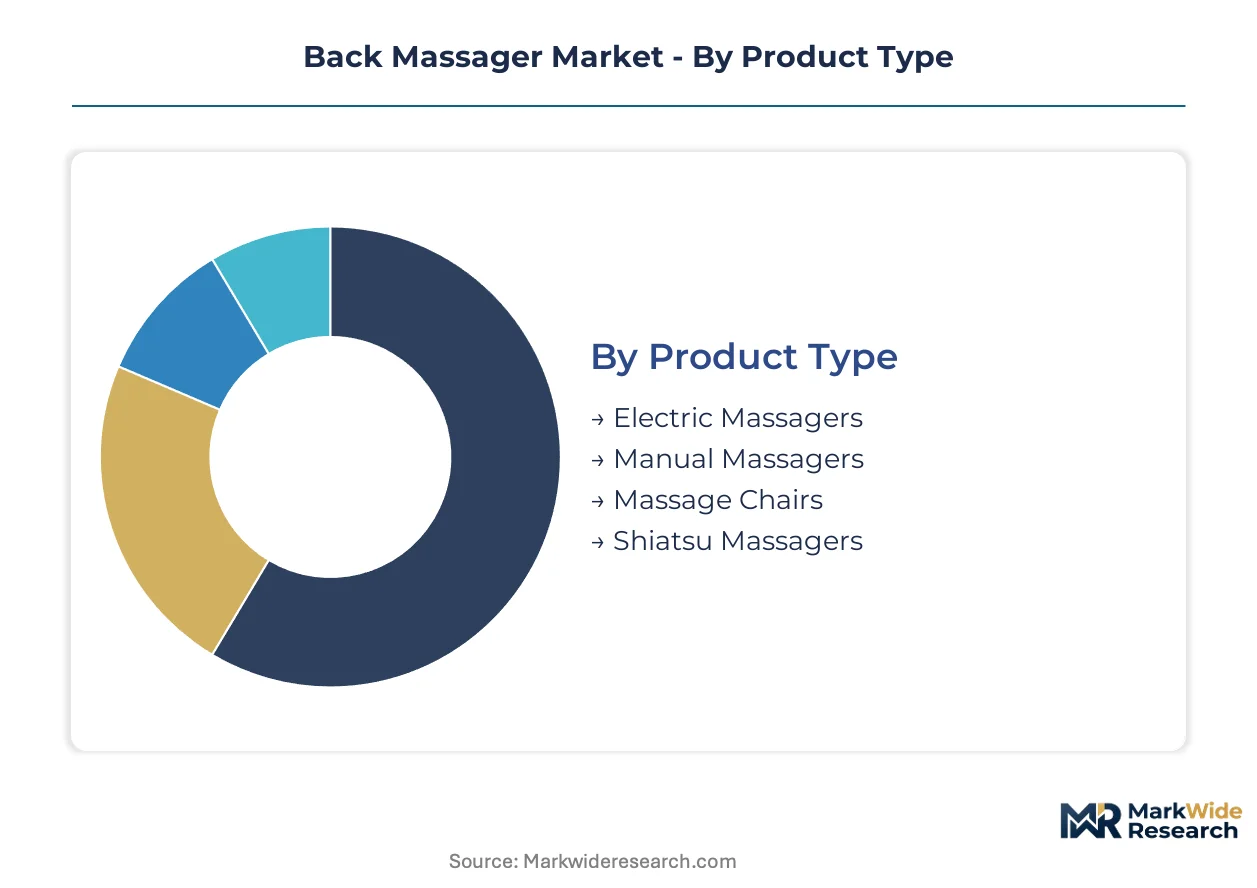
Back massager purchasing decisions hinge on therapeutic intensity, portability constraints, and reimbursement eligibility across distinct user environments. Manufacturers calibrate motor specifications, heating element integration, and price positioning to match the divergent expectations of home consumers versus clinical procurement committees.
Product Type:
Purchase volume concentrates around devices balancing unit economics with replacement part ecosystems, while growth trajectories favor Japanese-inspired deep-tissue functionality.
- Electric Massagers:Corded and cordless handheld units deploy brushless DC motors with Hall-effect sensors for 20-60 Hz percussion modulation. Home users in Germany and the United States drive replacement demand through corporate wellness subsidies, though battery thermal constraints limit cordless session duration versus AC-powered alternatives.
- Shiatsu Massagers:Rotating node mechanisms simulate thumb-pressure techniques through bi-directional motor control and thermal integration reaching 40-45 degrees Celsius. Southeast Asian flagship retail networks concentrate premium demand as consumers seek authentic Japanese therapeutic heritage combined with AI pressure mapping convergence.
- Manual Massagers:Non-powered devices relying on body-weight leverage and textured surfaces for myofascial release, typically manufactured from ABS plastic or sustainable bamboo composites.
- Massage Chairs:Full-body electromechanical systems incorporating zero-gravity recline, foot rollers, and lumbar heat zones with premium price points anchoring household discretionary spending in China, Japan, and South Korea.
Electric massagers lead on scale; shiatsu massagers lead on momentum.
End User:
Procurement authority fragments between individual discretionary purchases and institutional buying committees with documented clinical efficacy requirements.
- Home Users:Individual consumers prioritizing post-workout recovery and chronic pain management, purchasing through e-commerce platforms and big-box retail channels with warranty terms influencing brand selection.
- Physiotherapy Clinics:Clinical-grade device procurement governed by ISO 13485 compliance and electromagnetic compatibility verification under FDA or EU MDR frameworks, with brushless motor precision driving adoption for myofascial release protocols in Australia and Canada.
- Health Clubs:Facility managers selecting durable commercial-grade units with high-duty cycle ratings and minimal maintenance requirements for member amenity areas.
- Spa Centers:Hospitality-oriented establishments integrating heated massage chairs into service menus, with aesthetic design and upholstery durability ranking alongside therapeutic specifications.
Home users dominate absolute volume; physiotherapy clinics concentrate value per transaction.
Technology:
Engineering investment prioritizes frequency precision and thermal safety as regulatory thresholds tighten across European and North American markets.
- Vibration:Oscillating motor mechanisms operating at fixed or variable frequencies for surface-level muscle stimulation, dominating installed base volumes through lower manufacturing complexity and entry-level pricing accessibility.
- Percussion:Rapid vertical striking action penetrating deep fascial layers through amplitude-adjustable piston mechanisms, gaining share fastest among physiotherapy clinics seeking clinical-grade myofascial release capabilities.
- Heat Therapy:Resistive heating elements integrated into contact surfaces with biocompatibility documentation required under EU MDR for skin-contact materials.
- Kneading:Rotational compression mimicking manual massage techniques through opposing node movement, standard in shiatsu-form-factor devices.
Vibration leads on installed base; percussion leads on clinical adoption velocity.
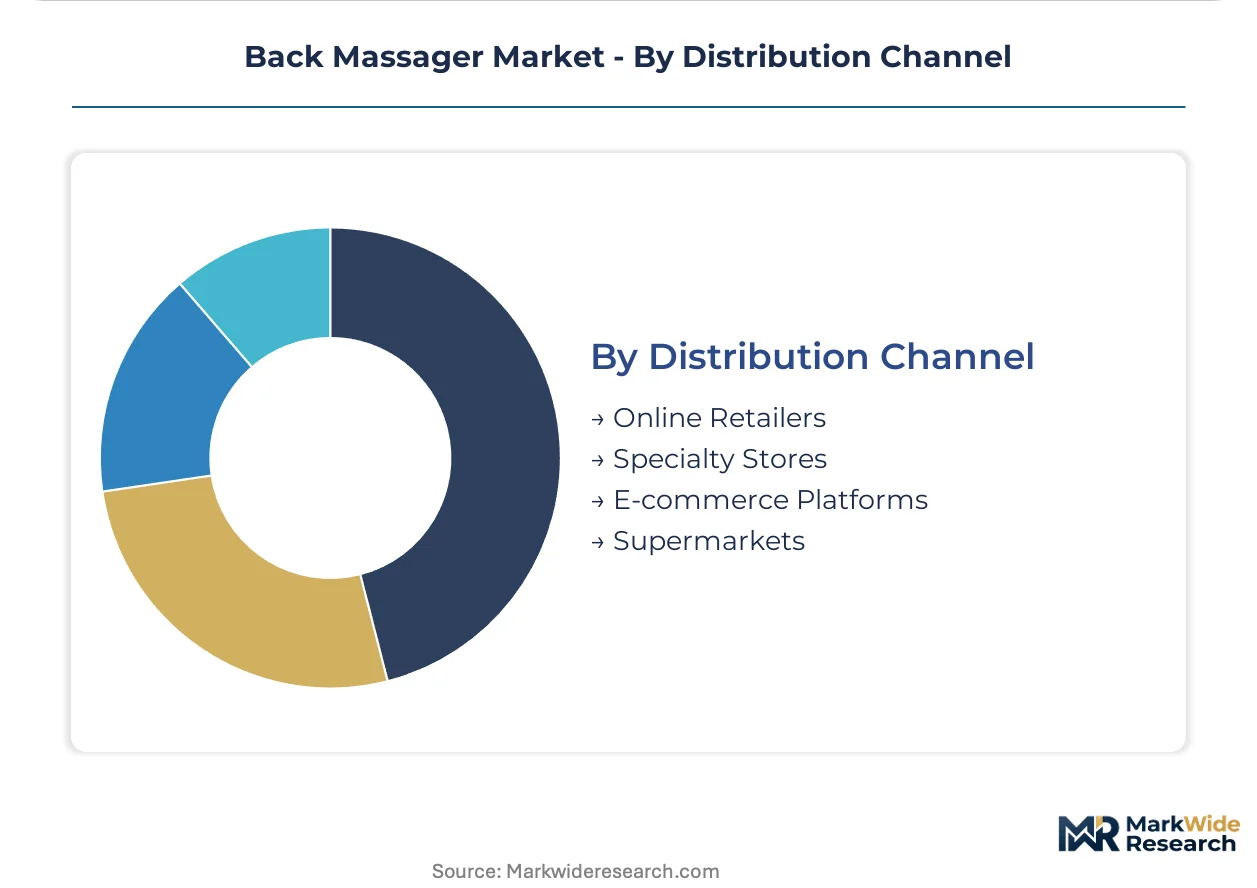
Distribution Channel:
Channel selection determines margin structure, warranty liability allocation, and access to usage telemetry for subscription revenue models.
- Online Retailers:Third-party marketplace platforms enabling price comparison and review aggregation, capturing significant home user volume with compressed margins and return logistics complexity.
- E-commerce Platforms:Direct-to-consumer brand websites with subscription leasing options and usage analytics integration, concentrating corporate wellness procurement authority in Texas and California benefits administrations.
- Specialty Stores:Dedicated wellness retailers with trained sales staff demonstrating therapeutic features, sustaining premium positioning for massage chair systems through consultative selling environments.
- Supermarkets:Mass-market retail placement for entry-level electric and manual massagers, prioritizing impulse purchase accessibility and seasonal promotional cycles.
Online retailers lead on transaction volume; e-commerce platforms lead on recurring revenue attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered electromechanical massage technology in the 1950s, establishing Osaka and Tokyo as the industry's foundational manufacturing clusters. This heritage continues shaping competitive dynamics across major consumer markets worldwide.
United States
Corporate wellness subsidies in Texas and California drive procurement of connected massage devices with usage telemetry. FDA oversight of electrical safety and therapeutic claims elevates compliance costs for new entrants. The Dallas-Fort Worth metroplex hosts distribution centers serving North American big-box retail channels.
Germany
Occupational health frameworks subsidize ergonomic equipment including back massagers as deductible wellness expenditures. EU MDR enforcement through notified bodies in Stuttgart extends certification timelines to 18-24 months. The Baden-Württemberg region concentrates regulatory affairs expertise for CE marking compliance.
China
Household discretionary spending in Shanghai and Beijing anchors demand for premium massage chair systems. SAMR enforcement of GB standards for electromagnetic compatibility raises engineering barriers for domestic manufacturers. The Pearl River Delta clusters PCB assembly and heating element controller production.
Japan
METI administration of PSE certification mandates shapes domestic appliance safety requirements. Osaka-based manufacturers leverage vertical heritage in motor and sensor technology for premium positioning. The Kansai region maintains flagship retail networks for shiatsu-form-factor distribution.
South Korea
MFDS oversight of household electronics safety converges with consumer preference for AI-integrated wellness devices. Seoul Capital Area households concentrate demand for full-body electromechanical systems with zero-gravity recline functionality. Busan-Ulsan industrial zones supply brushless DC motor components.
Back Massager Market Competitive Landscape
The competitive structure tilts toward diversified electronics conglomerates with captive component supply chains. Panasonic Corporation exemplifies this pattern through in-house production of motors and sensors. Three archetypes dominate: vertically integrated Japanese manufacturers, North American retail-channel specialists, and Southeast Asian premium-brand operators. Consolidation pressure intensifies as EU MDR compliance costs force mid-tier importers toward exit. Strategic moves concentrate on regulatory affairs team expansion and certified component supply chain lock-in.
Among Japanese electronics conglomerates, Panasonic Corporation and Family Inada occupy positions defined by manufacturing heritage and domestic market anchoring. OSIM International exemplifies the Southeast Asian premium-brand archetype through dedicated flagship store networks. HoMedics represents North American retail-channel specialization with broad big-box distribution coverage. These three companies illustrate how geographic origin and channel strategy stratify competitive positioning without requiring identical capability investments.
| Leading Market Players |
|---|
| Panasonic Corporation |
| HoMedics |
| OSIM International |
| Beurer GmbH |
| Human Touch |
| Family Inada |
| Fujiiryoki |
| OGAWA |
| Breo International Group |
| Others |
Value Network & Pricing Analysis
CE marking tier divergence between certified therapeutic devices and unregulated wellness products splits pricing power across European procurement channels while concentrating component sourcing among notified-body-approved suppliers in Stuttgart and Milan. This bifurcation forces mid-tier manufacturers to absorb compliance costs or exit, while premium incumbents leverage certified supply chains to sustain margin premiums in corporate wellness and clinical segments.
Pricing Analysis
Bundled subscription services for connected massage devices with usage telemetry separate from unbundled transactional hardware sales across United States corporate wellness channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under FDA and EU MDR frameworks, with ISO 13485-compliant clinical units commanding substantial premiums over consumer wellness alternatives. Pricing pressure stems from copper and rare-earth magnet cost volatility transmitting through brushless motor BOMs. Home users through online retailers exhibit highest price sensitivity; physiotherapy clinics demonstrate lowest sensitivity due to reimbursement eligibility.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for massage chair systems while specialty retail networks distribute premium shiatsu units through flagship environments. Component manufacturing concentrates in China, Japan, and South Korea, with Pearl River Delta facilities producing PCB assemblies and heating element controllers. Neodymium magnets, copper windings, and lithium-ion cells constitute critical input dependencies. Single-source vulnerability in Shenzhen component concentration exposes continuity to regional logistics disruptions. Distribution runs through big-box retail, e-commerce platforms, and dedicated wellness retail channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Back massager demand compounds steadily through corporate wellness program embedding, creating predictable replacement cycles and subscription revenue visibility across employer benefit channels.
For Market Incumbents: To counter EU MDR compliance cost compression, deepen regulatory affairs capabilities in Stuttgart and Milan while locking in certified component supply chains through long-term offtake agreements with Pearl River Delta manufacturers. Expand telehealth integration partnerships with United States remote physical therapy platforms to secure multi-year subscription visibility.
For New Entrants and Emerging Players: Capture white-space opportunity in India's streamlined BIS certification pathway for premium massage chair systems targeting Mumbai and Delhi NCR household discretionary spending. Exploit AI pressure mapping convergence in next-generation shiatsu form factors through sensor fusion partnerships with capacitive touch array suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed mid-tier importer margin capacity, creating acquisition opportunities for distressed brands with established retail shelf presence. Long-term viability favors vertically integrated manufacturers with captive motor and sensor production. Watch CE marking notified body backlog resolution as inflection indicator for product launch velocity recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Expansion | Opens reimbursement channels in France and Italy for certified therapeutic massagers under clarified EU MDR classification criteria. |
| Telehealth Platform Integration | Creates subscription revenue streams alongside hardware sales through United States remote physical therapy prescription networks. |
| AI Pressure Mapping Development | Differentiates next-generation shiatsu systems through real-time muscle tension detection using capacitive touch arrays. |
| Corporate Wellness Partnership | Secures multi-year revenue visibility through employer benefits administration procurement in Texas and California. |
| Certified Supply Chain Lock-in | Absorbs EU MDR biocompatibility and electromagnetic compliance costs while creating moats against mid-tier competitors. |
Research Methodology
Multiple input streams — regulatory filing analysis, component supplier interviews, and procurement database mining — were reconciled across primary conversations with massage device engineering directors, corporate benefits administrators, physiotherapy clinic procurement managers, and specialty retail channel heads. Secondary validation drew from FDA 510(k) submissions, EU MDR notified body documentation, SAMR GB standard filings, and corporate wellness program disclosures. Bottom-up unit shipment estimates and top-down category spend analysis were triangulated to constrain forecast variance.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product type, end-user environment, technology mechanism, and distribution channel dimensions with geographic regulatory cluster overlays. CAGRs were derived from fitted trend analysis adjusted for substitution elasticity between corded and cordless form factors and corporate wellness penetration saturation curves.
Raw material cost volatility, notified body certification timeline extensions, and battery thermal safety regulatory tightening are the dominant revision risks to shipment and value forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Hand Hygienic Product Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Smart Electric Toothbrush Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Personal Lubricants Market
Personal Grooming Products
Horsehair Clippers Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Electric Hair Brush Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Biometric Vaporizer Market