
 Razor Blade Market | 2026-2036
Razor Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Razor Blade Market Analysis
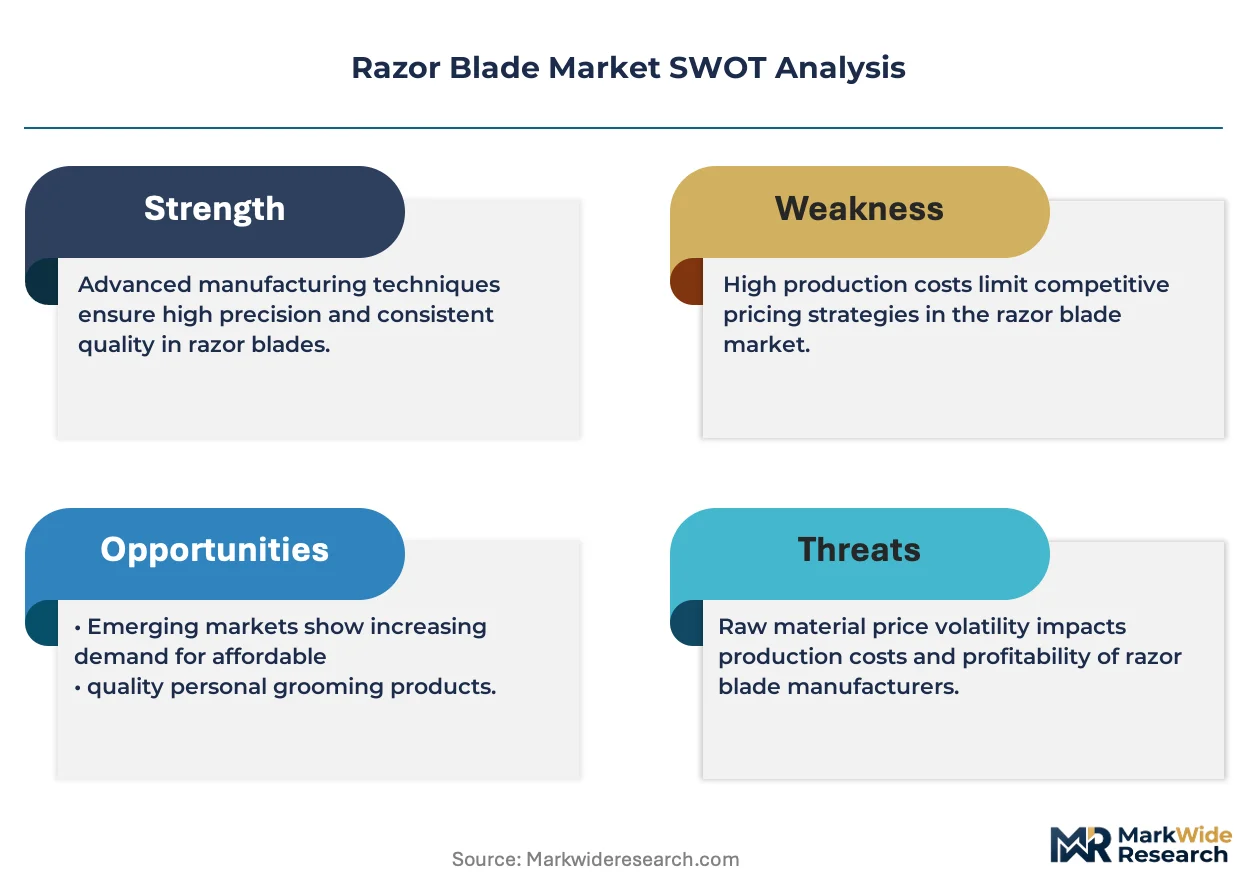
REACH is restructuring the cost-of-entry calculus for European razor blade manufacturers by mandating full material disclosure and restricted substance controls. Procter & Gamble leverages its captive supply chain to absorb compliance costs without margin erosion. Edgewell Personal Care competes through dermatological testing partnerships that satisfy both ECHA and FDA pathways.
A razor blade is a precision-ground cutting edge, typically fabricated from martensitic stainless steel with Rockwell hardness between 58 and 62 HRC, designed for controlled hair severance with minimal epidermal trauma. The cartridge segment dominates value pools through proprietary docking systems that lock in replacement cycles, while the double edge category sustains a niche but durable collector and sustainability-oriented user base. Ceramic coatings on stainless steel substrates represent the fastest-growing material trajectory as manufacturers seek differentiation through extended edge retention.
FDA oversight in the United States classifies certain razor systems as medical devices when marketed for surgical preparation, creating dual regulatory pathways that shape product development budgets. EMA-aligned dermatological safety standards in Europe and BIS certification requirements in India collectively fragment compliance architectures across major demand centers. Stakeholders must monitor how evolving extended producer responsibility frameworks in the European Union alter packaging and take-back obligations for disposable formats.
Market Dynamics
REACH compliance in Europe is restructuring material disclosure obligations across the razor blade supply chain, forcing manufacturers to absorb elevated testing costs or exit the region entirely.
Growth Catalysts
- Professional barbershop channel:India's dense network of street-side grooming establishments sustains bulk cartridge consumption through institutional procurement contracts.
- Ceramic coating technology:Extended edge retention properties reduce replacement frequency for premium users while commanding higher unit economics.
- EMA-aligned dermatological standards:Safety certification requirements create preference premiums for clinically tested cartridge systems in European pharmacies.
Market Restraints
- Martensitic stainless steel volatility:Nickel and chromium price swings compress margins for precision-ground substrate manufacturers.
- Proprietary docking concentration:Three cartridge systems control replacement cycle lock-in, limiting new entrant distribution access.
- Double edge substitution ceiling:Collector and sustainability-oriented users sustain niche demand but resist volume scaling.
Strategic Opportunities
- Extended producer responsibility frameworks:EU packaging take-back mandates create first-mover advantage for recyclable cartridge designs.
- Surgical preparation pathway:FDA medical device classification for pre-operative razor systems opens institutional hospital procurement.
- Direct-to-consumer subscription:Automated replenishment models bypass retail margin extraction in North American urban markets.
Industry Challenges
- Rockwell hardness calibration:Precision grinding to 58-62 HRC specifications requires scarce metallurgical expertise and capital-intensive equipment.
- Dual regulatory pathway complexity:Parallel FDA cosmetic and medical device tracks extend product development timelines by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Razor Blade Market |
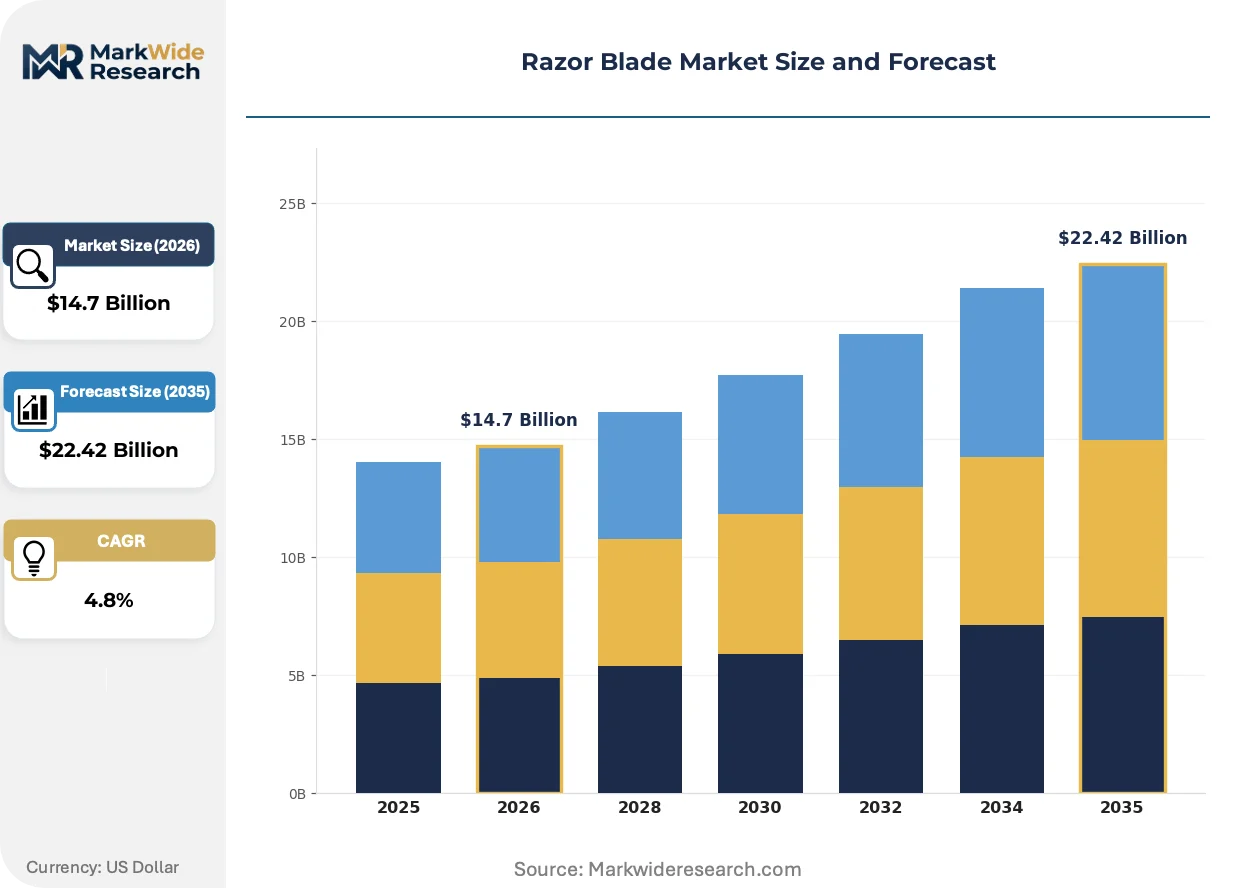
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Edge, Cartridge, Safety, Disposable Material: Stainless Steel, Carbon Steel, Ceramic, Coated End User: Personal Care, Professional Salons, Barbershops, Medical Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Drugstores |
| Companies Covered | Procter & Gamble, Edgewell Personal Care, BIC, Dorco, Feather Safety Razor, Kai Company, Supermax, Lord International, Harry's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Razor Blade Market Emerging Trajectories
Material science advances and regulatory fragmentation are simultaneously elevating performance thresholds and compliance costs across all major demand centers.
Ceramic coatings on martensitic stainless steel substrates is expanding into premium cartridge systems. Grooming enthusiasts and professional barbers in Germany and Japan adopt these formulations for extended shave consistency. The technology is compressing replacement cycle revenue for legacy uncoated blades while building aftermarket service attachment.
REACH substance restriction lists now cover seventeen additional chemicals in blade adhesives and lubrication strips. European manufacturers face reformulation costs or supply chain restructuring to maintain ECHA registration. Cartridge producers with captive chemistry capabilities absorb these transitions faster than contract-manufactured competitors.
Subscription-based replenishment models now dominate urban millennial acquisition channels. Traditional retail shelf space loses share to automated delivery platforms in US coastal cities and London. Barbershop institutional procurement in India resists this shift, preserving wholesale distribution concentration.
Razor Blade Market Segmentation
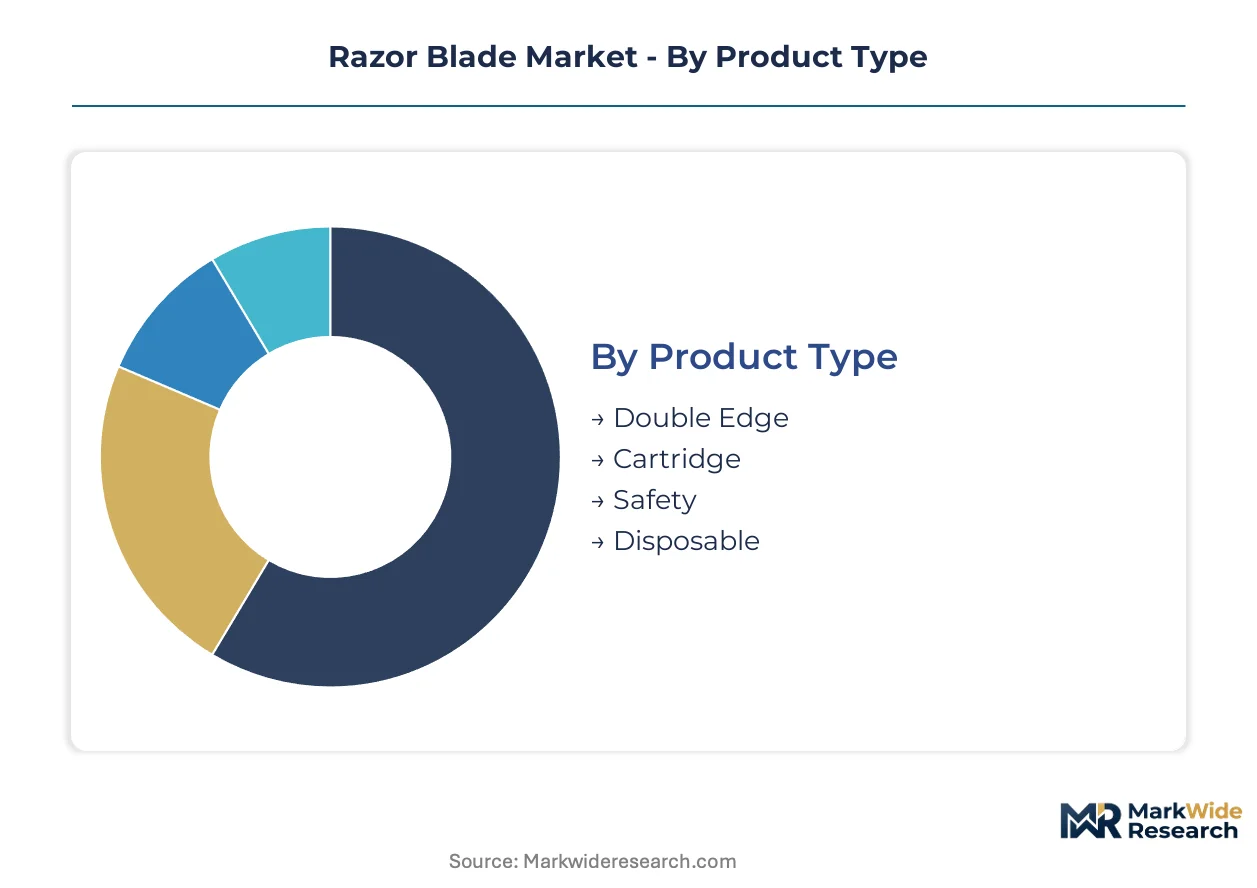
Razor blade segmentation reveals how replacement frequency and upgrade willingness vary dramatically across user profiles. Manufacturers calibrate coating investments and cartridge complexity against these divergent cycle economics.
Product Type:
Upgrade cycles range from daily disposables to decade-spanning safety razors, creating distinct margin architectures for each format.
- Cartridge:Proprietary docking systems lock users into branded replacement streams through precision-matched interfaces. German and Japanese grooming enthusiasts sustain premium pricing for five-blade configurations with lubrication strips.
- Double Edge:Standardized threading accepts blades from any manufacturer, breaking lock-in economics. Collector communities in the United Kingdom and Italy preserve artisanal scale production through heritage brand loyalty.
- Safety:Fixed-head designs with butterfly or three-piece construction appeal to technique-oriented users seeking cost control over convenience.
- Disposable:Single-piece construction eliminates replacement logistics entirely, dominating travel and institutional procurement in price-sensitive markets.
Volume placements concentrate in Disposable; the faster expansion belongs to Cartridge.
Material:
Substrate selection determines edge retention, corrosion resistance, and coating compatibility across humid and saline exposure conditions.
- Stainless Steel:Martensitic grades with 58-62 HRC hardness deliver the precision-ground edge standard for cartridge systems. Indian barbershops specify this substrate for bulk institutional procurement due to predictable corrosion performance in tropical climates.
- Ceramic:Zirconium dioxide coatings extend functional edge life threefold over uncoated alternatives. Japanese manufacturers lead integration into premium cartridges targeting weekly rather than daily replacement schedules.
- Carbon Steel:Superior initial sharpness requires immediate post-use drying, limiting adoption to enthusiast segments with disciplined maintenance rituals.
- Coated:Polytetrafluoroethylene and chromium nitride depositions reduce friction coefficients for sensitive skin applications in European pharmacy channels.
Stainless Steel commands current volume leadership; Ceramic climbs the fastest as coating costs decline.
End User:
Application context shapes blade specification from cosmetic hair removal to pre-surgical skin preparation with divergent sterility requirements.
- Personal Care:Individual consumers prioritize convenience and skin comfort over unit economics, sustaining cartridge premiumization in North American and Western European households.
- Barbershops:India's dense network of street-side establishments drives bulk cartridge consumption through wholesale procurement contracts with razor-agnostic blade suppliers.
- Professional Salons:Cosmetology licensing requirements in California and New York mandate single-use disposables for liability mitigation, compressing reusable format penetration.
- Medical:FDA device classification for pre-operative skin preparation opens hospital procurement pathways with sterility documentation requirements exceeding cosmetic standards.
Barbershops anchor current volume; Medical shows steepest expansion trajectory as surgical preparation protocols standardize.
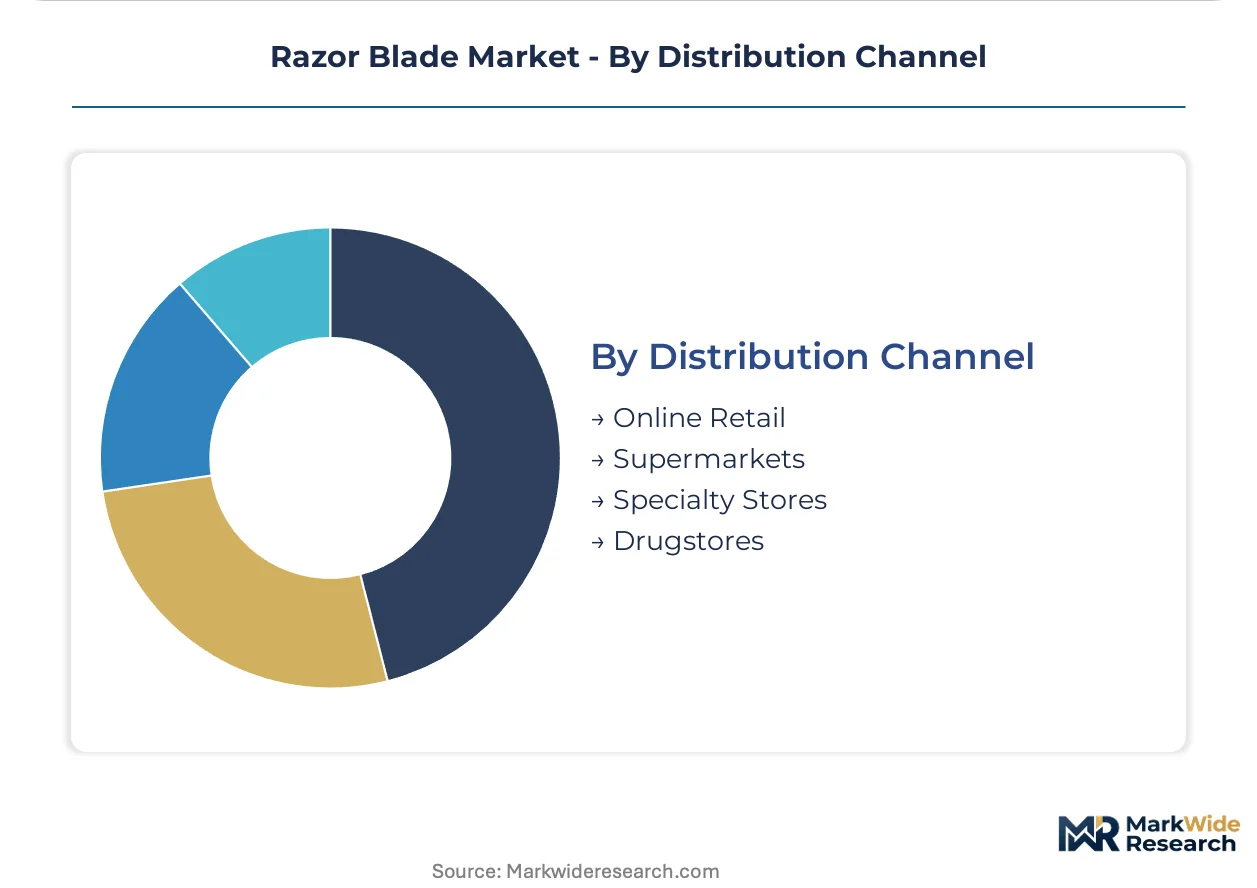
Distribution Channel:
Channel selection determines packaging format, margin extraction layers, and replenishment automation potential.
- Online Retail:Subscription algorithms automate replacement timing based on declared shave frequency, capturing urban millennial cohorts in London and New York with direct margin retention.
- Supermarkets:Mass-market placement requires blister-pack formats with theft-deterrent dimensions, limiting premium cartridge display space to top-three brands.
- Specialty Stores:Shave-den boutiques in Paris and Tokyo offer blade sampling and technique education, sustaining double-edge and safety razor discovery among converts from cartridge systems.
- Drugstores:Pharmacy placement in Germany and Switzerland requires EMA-aligned dermatological certification, filtering out uncoated and untested blade offerings.
Supermarkets retain volume dominance; Online Retail gains share fastest as replenishment automation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's dense network of special economic zones and export-oriented manufacturing corridors concentrates razor blade production capacity. These designated zones attract precision metallurgy investments through duty exemptions and streamlined customs procedures. Manufacturing clusters in Solingen, Germany and Seki, Japan maintain heritage grinding expertise alongside modern coating facilities.
United States
Subscription-based replenishment models capture urban millennial cohorts in New York and Los Angeles through automated delivery platforms. FDA dual regulatory pathways for cosmetic and medical device classifications extend product development timelines for surgical preparation systems. Boston-area dermatology research partnerships validate blade coatings for sensitive skin applications in pharmacy channels.
Germany
Solingen's precision grinding heritage anchors European martensitic stainless steel blade production with Rockwell hardness calibration expertise. REACH substance restrictions on blade adhesives force reformulation investments across seventeen newly controlled chemicals. Frankfurt pharmacy networks require EMA-aligned dermatological certification, filtering untested cartridge offerings from shelf placement.
India
Street-side barbershop density in Mumbai and Delhi sustains bulk institutional procurement through razor-agnostic blade suppliers. BIS certification mandates for imported stainless steel substrates elevate local metallurgy investments in Gujarat manufacturing corridors. Tamil Nadu's precision engineering clusters supply grinding equipment to domestic cartridge fabricators.
Japan
Seki's cutlery tradition translates into ceramic coating leadership for extended edge retention formulations. METI industrial standards govern precision grinding tolerances for export-grade cartridge systems. Osaka-based grooming enthusiasts drive premium five-blade configurations with lubrication strip innovations through specialty retail channels.
United Kingdom
Heritage safety razor collector communities in London and Birmingham preserve artisanal double-edge blade production at reduced scale. Post-BREACH chemical regulations align with REACH substance disclosure requirements for cross-border EU trade. Manchester distribution hubs consolidate wholesale procurement for European pharmacy networks.
Razor Blade Market Vendor Landscape
United States producers anchor the subscription-commerce tier; German and Japanese specialists hold precision-manufacturing positions. The vendor base concentrates around three proprietary cartridge docking systems that lock replacement cycles. Strategic archetypes include captive chemistry conglomerates, heritage grinding specialists, and direct-to-consumer challengers. Competitive moves center on dermatological certification partnerships and recyclable cartridge design patents.
Among heritage grinding specialists, Feather Safety Razor and Kai Company exemplify Japanese precision-metallurgy positioning. Procter & Gamble occupies a scale-driven archetype with captive supply chain absorption of regulatory compliance costs. Edgewell Personal Care sits within the dermatological certification tier through EMA and FDA pathway partnerships.
| Leading Market Players |
|---|
| Procter & Gamble |
| Edgewell Personal Care |
| BIC |
| Dorco |
| Feather Safety Razor |
| Kai Company |
| Supermax |
| Lord International |
| Harry's |
| Others |
Supply Flow & Price Mechanics
Captive chemistry capabilities at Procter & Gamble and Edgewell anchor both supply security and pricing power across European and North American markets. REACH compliance costs and ceramic coating investments concentrate margin leverage with vertically integrated incumbents who absorb regulatory burdens without passing through price erosion.
Pricing Analysis
Short lead-time premiums for ceramic-coated cartridges command forty to sixty percent markups over standard martensitic stainless steel alternatives in German and Japanese specialty channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by coating complexity and dermatological certification grade. Price differentiation stems from EMA-aligned safety documentation and volume procurement scale in Indian barbershop institutional contracts. Cost compression in uncoated double-edge segments intensifies because raw material volatility in nickel and chromium feeds margin tightening.
Supply Chain Analysis
Direct-to-retail and direct-to-consumer channels handle hyperscale subscription demand in US coastal cities and London, while wholesale distribution serves Indian barbershop procurement. Manufacturing concentrates in India, Germany, and Japan, with Solingen and Seki preserving precision grinding heritage alongside Tamil Nadu's emerging equipment fabrication. Raw material dependencies draw from martensitic stainless steel substrates, zirconium dioxide ceramic precursors, and chromium nitride deposition feedstocks. Single-source vulnerability in proprietary cartridge docking interfaces creates lock-in risk for replacement cycle revenue. Distribution runs through automated replenishment platforms, pharmacy networks, and institutional procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions on seventeen blade adhesive chemicals erect a cost-of-compliance moat that favors incumbents with captive chemistry capabilities over contract-manufactured competitors.
For Market Incumbents: Extend dermatological certification partnerships into EMA and FDA dual pathways to defend against direct-to-consumer challengers. Deepen backward integration into ceramic coating deposition facilities to capture extended edge retention premiums. Lock in Indian barbershop procurement contracts before wholesale distribution consolidation accelerates. For New Entrants and Emerging Players: Launch via recyclable cartridge designs targeting EU extended producer responsibility frameworks as a first-mover positioning play. Exploit white space in medical device-classified surgical preparation systems where FDA oversight creates institutional hospital procurement access. Target UK heritage safety razor collector communities through artisanal scale production partnerships with Solingen grinding specialists. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by captive chemistry conglomerates seeking dermatological certification assets. Five-to-ten year viability favors manufacturers with REACH-registered supply chains and ceramic coating integration capabilities. Watch for BIS certification mandates in India as a signal for local metallurgy investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Integration | Extends functional edge life threefold for premium cartridge positioning in German and Japanese markets. |
| REACH Compliance Registration | ECHA substance disclosure mandates restructure cost-of-entry calculus for European manufacturing presence. |
| Direct-to-Consumer Subscription Launch | Automated replenishment algorithms bypass retail margin extraction in North American urban cohorts. |
| Medical Device Pathway Pursuit | FDA classification for surgical preparation opens hospital procurement with sterility documentation requirements. |
| Recyclable Cartridge Design Patent | EU packaging take-back mandates create first-mover advantage for circular economy compliance. |
Methodological Framework
Trade databases, customs records, and SEC filings formed the secondary backbone for supply chain mapping and competitive positioning assessment. Primary interviews with cartridge manufacturing executives, ECHA regulatory affairs specialists, Indian barbershop procurement managers, and dermatological testing laboratory directors validated secondary findings. Bottom-up volume triangulation across product type, material substrate, and end-use application converged with top-down macroeconomic trend analysis.
Historical trendline analysis tracked replacement cycle frequencies and coating adoption curves across the projection horizon. Segmentation dimensions modeled include product format, substrate composition, end-use context, and distribution channel structure. CAGRs derived from regression analysis of volume placements and value pool migration. Industry-specific forecast inputs incorporated REACH substance restriction timelines and ceramic coating cost decline trajectories.
Regulatory enforcement intensity, raw material price volatility, and subscription model churn rates are the dominant revision risks for forecast accuracy. Forecasts reflect assumptions about compliance cost absorption and coating technology diffusion. Practitioners should monitor ECHA substance list updates and BIS certification rollout pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Shaving Care Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Razor Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Latin America Hand Soap Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
360 Degree Toothbrush Market
Personal Grooming Products
Cotton Buds Market
Personal Grooming Products
Global Mobile Barber Shop Market
Personal Grooming Products
Electric Shavers Market