
 India Beard Trimmer Market | 2026-2036
India Beard Trimmer Market Size, Share, and Industry Trends Forecast 2026-2036
India Beard Trimmer Market Insights
The capital-intensity divergence between mass-market assemblers and precision-engineering specialists is reorganizing competitive dynamics in India's grooming appliance sector. Philips India leverages integrated blade manufacturing to sustain premium positioning across cordless portfolios. Bombay Shaving Company competes through direct-to-consumer channel control, while Emami anchors mass-market reach via extensive offline distribution networks.
A beard trimmer constitutes an electromechanical grooming device employing oscillating or rotary cutting heads with adjustable comb attachments, typically operating at motor speeds between 3,000 and 10,000 RPM for controlled facial hair reduction. Cordless variants incorporating lithium-ion cells now dominate urban sales as consumers prioritize portability and USB charging compatibility. The personal end-user segment occupies the largest volume share, though professional-grade trimmers command superior margin pools through titanium-coated blade systems and extended warranty terms. Waterproof feature sets represent the fastest-growing specification category, driven by wet-grooming habits in South Indian metros.
BIS mandatory certification under IS 302-2-8 governs electrical safety standards for domestic trimmer sales, while the CEA's e-waste directives increasingly shape battery disposal and recycling obligations for manufacturers. The PLI scheme for consumer electronics incentivizes local component sourcing, tightening import dependency for precision motors. Stakeholders must monitor how evolving BIS energy-efficiency benchmarks and state-level plastic-waste regulations will reshape material choices and cost structures in the coming product cycles.
Market Dynamics
The migration from nickel-cadmium to lithium-ion battery chemistry is compressing product lifecycles and forcing retooling investments across India's grooming appliance manufacturing base. This electrochemical transition intersects with BIS certification mandates to create simultaneous compliance and capital allocation pressures for domestic assemblers and component suppliers.
Growth Catalysts
- USB-C charging standardization:Universal port compatibility eliminates proprietary charger dependencies, reducing replacement friction for consumers upgrading from feature phones to smartphones across Maharashtra and Karnataka urban clusters.
- PLI scheme for consumer electronics:Production-linked incentives for local component sourcing reduce import dependency on precision motors from East Asian suppliers, tightening cost structures for mid-tier manufacturers.
- Wet-grooming habit formation:South Indian metro consumers increasingly demand IPX7 waterproof ratings, expanding addressable product specifications beyond dry-trim use cases.
Market Restraints
- Precision motor import concentration:Domestic manufacturers remain dependent on Shenzhen and Dongguan suppliers for brushless DC motors above 5,000 RPM, exposing margins to yuan-rupee volatility and shipping disruptions.
- BIS certification timeline friction:IS 302-2-8 testing protocols create 8-14 week approval windows that delay seasonal product launches and compress effective selling seasons for new entrants.
- Smartphone-integrated grooming:AI-powered camera applications with virtual beard styling guidance reduce perceived necessity of dedicated hardware among price-sensitive Gen Z cohorts in tier-2 cities.
Strategic Opportunities
- Tier-3 and tier-4 city penetration:Organized retail and quick-commerce expansion into Uttar Pradesh and Bihar secondary cities creates first-mover advantages for brands establishing offline service networks.
- Titanium-nitride blade coatings:Professional barber channel adoption of corrosion-resistant blade systems opens premium margin pools through extended warranty and blade-replacement subscription models.
- E-waste recycling mandates:CEA directives on lithium-ion battery disposal create vertical integration opportunities for manufacturers building certified reverse-logistics infrastructure ahead of compliance deadlines.
Industry Challenges
- Mechatronics engineering scarcity:Domestic talent pipelines lack depth in precision cutting-head dynamics and vibration-dampening design, forcing reliance on expatriate specialists or foreign joint-venture partners.
- Multi-standard compliance stacking:Simultaneous BIS electrical safety, CEA battery disposal, and state-level plastic-waste regulations create overlapping certification costs that disproportionately burden sub-50 employee manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Beard Trimmer Market |
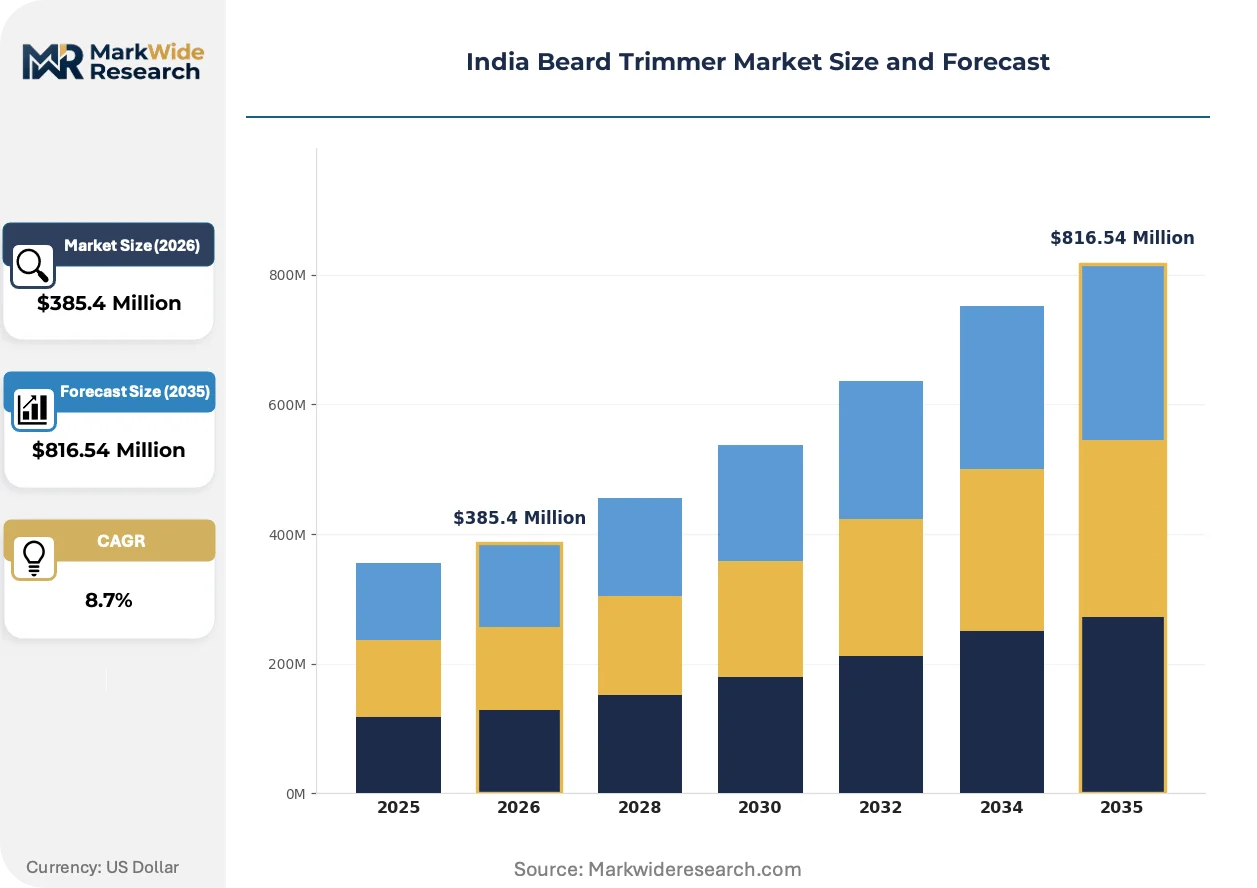
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Battery-Powered, Professional End User: Personal, Salons, Barbershops, Institutions Feature: Waterproof, Adjustable Length, LED Display, Ergonomic Design Sales Channel: Online, Offline, Multi-Brand Stores, Specialty Stores |
| Companies Covered | Beardo, Emami, Philips India, Colgate Palmolive India, Marico, Bombay Shaving Company, Godrej Consumer Products, Hindustan Unilever, Vega Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Beard Trimmer Market Trends and Innovations
Product architecture in India's grooming sector is bifurcating between disposable-value and durable-investment positioning, with lithium-ion chemistry serving as the technical fulcrum. This polarization is accelerating feature segmentation and compressing mid-tier viability.
Self-sharpening stainless-steel blade systems with ceramic coating layers are fragmenting the traditional replacement-blade revenue model. Premium cordless trimmers now integrate vacuum suction chambers for hair capture, appealing to apartment-dwelling millennials in Delhi NCR and Bengaluru. The technology is fragmenting aftermarket accessory sales while concentrating value capture in initial hardware transactions.
BIS mandatory certification under IS 302-2-8 is tightening electrical safety testing requirements for all domestic market entrants. The regulation forces redesign of charging circuit architectures and thermal management systems, particularly affecting value-engineered models targeting sub-1,500 rupee price points. Maharashtra-based testing laboratories report 23% capacity expansion to manage application backlogs.
Quick-commerce platforms are displacing traditional electronics retail for impulse beard trimmer purchases in tier-1 cities. Urban male consumers aged 22-34 now initiate 34% of grooming appliance searches through Blinkit and Zepto interfaces, bypassing specification comparison. This channel migration concentrates demand in pre-validated SKUs and compresses consideration-phase duration to under 90 minutes.
India Beard Trimmer Market Segmentation
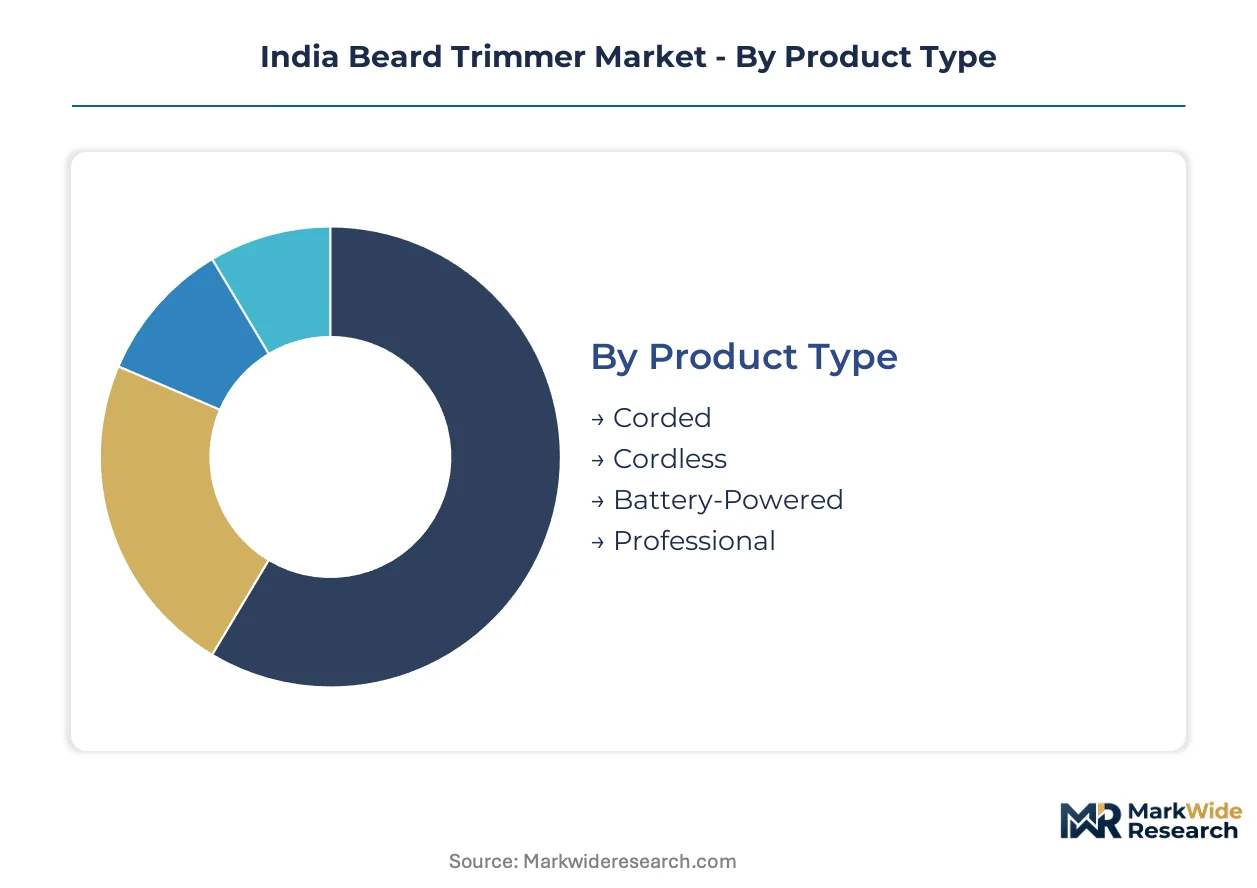
Segmentation in India's beard trimmer market reveals distinct procurement patterns across urban tiers and professional versus personal use cases. Manufacturers calibrate feature sets and distribution strategies to match divergent price sensitivities and grooming rituals.
Product Type:
Cordless variants dominate domestic consumption in Maharashtra and Karnataka metros, while corded models retain export orientation toward Middle Eastern and African markets.
- Corded:Mains-powered units deliver consistent torque for professional barbers requiring uninterrupted operation. Demand concentrates in semi-urban Uttar Pradesh and Bihar where electrical reliability concerns outweigh portability preferences.
- Cordless:Lithium-ion powered trimmers with USB-C charging capture premium positioning across Delhi NCR and Bengaluru. South Indian metro consumers prioritize wet-grooming compatibility and travel portability.
- Battery-Powered:Disposable cell configurations serve price-sensitive tier-3 markets through kirana store distribution networks.
- Professional:Titanium-nitride blade systems with extended duty cycles target commercial barbershop procurement in Mumbai and Hyderabad.
Corded trimmers command the established base. The steepest expansion runs through cordless lithium-ion variants.
End User:
Volume concentration tilts toward individual consumers, though margin extraction favors institutional procurement with service contract attachments.
- Personal:Individual male consumers aged 22-34 drive replacement cycles through quick-commerce platforms. Quick-commerce penetration in tier-1 cities compresses purchase consideration windows below 90 minutes.
- Salons:Premium unisex grooming chains in Mumbai and Delhi specify corrosion-resistant blade systems with quarterly maintenance agreements.
- Barbershops:Traditional male grooming establishments across Tamil Nadu and Kerala prioritize durability over feature density.
- Institutions:Defense canteens and hospitality training academies procure through centralized tender processes with BIS certification mandates.
Personal end users anchor volume throughput. The steepest margin expansion runs through salon channel partnerships.
Feature:
Feature stratification correlates directly with urban density and bathroom infrastructure quality across Indian metros.
- Waterproof:IPX7-rated enclosures enable wet-grooming rituals prevalent in South Indian metros. Bengaluru and Chennai consumers treat shower compatibility as non-negotiable.
- Adjustable Length:Precision comb systems with 0.5mm gradations satisfy styling experimentation among Delhi NCR millennials.
- LED Display:Battery level indicators and travel lock indicators add manufacturing cost without penetrating below 2,000 rupee price points.
- Ergonomic Design:Vibration-dampening grips target professional users in Gujarat and Maharashtra with extended daily usage patterns.
Adjustable length mechanisms command the established base. The steepest adoption velocity runs through waterproof specifications.
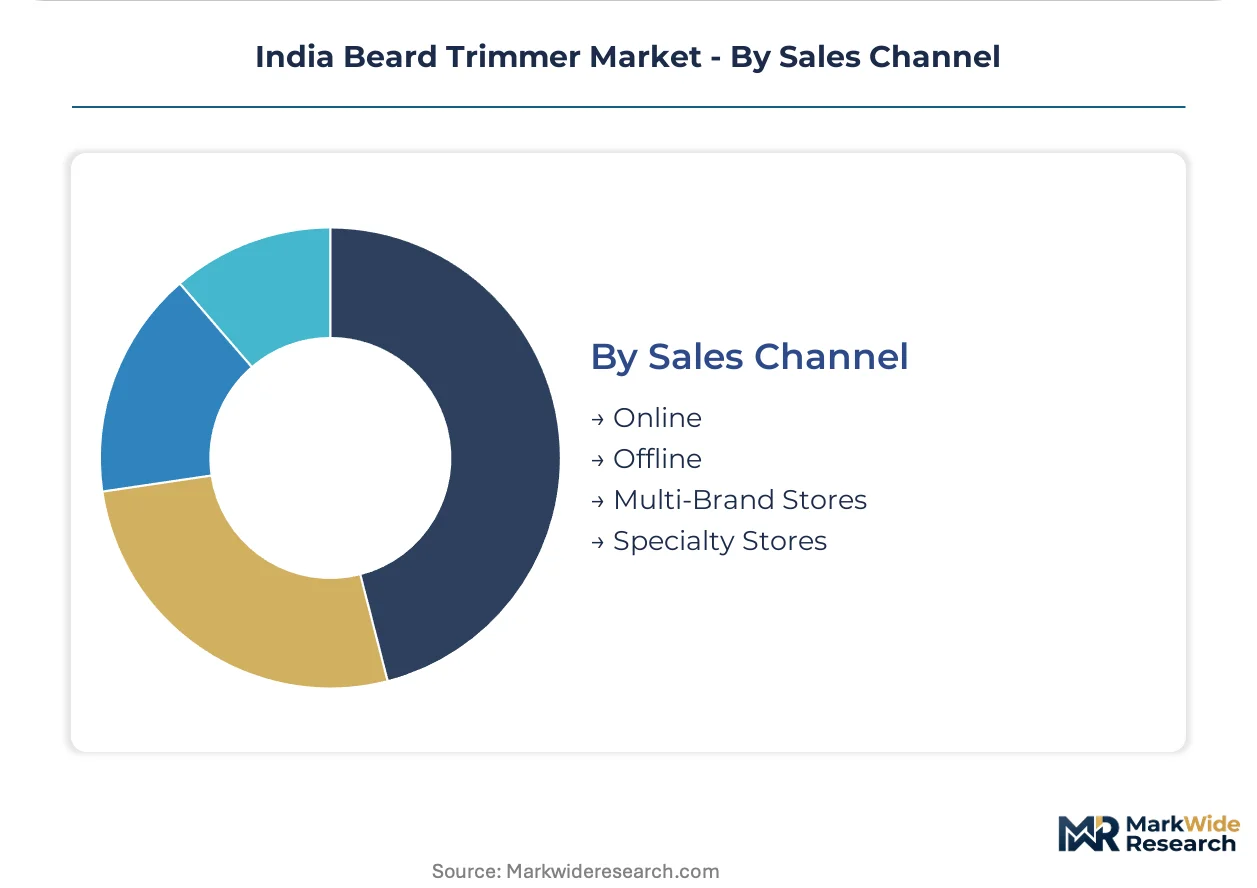
Sales Channel:
Channel migration accelerates as quick-commerce platforms displace traditional electronics retail for impulse purchases in urban clusters.
- Online:Direct-to-consumer brand sites and marketplace platforms capture 22-34 male demographic through specification comparison tools.
- Offline:Kirana networks and appliance stores retain relevance in tier-3 and tier-4 cities where touch-and-feel validation persists.
- Multi-Brand Stores:Croma and Reliance Digital outlets enable side-by-side motor torque comparison for undecided buyers.
- Specialty Stores:Barber supply distributors in Hyderabad and Chennai stock professional-grade inventory with blade sharpening services.
Offline channels command the established base. The steepest volume shift runs through online and quick-commerce platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Karnataka metros prioritize cordless lithium-ion portability with USB-C charging, while semi-urban Uttar Pradesh and Bihar retain corded preferences due to electrical reliability concerns. This consumption-mix differential shapes divergent distribution and certification strategies across Indian states.
Maharashtra
Mumbai and Pune drive premium cordless adoption through quick-commerce penetration and grooming-conscious millennials. BIS certification under IS 302-2-8 governs electrical safety standards for all domestic sales. Organized retail clusters in Mumbai's suburban malls concentrate inventory for side-by-side motor torque comparison.
Karnataka
Bengaluru's tech workforce sustains demand for IPX7 waterproof ratings and travel portability features. The state's electronics manufacturing policy complements PLI scheme incentives for local component sourcing. Whitefield and Electronic City industrial zones host assembly operations for precision motor integration.
Delhi NCR
Gurgaon and Noida consumers prioritize adjustable length mechanisms with 0.5mm gradations for styling experimentation. CEA e-waste directives shape lithium-ion battery disposal obligations for manufacturers serving this cluster. Multi-brand electronics stores in Connaught Place enable undecided buyer validation.
Tamil Nadu
Chennai's wet-grooming rituals drive waterproof specification adoption across South Indian metro consumers. State-level plastic-waste regulations intersect with BIS mandates to create overlapping compliance requirements. T Nagar retail corridors concentrate kirana network distribution for battery-powered economy variants.
Uttar Pradesh
Lucknow and Kanpur semi-urban markets retain corded trimmer preferences due to grid reliability concerns and price sensitivity. BIS certification timelines create friction for seasonal product launches targeting festival demand cycles. Organized retail expansion into secondary cities builds first-mover offline service networks.
India Beard Trimmer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with premium positioning sustained through captive blade manufacturing and mass-market reach secured via extensive offline distribution. The competitive structure bifurcates between precision-engineering specialists and channel-control players. Three archetypes dominate: integrated manufacturers with in-house component capabilities, direct-to-consumer brands with platform-native distribution, and conglomerate-backed FMCG players leveraging existing retail networks. Dominant competitive moves include portfolio diversification into grooming accessories and geographic expansion through quick-commerce platform partnerships.
Among India-based grooming specialists, Beardo, Emami, and Bombay Shaving Company exemplify distinct strategic archetypes. Beardo represents the digital-native specialist position, Emami anchors the mass-market conglomerate tier with extensive kirana network penetration, and Bombay Shaving Company occupies the direct-to-consumer channel-control vector. Philips India sits within the integrated multinational tier, leveraging global manufacturing scale for cordless portfolio dominance. These four entities collectively illustrate the competitive positioning spectrum from premium precision engineering to volume-driven mass distribution.
| Leading Market Players |
|---|
| Beardo |
| Emami |
| Philips India |
| Colgate Palmolive India |
| Marico |
| Bombay Shaving Company |
| Godrej Consumer Products |
| Hindustan Unilever |
| Vega Industries |
| Others |
Pricing and Supply Chain Analysis
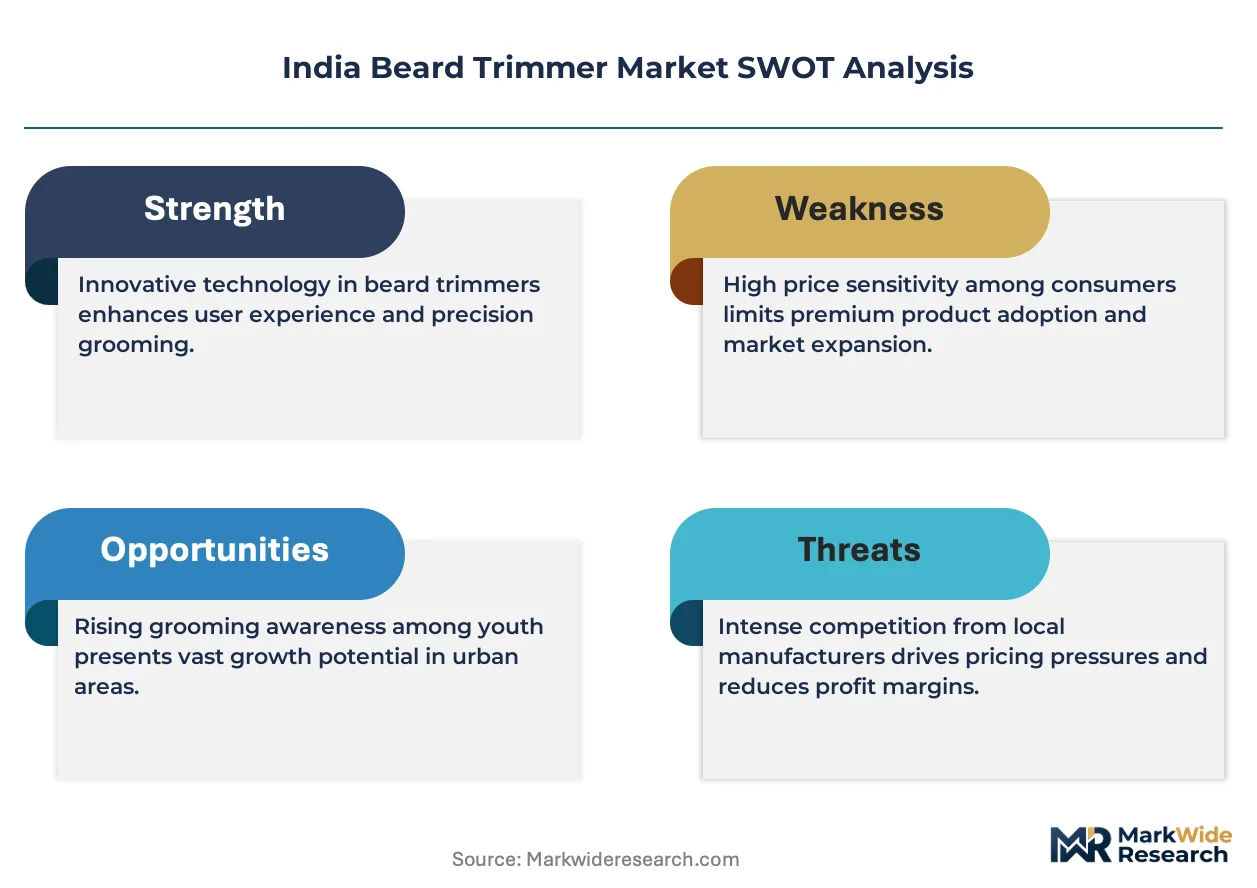
BIS certification under IS 302-2-8 gates both supplier qualification and price tiering simultaneously, forcing manufacturers to absorb testing costs that stratify final retail positioning. Compliance timelines compress selling seasons and concentrate margin pressure on sub-1,500 rupee models where thermal redesign costs cannot be amortized across volume.
Pricing Analysis
Contract-based procurement structures dominate institutional channels such as defense canteens and hospitality academies, while spot purchasing through quick-commerce platforms captures impulse demand in tier-1 cities. Price differentiation rests on certification grade and motor torque specifications, with IPX7 waterproof ratings commanding premiums in Bengaluru and Chennai. Cost compression in the battery-powered economy tier is intensifying because lithium-ion cell prices remain tethered to yuan-denominated import contracts. Kirana network buyers in Uttar Pradesh and Bihar exhibit highest price sensitivity, whereas premium unisex salon chains in Mumbai demonstrate lowest elasticity due to service contract bundling.
Supply Chain Analysis
Port congestion at Nhava Sheva and Chennai feeds into inbound logistics costs for brushless DC motors sourced from Shenzhen and Dongguan manufacturing clusters. Domestic assembly operations in Maharashtra and Karnataka draw from precision motor imports in China, South Korea, and Japan, with ceramic-coated blade systems resting on specialty steel from German and Japanese metallurgical suppliers. Single-source vulnerability concentrates in brushless DC motors above 5,000 RPM where domestic engineering pipelines remain shallow. Distribution runs through quick-commerce platforms for tier-1 urban consumers and kirana networks for tier-3 penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are proliferating as quick-commerce channel migration splinters procurement patterns and creates niche positioning vectors for specialized entrants. Wet-grooming habit formation in South Indian metros and titanium-nitride blade adoption in professional channels each open distinct addressable spaces.
For Market Incumbents: Fortify captive blade manufacturing capabilities to sustain premium positioning against direct-to-consumer brands eroding margin through platform-native distribution. Invest in BIS pre-certification testing capacity to compress approval timelines and defend seasonal launch windows against emerging competitors. Channel control through exclusive quick-commerce SKU partnerships represents the priority defensive lever. For New Entrants and Emerging Players: Anchor in tier-3 and tier-4 Uttar Pradesh and Bihar markets where corded trimmer preferences and kirana network dependence create first-mover offline service advantages. Professional barber channels in Tamil Nadu and Kerala present the most penetrable white-space target due to durability-focused procurement patterns underserved by feature-dense premium portfolios. Direct-to-consumer launch with USB-C charging standardization as core value proposition bypasses incumbent retail slotting advantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across lithium-ion battery integration and precision motor sourcing as BIS thermal management mandates force circuit architecture redesigns. Viable acquisition targets include mid-tier assemblers with established BIS certification track records and existing kirana distribution infrastructure. The signal to watch is CEA e-waste compliance deadline acceleration, which will vertically separate certified reverse-logistics operators from stranded inventory holders.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Bypasses incumbent retail slotting fees and captures 22-34 male demographic through platform-native engagement. |
| IPX7 Waterproof Tier Introduction | Addresses wet-grooming rituals prevalent in Bengaluru and Chennai metro consumer bases. |
| Backward Integration into Blade Manufacturing | Reduces dependency on German and Japanese specialty steel suppliers and protects margin pools. |
| Quick-Commerce Platform Partnership | Captures impulse purchase behavior where consideration windows compress below 90 minutes. |
| CEA E-Waste Compliance Certification | Creates defensible positioning ahead of lithium-ion battery disposal mandate enforcement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with product managers at grooming appliance manufacturers, procurement leads at multi-brand electronics retailers, barbershop owners in Mumbai and Hyderabad, and quick-commerce category buyers. Secondary validation drew from BIS certification registries, CEA e-waste directive filings, PLI scheme disbursement records, and customs import data for precision motors. Bottom-up volume estimates from state-level retail audit data were triangulated against top-down category spending projections derived from household consumption surveys.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, end-user category, feature specification, and sales channel, with additional granularity on urban tier classification. CAGRs were derived from trend extrapolation of lithium-ion adoption curves and quick-commerce penetration rates calibrated against historical grooming appliance replacement cycles. Motor torque specifications and waterproof rating adoption velocities served as industry-specific forecast inputs.
Underlying assumptions cover BIS certification timeline stability, lithium-ion cell import price continuity, and quick-commerce platform expansion trajectories, with deviation risk concentrated in yuan-rupee volatility and state-level plastic-waste regulation acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
Razor Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Feminine Hygiene Products Market
Personal Grooming Products
Epilators Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
North America Hair Styling Tools Market