
 Smart Water Bottle Market | 2026-2036
Smart Water Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Water Bottle Market Outlook
Fitness enthusiast adoption is broadening the addressable base for smart hydration hardware. Hidrate Spark leverages sensor-enabled tracking to anchor its position in athletic and clinical wellness channels. LARQ competes through UV-C purification technology leadership, while WATER.IO extends its footprint via app-connectivity platforms that integrate with third-party health ecosystems.
A smart water bottle is a portable beverage container incorporating electronic sensors, Bluetooth modules, and rechargeable power systems to monitor liquid intake, temperature, and consumption patterns. Insulated variants with embedded heating or cooling elements dominate premium pricing tiers due to higher material costs and energy management complexity. Sensor-enabled technology leads unit shipments, though app connectivity represents the fastest-expanding segment as users demand seamless data synchronization with Apple Health and Garmin Connect. Fitness enthusiasts constitute the most concentrated end-user pool, while online retail channels capture the largest volume share through direct-to-consumer subscription models.
The FDA regulates claims related to hydration health outcomes, constraining how manufacturers market clinical benefits. FCC certification governs Bluetooth and wireless transmission standards, adding compliance costs for entrants. California's Proposition 65 and EU REACH restrictions on battery materials and plastics are forcing redesigns of internal electronics housings. Stakeholders must weigh whether to prioritize sensor accuracy investments or sustainability certifications as procurement criteria diverge across North American and European retail channels.
Market Dynamics
Fitness tracking ecosystems are compressing adoption cycles for sensor-enabled hydration hardware, forcing manufacturers to prioritize Bluetooth synchronization accuracy over standalone device functionality. This structural pull from connected wellness platforms is reshaping R&D allocation across the competitive set.
Growth Catalysts
- EU Green Deal compliance mandates:REACH restrictions on battery materials and plastics are accelerating material innovation cycles, creating first-mover advantages for manufacturers with recyclable electronics housings already in production.
- Clinical wellness channel expansion:Hospitals and outpatient clinics are integrating hydration monitoring into patient recovery protocols, opening institutional procurement pathways previously closed to consumer hardware.
- Apple Health and Garmin Connect API openness:Third-party health platform integration is lowering friction for fitness enthusiasts seeking unified biometric dashboards.
Market Restraints
- Lithium-ion cell cost volatility:Rechargeable power systems constitute 18-25% of bill-of-materials exposure, with spot price fluctuations in cobalt and nickel concentrates squeezing margin structures for mid-tier producers.
- FCC certification timelines:Bluetooth module approval processes add 4-6 months to product launch schedules, creating working capital intensity for entrants without established regulatory affairs functions.
- Reusable insulated bottle substitution:Non-electronic vacuum-flask alternatives at $25-40 price points capture price-sensitive consumers unwilling to absorb smart-feature premiums.
Strategic Opportunities
- Germany's national digital health infrastructure:DiGA (Digital Health Applications) fast-track approval creates a regulatory pathway for hydration-tracking software to secure prescription reimbursement status.
- UV-C LED convergence with IoT sensors:Purification hardware paired with consumption analytics addresses two distinct user pain points in a single SKU, expanding addressable use cases beyond fitness into travel and outdoor recreation.
- Direct-to-employer corporate wellness channels:Self-insured enterprises are adding connected hydration devices to preventive health benefit catalogs, bypassing traditional retail margin structures entirely.
Industry Challenges
- Embedded systems firmware talent scarcity:Bluetooth Low Energy stack optimization and power management algorithm development require specialized skill sets concentrated in semiconductor hubs, forcing manufacturers into costly coastal hiring or outsourced development partnerships.
- California Proposition 65 labeling complexity:Warning requirements for battery housings and electronic components create packaging design constraints that delay regional launch timelines and inflate legal review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Water Bottle Market |
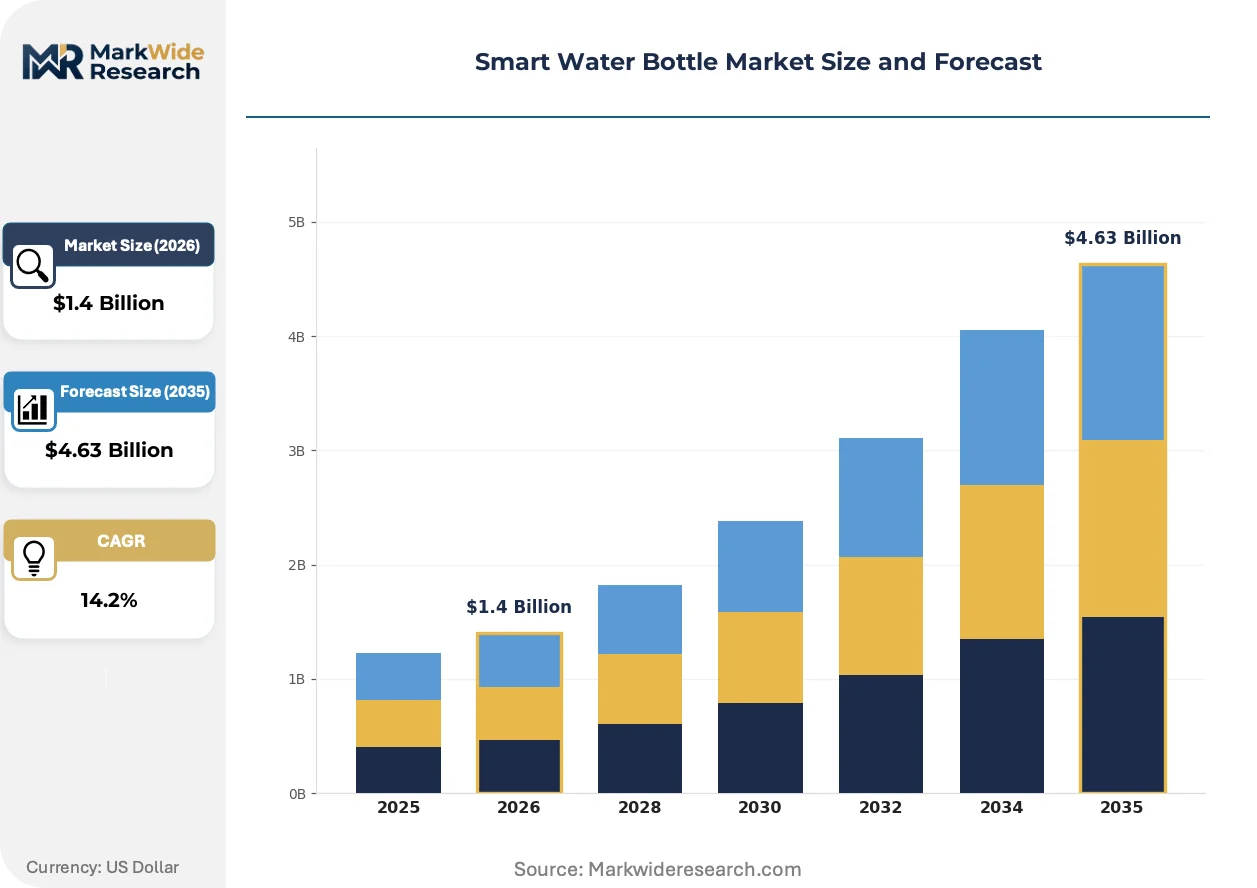
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.63 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated, Non-Insulated, Collapsible, Multi-Function Technology: Sensor-Enabled, Bluetooth, Hydration Reminder, App Connectivity End User: Fitness Enthusiasts, Students, Professionals, Outdoor Adventurers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Sports Outlets |
| Companies Covered | Thermos, LifeFuels, Hidrate Spark, EQUA, NOERDEN, LARQ, WATER.IO, CrazyCap, WaterH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Water Bottle Market Strategic Shifts
Sensor miniaturization and edge computing migration are collapsing the physical footprint required for meaningful hydration analytics, enabling form-factor experimentation previously constrained by PCB area requirements.
Capacitive liquid-level sensing is automating intake measurement without mechanical floats or optical components that degrade with residue buildup. Fitness enthusiasts and clinical trial coordinators are adopting these solid-state configurations for reliability-critical deployments. This automation is compressing warranty claim rates and extending replacement cycles, pressuring manufacturers to develop recurring revenue streams through subscription analytics rather than hardware refresh.
REACH Annex XVII restrictions on phthalates and heavy metals in plastics are forcing redesigns of internal electronics housings and sealing gaskets. Manufacturers with EU-market exposure are accelerating migration to bio-based TPU and recycled ocean-bound PET. Premium insulated variants with full material traceability are capturing shelf space in German and French retail channels where sustainability certifications influence assortment decisions.
Subscription-based hydration coaching is displacing one-time hardware transactions in direct-to-consumer channels. Wellness influencers and registered dietitians are bundling personalized intake protocols with device purchases, capturing recurring revenue streams that hardware margins alone cannot sustain. This model concentrates in United States and United Kingdom markets where telehealth integration and HSA-eligible spending create favorable reimbursement tailwinds.
Smart Water Bottle Market Segmentation
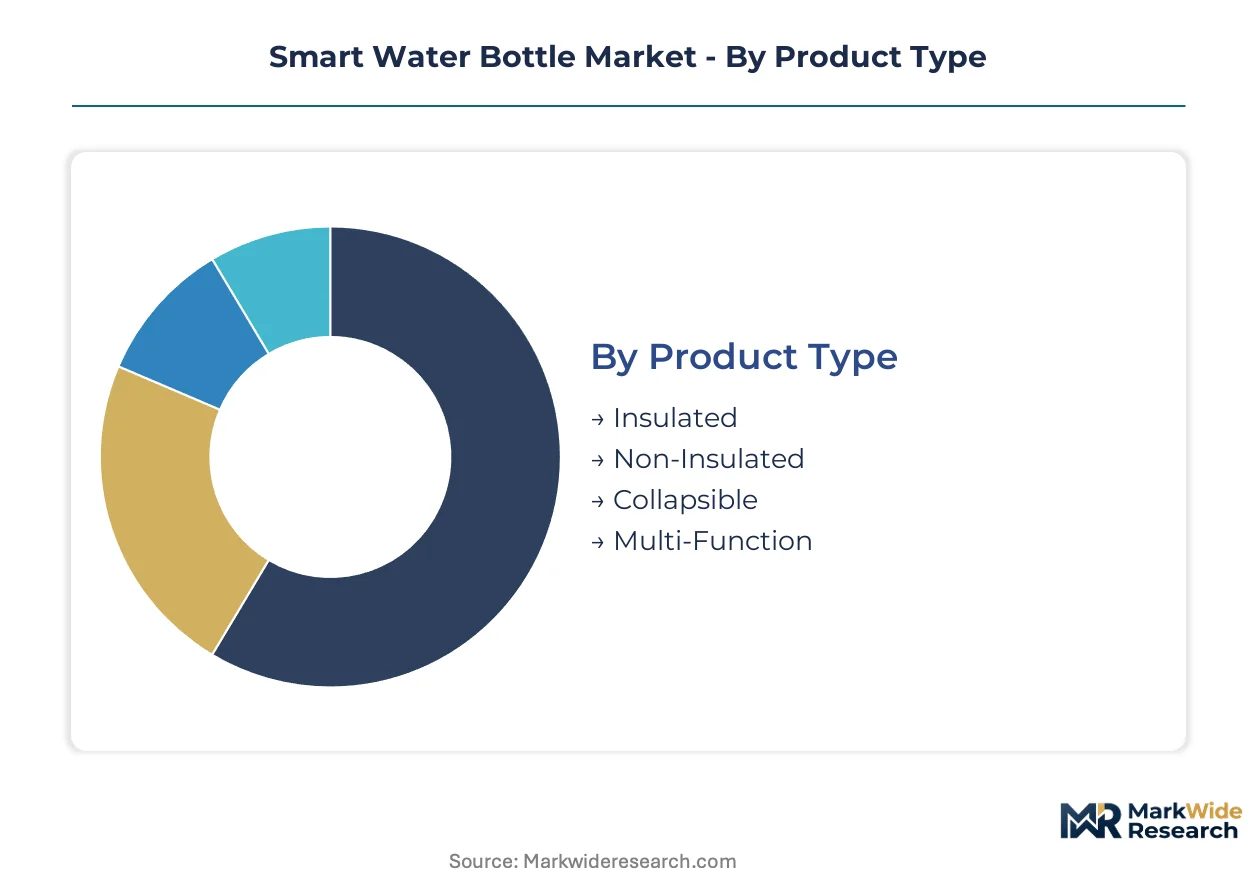
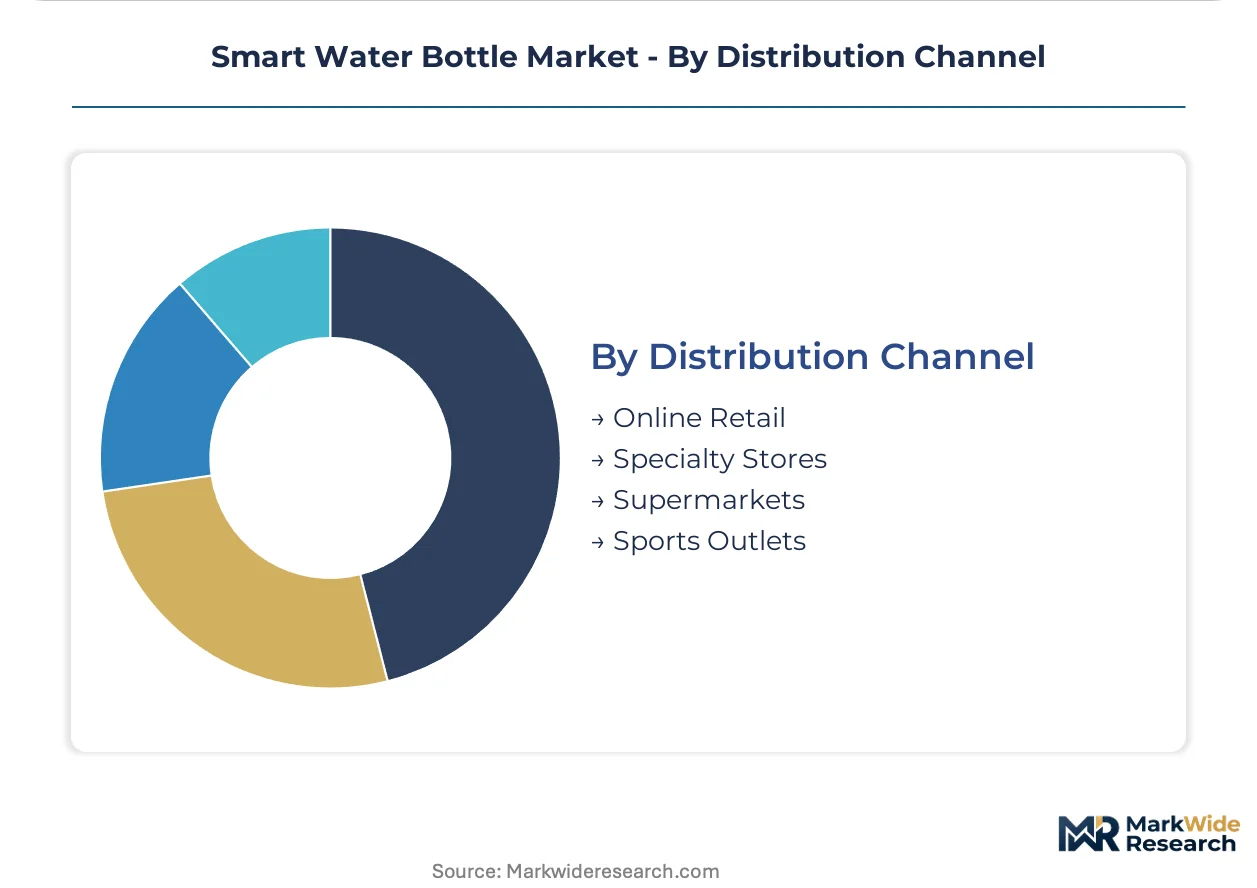
Smart water bottle manufacturers configure product portfolios across four distinct axes. Technology integration levels and distribution channel economics determine margin capture, while end-user specialization dictates sensor calibration and app feature sets.
Product Type:
Material construction and thermal management specifications create tiered price positioning across the hardware spectrum.
- Insulated:Double-wall vacuum construction with embedded heating or cooling elements commands premium positioning. Demand concentrates among fitness enthusiasts in the United States seeking temperature-stable hydration during extended training sessions, with higher material costs and energy management complexity justifying elevated price tiers.
- Non-Insulated:Single-wall designs prioritize sensor accessibility and reduced unit weight over thermal performance. Students and professionals in Germany favor these configurations for desk-based hydration tracking where temperature maintenance adds unnecessary cost.
- Collapsible:Silicone or TPU-based foldable structures target space-constrained users. Outdoor adventurers in Switzerland and Austria select these for multi-day trekking where pack volume limits apply.
- Multi-Function:Hybrid units combining purification, temperature control, and intake monitoring in single chassis. Travelers in Japan and South Korea demonstrate strongest uptake for airport and hotel use cases.
Mature deployment sits with Insulated variants. Newer deployment is concentrated in Multi-Function configurations.
Technology:
Connectivity architecture and data processing location determine user experience fidelity and battery life trade-offs.
- Sensor-Enabled:Capacitive liquid-level sensing and accelerometer-based tilt detection automate intake measurement without mechanical components. Fitness enthusiasts in the United States and clinical trial coordinators in the United Kingdom adopt these solid-state configurations for reliability-critical deployments where warranty claim minimization matters.
- Bluetooth:Low-energy wireless modules enable smartphone synchronization for data logging. FCC certification timelines and module cost volatility constrain margin structures for mid-tier producers targeting price-sensitive European consumers.
- Hydration Reminder:On-device LED or vibration alerts triggered by elapsed time or intake deficits. Students in India and Brazil respond to these entry-level features where smartphone penetration remains incomplete.
- App Connectivity:Full API integration with Apple Health, Garmin Connect, and third-party wellness platforms. This segment climbs the fastest as unified biometric dashboards become non-negotiable for health-conscious consumers in premium markets.
Volume concentration remains with Sensor-Enabled hardware. Steepest expansion trajectory belongs to App Connectivity.
End User:
Usage context and biometric sophistication requirements segment demand across distinct behavioral profiles.
- Fitness Enthusiasts:The most concentrated end-user pool, demanding precise sweat-loss estimation and electrolyte tracking integration. Athletes in Australia and the United States drive replacement cycles as training load analytics become standard.
- Students:Price-sensitive cohort prioritizing basic intake reminders and durable construction. Campus-based demand in Canada and the United Kingdom concentrates during back-to-school procurement windows.
- Professionals:Desk-bound workers seeking subtle hydration prompts without workplace disruption. Corporate wellness programs in Germany and the Netherlands subsidize these purchases as preventive health investments.
- Outdoor Adventurers:Ruggedized requirements including GPS integration and extended battery life. Trekkers in New Zealand and Norway prioritize reliability over connectivity sophistication.
Procurement volume peaks with Fitness Enthusiasts. Emerging demand concentrates among Professionals via employer-sponsored channels.
Distribution Channel:
Channel selection determines margin retention and customer relationship depth across the purchase lifecycle.
- Online Retail:Direct-to-consumer subscription models capture largest volume share. United States and United Kingdom markets demonstrate strongest recurring revenue conversion as telehealth integration and HSA-eligible spending create favorable reimbursement conditions.
- Specialty Stores:Curated assortment with staff consultation supports premium positioning. Running and cycling shops in France and Italy anchor brand credibility among serious athletes.
- Supermarkets:Mass-market penetration for entry-level SKUs with limited connectivity. Price-sensitive consumers in Spain and Poland select these for gift purchases or trial adoption.
- Sports Outlets:Equipment retailers bundling hydration hardware with athletic apparel. Decathlon and similar chains in Belgium and Sweden drive seasonal volume spikes.
Revenue concentration favors Online Retail. Physical channel expansion is accelerating in Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shenzhen and Dubai concentrate electronics assembly for connected hydration hardware, drawing contract manufacturers through tariff exemptions and streamlined customs clearance. These zones anchor supply networks serving premium consumer markets in North America and Western Europe.
United States
Corporate wellness programs at self-insured employers drive institutional procurement of connected hydration devices as preventive health investments. FDA oversight of hydration-related health claims constrains direct-to-consumer marketing, pushing manufacturers toward HSA-eligible positioning. Austin and Boulder anchor startup clusters where sensor-enabled hardware developers integrate with Apple Health and Garmin Connect ecosystems.
Germany
DiGA fast-track approval creates regulatory pathways for hydration-tracking software to secure prescription reimbursement status. EU REACH restrictions on battery materials and plastics force redesigns of internal electronics housings, accelerating migration to bio-based TPU. Berlin and Munich concentrate R&D operations for manufacturers pursuing sustainability certifications that influence retail assortment decisions.
Japan
Travelers in metropolitan centers demonstrate strongest uptake for multi-function units combining purification and intake monitoring for airport and hotel use cases. METI efficiency standards for small electronics shape power management requirements for rechargeable systems. Osaka-Kobe manufacturing corridors specialize in miniaturized sensor modules for capacitive liquid-level detection.
United Kingdom
Telehealth integration and HSA-eligible spending create favorable reimbursement tailwinds for subscription-based hydration coaching models. Clinical trial coordinators adopt solid-state sensor configurations for reliability-critical deployments in patient recovery protocols. Cambridge and Oxford clusters concentrate firmware talent for Bluetooth Low Energy stack optimization.
Australia
Fitness enthusiasts drive replacement cycles as training load analytics become standard in athletic performance monitoring. TGA oversight of therapeutic claims shapes how manufacturers position hydration monitoring for clinical applications. Melbourne and Sydney anchor distribution hubs serving outdoor adventurers in New Zealand and Southeast Asian markets.
Smart Water Bottle Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among sensor-integrated specialists while volume production flows through OEM arrangements. The vendor base organizes around three archetypes: purification-technology leaders, app-connectivity platform builders, and sensor-hardware specialists. Consolidation pressure concentrates among mid-tier producers squeezed by lithium-ion cost volatility and FCC certification timelines. Dominant competitive moves include strategic partnerships with third-party health platforms and portfolio diversification into corporate wellness channels.
Among purification-technology specialists, LARQ occupies a position exemplifying UV-C LED convergence with consumption analytics, while WATER.IO represents the app-connectivity archetype through API integration with unified biometric dashboards. Hidrate Spark anchors the sensor-hardware tier, exemplifying solid-state configurations adopted by fitness enthusiasts and clinical coordinators for reliability-critical deployments. These three companies collectively illustrate the strategic vectors—purification, connectivity, and sensor accuracy—through which manufacturers differentiate positioning across premium consumer and institutional procurement channels.
| Leading Market Players |
|---|
| Thermos |
| LifeFuels |
| Hidrate Spark |
| EQUA |
| NOERDEN |
| LARQ |
| WATER.IO |
| CrazyCap |
| WaterH |
| Others |
Value Chain & Pricing Dynamics
Embedded systems firmware talent scarcity in Shenzhen and Austin creates labor-cost differentials that widen pricing-tier spreads between premium sensor-integrated units and entry-level hydration reminder SKUs. Manufacturers absorbing coastal hiring premiums for Bluetooth Low Energy specialists pass these costs through to insulated multi-function variants, while outsourced development partnerships enable mid-tier producers to defend standard-tier positioning.
Pricing Analysis
Short lead-time premiums for FCC-certified Bluetooth modules command 15-25% markups over spot inventory with extended certification timelines. Three-tier pricing structure across premium, standard, and economy levels differentiates by sensor accuracy grade and app connectivity depth, with FCC certification tier and volume scale as primary price drivers. Cost compression in mid-tier Bluetooth-enabled units is intensifying because lithium-ion cell cost volatility squeezes margin structures. Students in India and Brazil demonstrate highest price sensitivity, while fitness enthusiasts in the United States absorb premium positioning for Apple Health integration.
Supply Chain Analysis
Dual-sourcing requirements for lithium-ion cells and capacitive sensor modules mandate multi-supplier qualification across Chinese, South Korean, and Japanese battery manufacturers. Raw material dependencies center on cobalt and nickel concentrates, PCB substrates, and bio-based TPU housings. Single-source vulnerability in miniaturized sensor module production concentrates risk in Osaka-Kobe manufacturing corridors. Distribution runs through direct-to-consumer online retail channels capturing largest volume share, with specialty stores anchoring premium brand credibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained with embedded systems firmware talent scarcity propping pricing power for manufacturers with captive development capabilities.
For Market Incumbents: Anticipate margin compression from non-electronic vacuum-flask substitutes by accelerating backward integration into sensor module production and securing exclusive API partnerships with Garmin Connect. Prioritize REACH-compliant bio-based TPU certification to defend shelf space in German and French retail channels where sustainability credentials determine assortment decisions. For New Entrants and Emerging Players: The $25-40 gap between premium insulated variants and basic hydration reminder SKUs offers white-space entry through employer-sponsored corporate wellness channels in Germany and the Netherlands. Target professionals in desk-based hydration tracking applications with subscription-based coaching bundles, leveraging telehealth integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with sensor-hardware specialists given DiGA fast-track approval creating prescription reimbursement pathways in Germany. Long-term viability over a multi-year window favors manufacturers with vertical integration into capacitive liquid-level sensing and established FCC regulatory affairs functions. Watch for lithium-ion cost stabilization as the inflection signal for margin expansion in mid-tier producers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Transition | EU Green Deal mandates accelerate migration to bio-based TPU and recycled ocean-bound PET housings. |
| DiGA Fast-Track Approval Pursuit | Germany's digital health infrastructure creates prescription reimbursement status for hydration-tracking software. |
| Corporate Wellness Channel Bypass | Direct-to-employer procurement eliminates traditional retail margin structures for preventive health investments. |
| UV-C LED Convergence Development | Purification hardware paired with consumption analytics expands addressable use cases into travel segments. |
| Subscription Analytics Platform Launch | Recurring revenue streams from personalized intake protocols displace one-time hardware transactions. |
Study Parameters
Document review covered SEC filings, EU REACH regulatory databases, and customs trade records, complemented by interviews with product development executives at sensor-hardware manufacturers, regulatory affairs specialists, and procurement managers at corporate wellness programs. Primary fieldwork engaged firmware engineers specializing in Bluetooth Low Energy stack optimization, category buyers at specialty running retailers, and hospital biomedical engineers evaluating clinical trial deployments. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segmentation outputs across product type, technology integration level, end-user archetype, and distribution channel fed into growth rate derivations using historical adoption curves for connected wellness devices. Modeled variables included FCC certification timeline impacts on launch schedules, lithium-ion spot price volatility coefficients, and regional sustainability certification penetration rates. The analytical framework incorporated patient recovery protocol adoption rates in outpatient clinics and fitness enthusiast replacement cycle dynamics.
Inputs from EU regulatory filings and hospital procurement databases were available through the study window; gaps in real-time lithium-ion contract pricing introduce uncertainty bands around bill-of-materials projections. Forecasts reflect assumptions regarding DiGA approval timelines and Apple Health API continuity. Deviation in REACH Annex XVII enforcement intensity or cobalt concentrate supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Global Hairbrush Market
Personal Grooming Products
Disposable Razor Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Organic and Natural Tampons Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Antibacterial Soap Market
Personal Grooming Products
Electric Shavers Market
Personal Grooming Products
Disposable Razor Blades Market
Personal Grooming Products
Cotton Buds Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Smart Hairbrush Market
Personal Grooming Products
Global Away-From-Home Tissue and Hygiene Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
Disposable Shower Caps Market