
 Electric Tooth Polisher Market | 2026-2036
Electric Tooth Polisher Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Tooth Polisher Market Analysis
Ultrasonic piezoelectric actuator integration is tilting electric tooth polisher engineering toward higher-frequency oscillation with lower power draw. Philips Sonicare leverages proprietary sonic motor architecture to sustain premium positioning across professional and retail channels. Oral-B competes through oscillating-rotating brush head systems that anchor its dental clinic partnerships. BURST Oral Care differentiates via direct-to-consumer subscription models that control recurring revenue streams.
An electric tooth polisher is a motorized oral hygiene instrument employing rotating or oscillating abrasive heads, typically operating at 3,000–40,000 strokes per minute, designed for clinical or consumer removal of extrinsic stains, plaque biofilm, and surface discoloration. Cordless and rechargeable configurations now dominate unit economics as lithium-ion cell density improves and water ingress protection reaches IPX7 ratings. Dental clinics command the steepest margin pools within end-user segmentation due to sterilization-grade construction requirements and bulk consumable attaché sales. Smart technology features including pressure sensors and Bluetooth connectivity represent the fastest-expanding feature category as oral health data monetization strategies mature.
FDA 510(k) clearance requirements shape device commercialization timelines and clinical claim substantiation in the United States, while the EU Medical Device Regulation imposes notified body conformity assessment for professional-grade polishers entering European markets. ISO 13485 quality management certification functions as a baseline qualifier for original equipment manufacturer partnerships and private-label supply agreements. Stakeholders must monitor evolving battery transportation regulations and biocompatibility testing protocols as material substitution accelerates.
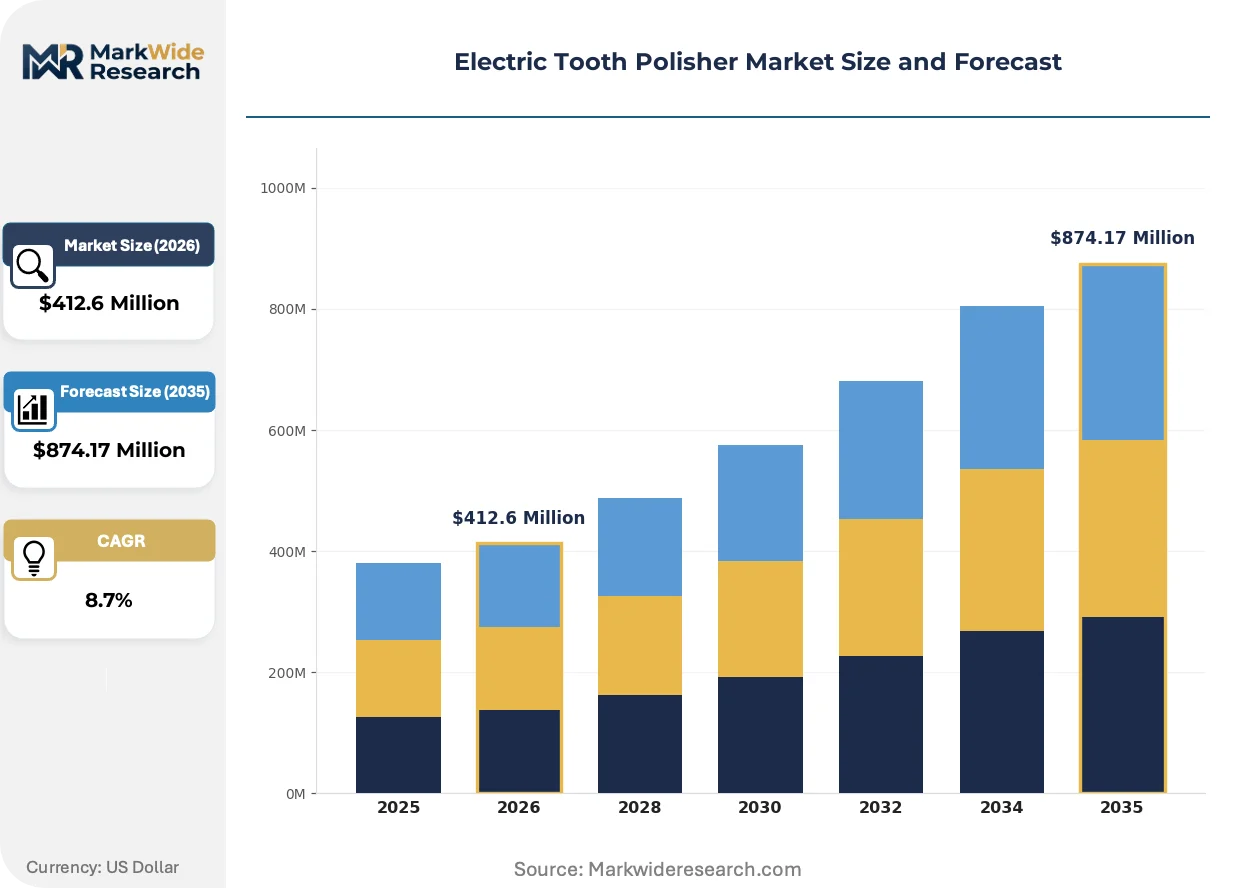
Market Dynamics
The electric tooth polisher market is restructuring around lithium-ion battery platform consolidation, as nickel-cadmium obsolescence forces manufacturers to redesign entire product architectures around energy density gains and IPX7 ingress protection standards.
Growth Catalysts
- EU Medical Device Regulation (MDR):Professional-grade device certification requirements are accelerating sterilization-grade construction upgrades across European dental clinic procurement, pulling premium unit sales upward.
- Per-capita dental expenditure concentration:The United States, Germany, and Japan collectively concentrate reimbursement frameworks that support premium device procurement by institutional buyers.
- Ultrasonic piezoelectric actuators:Higher-frequency oscillation architectures are reducing power draw while improving stain removal efficacy, expanding clinical application scope.
Market Restraints
- Lithium-ion cell supply concentration:Battery chemistry sourcing clusters in East Asian manufacturing corridors, exposing OEMs to logistics volatility and geopolitical friction.
- FDA 510(k) clearance timelines:Clinical claim substantiation requirements extend commercialization windows by 12-18 months for novel oscillation mechanisms entering US distribution.
- Manual prophylaxis substitution:Low-cost disposable polishing cups retain share in price-sensitive dental clinic segments, compressing mid-tier electric unit penetration.
Strategic Opportunities
- Direct-to-consumer channel innovation:Subscription-based consumable attaché models are capturing recurring revenue streams outside traditional dental distributor networks.
- Bluetooth-enabled oral health data:Smart pressure sensors and connectivity modules are creating monetization pathways through preventive care app ecosystems.
- Chairside efficiency mandates:Dental clinic consolidation is driving bulk procurement of cordless rechargeable platforms that reduce procedure turnaround times.
Industry Challenges
- ISO 13485 certification complexity:Quality management system implementation for OEM partnerships demands specialized regulatory affairs talent that remains scarce in emerging manufacturing hubs.
- Biocompatibility testing protocol evolution:Accelerating material substitution for abrasive heads requires continuous re-validation against evolving ISO standards, stretching R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Tooth Polisher Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless, Corded, Rechargeable, Battery-operated End User: Dental Clinics, Homecare, Hospitals, Cosmetic Offices Feature: Portable, Waterproof, Smart Technology, Ergonomic Design Application: Teeth Whitening, Plaque Removal, Stain Removal, Gum Care |
| Companies Covered | Relish, BURST Oral Care, Philips Sonicare, Aiwejay, Auxbon, Oral-B, Quip, SURI, Broxo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Tooth Polisher Market Emerging Trajectories
Product architecture is converging around smart connectivity and powertrain miniaturization, while regulatory frameworks on both sides of the Atlantic reshape competitive qualification requirements.
Piezoelectric ultrasonic oscillation is virtualizing traditional mechanical polishing architectures. Dental clinics in Japan and Germany are adopting these platforms at twice the rate of North American counterparts due to earlier reimbursement alignment. The technology is virtualizing supply chain requirements by consolidating motor, driver, and control electronics into single-chip solutions that compress BOM complexity.
REACH substance restrictions on nickel alloys are forcing abrasive head manufacturers toward ceramic and polymer composite alternatives. Industrial consequence includes 18-month reformulation cycles for consumable product lines. Professional-grade polishers entering European markets face the steepest compliance burden, with notified body conformity assessment now mandatory for all Class IIa devices.
After-sales service unbundling is fragmenting traditional distributor relationships. Dental service organizations are negotiating direct technical support agreements with manufacturers, bypassing regional equipment dealers. This pattern is most visible in United States metropolitan markets where DSO consolidation has concentrated buying power among fewer than fifty national accounts.
Electric Tooth Polisher Market Segmentation
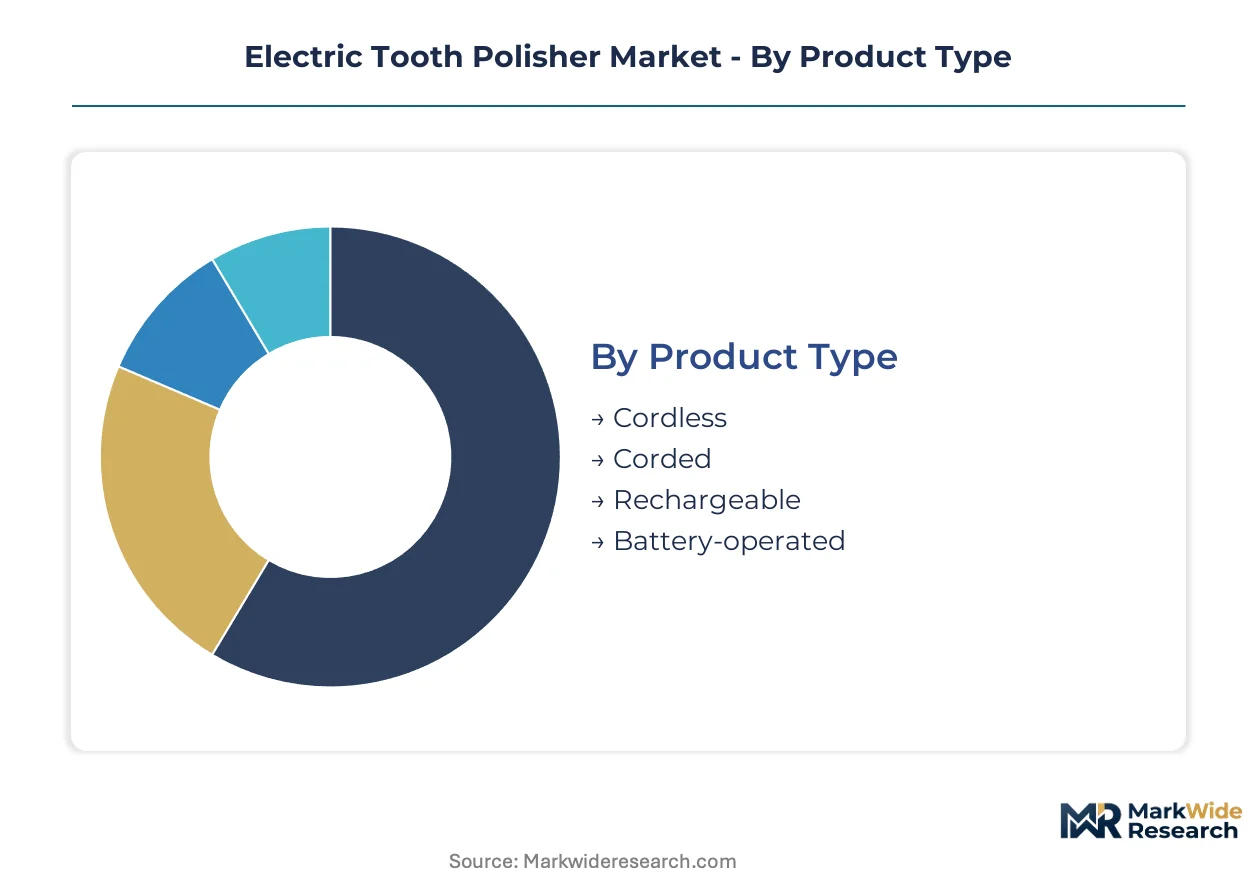
Segmentation in the electric tooth polisher market reveals divergent engineering requirements between clinical sterilization-grade platforms and consumer convenience-focused devices. Product architecture, end-user procurement patterns, and feature integration strategies each create distinct margin pools and competitive qualification barriers.
Product Type:
Cost tier differentiation separates professional-grade platforms from entry-level consumer alternatives through battery chemistry, ingress protection ratings, and motor architecture.
- Cordless:Lithium-ion cell platforms operating at 3,000–40,000 strokes per minute with IPX7 water ingress protection. Dental clinics in Germany and Japan prioritize these for chairside mobility and sterilization compatibility.
- Rechargeable:Docking station architectures with rapid-charge circuits and battery management systems. Homecare channels in the United States drive volume through subscription attaché models that lock in recurring consumable revenue.
- Corded:AC-powered units with continuous operation capability for high-throughput clinical environments. Demand concentrates in hospital dental departments where power reliability outweighs portability requirements.
- Battery-operated:Disposable or replaceable cell configurations targeting price-sensitive consumer segments. These units sacrifice oscillation consistency for unit economics in emerging retail channels.
Rechargeable platforms command the established base. The steepest expansion runs through cordless lithium-ion architectures.
End User:
Application context determines regulatory burden, procurement volume, and service attachment expectations across institutional and consumer settings.
- Dental Clinics:Sterilization-grade construction with autoclave-compatible materials and bulk consumable contracts. EU Medical Device Regulation conformity assessment mandates notified body involvement for professional-grade units entering European markets.
- Homecare:Direct-to-consumer distribution with Bluetooth connectivity and app ecosystems. FDA 510(k) clearance requirements shape clinical claim substantiation for whitening and plaque removal efficacy in United States retail channels.
- Hospitals:Integrated procurement through group purchasing organizations with preventive maintenance agreements. These buyers prioritize ISO 13485-certified supply chains and technical documentation depth.
- Cosmetic Offices:Aesthetic-focused applications with teeth whitening as the primary value proposition. Regulatory classification varies by jurisdiction, with some markets treating these as cosmetic devices exempt from medical device frameworks.
Dental clinics anchor professional-grade revenue. Homecare channels are climbing the fastest as subscription models capture recurring revenue outside traditional distributor networks.
Feature:
Customer type preferences segment the market between clinical functionality demands and lifestyle-oriented convenience attributes.
- Smart Technology:Pressure sensors, Bluetooth modules, and oral health data monetization through preventive care app ecosystems. These features expand fastest in United States and Japanese consumer markets where digital health integration carries premium positioning.
- Waterproof:IPX7-rated enclosures enabling submersion cleaning and shower use. Homecare adoption in Germany drives specification requirements that cascade through OEM private-label agreements.
- Portable:Compact form factors with travel cases and dual-voltage compatibility. Cosmetic offices and mobile dental services prioritize these for off-site procedure capability.
- Ergonomic Design:Grip geometry and weight distribution optimized for extended clinical use. Dental clinics specify these to reduce repetitive strain injury risk among hygienists.
Waterproof construction holds the volume base. Smart technology integration shows the steepest trajectory as data monetization strategies mature.
Application:
Volume concentration varies by clinical indication, with cosmetic outcomes commanding premium pricing and preventive care driving replacement frequency.
- Plaque Removal:Biofilm disruption at gingival margins and interproximal spaces. Dental clinics in Japan specify ultrasonic piezoelectric actuators for this indication due to earlier reimbursement alignment with high-frequency oscillation platforms.
- Teeth Whitening:Extrinsic stain oxidation and surface polishing for aesthetic outcomes. Cosmetic offices in the United States bundle these with bleaching agents, creating service revenue attachment.
- Stain Removal:Tobacco, coffee, and wine discoloration targeting consumer self-treatment. Homecare channels in Germany drive demand for abrasive head variety packs with graduated grit sequences.
- Gum Care:Subgingival irrigation and soft tissue massage with reduced pressure settings. FDA 510(k) clearance timelines extend for devices claiming therapeutic periodontal benefits in United States distribution.
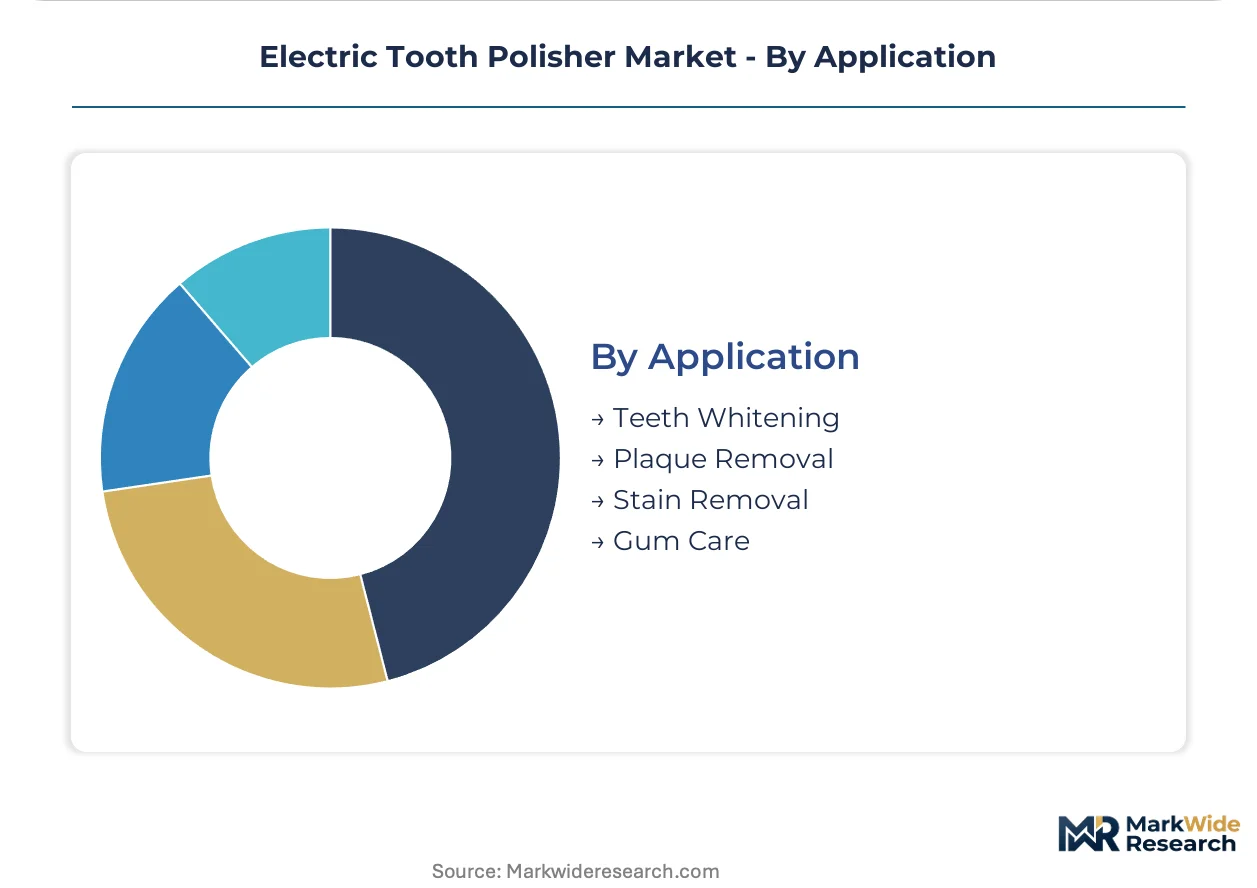
Plaque removal anchors clinical procurement. Teeth whitening applications are expanding most quickly as cosmetic dentistry consumerization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export professional-grade sterilization-compatible platforms to dental clinic networks across the United States and Japan, while Chinese OEMs supply lithium-ion battery assemblies to cordless device assemblers in North American consumer channels.
United States
FDA 510(k) clearance timelines shape commercialization windows for novel oscillation mechanisms entering retail distribution. Dental service organizations in metropolitan markets negotiate direct technical support agreements that bypass regional equipment dealers. Preventive maintenance contracts anchor procurement decisions among group purchasing organizations serving hospital dental departments.
Germany
EU Medical Device Regulation conformity assessment mandates notified body involvement for professional-grade units entering European markets. REACH substance restrictions on nickel alloys force abrasive head manufacturers toward ceramic and polymer composite alternatives. Stuttgart and Munich host precision motor manufacturers supplying piezoelectric actuator modules to cordless platform assemblers.
Japan
METI reimbursement frameworks align earlier with high-frequency oscillation platforms than North American counterparts. Osaka and Nagoya concentrate sterilization-grade device fabrication for chairside efficiency mandates in consolidated dental clinic networks. PMDA consultation procedures accelerate clinical claim substantiation for ultrasonic piezoelectric architectures.
China
NMPA medical device registration requirements extend commercialization timelines for imported professional-grade polishers. Shenzhen and Dongguan cluster lithium-ion cell manufacturing and battery management system assembly for export to cordless device OEMs. GB standards for electrical safety and biocompatibility testing govern domestic market entry.
South Korea
MFDS quality system certification functions as a baseline qualifier for OEM partnerships supplying rechargeable platforms to global brands. Seoul Capital Area hosts contract manufacturers integrating Bluetooth connectivity modules for smart feature differentiation. Domestic dental clinic procurement favors rapid-charge docking station architectures from local suppliers.
Electric Tooth Polisher Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation pressure concentrates among dental distributor networks as direct-to-consumer subscription models capture recurring revenue outside traditional procurement channels. Three archetypes dominate: oral care conglomerates with proprietary motor architectures, direct-to-consumer challengers with subscription attaché models, and contract manufacturers supplying private-label platforms to retail brands. Strategic moves center on M&A for connectivity technology assets and backward integration into lithium-ion battery cell sourcing.
Within the conglomerate tier, Philips Sonicare and Oral-B exemplify channel-controlling positions through dental clinic partnerships and retail shelf presence. BURST Oral Care occupies a specialist position representing direct-to-consumer archetype innovation with subscription-based consumable models. Aiwejay and Auxbon sit within the contract manufacturing tier supplying OEM private-label platforms to brands lacking in-house production capabilities.
| Leading Market Players |
|---|
| Relish |
| BURST Oral Care |
| Philips Sonicare |
| Aiwejay |
| Auxbon |
| Oral-B |
| Quip |
| SURI |
| Broxo |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Shenzhen lithium-ion cell assembly is compressing supplier margins and forcing cordless platform OEMs toward volume-based pricing concessions that reshape procurement negotiations across dental clinic and homecare channels.
Pricing Analysis
Next-generation ultrasonic piezoelectric platforms command 40-60% premiums over legacy oscillating-rotating systems, while nickel-cadmium legacy inventory clears at distressed levels. Three-tier pricing structure across premium sterilization-grade, standard professional, and economy consumer levels segments buyer access, with ISO 13485 certification and FDA 510(k) clearance functioning as the primary price differentiation drivers. Pricing pressure stems from manual prophylaxis substitution in cost-sensitive clinic segments, squeezing mid-tier electric unit viability. Dental service organizations exhibit lowest price sensitivity due to bulk procurement scale, while independent cosmetic offices face acute budget constraints.
Supply Chain Analysis
Contract manufacturing concentrates among Dongguan and Shenzhen EMS providers for cordless assembly, with Aiwejay and Auxbon holding significant private-label capacity. Lithium-ion cells source predominantly from China, South Korea, and Japan, while piezoelectric actuator modules draw from German and Japanese precision motor specialists. Single-source vulnerability runs through East Asian battery chemistry corridors exposed to logistics volatility and export control friction. Distribution runs through dental distributor networks fragmenting as direct-to-consumer subscription models capture recurring attaché revenue outside traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manual prophylaxis substitution threatens electric unit penetration in price-sensitive clinic segments, requiring incumbents to articulate clinical efficiency returns that justify premium positioning against low-cost disposable alternatives.
For Market Incumbents: Pre-empt margin erosion by backward integration into lithium-ion cell sourcing to reduce exposure to East Asian supply volatility, while accelerating sterilization-grade certification investments that lock out mid-tier challengers from dental clinic procurement. Defend channel position through exclusive technical support agreements with consolidating dental service organizations that bypass distributor intermediaries.
For New Entrants and Emerging Players: Pursue direct-to-consumer subscription white space in United States homecare channels where brand loyalty remains fluid and recurring consumable revenue models have proven traction. Target Bluetooth-enabled smart feature differentiation as the most penetrable wedge, leveraging app ecosystem partnerships to circumvent entrenched retail shelf access barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because dental clinic network concentration and DSO buying power aggregation favor scaled manufacturers with captive supply chains and regulatory affairs depth. Monitor FDA 510(k) clearance velocity and EU MDR notified body queue lengths as inflection signals for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Sourcing | Captive lithium-ion supply reduces exposure to East Asian logistics volatility and geopolitical friction. |
| FDA 510(k) Clearance Acceleration | Earlier market entry for ultrasonic piezoelectric platforms captures premium positioning before competitor replication. |
| Direct-to-Consumer Subscription Launch | Recurring consumable attaché revenue locks in lifetime value outside dental distributor margin capture. |
| Bluetooth Companion App Development | Oral health data monetization creates defensive moats through preventive care ecosystem integration. |
| EU MDR Notified Body Pre-Certification | Sterilization-grade construction alignment opens professional-grade procurement across German and Japanese clinic networks. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, and dental equipment customs records, combining structured interviews with dental clinic procurement managers, biomedical engineers at hospital purchasing committees, GPO contracts managers, and regulatory affairs leads at OEMs with bottom-up and top-down triangulation across product type, end user, feature, and application segmentation.
Forecast inputs span rechargeable platform adoption curves, lithium-ion cell cost trajectories, and reimbursement alignment timelines across the analysis window, with CAGRs derived from segment-level volume build-ups validated against macro dental expenditure trends and sterilization-grade certification penetration rates in Germany, Japan, and the United States.
Macroeconomic conditions sit as an overlay; deviation in dental reimbursement rates, battery raw material costs, or trade corridor stability would shift the trajectory. Quarterly review of FDA submission volumes, EU MDR certificate issuance rates, and lithium carbonate spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
Disposable Razor Blades Market
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Global Away-From-Home Tissue and Hygiene Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Underarm Sweat Pads Market