
 Protein Trends and Technologies Market | 2026-2036
Protein Trends and Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Trends and Technologies Market Intelligence
The market for protein ingredients is pivoting on a clear divergence between high-value, functionally specialized proteins and commoditized plant-based inputs. DuPont specializes in developing high-purity isolates for clinical nutrition and infant formula. In contrast, Cargill leverages its vast agricultural supply chain to dominate the animal feed and bulk food processing segments. PepsiCo positions its portfolio to capture consumer demand for branded functional foods and beverages containing tailored protein blends.
Protein technologies encompass the methods used to isolate and functionalize proteins, often achieving purity levels above 90% for isolates. These processes, including ultrafiltration and enzymatic hydrolysis, modify properties like solubility and digestibility for targeted industrial applications. Plant-based proteins are expanding rapidly, challenging the mature animal-derived protein segment. Sports nutrition applications command premium pricing, while the functional foods category drives overall market volume.
Regulatory frameworks from the US FDA and the European Food Safety Authority (EFSA) govern novel food approvals and allergen labeling, directly impacting market access. In India, FSSAI standards for protein content and fortification shape product formulation for nutraceutical companies. Ingredient suppliers and food manufacturers must now decide whether to invest in proprietary fermentation technologies or secure long-term supply of conventional plant isolates.
Market Dynamics
The central dynamic is the industrialization of protein production through advanced fermentation, which enables the creation of novel protein structures independent of traditional agricultural cycles. This technological shift directly addresses demand for improved functionality in specialized foods.
Growth Catalysts
- Fermentation Advances:Precision fermentation creates proteins with enhanced solubility and emulsification, targeting the functional foods sector.
- National Health Policies:Government health initiatives in China and India's FSSAI standards stimulate demand for protein-enriched consumer goods.
- Sustainable Sourcing Mandates:Corporate ESG goals drive a shift toward proteins with lower land and water footprints, like microbial and plant-based inputs.
Market Restraints
- High Capital Costs:Building large-scale bioreactors for precision fermentation requires substantial investment compared to established agricultural infrastructure.
- Regulatory Delays:Novel food approval processes, particularly under the European Food Safety Authority (EFSA), involve lengthy and costly safety dossiers.
- Sensory Deficits:Plant-based proteins often possess off-flavors or poor textures, limiting direct substitution for animal proteins in many food matrices.
Strategic Opportunities
- Hybrid Product Formulation:Combining plant isolates with cell-cultured fats can create meat analogues with superior taste and mouthfeel.
- Medical and Geriatric Nutrition:A market exists for highly digestible protein isolates formulated for clinical nutrition and elderly dietary needs.
- Southeast Asian Markets:Countries like Indonesia and Vietnam offer growth potential driven by rising incomes and evolving dietary habits.
Industry Challenges
- Feedstock Security:Scaling fermentation requires securing stable, high-purity carbohydrate feedstocks, creating new supply chain dependencies.
- Talent Scarcity:A shortage of bioprocess engineers experienced in scaling fermentation from pilot to industrial levels is a key bottleneck.
- Bioavailability Metrics:Lack of a standard metric to compare protein quality across novel sources complicates formulation for nutrition-focused products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Trends and Technologies Market |
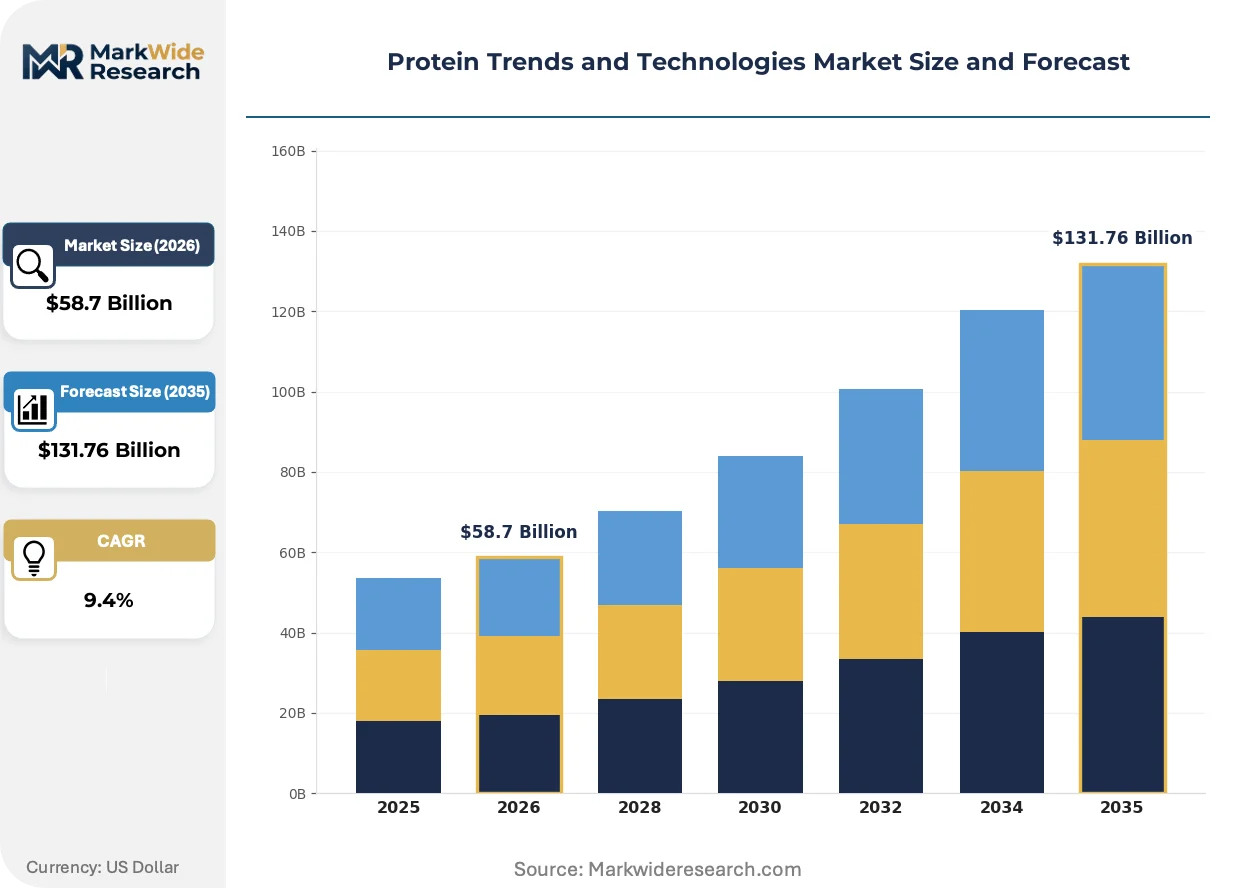
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
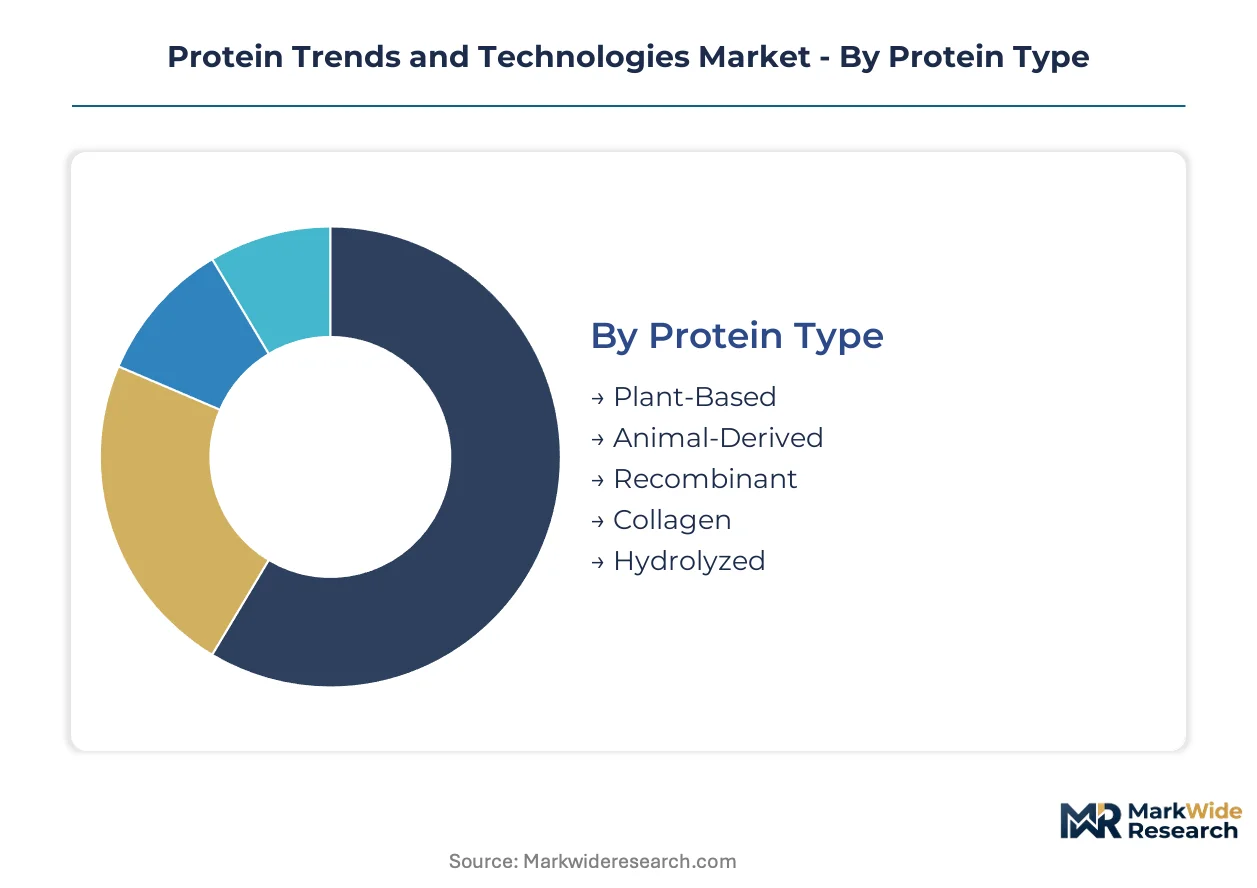
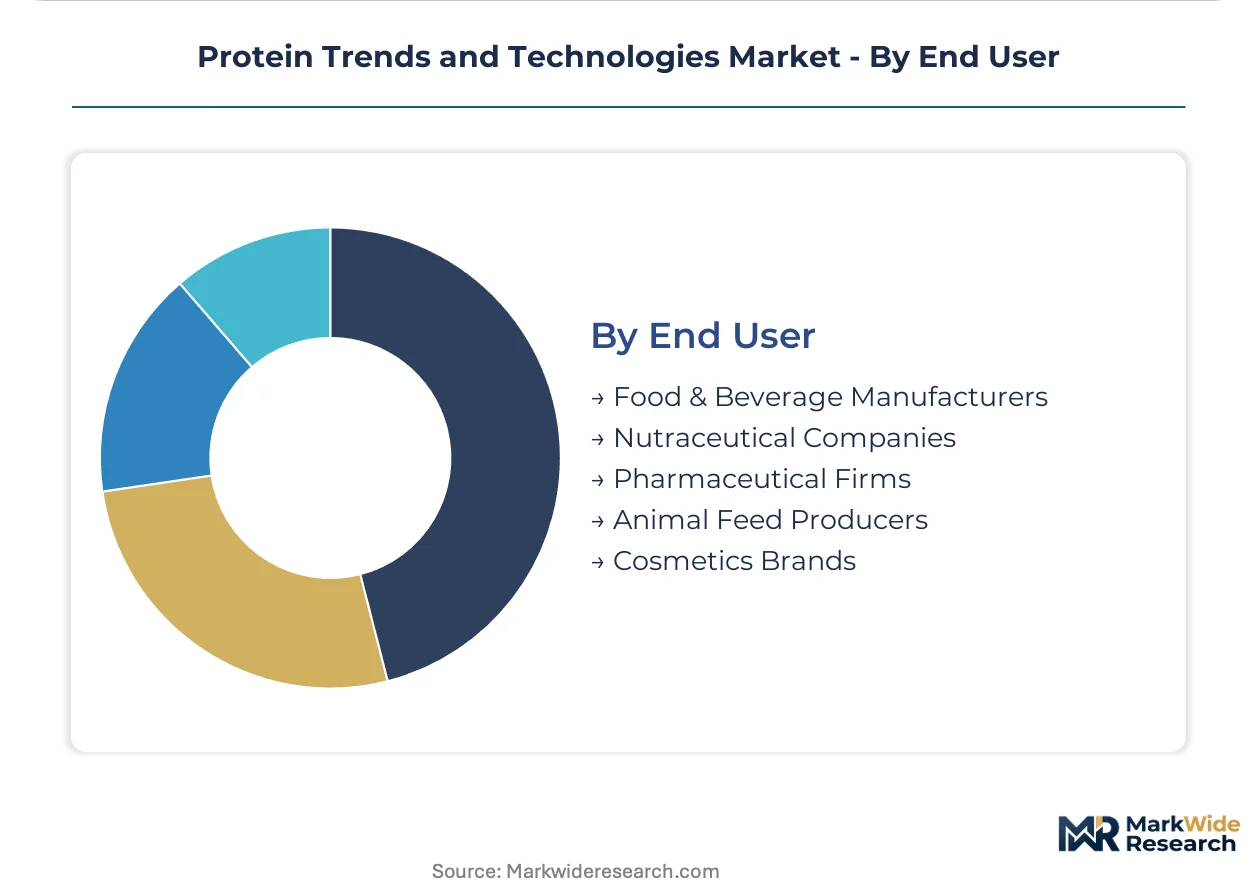
| Segmentation | Protein Type: Plant-Based, Animal-Derived, Recombinant, Collagen, Hydrolyzed Application: Sports Nutrition, Functional Foods, Clinical Nutrition, Infant Nutrition, Supplements Technology: Fermentation, Extraction, Ultrafiltration, Enzymatic Hydrolysis, Spray Drying End User: Food & Beverage Manufacturers, Nutraceutical Companies, Pharmaceutical Firms, Animal Feed Producers, Cosmetics Brands |
| Companies Covered | Nestle, BASF, Cargill, Olam International, Unilever, Archer Daniels Midland, PepsiCo, Thermo Fisher Scientific, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Trends and Technologies Market Strategic Shifts & Innovations
Technology is altering the definition of protein, shifting production from agricultural fields to bioreactors. This transition creates functional building blocks engineered for specific outcomes in food and nutrition systems.
AI-driven discovery platforms screen novel microorganisms and computationally design protein structures with desired functionalities. Ingredient developers are rapidly adopting this approach for new product development. The use of AI is automating the historically slow R&D process, compressing timelines for bringing new functional proteins to market.
Regulatory frameworks for novel foods, like the US FDA's GRAS notification pathway, are critical for market entry. This process offers a science-based route for validating the safety of ingredients from technologies like precision fermentation. Ingredient developers targeting the US market for sports nutrition prioritize ingredients with a clear GRAS strategy.
A behavioral shift sees food manufacturers procuring complete functional protein systems instead of single commodity ingredients. This trend disrupts traditional distributors, favoring suppliers who offer application support and customized blends. The shift is most pronounced in North America's competitive plant-based dairy and meat alternative categories where functionality is paramount.
Protein Trends and Technologies Market Segmentation
Understanding the protein market requires granular segmentation to identify specific value pools and competitive dynamics. This analysis dissects the market across key dimensions, revealing where innovation is concentrated and how different protein forms and technologies address diverse end-user needs. Strategic decisions hinge on recognizing these distinct market behaviors.
Protein Type:
The capital expenditure required to produce different protein types varies significantly, influencing market entry and scale.
- Recombinant:These proteins are produced through genetically engineered microorganisms in bioreactors, requiring substantial investment in fermentation infrastructure and bioprocessing expertise. Demand for highly pure, novel functional proteins in specialized clinical applications drives this segment, particularly in pharmaceutical firms.
- Plant-Based:Derived from sources like soy, pea, and rice, these proteins require large-scale agricultural processing and extraction facilities, with capital costs tied to raw material sourcing and processing efficiency. Consumer demand for sustainable and allergen-friendly options in functional foods and beverages is concentrating here.
- Animal-Derived:Sourced from dairy, egg, and meat, these proteins remain foundational for sports nutrition and infant formula due to their complete amino acid profiles.
- Collagen:This structural protein, often derived from animal connective tissues, finds use in nutraceuticals and cosmetics for its purported benefits in skin and joint health.
- Hydrolyzed:These proteins undergo enzymatic breakdown into smaller peptides, enhancing digestibility and solubility for specialized nutritional supplements and clinical formulations.
Most installed capacity flows through Animal-Derived proteins. Expansion is steepest in Recombinant proteins.
Application:
Application segments exhibit distinct pricing sensitivities and cost structures, from premium specialized formulations to mass-market consumer goods.
- Infant Nutrition:This application demands the highest purity and safety standards for protein ingredients, involving rigorous testing and regulatory compliance, leading to premium pricing. Demand in China and India is significant, driven by rising disposable incomes and parental focus on early child development.
- Sports Nutrition:Formulations for athletes prioritize protein content and rapid absorption, often incorporating isolates and hydrolysates, which command higher ingredient costs. Consumer demand for performance enhancement and muscle recovery products in North America sustains this premium segment.
- Functional Foods:Proteins integrated into everyday foods like yogurts and bars target general wellness and satiety, driving significant market volume.
- Clinical Nutrition:Tailored protein blends support recovery and manage specific dietary needs for patients in healthcare settings, requiring highly digestible forms.
- Supplements:Protein powders and pills offer concentrated protein doses for general health, with wide availability across retail channels.
Volume is highest in Functional Foods. Margin is highest in Infant Nutrition.
Technology:
Protein technologies are selected based on the desired functional properties and target application, from high-purity isolates to bulk ingredients.
- Fermentation:This technology uses microorganisms to produce specific proteins or modify existing ones, enabling precise control over structure and functionality, particularly for novel proteins. Investment in bioreactor capacity and downstream processing is critical as demand for sustainable and highly functional ingredients accelerates.
- Ultrafiltration:A membrane-based separation process, ultrafiltration concentrates proteins while removing smaller molecules, crucial for producing high-purity isolates like whey protein isolate. This technology is fundamental for applications requiring low-lactose or high-protein content, especially in sports and infant nutrition.
- Extraction:Mechanical or chemical methods separate proteins from their raw sources, forming the basis for plant-based protein concentrates and isolates.
- Enzymatic Hydrolysis:Enzymes break down proteins into smaller peptides, enhancing digestibility and reducing allergenicity for clinical and specialized nutritional products.
- Spray Drying:This common dehydration method converts liquid protein solutions into stable powders, essential for storage, transport, and integration into dry food mixes.
Precision and purity are paramount in Fermentation. Cost-efficiency drives adoption in Spray Drying.
End User:
End users represent diverse customer types with varying purchasing power, regulatory requirements, and ingredient specifications for protein inputs.
- Pharmaceutical Firms:These users require proteins of the highest purity and safety, often recombinant, for therapeutic applications, vaccines, and drug delivery systems, subject to stringent regulatory oversight like US FDA. Research and development investment in novel protein structures is substantial within this segment.
- Food & Beverage Manufacturers:This segment constitutes the largest volume buyer, integrating proteins into a wide array of consumer products for nutritional enhancement and functional benefits. Procurement patterns are shifting towards complete functional protein systems, particularly in North America.
- Nutraceutical Companies:These firms formulate protein-enriched products like dietary supplements and functional foods, targeting specific health benefits and wellness trends.
- Animal Feed Producers:Proteins are essential components in livestock and aquaculture feeds, focusing on cost-effectiveness and nutritional profiles for growth and health.
- Cosmetics Brands:Proteins like collagen and silk find applications in skincare and haircare products for their moisturizing and restorative properties.
The largest volume is consumed by Food & Beverage Manufacturers. The most specialized requirements come from Pharmaceutical Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The scarcity of bioprocess engineers globally shapes the protein trends and technologies market, influencing where advanced production facilities are established. This talent concentration anchors innovation in specialized protein production. Specific national policies further accelerate market development.
United States
Consumer demand for sports nutrition and functional foods drives protein innovation in the United States. The US FDA's GRAS notification pathway provides a clear route for novel protein ingredient market entry. California's biotech clusters are developing AI-driven discovery platforms for new protein structures.
China
A rising middle class and government health initiatives stimulate demand for protein-enriched consumer goods across China. National health policies and GB standards influence product formulation for nutraceutical companies. Food manufacturing hubs in the Yangtze River Delta integrate tailored protein blends into functional foods.
India
Infant nutrition and protein-enriched consumer goods fuel significant demand in India. FSSAI standards for protein content and fortification directly shape product formulation for local nutraceutical companies. Maharashtra's food processing industry experiences substantial investment in plant-based protein extraction facilities.
Germany
Functional foods and sustainable sourcing mandates propel protein market growth in Germany. The European Food Safety Authority (EFSA) governs novel food approvals, impacting market access for fermentation-derived proteins. Bavaria's biotech parks are centers for precision fermentation technology development.
Brazil
Strong demand for animal feed and plant-based protein exports drives Brazil's market. ANVISA regulations for food ingredients ensure safety and quality across protein applications. São Paulo's agricultural processing centers are scaling up extraction facilities for soy and pea proteins.
Protein Trends and Technologies Market Key Industry Players
Top-tier vendors anchor the specialized protein isolate segment, while a broader base of commodity producers serves bulk food processing. The market features integrated agricultural giants, specialized biotech firms, and consumer-facing branded product developers. Companies are pursuing strategic partnerships for technology access and expanding capacity in fermentation infrastructure. Portfolio diversification into hybrid product formulations also represents a key competitive move.
Within the specialized protein segment, DuPont exemplifies a focus on high-purity isolates, catering to demanding applications like clinical nutrition and infant formula. This positioning reflects a deep investment in advanced processing technologies. Cargill occupies a position as an integrated agricultural giant, leveraging its vast supply chain to dominate animal feed and bulk food processing segments. Its scale provides a cost advantage in commodity protein inputs. PepsiCo represents the consumer-facing branded functional foods and beverages archetype, strategically positioning its portfolio to capture demand for tailored protein blends. This approach emphasizes consumer perception and product differentiation.
| Leading Market Players |
|---|
| Nestle |
| BASF |
| Cargill |
| Olam International |
| Unilever |
| Archer Daniels Midland |
| PepsiCo |
| Thermo Fisher Scientific |
| DuPont |
Cost & Logistics Intelligence
Advanced fermentation technology, a significant production-method transition, simultaneously reshapes cost economics by enabling novel protein creation and concentrates supply in regions with specialized infrastructure and talent.
Pricing Analysis
The market exhibits a bundled-vs-unbundled service split, where suppliers offer either raw ingredients or complete functional protein systems. Pricing stratifies across premium, standard, and economy tiers, driven by purity levels for isolates and the degree of customization for functional blends. Pricing pressure stems from the increasing competition in commoditized plant-based protein segments, particularly for bulk applications. Pharmaceutical firms exhibit the least price sensitivity due to stringent quality requirements, while animal feed producers are highly sensitive to ingredient costs.
Supply Chain Analysis
Workforce availability for bioprocess engineers in manufacturing geographies like Germany and the United States anchors advanced protein production. Supply concentrates in agricultural powerhouses such as Brazil for plant-based proteins and specialized biotech clusters in the US for recombinant proteins. Raw material dependencies include high-purity carbohydrate feedstocks for fermentation and agricultural crops like soy and pea. Regulatory uncertainty for novel food approvals represents a structural supply chain risk. Distribution runs through specialized ingredient distributors for high-value isolates and bulk commodity traders for feed-grade proteins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with sustained consumer focus on health and sustainability driving consistent, long-term growth.
For Market Incumbents:Hedge against the emerging threat of novel protein competition by investing in proprietary fermentation technologies and securing long-term supply of specialized feedstocks. Deepen vertical integration into high-ppurity isolate production for clinical nutrition applications. Focus R&D on enhancing the sensory properties and functionality of existing protein portfolios. Ensure robust regulatory expertise to navigate complex approval pathways for new ingredients.
For New Entrants and Emerging Players:Digital platforms offer a direct-to-consumer route for specialized protein supplements, bypassing traditional distribution. Target the underpenetrated medical and geriatric nutrition segments with highly digestible protein isolates. Focus on developing hybrid product formulations that combine plant isolates with cell-cultured fats for superior taste profiles. Leverage sustainability claims and enhanced sensory profiles as key go-to-market angles in Southeast Asian markets, where dietary habits are evolving.
For Investors and Strategic Acquirers:Roll-up economics work for specialized ingredient suppliers because fragmentation exists among smaller biotech firms with unique intellectual property. Long-term viability remains strong, driven by health and wellness trends and the industrialization of protein production. Target specialized biotech firms with proven fermentation platforms or unique protein structures. The signal to watch is the acceleration of novel food approvals by regulatory bodies like the US FDA and EFSA, indicating market readiness for new protein sources.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Precision Fermentation IP | Secures proprietary protein structures with superior functional properties for diverse applications. |
| Expand Clinical Nutrition Portfolio | Addresses demand for highly digestible proteins in medical and elderly dietary needs. |
| Develop Hybrid Product Formulations | Improves taste and texture of plant-based alternatives, expanding consumer appeal. |
| Strengthen Supply Chain for Feedstocks | Ensures stable, cost-effective access to critical raw materials for fermentation processes. |
| Accelerate Regulatory Approval Processes | Reduces time-to-market for novel protein ingredients, gaining competitive advantage. |
Research Approach
Coverage spans the United States, China, India, Germany, and Brazil, with primary inputs from each region. The analysis combines extensive primary interviews with food scientists, bioprocess engineers, regulatory specialists, and procurement managers, validated by comprehensive secondary research. Secondary sources include public documents from the US FDA and EFSA, industry association reports, and academic journals. This approach ensures robust bottom-up and top-down triangulation.
The rate-of-change decomposition framework structures the forecast, breaking down market dynamics across the analysis window. Segmentation dimensions modeled include protein type, application, technology, end-user, and regional demand patterns. Compound annual growth rates are derived using regression analysis and market penetration models. Key forecast inputs include global consumer health spending trends and the availability of specialized carbohydrate feedstocks.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and capital cost trajectories. Material deviation in regulatory approvals or feedstock security warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Organic Starch Market
Ingredients
High Oleic Oil Market
Ingredients
Boysenberry Extract Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Waxy Maize Starch Market
Ingredients
Italy Soy Protein Market
Ingredients
Clean Label Starch Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Casein Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Casein Hydrolysate Market
Ingredients
Non-GMO Oil Market
Ingredients
Rooster Comb Extract Market
Ingredients
Green Gram Powder Market
Ingredients
All Purpose Flour Market