
 Self - Locking Trays Market | 2026-2036
Self - Locking Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Self - Locking Trays Market Analytics
China is fragmenting as domestic converters add thermoforming capacity to serve Asia-Pacific food export corridors. Amcor plc leverages integrated film-to-tray manufacturing across multiple continents to secure raw material continuity. Sealed Air Corporation specializes in barrier-coated structures that extend protein shelf life in self-locking formats. Smurfit Kappa Group anchors European fresh produce logistics through molded fiber tray systems with integrated locking tabs.
Self-locking trays are rigid or semi-rigid containers engineered with interlocking perimeter flanges or snap-fit closures that eliminate secondary sealing materials, typically manufactured through thermoforming, injection molding, or pressed fiber processes with caliper tolerances between 0.3 mm and 1.2 mm depending on payload requirements. These structures serve primary containment and unitization functions across temperature-controlled supply chains where mechanical closure integrity prevents contamination, spillage, or unauthorized access. Paper trays lead in fresh produce and prepared meal segments where fiber-based recyclability aligns with retailer sustainability mandates, while plastic trays dominate medical device and electronics packaging applications demanding hermetic seal compatibility and dimensional stability under sterilization protocols. Biodegradable trays represent the fastest-expanding structural category as polylactic acid and bagasse formulations achieve cost parity with conventional polymers in food service disposable applications.
The FDA regulates direct food-contact tray materials through 21 CFR compliance pathways that govern migration limits and substance notifications, while the EU F-Gas Regulation indirectly shapes plastic tray production economics through refrigerant phase-downs affecting cold chain infrastructure investment. REACH compliance obligations for chemical substance registration constrain additive portfolios available to European tray converters, elevating testing and documentation burdens for imported products. Stakeholders must monitor evolving extended producer responsibility frameworks that will reallocate end-of-life collection and recycling costs toward brand owners and tray manufacturers across major demand centers.
Market Dynamics
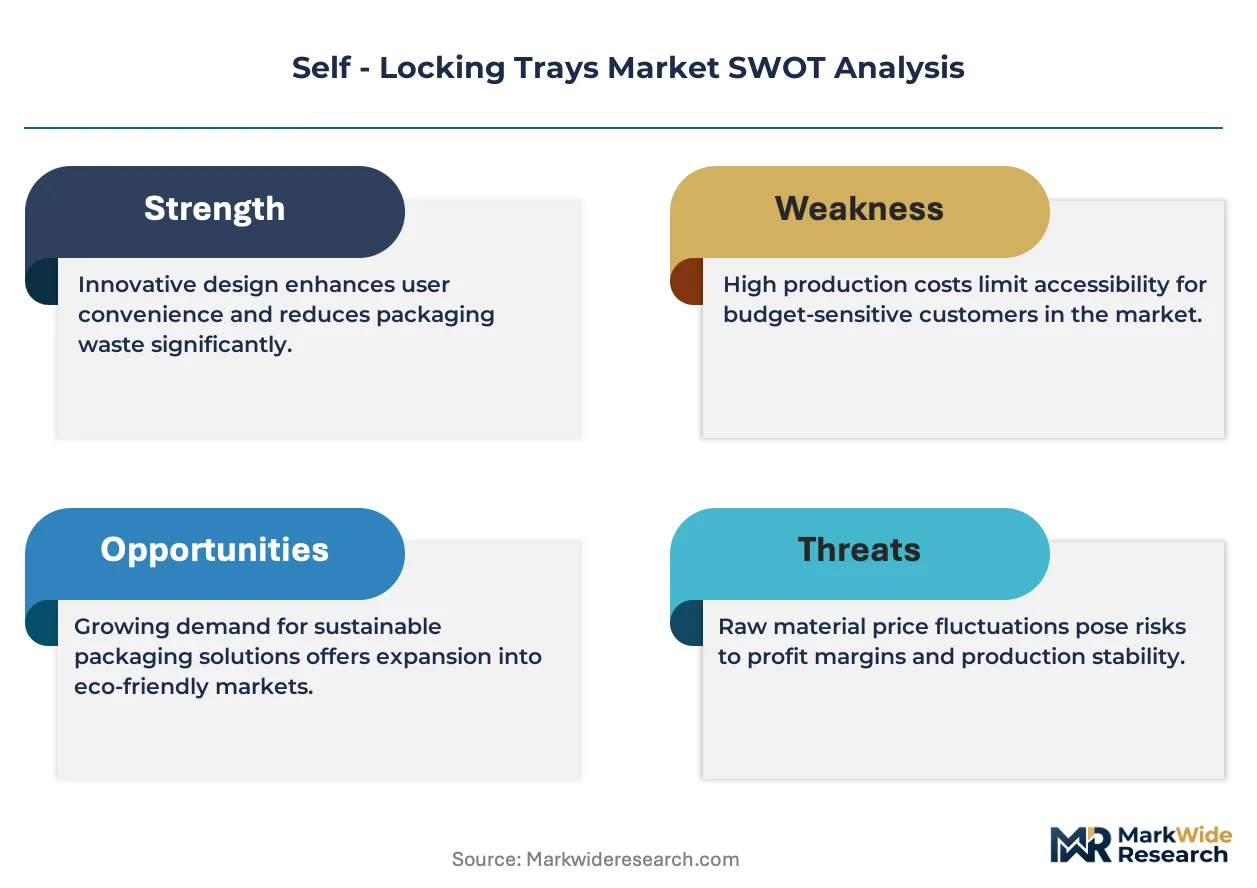
Thermoforming capacity expansion across Asia-Pacific export corridors is fragmenting supply concentration that previously centered on European and North American converters. This geographic redistribution of manufacturing assets is reshaping raw material sourcing patterns and forcing incumbent suppliers to defend margin positions through barrier-coating specialization and integrated film-to-tray production systems.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory material recovery targets for single-use food containers are accelerating specification upgrades across German cold chain logistics.
- Quick-service restaurant chains:Tamper-evident packaging mandates in food service are eliminating secondary sealing materials through snap-fit closure adoption.
- Bagasse and polylactic acid formulations:Cost parity achievements in biodegradable tray production are displacing conventional polymers in disposable food service applications.
Market Restraints
- REACH compliance obligations:Chemical substance registration requirements in Europe are constraining additive portfolios available to tray converters and elevating testing burdens for imported products.
- Refrigerant phase-downs:The EU F-Gas Regulation is indirectly compressing cold chain infrastructure investment economics, affecting temperature-controlled distribution network expansion.
- Molded fiber dimensional tolerances:Caliper variability in pressed fiber processes limits hermetic seal compatibility for medical device packaging applications.
Strategic Opportunities
- Centralized food processing clusters in Germany:Stringent hygiene protocols are driving premium specification adoption across protein and prepared meal segments.
- Extended producer responsibility frameworks:Emerging cost reallocation mechanisms toward brand owners are creating service-based revenue streams for tray manufacturers managing end-of-life collection.
- Barrier-coated structure convergence:Integration of oxygen-scavenging films with self-locking formats is extending shelf life for fresh produce logistics in European retail channels.
Industry Challenges
- Thermoforming technician scarcity:Caliper control expertise for 0.3-1.2 mm tolerance maintenance is concentrated among aging workforces in established manufacturing regions.
- Legacy sterilization compatibility:Medical device tray producers face capex-intensive validation cycles when adapting self-locking designs to gamma and ethylene oxide protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self - Locking Trays Market |
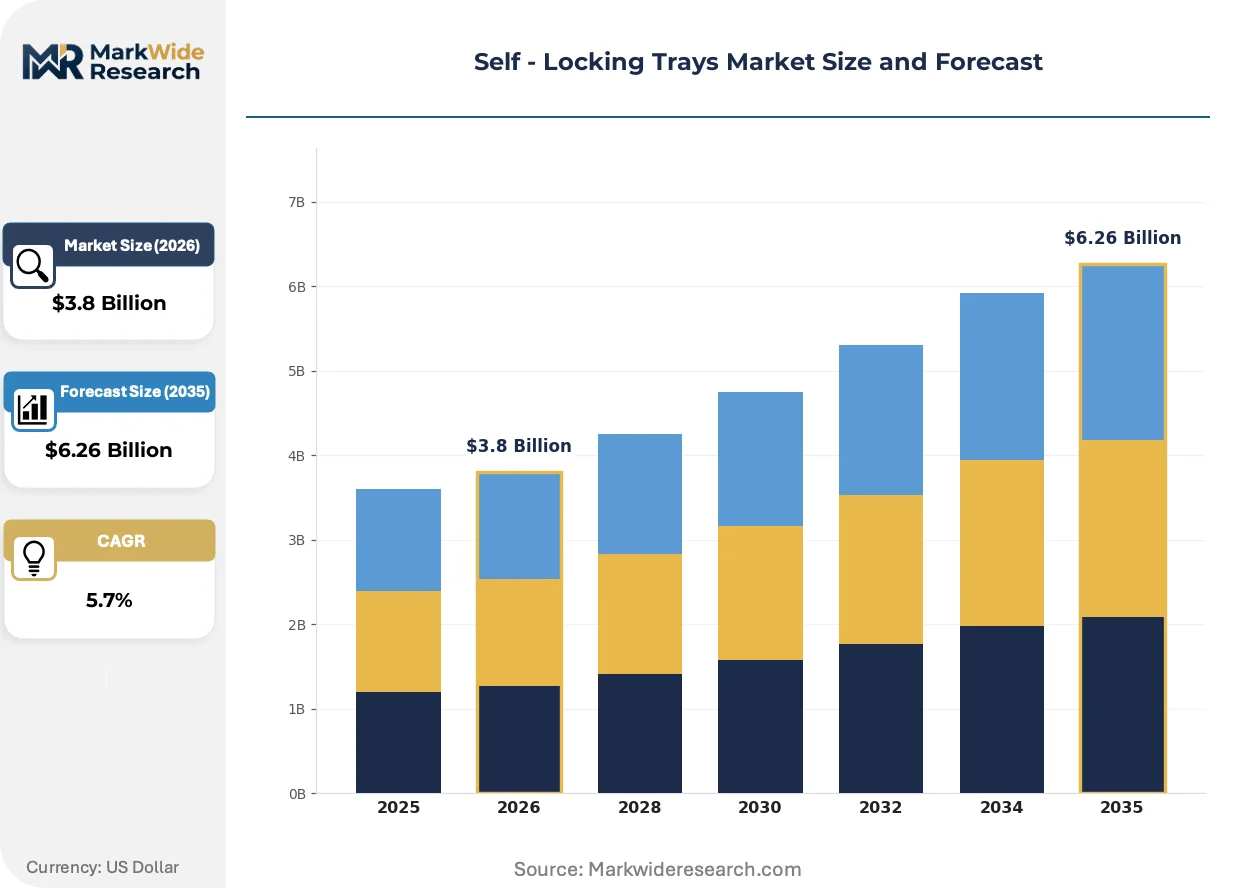
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Trays, Paper Trays, Metal Trays, Biodegradable Trays Application: Food Packaging, Medical Devices, Cosmetic Storage, Electronics Packaging End User: Food Service Industries, Healthcare Providers, Retailers, Manufacturers Distribution Channel: Online Retail, Direct Sales, Supermarkets, Specialty Stores |
| Companies Covered | Amcor plc, Sealed Air Corporation, Smurfit Kappa Group, WestRock Company, Mondi Group, DS Smith Plc, International Paper Company, Huhtamaki Oyj, Graphic Packaging International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self - Locking Trays Market Evolving Landscape
Active sensor integration and digital traceability layers are transforming self-locking trays from passive containment units into data-capture nodes within supply chain networks. This functional expansion is attracting technology investment from outside traditional packaging converters.
Embedded NFC and RFID tag integration is digitizing custody verification for high-value pharmaceutical and medical device shipments. Hospital procurement departments and third-party logistics providers are piloting these smart tray formats at accelerating rates. The technology is digitizing chain-of-capture documentation that previously required manual seal inspection and paper manifests.
The EU F-Gas Regulation's refrigerant phase-down timeline is compressing cold chain equipment replacement cycles across European distribution networks. Food service operators are responding by specifying trays with enhanced insulation properties to compensate for transitional refrigeration efficiency gaps. German quick-service chains are leading this specification shift, prioritizing thermal performance in molded fiber and expanded polymer structures.
Consolidated buying by multinational food service operators is compressing supplier qualification timelines and unbundling technical service from unit pricing. Procurement departments are replacing relationship-based vendor selection with standardized performance scorecards. This behavioral shift is most visible in North American and Western European contract catering, where self-locking tray specifications are increasingly determined by central technical teams rather than regional operations managers.
Self - Locking Trays Market Segmentation
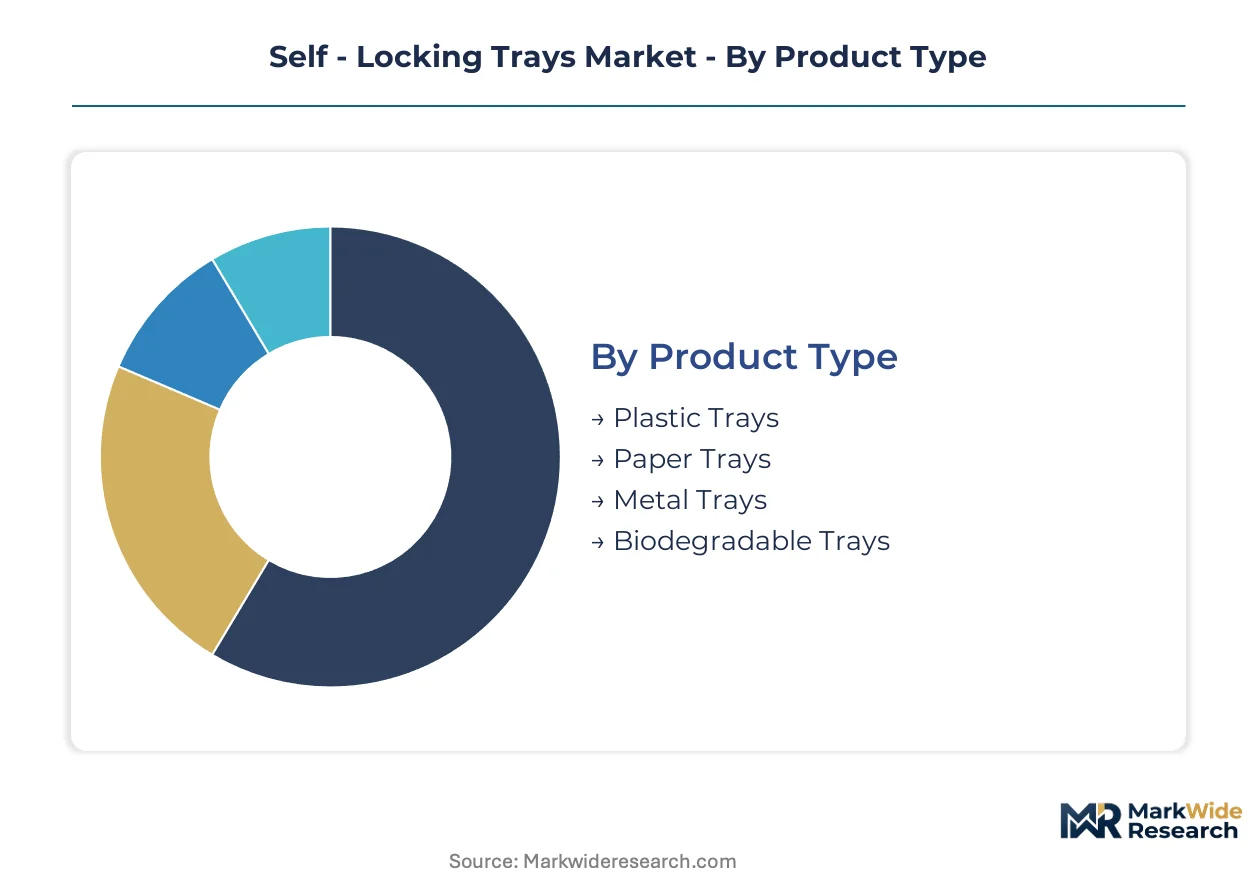
Segmentation in self-locking trays reveals divergent specification cycles across material classes and end-use verticals. Food service applications refresh inventory quarterly while medical device validations extend across multi-year certification timelines. Understanding these rhythm differences shapes capacity planning and margin capture strategies for converters.
Product Type:
Plastic trays turn inventory fastest through standardized thermoforming runs, whereas biodegradable formulations require longer curing cycles that compress effective throughput.
- Plastic Trays:Polypropylene and PET structures dominate through injection molding and thermoforming with 0.3-1.2 mm caliper precision. German quick-service chains specify these for protein packaging where hermetic seal compatibility and gamma sterilization resistance are mandatory.
- Biodegradable Trays:Polylactic acid and bagasse formulations achieve cost parity with conventional polymers in disposable food service applications. EU Packaging and Packaging Waste Regulation material recovery targets are accelerating specification shifts across centralized food processing clusters in Germany.
- Paper Trays:Molded fiber systems with integrated locking tabs serve fresh produce logistics where retailer sustainability mandates prioritize fiber-based recyclability.
- Metal Trays:Aluminum and stainless steel structures deliver dimensional stability for high-temperature sterilization protocols in medical device containment.
Plastic trays anchor the volume base while biodegradable trays gain share at the steepest rate.
Application:
Cost tier stratification separates premium validated formats from commodity disposables, with medical and electronics applications commanding specification premiums over food service.
- Food Packaging:Primary containment for prepared meals and fresh produce across temperature-controlled supply chains. Quick-service restaurant chains in Germany are eliminating secondary sealing materials through tamper-evident snap-fit adoption.
- Medical Devices:Hermetic seal compatibility and dimensional stability under ethylene oxide and gamma sterilization protocols. FDA 21 CFR compliance pathways govern migration limits and substance notifications for direct food-contact tray materials.
- Electronics Packaging:ESD-safe formulations protect sensitive components through distribution networks requiring mechanical closure integrity.
- Cosmetic Storage:Premium aesthetic finishes with locking tab security for retail display applications.
Food packaging commands the widest volume footprint while medical device applications deliver the highest margin per unit.
End User:
Customer type determines procurement cadence, with institutional healthcare contracts running multi-year against food service spot purchasing.
- Food Service Industries:Quick-service chains and contract catering operations specify trays for tamper-evident compliance and thermal performance. German operators prioritize enhanced insulation properties to compensate for EU F-Gas Regulation refrigerant phase-down impacts.
- Healthcare Providers:Hospital procurement departments pilot NFC-embedded trays for pharmaceutical chain-of-capture digitization.
- Retailers:Sustainability mandates drive fiber-based tray adoption for fresh produce private label programs.
- Manufacturers:Electronics and medical device OEMs require validated sterilization compatibility and dimensional tolerance guarantees.
Food service industries generate the highest transaction velocity while healthcare providers are consolidating toward outcome-based supplier partnerships.
Distribution Channel:
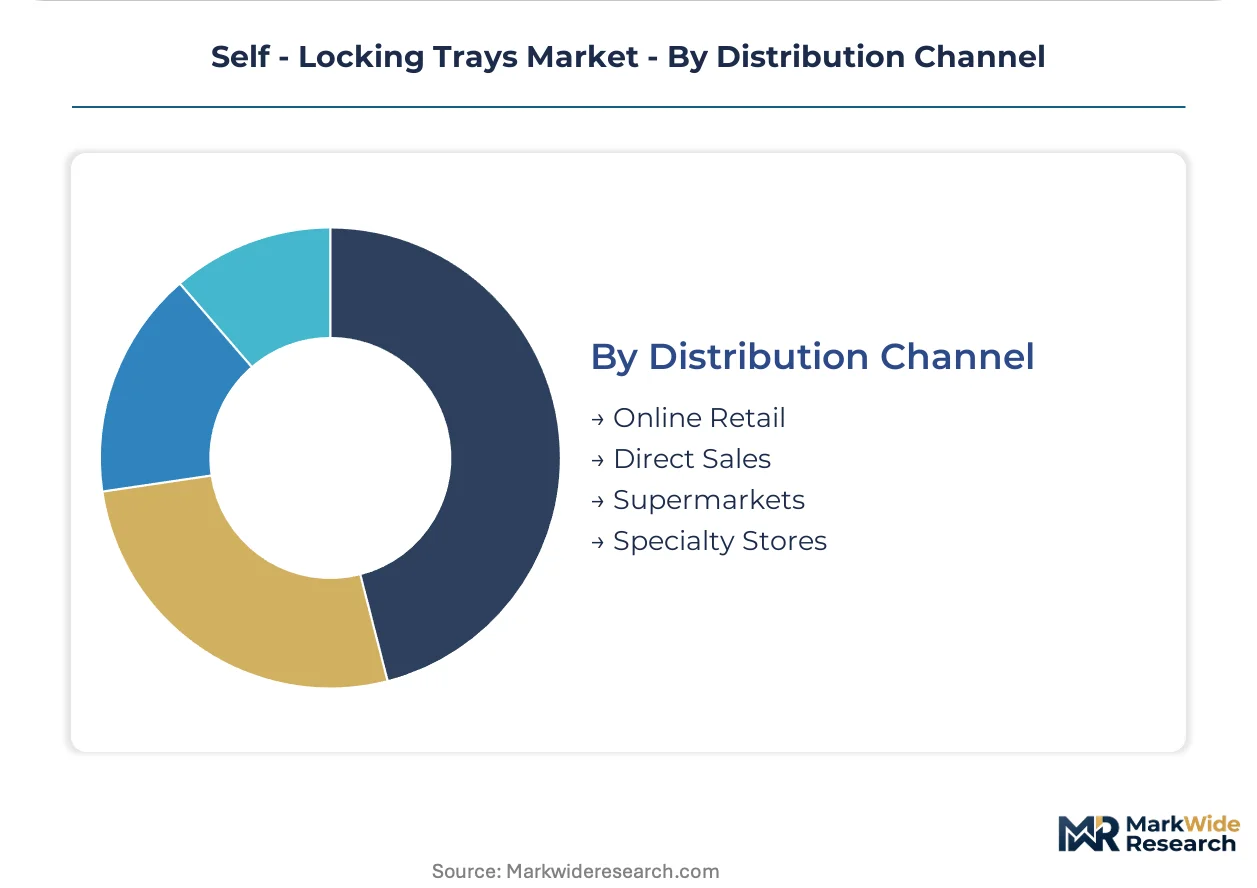
Supply concentration varies by channel control, with direct sales capturing specification-intensive medical accounts and online retail fragmenting commodity food service procurement.
- Direct Sales:Technical service integration supports medical device and electronics validation cycles. Smurfit Kappa Group anchors European fresh produce logistics through molded fiber tray systems with integrated locking tabs.
- Online Retail:Consolidated buying by multinational food service operators compresses supplier qualification timelines through standardized performance scorecards.
- Supermarkets:Private label sustainability specifications prioritize paper tray formats for produce merchandising.
- Specialty Stores:Niche cosmetic and premium food applications requiring customized locking geometries.
Direct sales retain the specification premium while online retail is expanding most quickly through procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Self-locking tray manufacturing concentrates in Germany, China, and the United States, with emerging capacity additions across Vietnam and Mexico reshaping regional supply patterns. Cold chain infrastructure investments and food safety regulations drive specification divergence across these production centers.
Germany
Centralized food processing clusters in Bavaria and North Rhine-Westphalia drive premium tray specification adoption. The EU F-Gas Regulation's refrigerant phase-down compresses cold chain equipment economics, forcing operators to prioritize enhanced insulation properties in molded fiber structures. Quick-service chains in the Munich-Stuttgart corridor eliminate secondary sealing materials through tamper-evident snap-fit mandates.
China
Domestic thermoforming capacity expansion across the Yangtze River Delta and Pearl River Delta fragments supply concentration previously centered on European converters. The country's national packaging standards authority tightens food-contact material migration limits. Zhejiang and Jiangsu provinces host expanding converter bases serving Asia-Pacific food export corridors.
United States
FDA 21 CFR compliance pathways govern direct food-contact tray material approvals, elevating documentation burdens for imported products. The Southeast's poultry processing belt and California's fresh produce logistics drive divergent specification requirements. Consolidated buying by multinational food service operators compresses supplier qualification timelines through standardized performance scorecards.
Vietnam
Export-oriented thermoforming investments target seafood and tropical produce logistics serving Japanese and European buyers. The country's national food safety authority aligns domestic standards with CODEX Alimentarius frameworks. Ho Chi Minh City and Binh Duong province host expanding converter capacity benefiting from tariff-advantaged access to key demand centers.
Mexico
Nearshoring trends accelerate tray capacity additions serving US quick-service restaurant supply chains. The federal consumer protection agency enforces labeling and material safety protocols for food-contact articles. Nuevo León and Jalisco concentrate thermoforming investments targeting cross-border refrigerated distribution networks.
Self - Locking Trays Market Competitive Landscape
Integrated multinationals and regional specialists split the market between barrier-coating specialization and molded fiber logistics. Three archetypes dominate: film-to-tray integrators securing raw material continuity, barrier-coated structure specialists extending protein shelf life, and molded fiber system providers anchoring fresh produce channels. Competitive dynamics center on capacity expansion across Asia-Pacific export corridors and backward integration into resin and pulp supply streams.
Among integrated packaging multinationals, Amcor plc exemplifies film-to-tray manufacturing archetypes spanning multiple continents. Sealed Air Corporation occupies a position within barrier-coated structure specialization. Smurfit Kappa Group anchors European molded fiber logistics through integrated locking tab systems. These three represent distinct strategic postures rather than direct segment overlap, with each occupying defensible positions across temperature-controlled supply chain applications.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Smurfit Kappa Group |
| WestRock Company |
| Mondi Group |
| DS Smith Plc |
| International Paper Company |
| Huhtamaki Oyj |
| Graphic Packaging International LLC |
| Others |
Value Network & Pricing Analysis
German thermoforming capacity concentration anchors margin capture downstream, with Bavarian converters commanding premium pricing for medical-grade caliper precision while Asian entrants compress food service tier economics through standardized runs.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across cold chain applications, separating premium insulated formats from commodity disposables. Three-tier pricing stratifies across medical validation grade, food service performance tier, and economy disposable levels. Cost compression in standard food service tiers intensifies because Zhejiang thermoforming expansions flood export corridors with undifferentiated capacity. Quick-service chains exhibit highest price sensitivity, while hospital procurement departments accept specification premiums for gamma sterilization compatibility.
Supply Chain Analysis
Polypropylene resin supply draws from Saudi petrochemical complexes, German chemical producers, and US Gulf Coast crackers, with bagasse fiber sourcing anchored in Indian sugarcane processing belts and Thai agricultural waste streams. Raw material portfolios hinge on petroleum-derived polymers, molded fiber pulp, and polylactic acid fermentation feedstocks. Single-source vulnerability concentrates in barrier coating chemistries where European REACH compliance has eliminated alternative additive suppliers. Distribution runs through direct technical sales for medical accounts and consolidated online procurement portals for multinational food service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tray manufacturers are pivoting toward service-attach revenue as end-of-life collection and recycling management contracts expand faster than unit sales. Digital traceability layer subscriptions and sterilization validation services now outpace hardware growth rates across healthcare verticals.
For Market Incumbents: Entrench barrier-coating specialization against Asian thermoforming commoditization by securing captive resin supply through backward integration into polymer production. Expand technical service teams to defend medical device validation relationships against emerging molded fiber entrants. Capacity addition in Vietnam and Mexico protects tariff-advantaged access to US quick-service supply chains.
For New Entrants and Emerging Players: Pursue biodegradable tray white space in German centralized food processing clusters where EU Packaging and Packaging Waste Regulation mandates accelerate specification shifts. Target fresh produce logistics applications where retailer sustainability mandates favor fiber-based recyclability over plastic incumbent positions. Go-to-market through direct sustainability certification partnerships with European retail private label programs.
For Investors and Strategic Acquirers: Capital is best deployed toward film-to-tray integrators with multi-continent manufacturing footprints and established FDA 21 CFR compliance pathways. Long-term viability favors converters with in-house barrier coating R&D and hospital system direct sales relationships. Watch for inflection signals in extended producer responsibility framework implementation timelines across major demand centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polypropylene sourcing insulates margin against petrochemical volatility in German medical tray production. |
| Barrier Coating R&D Expansion | Oxygen-scavenging film integration extends protein shelf life for Bavarian quick-service chain specifications. |
| End-of-Life Collection Service Launch | Extended producer responsibility compliance creates recurring revenue streams from brand owner contracts. |
| NFC-Enabled Smart Tray Development | Embedded sensor integration digitizes pharmaceutical chain-of-capture for hospital procurement pilots. |
| Thermoforming Capacity Addition in Vietnam | Tariff-advantaged export positioning serves Japanese seafood logistics and European tropical produce buyers. |
Research Methodology
A standing panel of tray manufacturing plant managers, quick-service chain procurement directors, hospital biomedical engineers, and cold chain logistics operators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA 21 CFR filings, EU Packaging and Packaging Waste Regulation implementation documents, and SEC disclosures from listed packaging multinationals. Trade data from German customs authorities and US import records supplemented bottom-up and top-down triangulation approaches.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning material class, application vertical, end-user type, and regional production hub. CAGRs derived from historical shipment data and forward capacity announcements were stress-tested against sterilization protocol adoption curves and biodegradable formulation cost parity milestones. Forecast inputs incorporated thermoforming technician workforce demographics and EU F-Gas Regulation equipment replacement cycle impacts.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Asian petrochemical conglomerates would shift outcomes beyond modeled ranges. Cross-checking against hospital GPO contract award databases and quick-service chain sustainability scorecard disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Non-Corrugated Boxes Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Correx Trays Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Airless Bottles Market
Packaging Containers
Trigger Spray Bottle Market