
 Cluster Packaging Market | 2026-2036
Cluster Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cluster Packaging Market Analysis
Asset-light leasing models for converting equipment is narrowing the capital barrier for mid-tier entrants in cluster packaging. Westrock leverages its integrated pulp-to-box network to sustain cost leadership in corrugated multi-packs. Mondi Group anchors European demand through specialized kraft-based cluster solutions for beverage clients. Smurfit Kappa competes via geographic density, operating converting plants within delivery radius of major fast-moving consumer goods bottlers.
Cluster packaging denotes multi-unit containment systems that group individual primary packages into transport-ready configurations, typically using corrugated fiberboard, shrink film, or paperboard carriers with specified burst strength and stack-load ratings for palletized distribution. The format serves retail shelf presentation and supply-chain handling efficiency simultaneously. Secondary packaging dominates volume within the product-type dimension, though flexible packaging captures expanding share in lightweight beverage and personal-care bundles where material reduction targets intensify. Paper-based materials lead in regulatory-sensitive European markets, while plastic retains cost advantage in emerging-market wholesale channels where infrastructure for fiber recovery remains underdeveloped.
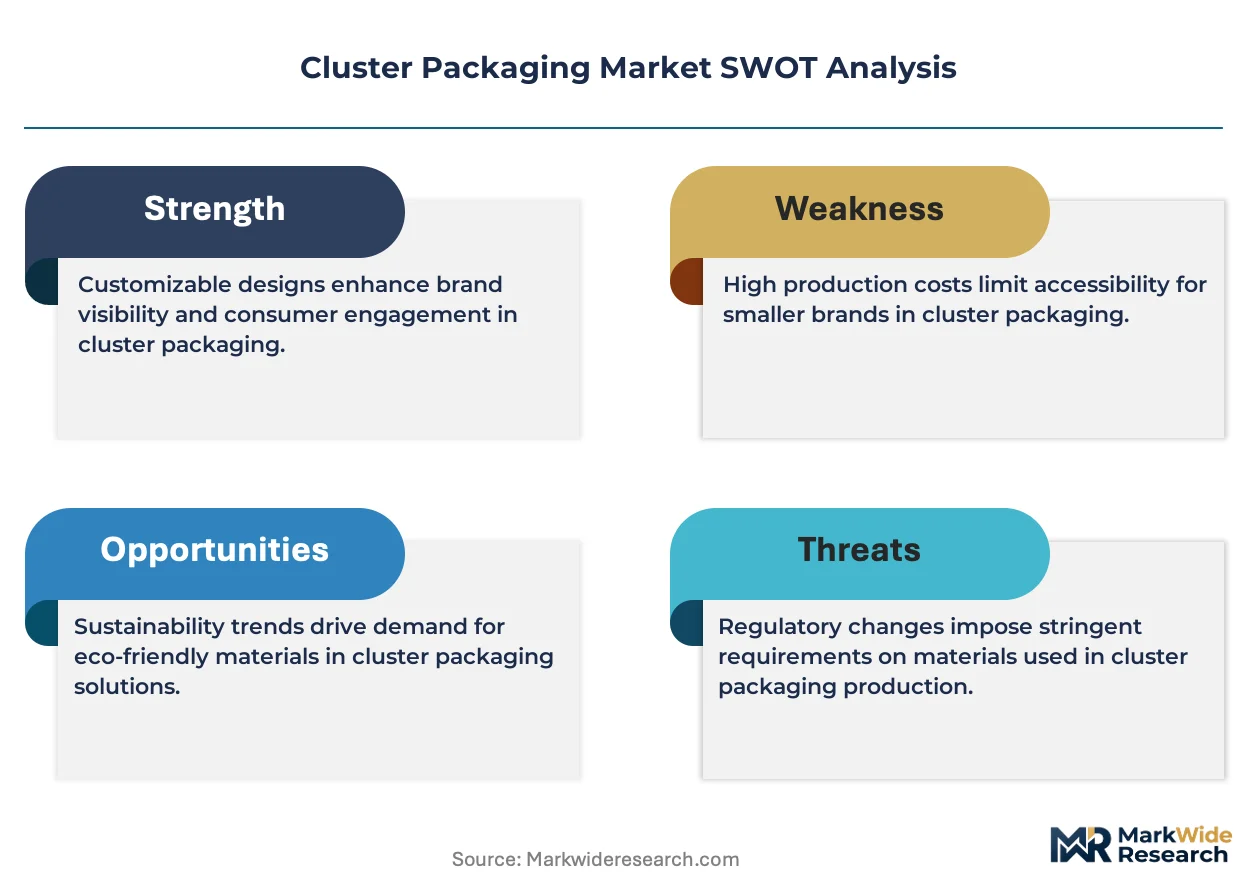
EPA guidelines on recycled content thresholds and the EU Packaging and Packaging Waste Regulation shape material substitution timelines across the cluster packaging value chain. FDA food-contact compliance requirements for adhesives and coatings used in beverage carriers create formulation complexity that favors suppliers with in-house testing laboratories. Stakeholders must monitor evolving extended producer responsibility fee structures to determine whether regional manufacturing consolidation or material-platform diversification offers superior margin protection.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material substitution timelines across the cluster packaging value chain, forcing converters to accelerate fiber-based format development ahead of mechanical recycling infrastructure maturation.
Growth Catalysts
- Beverage Multipack Demand:Brand owners in carbonated soft drinks and craft beer are adopting corrugated six-pack carriers and shrink-wrapped bundles to secure shelf differentiation in consolidated retail environments. Germany's deposit-return system standardizes multi-unit configurations, creating procurement pull.
- REACH Compliance Deadlines:ECHA restrictions on certain plastic additives are redirecting pharmaceutical bundle formats toward kraft paperboard carriers with specified burst strength ratings for palletized distribution.
- Logistics Efficiency Mandates:Fast-moving consumer goods bottlers are specifying stack-load ratings that favor secondary packaging formats reducing damage rates in automated warehouse retrieval systems.
Market Restraints
- Recovered Pulp Price Volatility:Old corrugated container availability fluctuates with e-commerce box demand, compressing margins for converters without integrated pulp-to-box networks.
- Film Recovery Infrastructure Gaps:Emerging-market wholesale channels lack collection systems for polyethylene shrink film, locking plastic cluster formats in cost-advantaged positions despite regulatory pressure elsewhere.
- FDA Adhesive Compliance Complexity:Food-contact notification requirements for beverage carrier coatings create formulation bottlenecks favoring suppliers with captive testing laboratories.
Strategic Opportunities
- India Modern Trade Expansion:Organized retail penetration in Mumbai and Delhi is creating demand for shelf-ready secondary packaging configurations previously absent in traditional trade channels.
- Extended Producer Responsibility Fee Arbitrage:Producers can optimize manufacturing footprints across EU member states with divergent EPR fee structures for fiber versus plastic cluster formats.
- Digital Print Convergence:Integration of inkjet decoration with corrugated converting lines enables short-run customized multipacks for seasonal beverage promotions without plate changeover costs.
Industry Challenges
- Structural Engineer Talent Scarcity:Finite supply of packaging engineers capable of optimizing flute profiles and board combinations for specified burst strength and stack-load performance.
- Legacy ERP Integration Friction:Converters face data architecture gaps when connecting automated converting equipment with customer order management systems for just-in-time replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cluster Packaging Market |
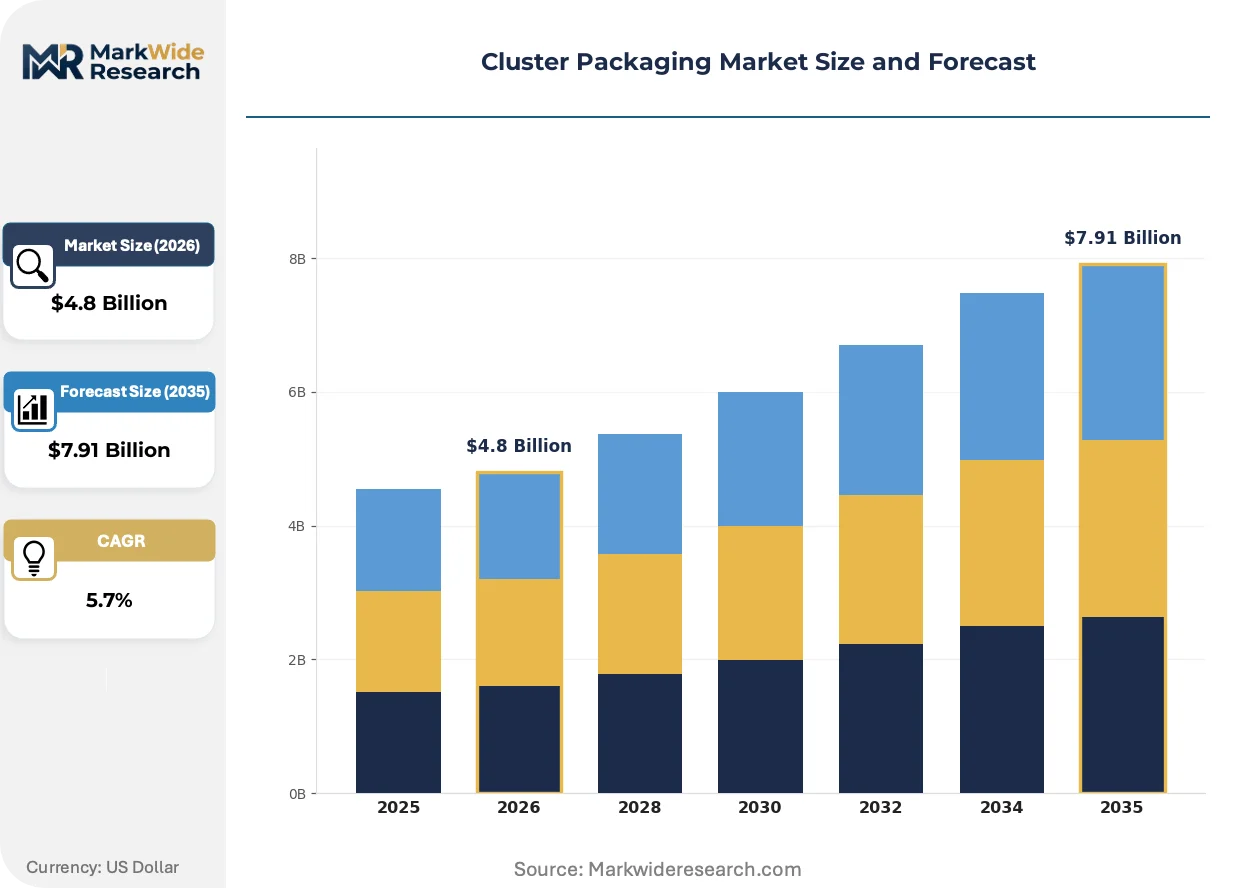
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Packaging, Secondary Packaging, Composite Packaging, Flexible Packaging Material: Plastic, Glass, Metal, Paper End User: Food & Beverage, Healthcare, Consumer Goods, Electronics Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Westrock, Smurfit Kappa, Mondi Group, PET Power, Alpha Packaging, Shanghai Wellzone Packaging, Berry Global, International Paper, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cluster Packaging Market Emerging Trajectories
Active digitization of converting equipment and regulatory compression of material approval timelines are restructuring competitive capability requirements across the cluster packaging supply base.
Machine vision inspection systems are digitizing quality assurance workflows in corrugated converting plants. High-speed cameras coupled with edge-computing analytics detect board defects and print registration errors in real time. Tier-one beverage bottlers are mandating these systems for supplier qualification, compressing acceptable quality limit thresholds and disqualifying manual inspection-dependent converters from premium contract tiers.
REACH authorization requirements for certain phthalate plasticizers are accelerating substitution toward bio-based shrink film formulations. ECHA's sunset date enforcement creates material discontinuity risk for pharmaceutical bundle producers reliant on legacy film specifications. German converters are responding with pilot lines testing polylactic acid blends, though heat-seal performance gaps persist against incumbent polyethylene.
Retail buyer consolidation is compressing procurement cycles and unbundling design services from manufacturing supply agreements. Discounters in the Netherlands and Belgium are issuing standardized cluster format specifications across private-label beverage portfolios, displacing brand-specific carrier development. This concentrates volume with converters capable of rapid specification turnaround without dedicated tooling investment.
Cluster Packaging Market Segmentation
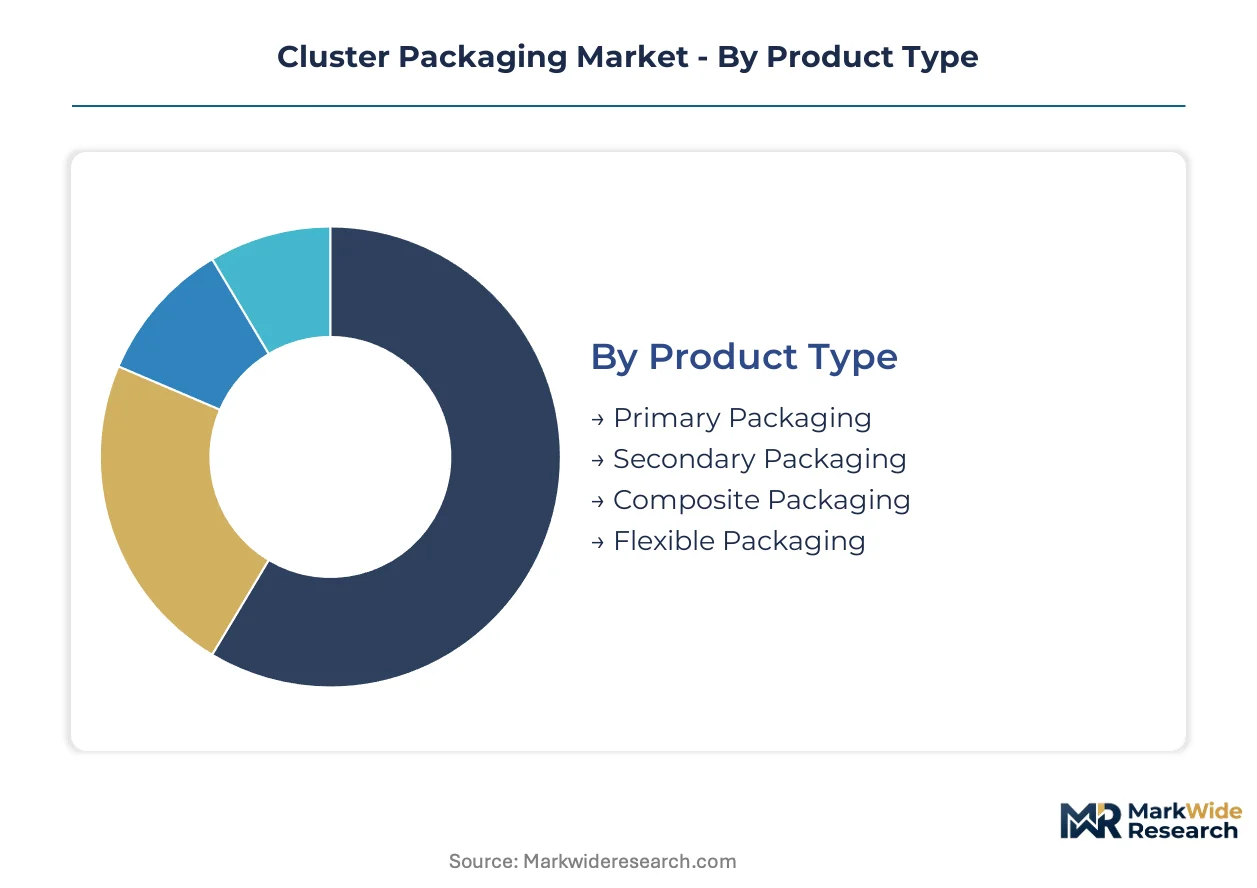
Cluster packaging procurement decisions cascade through four interdependent dimensions—product hierarchy, substrate selection, end-use performance requirements, and channel fulfillment velocity. Converters must align specifications across all four to secure multi-year supply agreements with consolidated retail buyers.
Product Type:
Mature formats dominate volume while emerging configurations capture specification innovation in sustainability-sensitive accounts.
- Secondary Packaging:Corrugated fiberboard carriers and shrink-wrapped bundles group primary units into pallet-ready configurations with defined burst strength and stack-load ratings. German beverage bottlers specify these formats for deposit-return system compatibility, creating standardized procurement pools.
- Flexible Packaging:Lightweight polyethylene and bio-based shrink films reduce material mass in beverage multipacks and personal-care bundles. ECHA restrictions on phthalate plasticizers are redirecting pharmaceutical applications toward polylactic acid blends despite heat-seal performance gaps.
- Primary Packaging:Individual containment units that interface directly with product—bottles, cans, jars—before cluster aggregation. Food-contact compliance requirements for adhesives and coatings create formulation complexity favoring suppliers with captive testing laboratories.
- Composite Packaging:Hybrid structures combining rigid and flexible elements for specialized protection needs. Electronics manufacturers specify these for shock-sensitive component shipments requiring moisture barrier plus structural rigidity.
Secondary packaging retains volume leadership; flexible packaging holds the steepest expansion curve as material reduction targets intensify across European markets.
Material:
Cost tiers separate regulatory-compliant substrates from commodity alternatives with divergent recovery infrastructure requirements.
- Paper:Kraft paperboard and corrugated fiberboard lead in EU markets where the Packaging and Packaging Waste Regulation tightens material recovery targets. German retail consolidation favors standardized fiber-based carriers with specified recyclability credentials.
- Plastic:Polyethylene shrink film and polypropylene strapping retain cost advantage in emerging-market wholesale channels where collection infrastructure remains underdeveloped. REACH authorization deadlines are compressing substitution timelines for legacy phthalate formulations.
- Metal:Steel and aluminum clips, bands, and frames provide structural reinforcement for heavy-load beverage multipacks. Deposit-return systems in Northern European markets standardize metal-compatible format specifications.
- Glass:Limited direct use in cluster structures; primarily appears as primary packaging aggregated into secondary carriers. Weight penalties restrict glass-to-glass cluster configurations outside premium spirits segments.
Paper commands premium positioning in regulated European markets; plastic maintains cost leadership where recovery infrastructure lags.
End User:
Application-specific performance requirements drive divergent specification priorities across customer verticals.
- Food & Beverage:Carbonated soft drink and craft beer brand owners adopt corrugated six-pack carriers and shrink-wrapped bundles to secure shelf differentiation. Automated warehouse retrieval systems mandate stack-load ratings that damage-resistant formats must satisfy.
- Healthcare:Pharmaceutical bundle formats require kraft paperboard carriers with specified burst strength for palletized distribution. FDA food-contact notification requirements for adhesives create qualification bottlenecks.
- Consumer Goods:Personal-care and household product multipacks prioritize lightweight flexible formats for e-commerce fulfillment efficiency. Machine vision inspection systems are becoming mandatory for supplier qualification with tier-one brands.
- Electronics:Anti-static and moisture-barrier specifications dominate cluster format selection. Composite structures combining corrugated cushioning with metallized film barriers address shock and humidity protection simultaneously.
Food & Beverage anchors procurement volume; Healthcare is climbing the fastest as ECHA restrictions redirect pharmaceutical formats toward compliant substrates.
Distribution Channel:
Channel velocity and handling intensity dictate durability and presentation requirements.
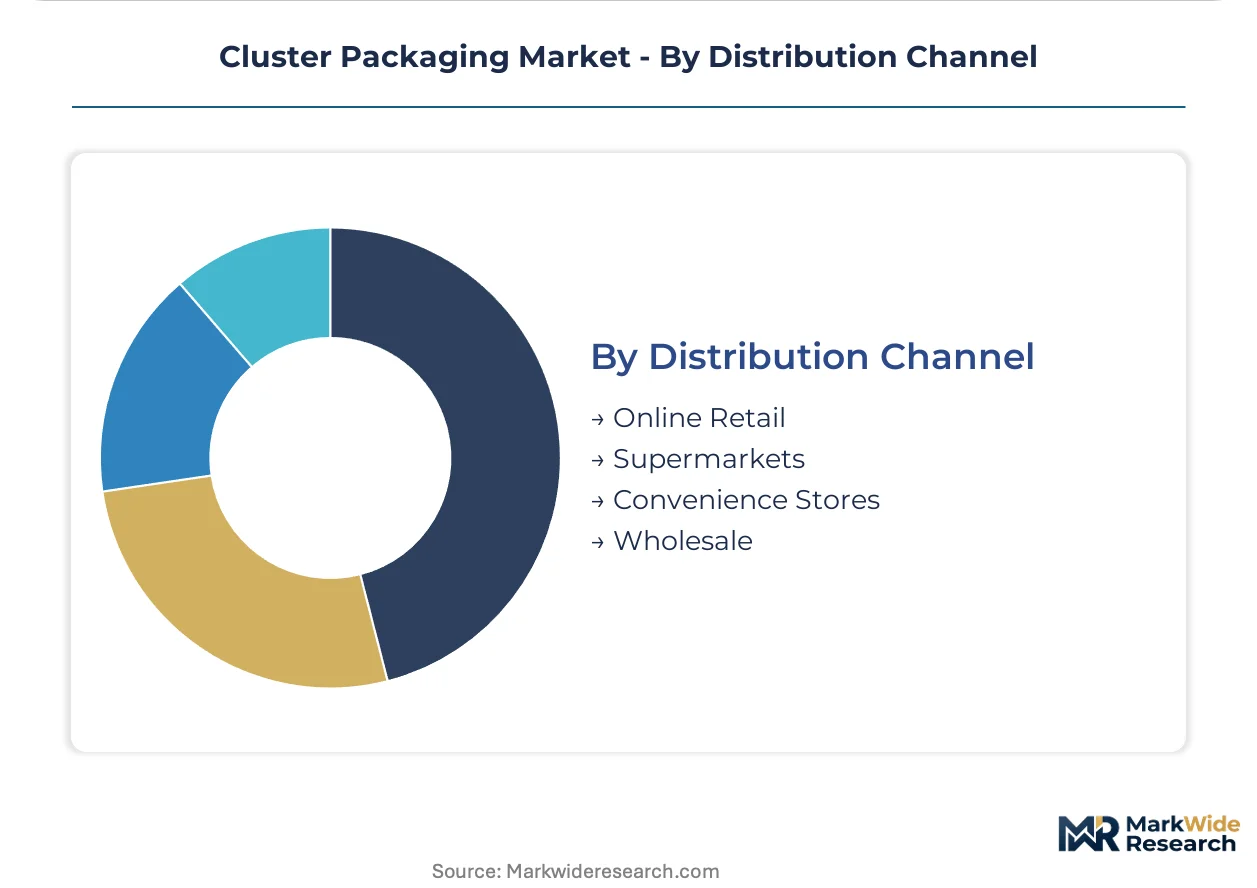
- Supermarkets:Shelf-ready secondary packaging configurations with retail-facing graphics and easy-open features. Dutch and Belgian discounters are unbundling design services from manufacturing agreements and issuing standardized specifications across private-label portfolios.
- Online Retail:E-commerce fulfillment demands damage-resistant formats surviving individual parcel handling rather than palletized distribution. Mumbai and Delhi modern trade expansion is creating demand for shelf-ready configurations previously absent in traditional Indian channels.
- Wholesale:Bulk aggregation formats prioritizing cube efficiency over retail presentation. Emerging-market channels lock plastic cluster formats in cost-advantaged positions due to film recovery infrastructure gaps.
- Convenience Stores:Small-format multipacks optimized for limited shelf space and rapid inventory turnover. Urban density in metropolitan markets drives demand for compact footprint configurations.
Supermarkets retain specification leadership; Online Retail is gaining share fastest as e-commerce penetration redirects format development priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters extract pricing premiums from standardized deposit-return formats while Indian suppliers compete on cost in infrastructure-constrained wholesale channels. This asymmetry shapes procurement patterns across the value chain.
Germany
Beverage bottlers specify corrugated six-pack carriers for deposit-return system compatibility, creating procurement pull toward fiber-based formats. The EU Packaging and Packaging Waste Regulation tightens material recovery targets, compressing substitution timelines. Converting plants in Bavaria and North Rhine-Westphalia supply standardized multi-unit configurations to consolidated retail buyers.
United States
Carbonated soft drink brand owners adopt shrink-wrapped bundles for shelf differentiation in consolidated retail environments. EPA guidelines on recycled content thresholds shape material substitution decisions across the value chain. Converting capacity concentrates in the Southeast and Midwest, serving fast-moving consumer goods bottlers with automated warehouse retrieval requirements.
India
Organized retail penetration in Mumbai and Delhi creates demand for shelf-ready secondary packaging previously absent in traditional trade channels. The BIS certification framework for packaging materials influences converter qualification requirements. Manufacturing clusters in Maharashtra and Gujarat supply modern trade expansion with corrugated multi-pack configurations.
Netherlands
Discounters issue standardized cluster format specifications across private-label beverage portfolios, displacing brand-specific carrier development. The EU Green Deal accelerates fiber-based format adoption ahead of mechanical recycling infrastructure maturation. Converting plants in the Randstad region concentrate volume with rapid specification turnaround capabilities.
China
E-commerce fulfillment demands damage-resistant formats surviving individual parcel handling rather than palletized distribution. SAMR packaging standards and dual carbon goals redirect material selection toward recyclable substrates. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta serve domestic beverage and consumer goods producers.
Cluster Packaging Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in material and equipment supply. The vendor base organizes around three tiers: integrated pulp-to-box networks, regional converting specialists, and equipment-leasing intermediaries. Two strategic archetypes dominate—asset-heavy integrated producers and asset-light specification houses. Competitive moves concentrate on geographic density expansion and digital print convergence with converting lines.
Among integrated fiber-based producers, Westrock and International Paper occupy positions anchored by captive pulp supply. Smurfit Kappa exemplifies the geographic density archetype, with converting plants positioned within delivery radius of major bottlers. Mondi Group represents the European specialization vector, anchoring demand through kraft-based cluster solutions. These three names illustrate how scale, proximity, and substrate focus differentiate competitive positioning.
| Leading Market Players |
|---|
| Westrock |
| Smurfit Kappa |
| Mondi Group |
| PET Power |
| Alpha Packaging |
| Shanghai Wellzone Packaging |
| Berry Global |
| International Paper |
| DS Smith |
| Others |
Supply Flow & Price Mechanics
Bavaria's converting plant concentration shapes downstream pricing power for corrugated six-pack carriers serving German deposit-return systems. Old corrugated container availability fluctuates with e-commerce box demand, compressing margins for converters without integrated pulp-to-box networks while rewarding fiber-based specialists with captive supply.
Pricing Analysis
The customization-premium spread separates configured-to-order beverage carriers from standardized discounter specifications in the Netherlands and Belgium. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in commodity corrugated runs through recovered pulp price volatility at OCC collection points. Wholesale channels in emerging markets exhibit highest price sensitivity; EU-regulated beverage bottlers show lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Tariff exposure between the United States and Canada disrupts kraft paperboard flow for pharmaceutical bundle formats. Supply concentrates in Germany, the United States, and China for converting capacity; India and Vietnam for emerging-market growth. Raw material dependencies include old corrugated containers, virgin kraft pulp, and polyethylene resin. Single-source vulnerability sits with specialized adhesive suppliers holding FDA food-contact notification approvals. Distribution runs through palletized truckload networks to bottler warehouses, with e-commerce fulfillment demanding parcel-ready configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cluster packaging market tracks a cyclical recovery anchored to beverage volume rebounds following retail consolidation waves. German deposit-return system standardization and Indian modern trade expansion provide sequential demand pulses.
For Market Incumbents: Entrench fiber-based format leadership by accelerating Bavaria and North Rhine-Westphalia capacity additions ahead of EU Packaging and Packaging Waste Regulation enforcement. Capture integrated pulp-to-box cost advantages as recovered pulp volatility displaces non-integrated competitors. Defend against emerging-market plastic converters through EPR fee arbitrage optimization across member states.
For New Entrants and Emerging Players: Build out digital print convergence capabilities for short-run seasonal beverage promotions, targeting craft beer brand owners with plateless customization. India's organized retail penetration in Mumbai and Delhi offers the most penetrable white-space. Lead with machine vision inspection system integration as tier-one bottler qualification mandates tighten.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because geographic density within delivery radius of major bottlers determines contract renewal rates. Target regional converting specialists with Randstad or Yangtze River Delta positioning and unutilized digital print capacity. Watch ECHA sunset date enforcement for phthalate plasticizers as inflection signal for bio-based film substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Westrock and International Paper neutralize OCC price volatility through captive containerboard mills. |
| Digital Print Line Integration | Smurfit Kappa enables seasonal promotion agility without dedicated tooling investment for craft beer clients. |
| Geographic Density Expansion | Mondi Group anchors European demand through kraft-based cluster solutions positioned within German bottler delivery radius. |
| EPR Fee Structure Arbitrage | Producers optimize manufacturing footprints across EU member states with divergent fiber versus plastic fee schedules. |
| Bio-Based Film Pilot Lines | German converters test polylactic acid blends ahead of REACH authorization deadlines for legacy phthalate formulations. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association data, and customs records. Interviews with corrugated plant managers, beverage procurement leads, pharmaceutical packaging engineers, and retail category buyers inform operating reality. Secondary validation draws from EU Packaging and Packaging Waste Regulation documentation, ECHA substance restriction databases, and EPA recycled content guidelines. Bottom-up volume modeling triangulates against top-down macroeconomic demand indicators.
Forecast inputs include substrate substitution timelines, deposit-return system expansion patterns, and e-commerce penetration curves across the analysis window. Segmentation dimensions cover product hierarchy, material platform, end-use vertical, and channel fulfillment velocity. CAGRs derive from regression analysis against historical volume trajectories and elasticity-adjusted demand projections. Industry-specific inputs incorporate flute profile optimization rates and machine vision inspection adoption thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light digital print specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Chalk Boxes Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Portion Packs Market
Packaging Containers
Dosage Cups Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Telescope Box Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Airless Bottles Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Euro Box Market