
 Foldable Mailer Box Market | 2026-2036
Foldable Mailer Box Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Mailer Box Market Foresight
E-commerce fulfillment is restructuring demand patterns across the foldable mailer box landscape, pulling volume away from traditional retail packaging toward lightweight, return-ready formats. DS Smith leverages its European recycled paper network to anchor supply for major online retailers. Smurfit WestRock sustains manufacturing scale across North American corrugated facilities. EcoEnclose differentiates through climate-neutral certification and plastic-free adhesive systems.
Foldable mailer boxes are self-erecting, flat-shipped containers manufactured from single-wall or double-wall corrugated board, typically scoring between 200 and 400 grams per square meter, designed to protect goods during transit while minimizing dimensional weight charges. Corrugated board dominates material selection for its crush resistance and printability in branded unboxing experiences. Kraft paper segments are gaining traction among subscription box operators seeking rustic aesthetic differentiation with lower basis weights. Self-lock closure types lead volume due to elimination of tape and reduced packing labor.
FDA guidelines for indirect food contact materials influence barrier coatings and adhesive chemistry selections in US-bound shipments. The EU Packaging and Packaging Waste Regulation and REACH restrictions on heavy metals in inks reshape material specifications for European market access. California's SB 54 mandates extended producer responsibility for single-use packaging, affecting specification decisions for brands distributing through West Coast logistics hubs. Stakeholders must monitor evolving state-level packaging EPR frameworks to avoid stranded inventory in high-compliance corridors.
Market Dynamics
E-commerce fulfillment networks are compressing packaging specifications toward lightweight, return-ready formats that minimize dimensional weight charges while maintaining structural integrity during last-mile transit.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recycled content mandates across member states are pulling converters toward certified fiber sourcing and closed-loop supply arrangements.
- Third-party logistics consolidation:3PL specification standardization is creating volume concentration that rewards scale-capable manufacturers with multi-year fulfillment contracts.
- Self-lock closure engineering:Tape-eliminating designs are reducing packing labor seconds per unit in high-velocity distribution centers.
Market Restraints
- Old corrugated container price volatility:OCC spot markets in North America and Europe transmit pulp cost swings directly into converter margins with limited pass-through elasticity.
- Adhesive chemistry constraints:REACH restrictions on heavy metal catalysts in hot-melt formulations are extending qualification timelines for European-bound shipments.
- Rigid plastic mailer substitution:Polyethylene-based alternatives with integrated return labels are capturing apparel segments where moisture resistance outweighs fiber-based sustainability claims.
Strategic Opportunities
- German D2C brand ecosystem:Berlin and Hamburg-based subscription box operators are specifying custom-printed kraft finishes that command premium positioning in unboxing-driven categories.
- California SB 54 extended producer responsibility:EPR frameworks are creating first-mover advantages for domestic converters offering verified post-consumer recycled content documentation.
- Digital print convergence with corrugated:Water-based inkjet systems are enabling lot-size-one customization for promotional and limited-release product launches.
Industry Challenges
- Structural design engineering talent:Finite element modeling expertise for optimizing board grades against ISTA transit testing protocols remains concentrated among legacy packaging engineering programs.
- California Air Resources Board compliance:CARB emissions thresholds for coating and adhesive operations are requiring capital deployment into thermal oxidizer upgrades at West Coast converting facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Mailer Box Market |
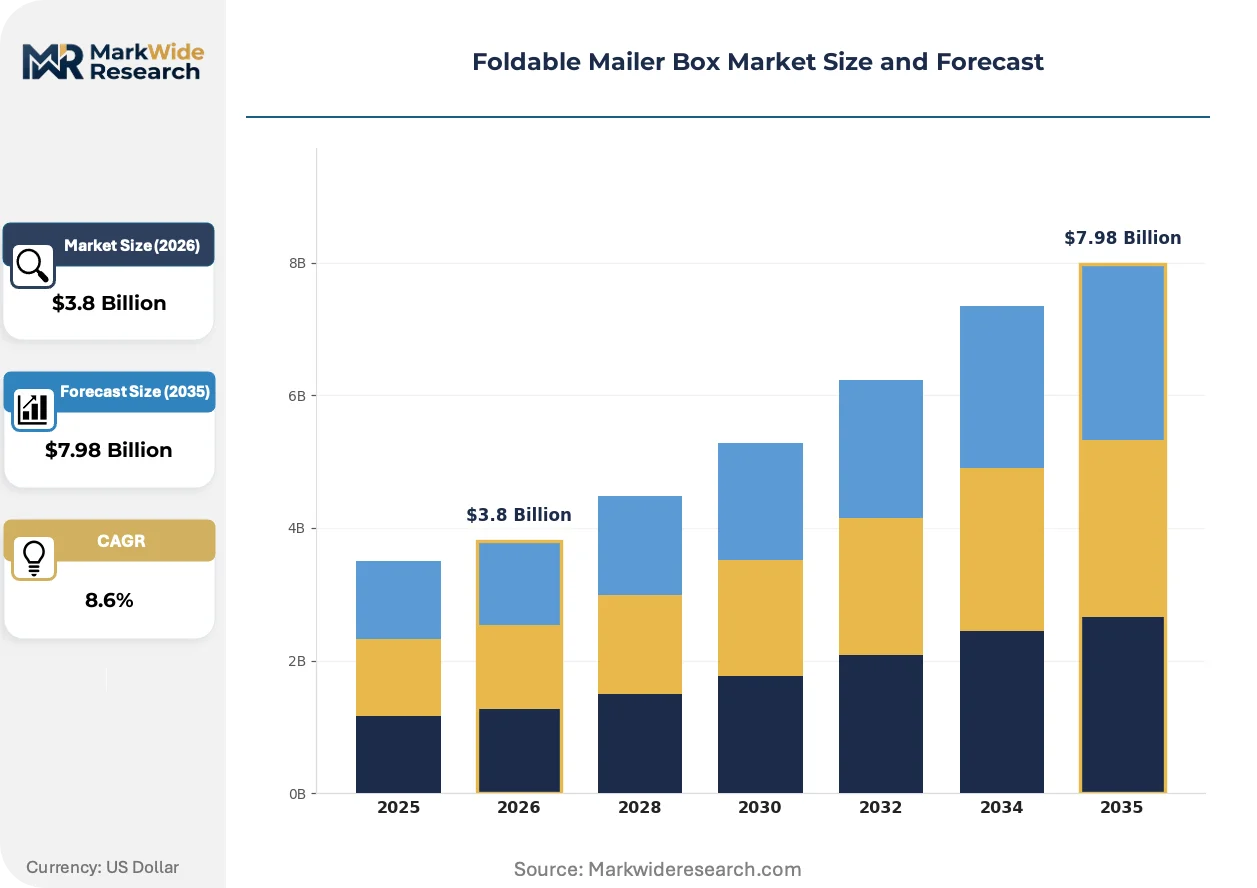
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Kraft Paper, Corrugated Board, Cardboard, Plastic Composite, Recycled Fiber End Use Industry: E-Commerce, Apparel, Electronics, Cosmetics, Consumer Goods Application: Shipping, Retail Packaging, Subscription Boxes, Gifting, Promotional Mailing Closure Type: Self-Lock, Tuck Flap, Adhesive Strip, Magnetic Seal, Snap Lock |
| Companies Covered | ULINE, Packlane, EcoEnclose, DS Smith, Smurfit WestRock, Graphic Packaging International, International Paper Company, WestRock Company, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Mailer Box Market Shifts & Advancements
Active material science and regulatory chemistry are converging to redefine performance thresholds and compliance architectures across foldable mailer specifications.
Water-based barrier coatings are overtaking wax and polyethylene laminates in moisture-sensitive applications. Subscription cosmetics and nutraceutical shippers are specifying these formulations at accelerating rates. The shift is overtaking incumbent fluorochemical treatments that face PFAS scrutiny under EPA TSCA Section 5 premanufacture notification requirements.
REACH Annex XVII restrictions on intentionally added microplastics are forcing reformulation of pressure-sensitive adhesives used in return-label integration. European converters are qualifying bio-based alternatives derived from tackified rosin esters. Food-contact and personal-care subscription segments in Germany and France are most affected, with qualification cycles extending six to twelve months beyond standard adhesive approvals.
Direct-to-consumer brands are consolidating vendor relationships around vertically integrated converters offering design-through-fulfillment service bundles. Traditional specification-by-RFP processes are contracting in favor of multi-year partnerships with shared inventory risk. This concentration is most visible among mid-market apparel and home goods operators in the US Northeast and German Rhine-Ruhr corridor.
Foldable Mailer Box Market Segmentation
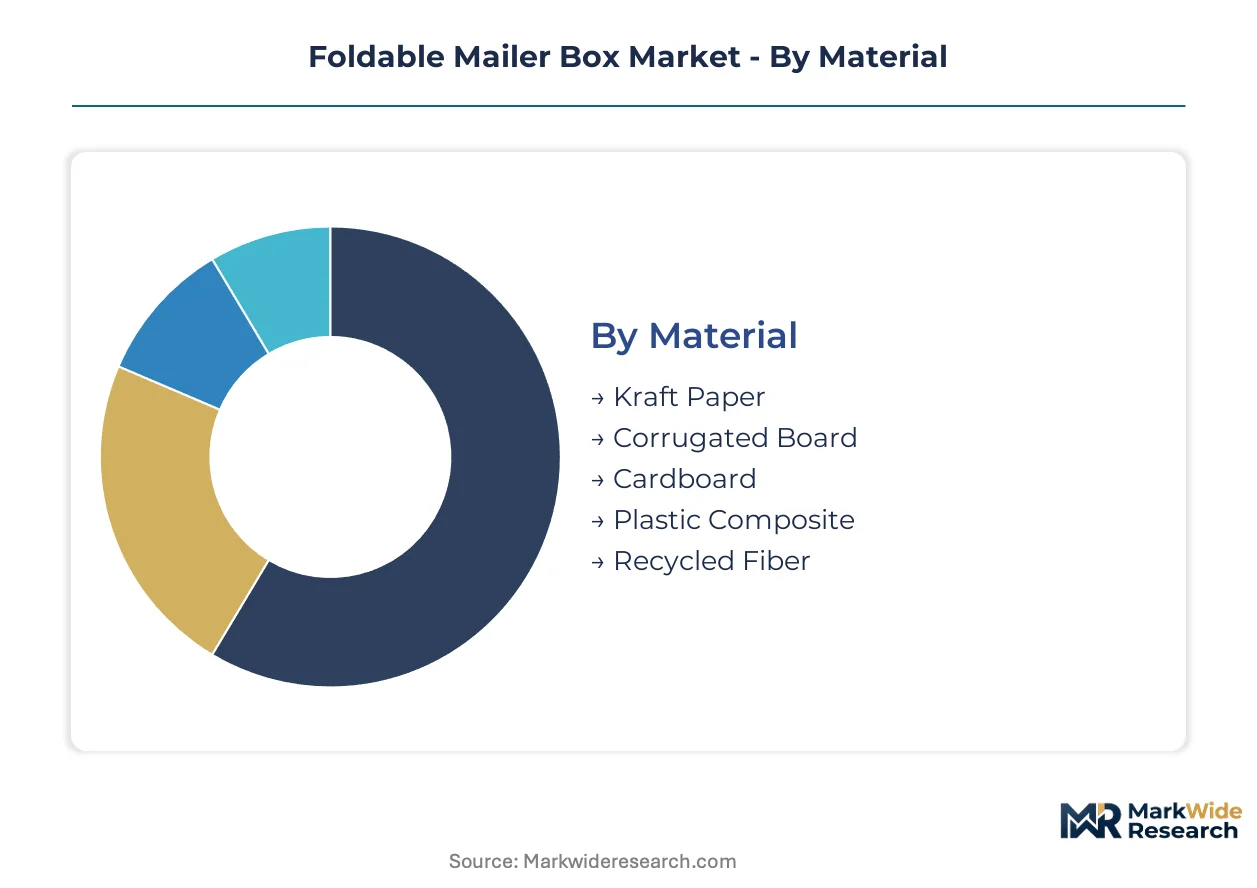
Specification divergence across foldable mailer boxes reflects divergent fulfillment economics. Material selection and closure engineering determine dimensional weight charges, return-loop functionality, and unboxing experience quality.
Material:
Converters are upgrading board specifications to meet recycled content mandates without sacrificing crush resistance.
- Corrugated Board:Single-wall and double-wall constructions between 200-400 GSM provide crush resistance for ISTA transit protocols. E-commerce fulfillment centers in Germany specify this grade for automated packing line compatibility.
- Kraft Paper:Unbleached sulfate pulp delivers rustic aesthetic differentiation at lower basis weights. Subscription box operators in Berlin and Hamburg favor custom-printed kraft finishes for unboxing-driven categories.
- Cardboard:Solid fiberboard variants suit lightweight consumer goods requiring rigid presentation without corrugated bulk.
- Plastic Composite:Polyethylene-fiber laminates address moisture-sensitive shipments where fiber-based barriers prove insufficient.
- Recycled Fiber:Post-consumer content grades are gaining specification share under California SB 54 documentation requirements.
Corrugated Board sits at the top of the volume ranking, with Recycled Fiber climbing the fastest.
End Use Industry:
Customer procurement patterns cluster around fulfillment velocity and return-loop requirements.
- E-Commerce:Third-party logistics providers standardize specifications across multi-tenant distribution networks. Self-lock closures and lightweight formats reduce labor seconds per unit in high-velocity centers.
- Apparel:Return-ready formats with integrated label pockets dominate. Moisture resistance requirements in this segment drive qualification of water-based barrier coatings over wax laminates.
- Electronics:Anti-static specifications and crush resistance for fragile components require double-wall corrugated or foam-insert compatibility.
- Cosmetics:FDA indirect food contact compliance shapes adhesive and coating selections for subscription skincare shipments.
- Consumer Goods:Mass-market retail distribution favors cost-optimized single-wall formats with standard tuck-flap closures.
E-Commerce commands the largest procurement volumes, though Apparel is expanding most quickly.
Application:
Usage context dictates structural reinforcement and print finish specifications.
- Shipping:Transit-tested designs prioritize dimensional weight minimization and ISTA protocol compliance over aesthetic refinement.
- Subscription Boxes:Unboxing experience requirements drive investment in direct-print kraft surfaces and magnetic or self-lock premium closures.
- Retail Packaging:Shelf-ready formats balance stack strength with point-of-sale print quality for branded display.
- Gifting:Premium segments specify rigid setups with foil stamping and ribbon integration for seasonal peaks.
- Promotional Mailing:Lot-size-one digital print compatibility enables campaign-specific customization with minimal tooling costs.
Shipping accounts for the highest unit volumes, while Subscription Boxes show the steepest expansion trajectory.
Closure Type:
Engineering selection directly impacts packing labor economics and return-loop functionality.
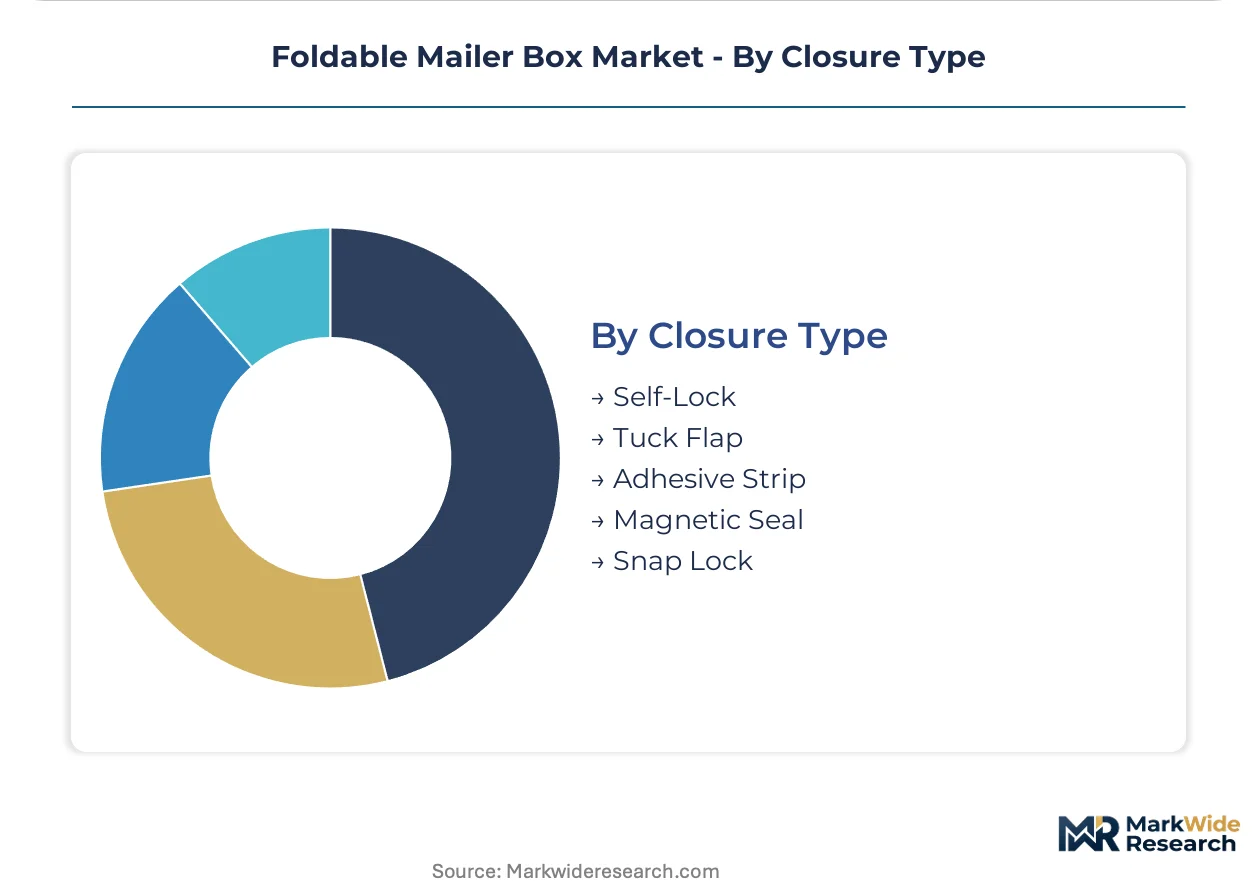
- Self-Lock:Interlocking tab designs eliminate tape application and reduce packing time. This format dominates 3PL specification standards across North American and European fulfillment networks.
- Adhesive Strip:Pressure-sensitive closures enable clean return paths but face REACH Annex XVII reformulation requirements for European-bound shipments.
- Tuck Flap:Basic friction-fit designs persist in cost-sensitive consumer goods segments with minimal return requirements.
- Magnetic Seal:Premium subscription and gifting applications specify hidden magnet integration for reusable unboxing experiences.
- Snap Lock:Audible closure confirmation suits high-value electronics requiring tamper-evidence without adhesive residue.
Self-Lock leads procurement specifications, with Magnetic Seal gaining share fastest in premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German Rhine-Ruhr corridor concentrates third-party logistics specification authority for European foldable mailer procurement. Berlin and Hamburg anchor direct-to-consumer brand clusters that drive custom-printed kraft demand. California's SB 54 implementation is reshaping West Coast converter qualification requirements.
United States
Third-party logistics providers in the Chicago and Dallas-Fort Worth metro areas standardize self-lock closure specifications across multi-tenant fulfillment networks. California SB 54 mandates extended producer responsibility documentation for post-consumer recycled content claims. The Inland Empire logistics cluster east of Los Angeles is requiring thermal oxidizer upgrades at converting facilities to meet CARB emissions thresholds.
Germany
Berlin-based subscription cosmetics operators and Hamburg direct-to-consumer apparel brands are specifying water-based barrier coatings over wax laminates. The EU Packaging and Packaging Waste Regulation tightens recycled content mandates that pull converters toward certified fiber sourcing. The Rhine-Ruhr corridor's 3PL consolidation is creating volume concentration that rewards scale-capable manufacturers with multi-year contracts.
China
E-commerce fulfillment centers in the Yangtze River Delta and Pearl River Delta are compressing specifications toward lightweight formats that minimize dimensional weight charges. The country's dual carbon goals are accelerating converter investment in recycled fiber processing capacity. Shenzhen and Guangzhou-based exporters are qualifying bio-based adhesive alternatives to meet REACH Annex XVII restrictions on European-bound shipments.
United Kingdom
London and Southeast England direct-to-consumer brands are consolidating vendor relationships around vertically integrated converters offering design-through-fulfillment service bundles. The UK implementation of EU-derived packaging EPR frameworks is creating first-mover advantages for domestic converters with verified recycled content documentation. The Midlands logistics corridor is seeing specification standardization across apparel and home goods subscription operators.
India
Maharashtra and Gujarat-based e-commerce fulfillment networks are adopting self-lock closure formats to reduce packing labor seconds per unit in high-velocity distribution centers. The Bureau of Indian Standards is developing corrugated board specifications for transit-tested designs. Mumbai and Ahmedabad industrial clusters are investing in water-based inkjet systems for lot-size-one customization in promotional mailing applications.
Foldable Mailer Box Market Competitive Landscape
Capacity expansion dominates the current landscape as converters deploy capital into recycled fiber processing and digital print integration. The market exhibits tiered concentration with integrated paperboard producers, regional converting specialists, and vertically integrated design-through-fulfillment service providers competing across distinct value chain positions. Three archetypes define competitive positioning: scale-driven integrated producers, sustainability-certified specialists, and logistics-integrated converters. M&A activity and geographic expansion represent the dominant competitive moves as players seek multi-regional qualification for 3PL specification standards.
Among integrated paperboard producers, DS Smith and Smurfit WestRock exemplify scale-capable manufacturers with multi-regional corrugated facility networks. EcoEnclose occupies a position within the sustainability-certified specialist tier, representing converters that differentiate through climate-neutral certification and plastic-free adhesive systems. These three companies anchor the competitive structure across European and North American fulfillment corridors.
| Leading Market Players |
|---|
| ULINE |
| Packlane |
| EcoEnclose |
| DS Smith |
| Smurfit WestRock |
| Graphic Packaging International |
| International Paper Company |
| WestRock Company |
| Packaging Corporation of America |
| Others |
Supply & Pricing Matrix
OCC spot market volatility in North America and Europe cascades through converter margins into three distinct pricing tiers, with e-commerce fulfillment centers bearing the steepest pass-through pressure during pulp cost spikes.
Pricing Analysis
Input-cost pass-through from old corrugated container spot markets drives pricing stratification across premium, standard, and economy tiers. Certification grade under EU Packaging and Packaging Waste Regulation mandates and volume scale commitments to 3PL networks differentiate contract rates. Cost compression in standard-grade single-wall formats is intensifying because Chinese recycled fiber capacity expansion feeds global pulp substitution. Mass-market consumer goods distributors exhibit highest price sensitivity, while Berlin-based D2C subscription operators absorb premium positioning for custom-printed kraft finishes.
Supply Chain Analysis
Dual-sourcing requirements from major 3PL networks mandate multi-supplier qualification across Germany, the United States, and China to mitigate single-source vulnerability. Recycled fiber supply draws from municipal collection networks in the EU, post-industrial streams in North America, and imported pulp from Southeast Asian processing hubs. Distribution runs through vertically integrated converters with captive corrugating capacity and regional specialists dependent on merchant board supply. REACH Annex XVII adhesive reformulation timelines extend qualification cycles, creating inventory risk for European-bound shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce fulfillment growth provides a stable compounding foundation, with regulatory mandates for recycled content and extended producer responsibility locking in durable demand expansion.
For Market Incumbents: Lock in multi-year 3PL contracts with shared inventory risk arrangements before California SB 54 documentation requirements harden qualification barriers. DS Smith and Smurfit WestRock should accelerate thermal oxidizer upgrades at West Coast facilities to preempt CARB emissions enforcement. Backward integration into recycled fiber processing secures margin protection against OCC spot volatility. For New Entrants and Emerging Players: California SB 54 in the United States opens a window for domestic converters with verified post-consumer recycled content documentation to capture first-mover share in the Inland Empire logistics corridor. White-space targets include water-based barrier coating specialization for cosmetics subscription shippers and digital print integration for lot-size-one promotional mailing. A design-through-fulfillment service bundle positions new entrants against specification-by-RFP legacy processes. For Investors and Strategic Acquirers: Asymmetric upside sits with sustainability-certified specialists possessing climate-neutral certification and plastic-free adhesive systems. The 5-10 year viability window favors converters with proven REACH compliance and multi-regional 3PL qualification. Watch for inflection when EU Packaging and Packaging Waste Regulation enforcement triggers stranded inventory events at non-compliant competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Fiber Processing Capacity Expansion | Captive OCC supply insulates margins from pulp spot volatility in North American markets. |
| Water-Based Barrier Coating Qualification | PFAS-free formulations unlock cosmetics and nutraceutical subscription segments under EPA scrutiny. |
| Digital Print System Integration | Inkjet compatibility enables lot-size-one customization for D2C promotional campaigns. |
| Multi-Regional 3PL Qualification | Specification standardization across Chicago, Dallas-Fort Worth, and Rhine-Ruhr corridors secures volume concentration. |
| Design-Through-Fulfillment Service Bundling | Vertically integrated partnerships reduce customer procurement friction against RFP-based competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with corrugated plant managers, 3PL procurement leads, D2C brand supply chain directors, and adhesive formulation specialists with secondary validation against customs trade data, FEFCO industry reports, EPA TSCA filings, and SEC 10-K disclosures from integrated paperboard producers. Bottom-up volume modeling and top-down market sizing triangulated segment estimates.
Segment-weighting across material grades, closure types, end-use industries, and regional fulfillment corridors shaped the analytical framework across the analysis window. CAGRs derived from historical trajectory analysis and elasticity-adjusted demand projections incorporated e-commerce penetration rates, recycled content mandate compliance timelines, and dimensional weight pricing evolution from major carriers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt OCC price spikes or accelerated PFAS regulatory restrictions. Deviation in EU Packaging and Packaging Waste Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Plasma Bottle Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
Insulated Icebox Market
Packaging Containers
Euro Box Market
Packaging Containers
Airless Bottles Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Portion Packs Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Dosage Cups Market
Packaging Containers
Bottles Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Snap Single Dose Dispensers Market