
 Industrial Mixers Market | 2026-2036
Industrial Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Mixers Market Outlook
Direct distribution from OEMs to end-user engineering departments is tilting away from traditional distributor networks. Sulzer leverages its aftermarket service infrastructure to sustain long-term contracts with chemical processors. SPX Flow anchors its position through dedicated food and beverage application centers. Alfa Laval competes on heat-transfer-integrated mixer designs that reduce footprint in pharmaceutical cleanrooms.
Industrial mixers are mechanical devices that apply controlled shear, turbulence, or laminar flow to blend, disperse, or react multiphase materials, typically operating at motor powers from 0.5 kW to over 1,000 kW with shaft speeds calibrated to Reynolds number regimes. Their primary purpose is to achieve batch uniformity, reaction consistency, or phase stability in continuous process lines. Batch mixers retain the largest installed base across food processing and pharmaceuticals, though continuous mixers are gaining share in high-volume chemical manufacturing where residence-time control directly yields throughput gains. Magnetic mixing technology leads in aseptic pharmaceutical applications because eliminated shaft seals remove contamination vectors and reduce validation burden.
FDA cGMP guidelines and EPA emissions standards govern material selection and seal design in US installations, while REACH restricts certain elastomer and coating chemistries in European equipment. OSHA lockout/tagout requirements shape mixer guard and drive-access configurations. Stakeholders must monitor evolving PFAS restrictions and ATEX zone classifications, as these will determine which motor and sealing architectures remain certifiable across jurisdictions.
Market Dynamics
Magnetic mixing architectures are compressing validation timelines in pharmaceutical cleanrooms while REACH and FDA cGMP tighten material specifications, forcing simultaneous technology migration and compliance reinvestment across installed bases.
Growth Catalysts
- High-viscosity chemical formulations:Specialty polymer and adhesive producers in Germany's Ruhr cluster are procuring premium shear-intensive units. These installations demand precision torque control and heated jacketing.
- REACH material restrictions:ECHA's expanding substance restrictions on PFAS and certain elastomers are disqualifying legacy seal materials. Equipment vendors with pre-certified compliant designs capture replacement cycles.
- Magnetic drive technology:Eliminated mechanical seals remove contamination vectors in aseptic bioprocessing. This architecture reduces cleanroom validation burden and maintenance downtime.
Market Restraints
- Stainless steel alloy volatility:Nickel and molybdenum price swings compress margin predictability for fabricated wetted components. Foundry capacity concentration in China amplifies input cost exposure.
- Specialized gearbox supply concentration:Precision helical and planetary reducers for high-torque mixers concentrate among German and Italian suppliers. Geographic supply risk elevates lead times during demand spikes.
- Mechanical seal substitution ceiling:Magnetic drives face power transmission limits above certain viscosity-threshold applications. Some high-solids chemical processes remain locked into conventional sealed architectures.
Strategic Opportunities
- Modular continuous mixing skids:Plug-and-play process intensification units bypass traditional field fabrication. This format accelerates deployment in contract manufacturing organizations seeking rapid capacity scaling.
- Heat-transfer integration convergence:Combining mixing and thermal management into single-vessel designs reduces pharmaceutical cleanroom footprint. Alfa Laval and specialized vendors are anchoring positions here.
- Aftermarket service unbundling:Predictive maintenance contracts and remote vibration monitoring create recurring revenue streams. Sulzer's service infrastructure demonstrates this model's viability with chemical processors.
Industry Challenges
- Cross-functional commissioning expertise:Integrated mixer-skid deployments demand simultaneous mechanical, automation, and process chemistry competency. Talent scarcity in this intersection extends project timelines.
- Legacy DCS integration friction:Modern variable-frequency drive and torque-monitoring systems must interface with decades-old distributed control architectures. Protocol translation and safety certification add cost and delay.
- Multi-jurisdiction certification stacking:Equipment destined for multinational chemical firms must simultaneously satisfy ATEX, FDA cGMP, and REACH. Parallel validation tracks compress delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Mixers Market |
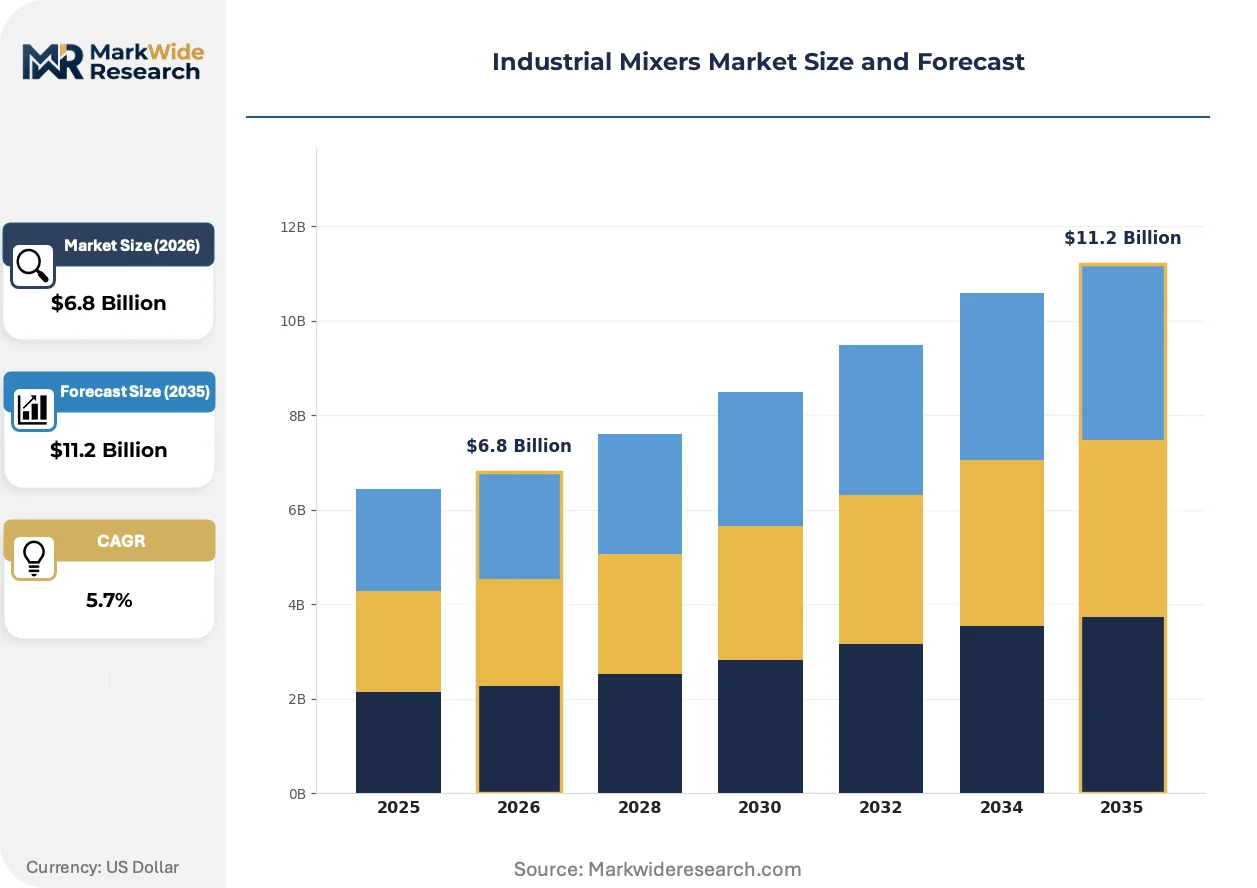
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Mixers, Continuous Mixers, Portable Mixers, Laboratory Mixers End User: Food Processing, Chemical Manufacturing, Pharmaceuticals, Paints & Coatings Technology: Mechanical Mixing, Magnetic Mixing, Pneumatic Mixing, Ultrasonic Mixing Application: Homogenization, Dissolution, Emulsification, Coagulation |
| Companies Covered | Sulzer, EKATO Holding, SPX Flow, Silverson Machines, Charles Ross & Son Company, Alfa Laval, Xylem, IKA-Werke, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Mixers Market Strategic Shifts
Computational fluid dynamics and additive manufacturing are compressing development cycles while regulatory material bans force simultaneous redesign of legacy product lines across all major jurisdictions.
Magnetic drive systems eliminate mechanical seals through synchronous torque transmission across a containment shell. Pharmaceutical bioreactor operators in Switzerland and Ireland are specifying these architectures for new aseptic installations. Conventional packed-gland and mechanical seal configurations are rendering obsolete in facilities where contamination risk carries batch-rejection costs.
REACH Annex XVII expansions and the EU Green Deal's chemical sustainability criteria are restricting per- and polyfluoroalkyl substances in mixer wetted parts. Equipment fabricators must reformulate coatings, gaskets, and bearing lubricants to maintain market access. German specialty chemical clusters face the most acute compliance pressure given their concentration of export-oriented pharmaceutical and fine chemical production.
Direct OEM-to-engineering-department engagement is displacing traditional distributor networks for complex application engineering. Food and beverage processors in Denmark and the Netherlands are consolidating vendor relationships around dedicated application centers. This channel compression is most visible in segments where process-specific customization outweighs standard catalog selection.
Industrial Mixers Market Segmentation
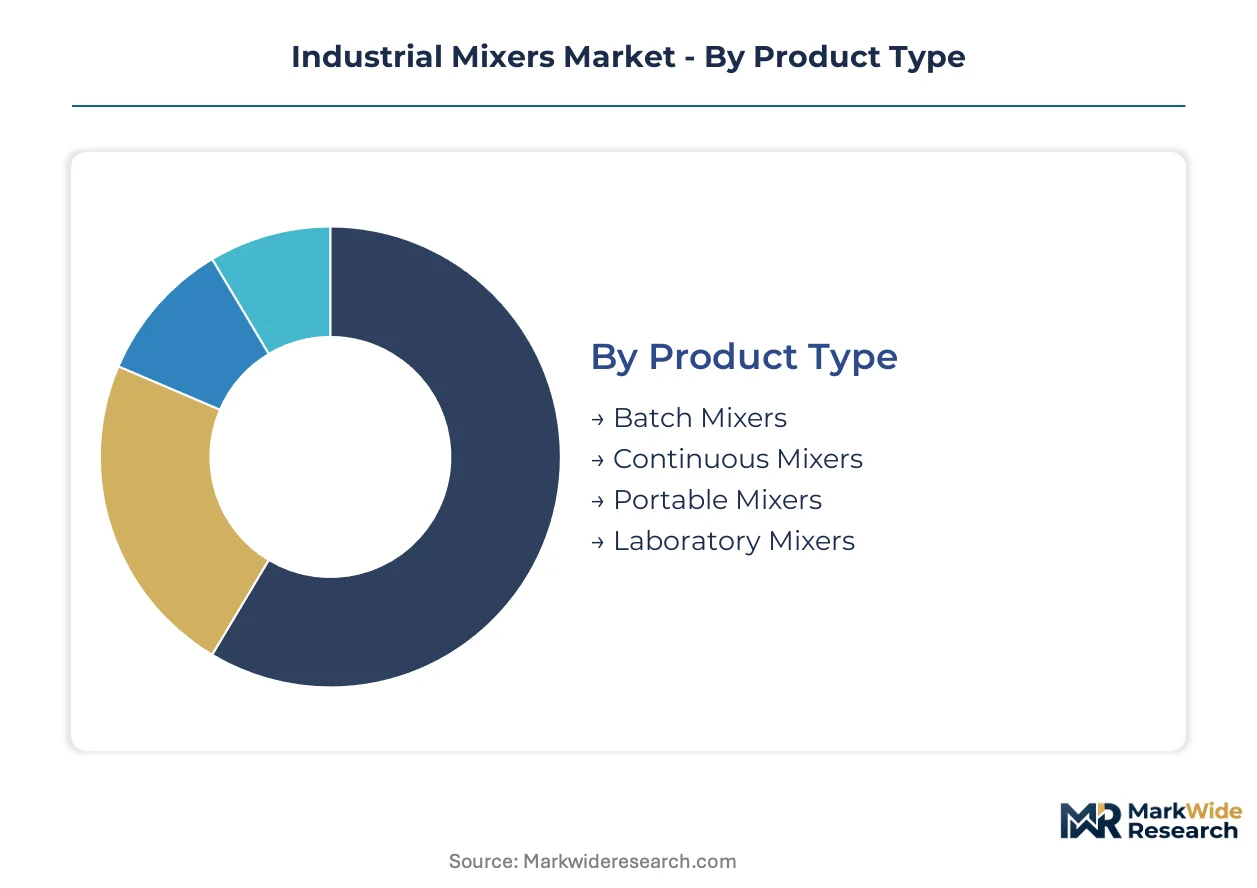
Mixer procurement cycles vary dramatically across product architectures and end-use sectors. Food processors replace portable units on compressed timelines, while chemical plants run batch vessels for decades. Understanding these replacement rhythms shapes inventory positioning and aftermarket service scheduling.
Product Type:
Replacement velocity separates this category sharply: portable and laboratory units turn over fastest, while installed batch and continuous systems persist for 15-25 years.
- Batch Mixers:These vessels operate on discrete loading cycles with defined residence times, accommodating viscosity swings through variable-speed drives and interchangeable impeller geometries. Chemical manufacturing plants in Germany's Ruhr cluster specify heated jacketing and precision torque control for polymer synthesis. Batch architecture dominates installed base across food processing and pharmaceuticals due to formulation flexibility and easier validation documentation.
- Continuous Mixers:Residence-time-controlled designs deliver steady-state throughput for high-volume chemical operations, with screw, paddle, or static mixing elements configured to Reynolds number regimes. Specialty adhesive producers in Germany procure premium shear-intensive continuous units where throughput gains directly yield margin expansion. These systems demand higher upfront capital but reduce labor intensity per ton output.
- Portable Mixers:Drum-mounted or tote-agitation units serve small-batch contract manufacturers and pilot-scale operations with rapid redeployment between product campaigns.
- Laboratory Mixers:Bench-scale units with sub-kilowatt drives support formulation development and process validation before commercial scale-up.
Batch Mixers dominate installed base. Continuous Mixers are where expansion concentrates.
End User:
Margin structure and regulatory burden differentiate demand profiles, with pharmaceuticals paying certification premiums and chemicals prioritizing throughput economics.
- Chemical Manufacturing:High-viscosity formulations and abrasive slurries drive specification toward hardened wetted components and heated jacketing. REACH compliance and PFAS restrictions force simultaneous material migration across installed bases. Specialty polymer and adhesive producers in Germany's industrial clusters anchor premium equipment procurement.
- Pharmaceuticals:Aseptic bioprocessing demands magnetic drive architectures that eliminate shaft seals and reduce contamination vectors. FDA cGMP validation timelines compress when equipment arrives with pre-certified documentation. Swiss and Irish bioreactor operators specify these systems for new installations.
- Food Processing:Sanitary stainless construction and clean-in-place compatibility dominate specifications, with batch vessels retaining largest share in dairy and beverage applications.
- Paints & Coatings:High-solids dispersion requirements sustain demand for conventional sealed architectures where magnetic drives face power transmission limits.
Chemical Manufacturing anchors volume procurement. Pharmaceuticals is climbing the fastest.
Technology:
Architecture selection hinges on contamination risk tolerance, power density requirements, and maintenance access constraints.
- Magnetic Mixing:Synchronous torque transmission across a containment shell eliminates mechanical seals entirely. Pharmaceutical cleanroom operators in Switzerland and Ireland specify these for aseptic bioprocessing where batch-rejection costs dwarf equipment premiums. Reduced validation burden and maintenance downtime justify higher capital outlay.
- Mechanical Mixing:Conventional packed-gland and mechanical seal configurations persist where viscosity-threshold applications exceed magnetic drive power limits. High-solids chemical processes remain locked into these architectures despite higher contamination risk.
- Pneumatic Mixing:Compressed-air-driven agitation serves explosion-risk environments and remote installations without electrical infrastructure.
- Ultrasonic Mixing:Acoustic cavitation achieves micro-scale dispersion for nanoemulsion and cell-lysis applications in laboratory and pilot settings.
Mechanical Mixing retains largest legacy footprint. Magnetic Mixing is gaining share fastest.
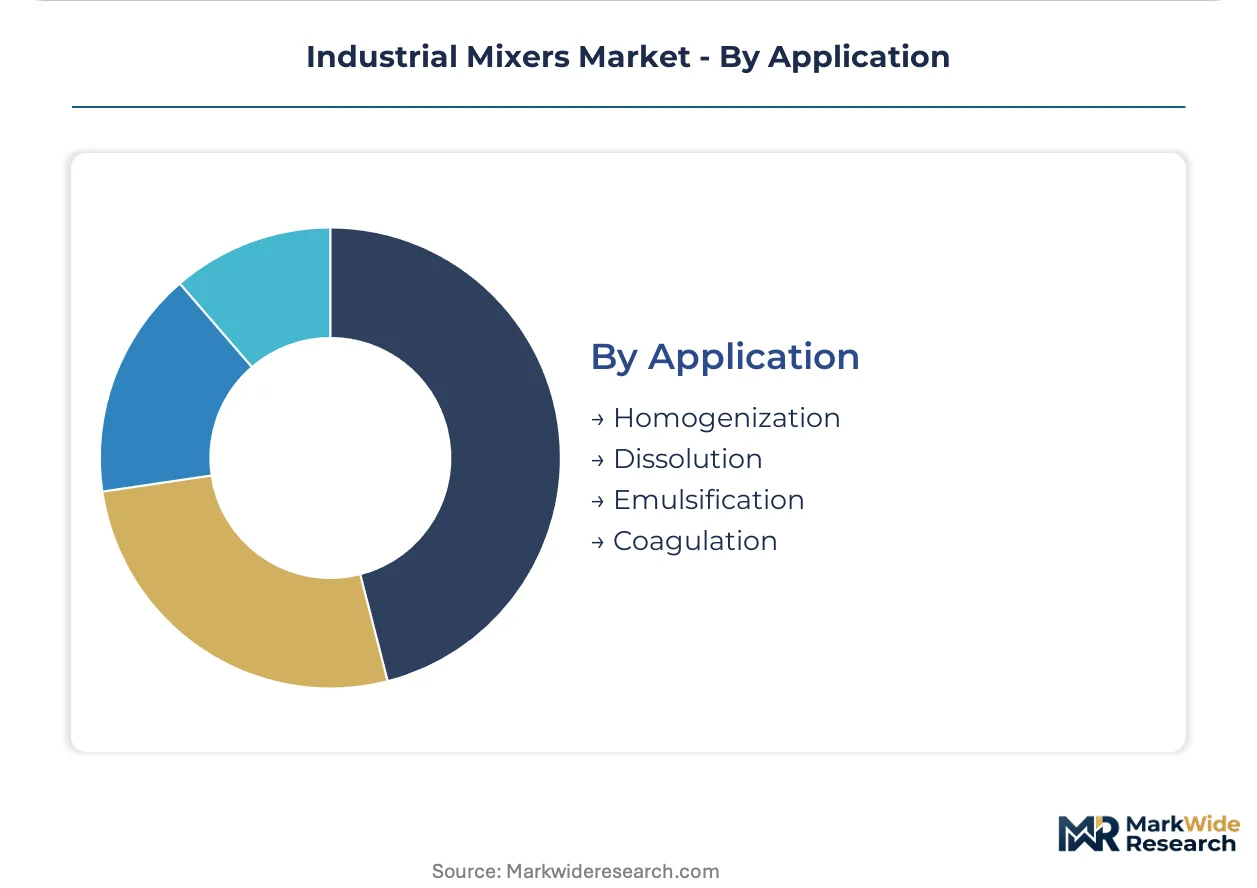
Application:
Process physics determine impeller selection, with shear intensity and residence time distribution calibrated to each unit operation.
- Homogenization:High-shear rotor-stator or high-pressure valve designs reduce droplet size for stable emulsions and suspensions. Dairy and beverage processors in Denmark deploy these for extended-shelf-life product lines.
- Emulsification:Phase-stabilization requirements drive specification toward controlled shear gradients and surfactant addition protocols. Paints and coatings formulators balance dispersion quality with throughput economics.
- Dissolution:Solid-liquid mass transfer optimization governs impeller geometry and tank aspect ratio selection.
- Coagulation:Controlled destabilization of colloidal suspensions demands precise energy input to achieve floc structure without fragmentation.
Homogenization commands premium pricing. Emulsification shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical cargo throughput anchors European mixer procurement, while China's Yangtze River Delta manufacturing corridor concentrates Asian demand. Rail-linked industrial corridors in Germany and pipeline-fed petrochemical zones on the US Gulf Coast complete the infrastructure map.
United States
FDA cGMP validation requirements and EPA emissions standards drive specification upgrades across pharmaceutical and chemical installations. OSHA lockout/tagout mandates reshape guard and drive-access configurations for new equipment. The Gulf Coast petrochemical corridor from Houston to Baton Rouge sustains premium procurement for high-viscosity polymer processing.
Germany
REACH Annex XVII restrictions on PFAS and elastomer chemistries force simultaneous material migration across installed bases. ECHA compliance deadlines compress replacement cycles for legacy seal configurations. The Ruhr industrial cluster anchors specialty chemical demand for heated jacketing and precision torque control systems.
China
GB standards alignment and MIIT industrial upgrading programs accelerate domestic mixer fabrication capability. Dual carbon goals tighten energy efficiency requirements for motor and drive systems. The Yangtze River Delta chemical processing belt concentrates procurement for high-volume continuous mixing installations.
Switzerland
Swissmedic aseptic processing guidelines elevate magnetic drive specifications for bioreactor operations. Contamination risk tolerance sits at zero given batch-rejection cost structures. Basel's pharmaceutical manufacturing cluster specifies seal-free architectures for new cleanroom deployments.
India
CDSCO pharmaceutical manufacturing standards and BIS equipment certification expand addressable market for compliant vendors. PLI scheme incentives for active pharmaceutical ingredient production drive capital expenditure timelines. Gujarat's specialty chemical zones and Maharashtra's formulation corridors concentrate import substitution demand.
Industrial Mixers Market Competitive Environment
On the supply side, the industry is consolidating around application-specific engineering competence rather than scale alone. Mid-cap specialists with dedicated food, pharmaceutical, or chemical expertise capture premium pricing against catalog distributors. Three archetypes dominate: integrated process technology conglomerates, dedicated mixing engineering houses, and diversified fluid handling groups. M&A activity targets aftermarket service capabilities, while geographic expansion focuses on regulatory pre-certification in multiple jurisdictions.
Among Swiss and Swedish engineering conglomerates, Sulzer and Alfa Laval occupy positions defined by aftermarket infrastructure and heat-transfer integration respectively. German specialist EKATO Holding exemplifies the dedicated mixing engineering archetype with torque-intensive system focus. These three represent distinct competitive vectors: service-led retention, technology convergence, and application depth.
| Leading Market Players |
|---|
| Sulzer |
| EKATO Holding |
| SPX Flow |
| Silverson Machines |
| Charles Ross & Son Company |
| Alfa Laval |
| Xylem |
| IKA-Werke |
| GEA Group |
| Others |
Value Chain & Pricing Dynamics
Commodity volatility in nickel and molybdenum alloy markets compresses margin predictability for fabricated wetted components while simultaneously widening spreads between premium certified units and standard catalog equipment. Foundry capacity concentration in China amplifies input cost exposure, forcing tiered procurement strategies that separate REACH-compliant pharmaceutical-grade systems from economy batch vessels serving food processing.
Pricing Analysis
Volume-discount tiering structures dominate capital equipment transactions, with three-tier pricing stratification across premium magnetic-drive pharmaceutical systems, standard mechanical-seal chemical units, and economy portable agitators for food processing. Certification grade under the FDA cGMP and REACH frameworks commands substantial premiums, while stainless steel alloy surcharges introduce volatility into quoted pricing. Cost compression in mid-tier batch vessels intensifies as Chinese fabricators expand export capacity. Contract manufacturing organizations exhibit highest price sensitivity due to campaign-based redeployment needs, whereas Swiss bioreactor operators prioritize contamination-risk mitigation over capital outlay.
Supply Chain Analysis
Tariff exposure between China and Western pharmaceutical markets dominates supply chain risk planning for precision gearbox and magnetic drive subassemblies. Foundry capacity concentrates in China, Germany, and Italy for specialty stainless alloys and helical reducers. Raw material procurement draws from Indonesian nickel mines, Chilean molybdenum concentrates, and domestic European scrap recycling streams. Single-source vulnerability persists for high-torque planetary gearboxes from German and Italian specialists. Distribution runs through direct OEM-to-engineering-department channels for complex pharmaceutical applications, with traditional distributor networks retaining food and beverage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to specialty chemical capital expenditure cycles in Germany's Ruhr cluster, where polymer and adhesive expansion programs are reactivating premium equipment procurement after deferred maintenance periods.
For Market Incumbents: Harden aftermarket service infrastructure to capture replacement cycles driven by REACH Annex XVII material restrictions on PFAS and legacy elastomers. Expand in-house foundry capacity or captive supply agreements for nickel-molybdenum alloys to buffer against Chinese commodity volatility. Prioritize pre-certification investments across FDA cGMP, ATEX, and REACH frameworks to compress delivery windows for multinational chemical firms. For New Entrants and Emerging Players: Modular continuous mixing skids for contract manufacturing organizations in India and Southeast Asia represent the most penetrable entry point, given rapid capacity scaling needs and limited incumbent service presence. Laboratory and pilot-scale magnetic mixing systems for bioprocessing startups offer secondary white-space with lower capital barriers. A go-to-market strategy anchored to remote predictive maintenance subscriptions can differentiate against established OEMs with legacy service models. For Investors and Strategic Acquirers: ECHA's expanding PFAS restriction timelines reshape the acquisition landscape toward vendors with pre-certified compliant seal architectures and reformulated coating portfolios. Long-term viability centers on equipment suppliers capable of simultaneous technology migration and compliance reinvestment across installed bases. The signal to monitor is replacement cycle acceleration in German specialty chemical clusters as compliance deadlines approach.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Foundries | Captive nickel-molybdenum supply buffers margin compression from Chinese commodity volatility. |
| Magnetic Drive Technology Licensing | Seal-free architectures capture pharmaceutical cleanroom procurement in Switzerland and Ireland. |
| REACH Pre-Certification Investment | Pre-validated equipment compresses delivery windows for ECHA compliance deadlines. |
| Predictive Maintenance Service Unbundling | Remote vibration monitoring creates recurring revenue streams with chemical processors. |
| Joint Venture in Yangtze River Delta | Local fabrication capability addresses GB standards alignment and MIIT efficiency mandates. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, procurement leads at downstream chemical and pharmaceutical firms, aftermarket service directors, and technical R&D managers at mixing equipment specialists. Secondary validation drew from customs and trade data, SEC filings of publicly listed process technology conglomerates, ECHA substance restriction databases, and FDA cGMP guidance documents. Bottom-up equipment shipment analysis was triangulated against top-down capital expenditure surveys across end-use industries.
Calibration against historical replacement cycles and regulatory compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-use industry, technology type, application physics, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and expansion capital commitments. Forecast inputs incorporated nickel and molybdenum price trajectories, ECHA restriction implementation schedules, and pharmaceutical cleanroom construction pipelines.
Macroeconomic conditions sit as an overlay; deviation in specialty chemical capital expenditure cycles or stainless steel alloy pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Steel Processing Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Plastic Molds Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Modified Wood Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Global Jet Mill Market
Industrial Materials
Industrial Kiln Market
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Static Mixer Market