
 Selenium Sulfide Market | 2026-2036
Selenium Sulfide Market Size, Share, and Industry Trends Forecast 2026-2036
Selenium Sulfide Market Analytics
The gap between pharmaceutical-grade selenium sulfide and commodity feedstock is restructuring procurement dynamics across the value chain. BASF SE leverages its integrated chemical platform to sustain supply security for regulated applications. Hubei Xinjing New Material Co., Ltd. anchors Chinese production capacity for regional dermatological formulators. Omkar Specialty Chemicals Ltd. specializes in fine-chemical grades that meet stringent purity thresholds for therapeutic use.
Selenium sulfide is an inorganic compound with the formula SeS₂, typically supplied as a bright orange to reddish powder with purity grades ranging from 99% to 99.9% for pharmaceutical applications; manufacturers synthesize it via direct combination of elemental selenium and sulfur under controlled temperature conditions, primarily for incorporation into anti-seborrheic and anti-fungal topical preparations. The shampoo segment dominates volume consumption due to established over-the-counter distribution through retail and online stores, while therapeutic applications command premium pricing through hospital and pharmacy channels where clinical validation requirements create margin concentration. Cream and lotion formats occupy narrower but defensible positions in prescription dermatology, with packaging in tubes and bottles reflecting distinct regulatory pathways and patient compliance considerations.
FDA oversight of active pharmaceutical ingredients governs US market access for selenium sulfide destined for drug products, while REACH registration requirements in Europe impose full toxicological dossiers on importers and manufacturers. India's CDSCO mandates batch testing and manufacturing facility inspections for selenium sulfide used in domestically marketed anti-dandruff formulations. Stakeholders must monitor evolving classification debates under the EU CLP regulation and prepare for potential reclassification that could reshape formulation strategies and labeling obligations across export markets.
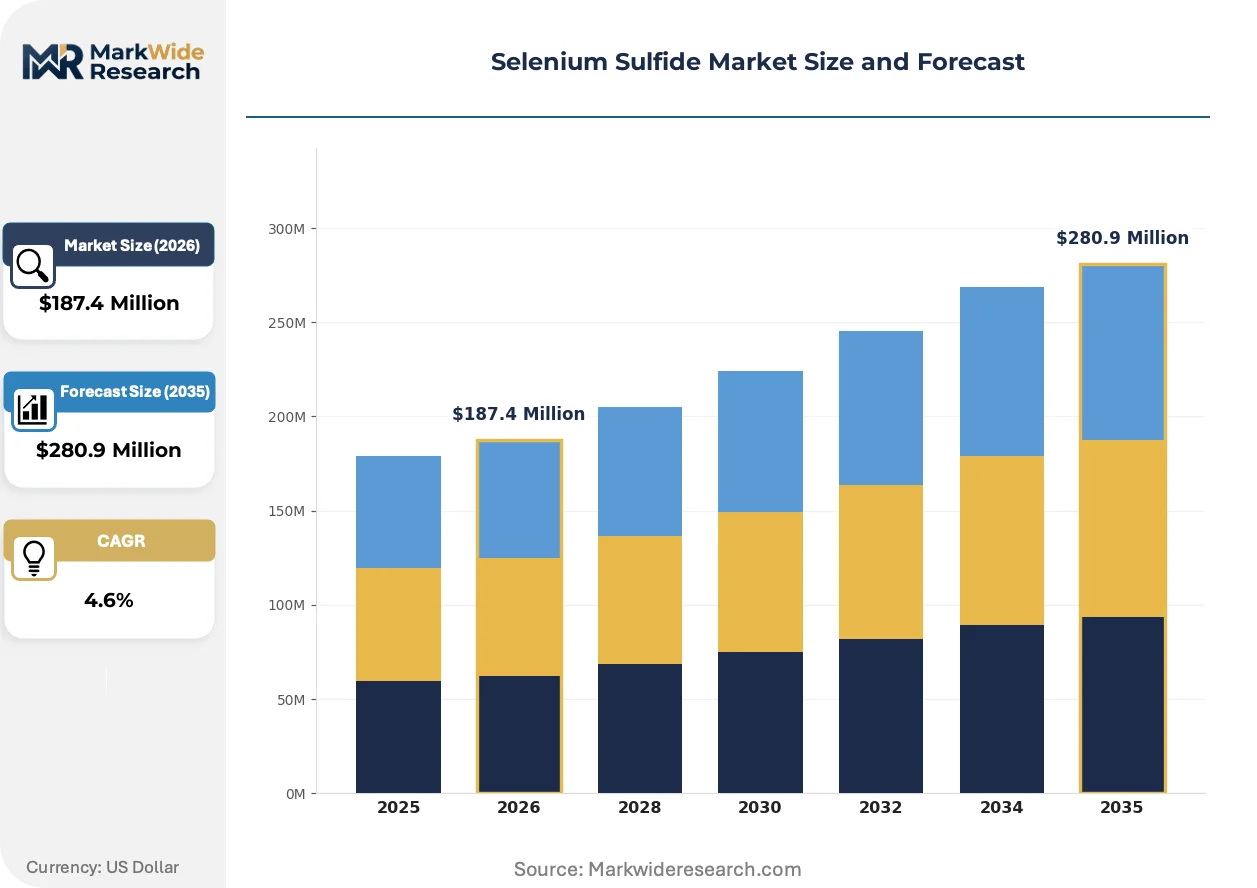
Market Dynamics
REACH registration requirements in Europe are compressing supplier margins while simultaneously filtering out non-compliant producers, concentrating supply among integrated chemical platforms capable of absorbing toxicological dossier costs.
Growth Catalysts
- India CDSCO batch testing mandates:Domestic anti-dandruff shampoo manufacturers must source pharmaceutical-grade selenium sulfide from CDSCO-inspected facilities, creating captive demand for certified suppliers.
- Direct elemental synthesis:Controlled-temperature combination of selenium and sulfur delivers 99.9% purity grades that unlock therapeutic pricing premiums in hospital pharmacy channels.
- China pharmaceutical manufacturing corridors:Concentrated dermatological formulator clusters in Jiangsu and Zhejiang provinces generate predictable offtake volumes for regional producers.
Market Restraints
- Elemental selenium price volatility:Mining supply disruptions and refining capacity constraints in major producing regions transmit directly to selenium sulfide input costs.
- EU CLP reclassification risk:Pending hazard classification debates under Europe's chemical labeling regulation could trigger formulation reformulation costs and export market exclusions.
- Zinc pyrithione substitution:Alternative anti-seborrheic actives with established safety dossiers compete for shelf space in mass-market shampoo formulations.
Strategic Opportunities
- Brazil ANVISA therapeutic registration pathway:Prescription dermatology markets in Latin America's largest economy remain underpenetrated by pharmaceutical-grade selenium sulfide suppliers.
- Online pharmacy channel expansion:Direct-to-patient distribution models bypass traditional wholesale markups for cream and lotion formats in regulated markets.
- Green chemistry process innovation:Solvent-free synthesis methods align with EU Green Deal manufacturing standards and open preferential procurement channels.
Industry Challenges
- API certification timeline compression:FDA active pharmaceutical ingredient facility inspections and drug master file reviews create 18-24 month market entry delays for new suppliers.
- Multi-jurisdiction compliance staffing:Simultaneous navigation of REACH, CDSCO, and FDA requirements demands specialized regulatory affairs capabilities that command premium salaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Selenium Sulfide Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Lotion, Cream, Soap Application: Anti-dandruff, Anti-fungal, Therapeutic, Skin Care End User: Retail, Hospitals, Pharmacies, Online Stores Packaging Type: Tubes, Bottles, Jars, Sachets |
| Companies Covered | BASF SE, Hubei Xinjing New Material Co., Ltd., Omkar Specialty Chemicals Ltd., Alfa Aesar, MilliporeSigma, Wockhardt Ltd., GlaxoSmithKline plc, Vanderbilt Chemicals, Gujarat Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Selenium Sulfide Market Evolving Landscape
Continuous manufacturing methods are displacing batch synthesis in selenium sulfide production, enabling real-time quality monitoring that reduces rework rates and accelerates regulatory filing timelines for pharmaceutical applications.
Continuous flow reactor technology is overtaking traditional batch vessel synthesis in pharmaceutical-grade selenium sulfide manufacturing. Leading dermatological formulators in Germany and Switzerland now specify continuous-process material for new drug submissions. This shift is compressing capital recovery timelines while raising barriers for batch-only producers unable to fund reactor conversion.
EU CLP regulation harmonization efforts are forcing toxicological data sharing across member states. Importers must now submit full substance dossiers to ECHA before market entry, not merely downstream notifications. Pharmaceutical-grade applications face the strictest scrutiny, with some suppliers redirecting commodity-grade volumes to less regulated industrial markets.
Hospital procurement consortia are consolidating active pharmaceutical ingredient purchasing across dermatology portfolios. Large health system networks in the United States now negotiate multi-year selenium sulfide supply agreements with integrated chemical platforms rather than trading through distributors. This concentration is visible most acutely in the Midwest and Southeast regions where hospital merger activity has accelerated.
Selenium Sulfide Market Segmentation
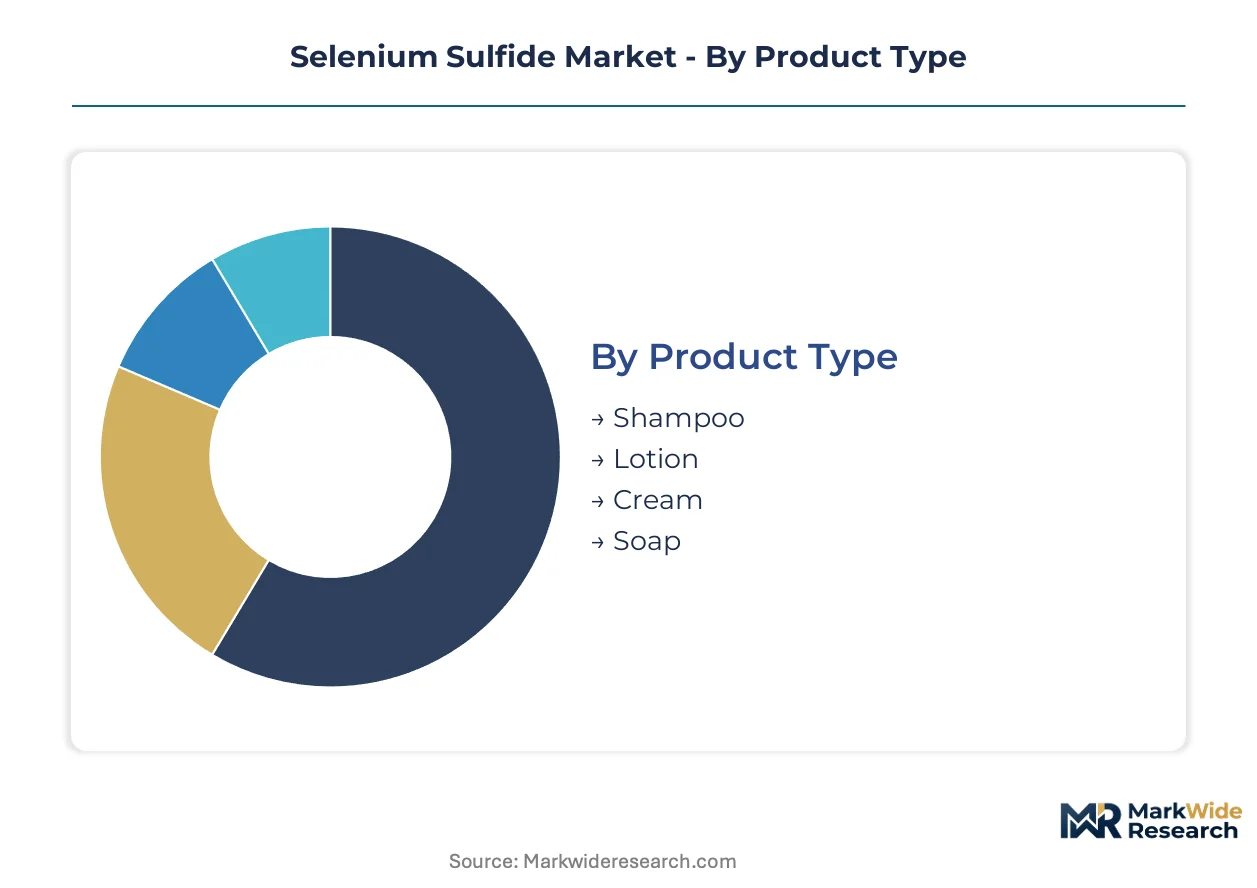
Selenium sulfide formulation formats and distribution channels determine pricing power, regulatory pathway complexity, and customer acquisition costs. Segment boundaries blur where prescription therapeutic applications migrate to over-the-counter retail, forcing manufacturers to maintain dual certification portfolios.
Product Type:
Supply concentration favors high-volume liquid formats where continuous manufacturing investments amortize across larger batch yields.
- Shampoo:Suspension formulations containing 1% selenium sulfide for over-the-counter distribution dominate volume consumption. Mass-market anti-dandruff demand in India and the United States absorbs the majority of commodity-grade supply, though zinc pyrithione substitution pressures shelf space allocation.
- Lotion:Lower viscosity vehicles enable broader body surface coverage for seborrheic dermatitis extending beyond the scalp. Hospital procurement consortia in the American Midwest specify lotion formats for formulary inclusion, creating pricing premiums above retail shampoo equivalents.
- Cream:Occlusive bases enhance epidermal retention for localized fungal infections.
- Soap:Bar formats occupy niche positioning in emerging markets with limited cold-chain distribution infrastructure.
Today's leader: Shampoo. Tomorrow's challenger: Lotion.
Application:
Cost tier stratification separates mass-market cosmetic claims from validated therapeutic indications requiring clinical dossiers.
- Anti-dandruff:Cosmetic-grade formulations with 1% active concentration circulate through retail and online channels without prescription requirements. CDSCO batch testing mandates in India concentrate demand among certified suppliers capable of documentation compliance.
- Therapeutic:Prescription-strength 2.5% preparations for seborrheic dermatitis and tinea versicolor command hospital pharmacy pricing tiers. FDA active pharmaceutical ingredient oversight and REACH toxicological dossier requirements filter supplier participation to integrated chemical platforms.
- Anti-fungal:Dermatophyte-targeting indications compete with azole-class alternatives in clinical settings.
- Skin Care:Adjunctive uses in acne and rosacea protocols remain investigational with limited commercial traction.
Premium pricing accrues to Therapeutic; volume expansion concentrates in Anti-dandruff.
End User:
Customer type determines margin structure, with institutional procurement compressing prices while direct-to-patient channels preserve markup.
- Retail:Supermarket and pharmacy shelf placement generates predictable offtake for shampoo formats. Brand marketing expenditure requirements erode manufacturer margins despite high unit volumes.
- Hospitals:Integrated delivery network purchasing consolidation in the American Southeast and Midwest regions shifts negotiation leverage toward buyers. Multi-year supply agreements with BASF SE and comparable platforms displace distributor intermediaries.
- Pharmacies:Independent and chain dispensaries bridge prescription and over-the-counter categories.
- Online Stores:Direct-to-consumer platforms bypass wholesale markups for cream and lotion formats.
Institutional concentration favors Hospitals; margin preservation favors Online Stores.
Packaging Type:
Volume throughput and patient compliance considerations shape format selection across regulated markets.
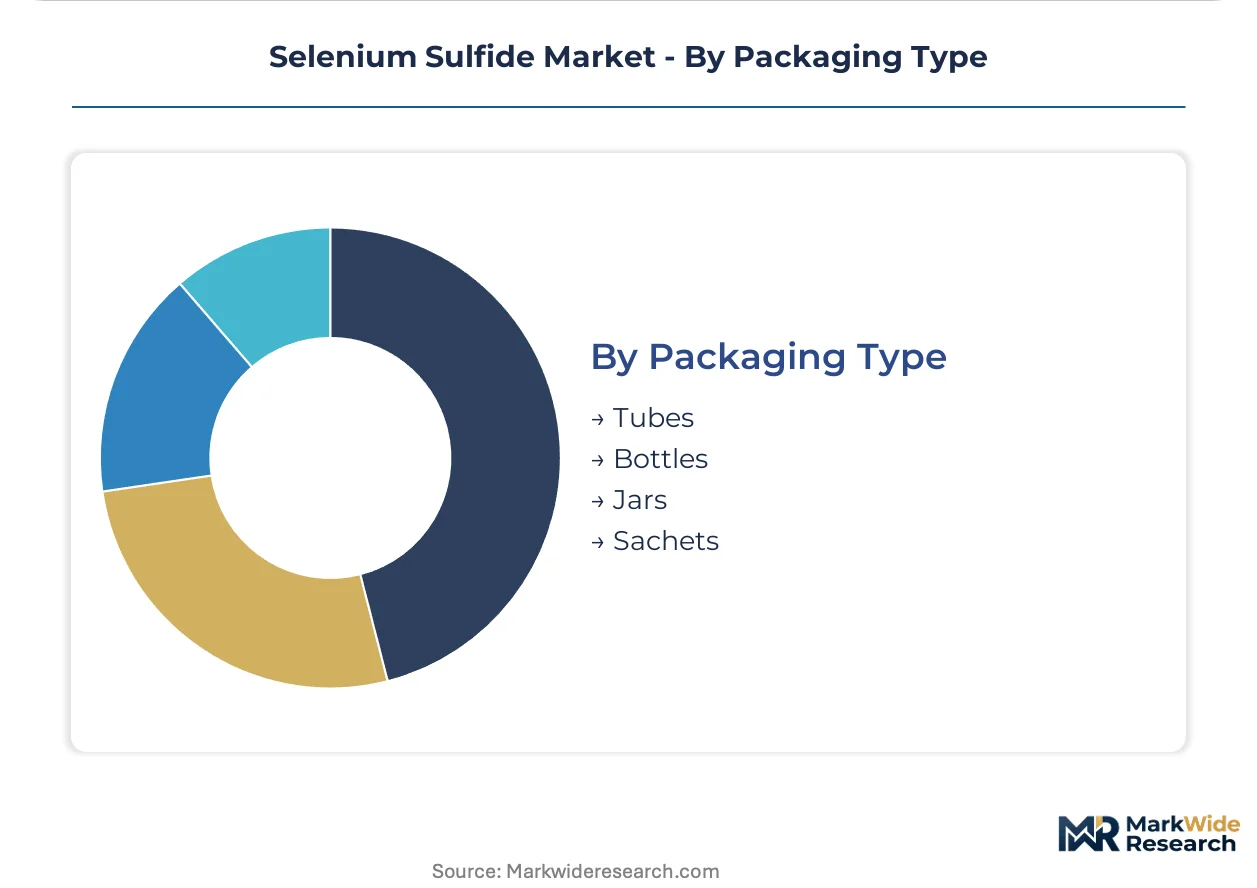
- Tubes:Collapsible aluminum and laminated plastic containers dominate prescription cream and lotion dispensing. German dermatological formulators specify tube formats for hospital pharmacy distribution to minimize contamination risk.
- Bottles:Pump and flip-cap dispensers accommodate shampoo and lotion viscosity ranges. Chinese manufacturing corridors in Jiangsu province produce bottles at scale for regional formulator clusters.
- Jars:Wide-mouth containers facilitate cream extraction but introduce preservation challenges.
- Sachets:Single-use foil pouches address price-sensitive segments and travel-size requirements.
Tubes capture therapeutic premium; Bottles absorb mass-market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemists and process engineers cluster in Germany's Rhine-Ruhr corridor and China's Jiangsu province, anchoring the technical workforce for pharmaceutical-grade synthesis. Regulatory divergence between FDA, EMA, and CDSCO standards fragments certification requirements across export markets.
United States
Hospital procurement consortia in the Midwest and Southeast negotiate multi-year supply agreements for therapeutic-grade material. FDA active pharmaceutical ingredient facility inspections create 18-24 month entry barriers for new suppliers. Indianapolis and Raleigh-Durham host dermatological formulation clusters serving institutional pharmacy channels.
Germany
Continuous flow reactor specifications from German and Swiss formulators now dominate new drug submission requirements. REACH toxicological dossier obligations filter supplier participation to integrated chemical platforms. Ludwigshafen and Leverkusen concentrate production capacity for regulated European markets.
China
Jiangsu and Zhejiang provinces generate predictable offtake volumes through concentrated dermatological formulator clusters. NMPA alignment with ICH Q7 guidelines tightens manufacturing facility standards for export-oriented producers. Shanghai and Nanjing anchor the pharmaceutical manufacturing corridor for regional supply.
India
CDSCO batch testing mandates concentrate demand among certified suppliers for domestic anti-dandruff shampoo manufacturers. Mumbai and Ahmedabad host formulation facilities subject to manufacturing facility inspections. The country's national pharmaceutical regulator tightens documentation compliance for therapeutic-grade imports.
Brazil
Prescription dermatology markets remain underpenetrated by pharmaceutical-grade suppliers despite ANVISA therapeutic registration pathways. São Paulo and Rio de Janeiro clusters absorb commodity-grade volumes for cosmetic applications. The national health surveillance agency's approval timelines deter entry by specialized producers.
Selenium Sulfide Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct value chain positions. The supplier base concentrates among integrated chemical platforms capable of absorbing toxicological dossier costs and specialized fine-chemical producers serving therapeutic niches. Three archetypes dominate: multinational integrated platforms, regional API specialists, and commodity chemical traders. Competitive moves center on continuous manufacturing conversion and backward integration into elemental selenium sourcing.
Within the integrated platform tier, BASF SE exemplifies the capital-intensive archetype with Rhine-Ruhr corridor presence. Among Asia-Pacific specialists, Hubei Xinjing New Material Co., Ltd. occupies a position reflecting Chinese production scale, while Omkar Specialty Chemicals Ltd. represents the India-based fine-chemical model serving CDSCO-regulated demand. These three anchors illustrate the geographic and capability stratification shaping procurement decisions.
| Leading Market Players |
|---|
| BASF SE |
| Hubei Xinjing New Material Co., Ltd. |
| Omkar Specialty Chemicals Ltd. |
| Alfa Aesar |
| MilliporeSigma |
| Wockhardt Ltd. |
| GlaxoSmithKline plc |
| Vanderbilt Chemicals |
| Gujarat Organics |
| Others |
Value Network & Pricing Analysis
Backward integration into elemental selenium sourcing anchors both supply security and pricing power for pharmaceutical-grade producers navigating CDSCO, FDA, and REACH compliance costs simultaneously. BASF SE's Rhine-Ruhr corridor operations demonstrate how captive refining capacity insulates margin structures against mining supply disruptions while enabling premium positioning in hospital pharmacy channels.
Pricing Analysis
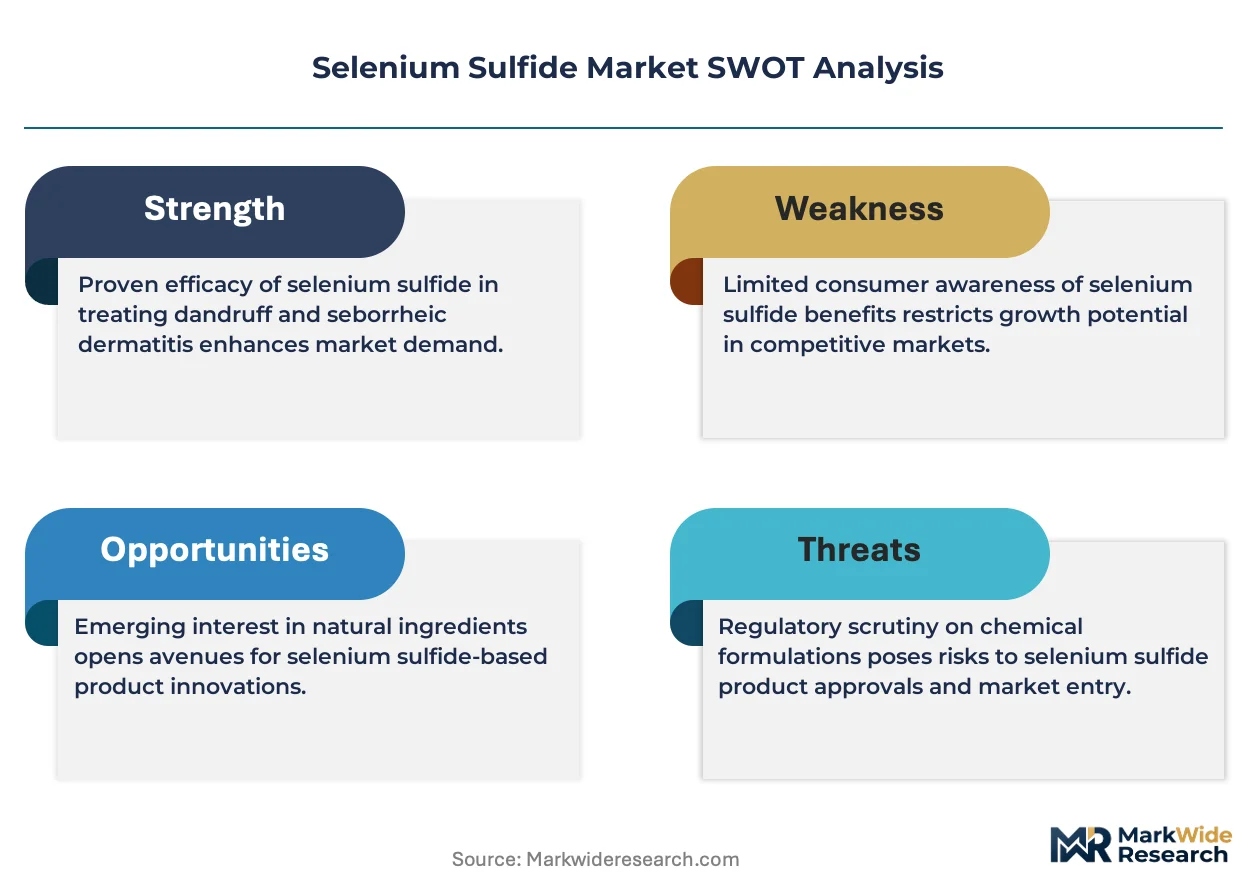
Unbundled regulatory certification services from base material supply create a two-tier pricing architecture in this market. Pharmaceutical-grade selenium sulfide draws from 99.9% purity thresholds and CDSCO-inspected facility status to command hospital pharmacy premiums, while commodity-grade volumes face price erosion from zinc pyrithione substitution in mass-market shampoo formulations. Brand-sensitive retail buyers in India and the United States exhibit highest price sensitivity, whereas integrated delivery network procurement consortia in the American Midwest accept premium positioning for therapeutic-grade material with validated clinical dossiers.
Supply Chain Analysis
Certification gating through REACH toxicological dossiers and FDA active pharmaceutical ingredient facility inspections concentrates supply among integrated chemical platforms in Germany, China, and India. Elemental selenium feedstock draws from mining operations in major producing regions, while sulfur inputs rest on petrochemical and natural gas processing byproduct streams. Single-source vulnerability in selenium mining transmits directly to input cost volatility. Distribution runs through direct manufacturer-to-formulator relationships for pharmaceutical applications, with distributor intermediaries persisting in commodity-grade shampoo supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO batch testing mandates in India create captive demand premiums unavailable in REACH-saturated European markets with compressed supplier margins.
For Market Incumbents: Acquire continuous flow reactor assets to displace batch-only competitors unable to fund capital conversion. BASF SE's integrated platform model demonstrates how backward integration into elemental selenium sourcing defends margin structures against mining supply disruptions. Capacity expansion in Jiangsu province captures Chinese dermatological formulator cluster demand while zinc pyrithione substitution pressures mass-market shampoo positioning. For New Entrants and Emerging Players: Solvent-free synthesis technology offers a technology-first wedge into EU Green Deal preferential procurement channels unavailable to legacy batch producers. Brazil's ANVISA therapeutic registration pathway presents the most penetrable geography for pharmaceutical-grade suppliers, with São Paulo prescription dermatology markets absorbing initial volumes through hospital pharmacy distribution partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction compliance staffing costs exceed $200,000 annually per specialized regulatory affairs hire. Fine-chemical specialists with CDSCO-inspected facilities and existing drug master file submissions represent priority acquisition targets. Watch for EU CLP reclassification debates as the inflection signal that would trigger formulation reformulation costs and redirect commodity-grade volumes to industrial markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elemental Selenium | Captive refining capacity insulates BASF SE against mining supply disruptions in major producing regions. |
| Continuous Manufacturing Conversion | Flow reactor technology meets German and Swiss formulator specifications for new drug submissions. |
| CDSCO Certification Investment | Batch testing compliance unlocks captive demand from domestic Indian anti-dandruff shampoo manufacturers. |
| Green Chemistry Process Development | Solvent-free synthesis aligns with EU Green Deal standards and preferential procurement channels. |
| Brazil ANVISA Registration Pathway | Therapeutic-grade positioning captures underpenetrated prescription dermatology demand in São Paulo clusters. |
Research Methodology
Direct dialogue with plant managers at selenium sulfide production facilities, procurement leads at dermatological formulators, CDSCO regulatory affairs officers, and hospital pharmacy directors grounded the qualitative foundation. Secondary validation drew from FDA drug master file databases, ECHA REACH registration dossiers, CDSCO manufacturing facility inspection records, and customs trade data for elemental selenium and sulfur derivatives. Bottom-up capacity estimates from identified producers triangulated against top-down demand calculations from shampoo, lotion, and cream formulation volumes.
Bottom-up modeling of production capacity by facility and grade tier converged with top-down consumption estimates from end-use segment analysis across the projection horizon. Segmentation dimensions included formulation format, application category, end-user channel, and regional regulatory cluster. CAGRs derived from slope analysis of normalized growth trajectories against historical capacity utilization and pricing trend data. Forecast inputs incorporated REACH compliance cost absorption rates and CDSCO inspection timeline compression effects.
The model holds under stable regulatory classification and continuous manufacturing adoption curves; deviation in EU CLP reclassification outcomes or elemental selenium supply disruptions would shift volume and value trajectories. A model refresh is warranted upon material change in REACH toxicological dossier requirements or CDSCO batch testing mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
Hydroxyzine Imine Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Amine Oxide Market
Chemicals
Fluorene Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Photographic Chemicals Market
Chemicals
Diphenylamine (DPA) Market
Chemicals
Pinoxaden Market
Chemicals
Allyl Chloride Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Copper Oxychloride Market
Chemicals
Triethylenediamine Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Fatty Alcohol Ethoxylates Market