
 Fluorene Market | 2026-2036
Fluorene Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorene Market Intelligence
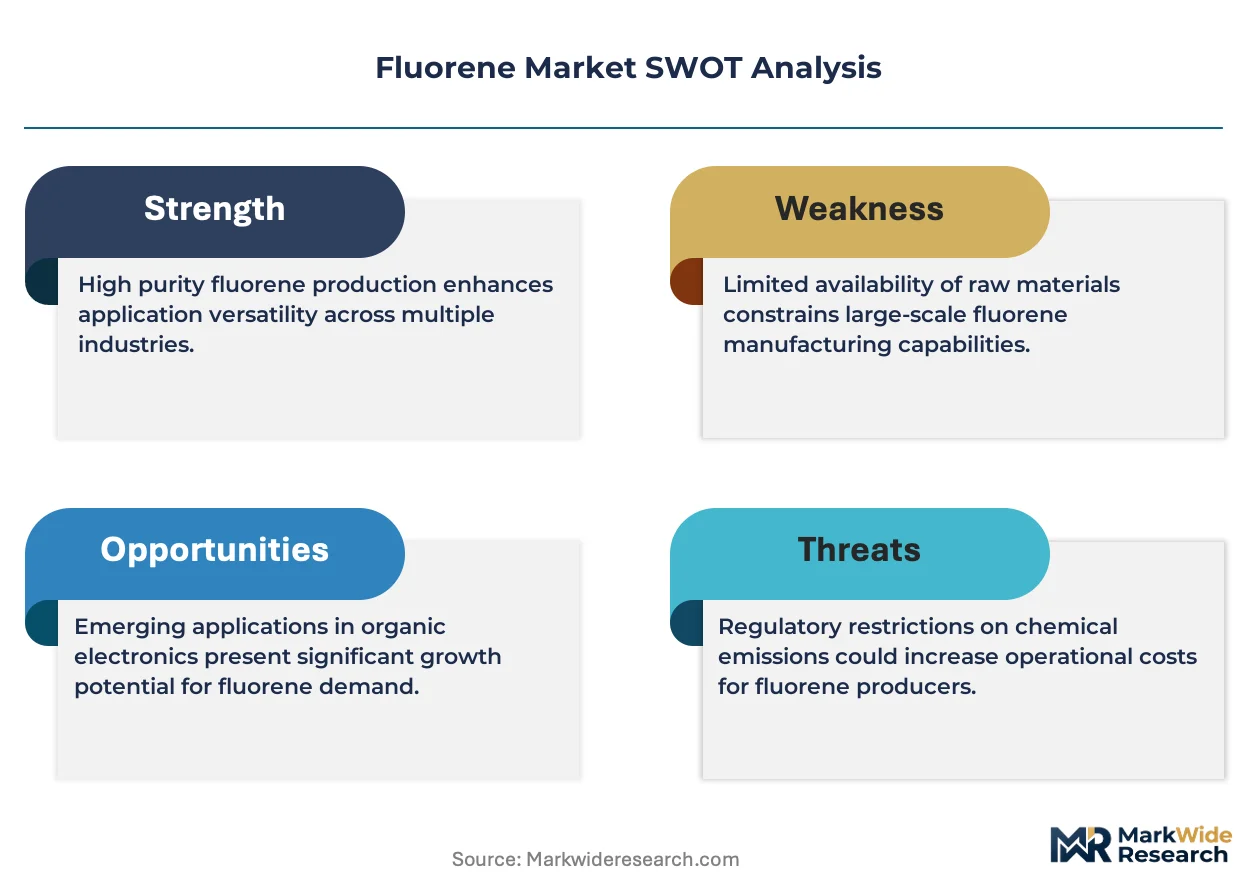
High-performance fluorene-based polymers for organic light-emitting diodes (OLEDs) is pivoting the market away from traditional display materials. This shift creates opportunities for chemical specialists like Solvay, which leverages its expertise in advanced polymer formulations. Meanwhile, DIC Corporation specializes in fine chemicals for electronics applications, and Arkema Group competes on the basis of its broad portfolio of specialty materials.
Fluorene is a polycyclic aromatic hydrocarbon (PAH) derived from coal tar, characterized by its white crystalline structure and fluorescent properties under UV light. It primarily functions as a chemical intermediate for synthesizing more complex molecules. Within applications, polymer production for organic electronics commands significant attention due to its high growth potential. Demand for 9-Fluorenone and other fluorene derivatives is expanding for use in dye manufacturing and pharmaceutical synthesis.
The handling and use of fluorene are governed by chemical safety regulations, including Europe's REACH framework and the US EPA's Toxic Substances Control Act (TSCA). These regulations mandate rigorous testing and registration, influencing production costs and market access. Consequently, navigating the evolving chemical safety and environmental compliance landscape is a critical success factor for all market participants.
Market Dynamics
The transition of fluorene from a bulk chemical intermediate into a high-value precursor for advanced polymers is the central force shaping the market. This pivot is driven by the exacting material science requirements of the organic electronics industry, particularly for OLED applications.
Growth Catalysts
- OLED Technology Expansion:The adoption of organic light-emitting diodes in premium smartphones, televisions, and automotive lighting systems creates direct demand for high-purity fluorene derivatives used as blue-light emitters and host materials.
- Energy Efficiency Mandates:Regulations like the EU's Ecodesign Directive, which phase out less efficient lighting technologies, indirectly support the market by encouraging the use of energy-efficient OLEDs, thereby stimulating demand for their constituent materials.
- Pharmaceutical Synthesis:Demand for specialized fluorene derivatives is expanding in the pharmaceutical industry for the synthesis of new drug candidates, including anti-inflammatory and anti-cancer agents, particularly in research-intensive regions.
Market Restraints
- Feedstock Volatility:The market's primary reliance on coal tar, a byproduct of metallurgical coke production, links fluorene supply and cost directly to the cyclical steel industry, creating significant price and availability instability for producers.
- Regulatory Scrutiny:As a polycyclic aromatic hydrocarbon (PAH), fluorene is subject to stringent environmental and health regulations, including Europe's REACH and the US EPA's TSCA, which impose costly testing and registration burdens.
- Material Substitution:The intense R&D focus on OLED emitters presents a constant threat of substitution from alternative, non-fluorene-based material families like thermally activated delayed fluorescence (TADF) compounds that may offer superior performance.
Strategic Opportunities
- Organic Photovoltaics:The development of fluorene-based polymers for use in organic solar cells (OPVs) represents a significant opportunity, leveraging their electronic properties to create flexible, lightweight, and transparent energy-harvesting devices.
- Regional Production Hubs:Establishing high-purity fluorene synthesis and purification facilities within electronics manufacturing clusters in Southeast Asia could capture value by serving local OLED panel makers directly and reducing supply chain lead times.
- Functional Copolymers:There is an opportunity to design and synthesize novel copolymers that integrate fluorene units with other monomers to create materials with tailored properties for emerging applications like flexible sensors and wearable electronics.
Industry Challenges
- Cross-Jurisdictional Compliance:Navigating the complex and divergent requirements of chemical control laws, such as the registration dossiers needed for ECHA in Europe versus the risk evaluations under the US EPA, presents a major operational hurdle.
- Purification Capital Expense:Achieving the ultra-high purity (99.99%+) demanded by the electronics industry requires multi-stage, capital-intensive purification processes like sublimation and chromatography, which act as a barrier to entry.
- Intellectual Property Density:The landscape for high-performance OLED materials is crowded with patents, making it challenging for new and existing players to innovate without infringing on existing intellectual property held by established chemical specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorene Market |
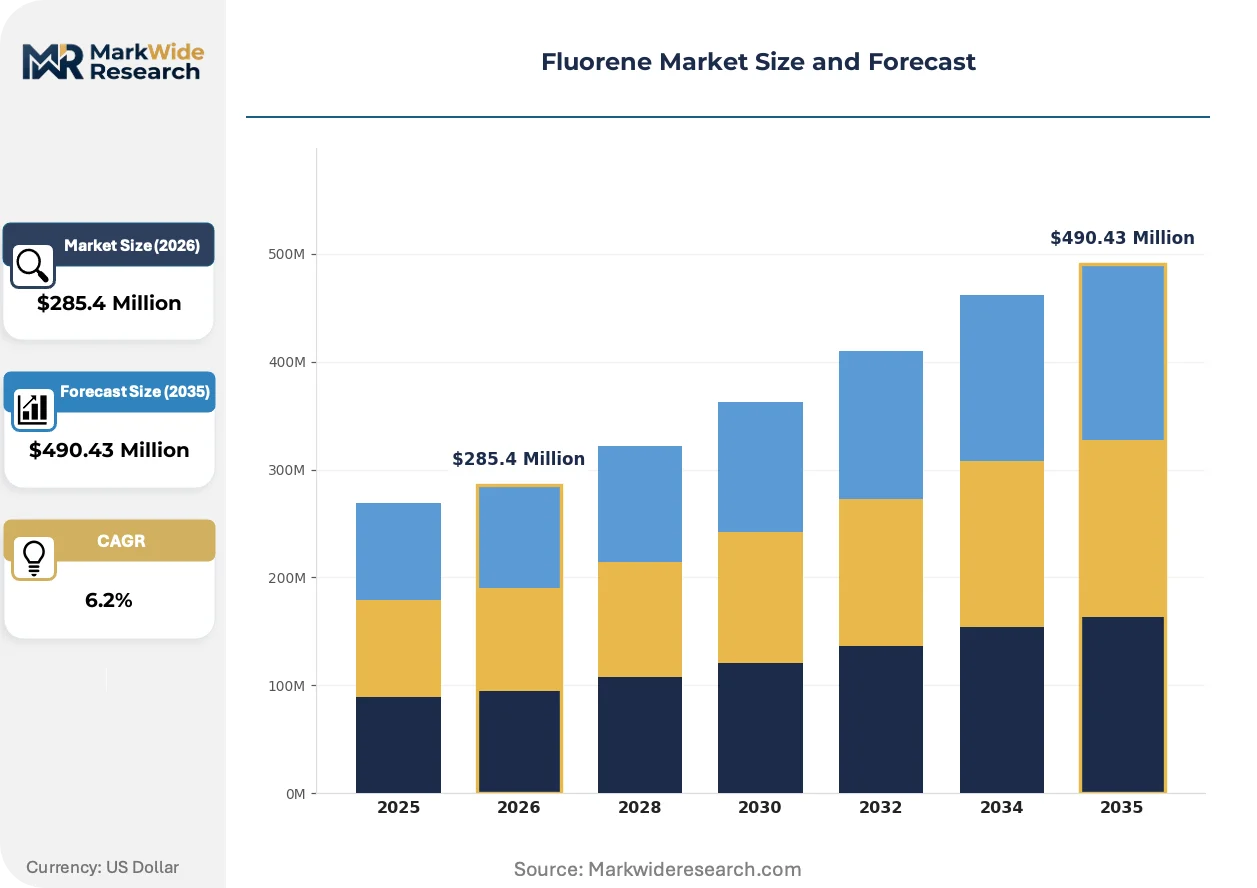
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
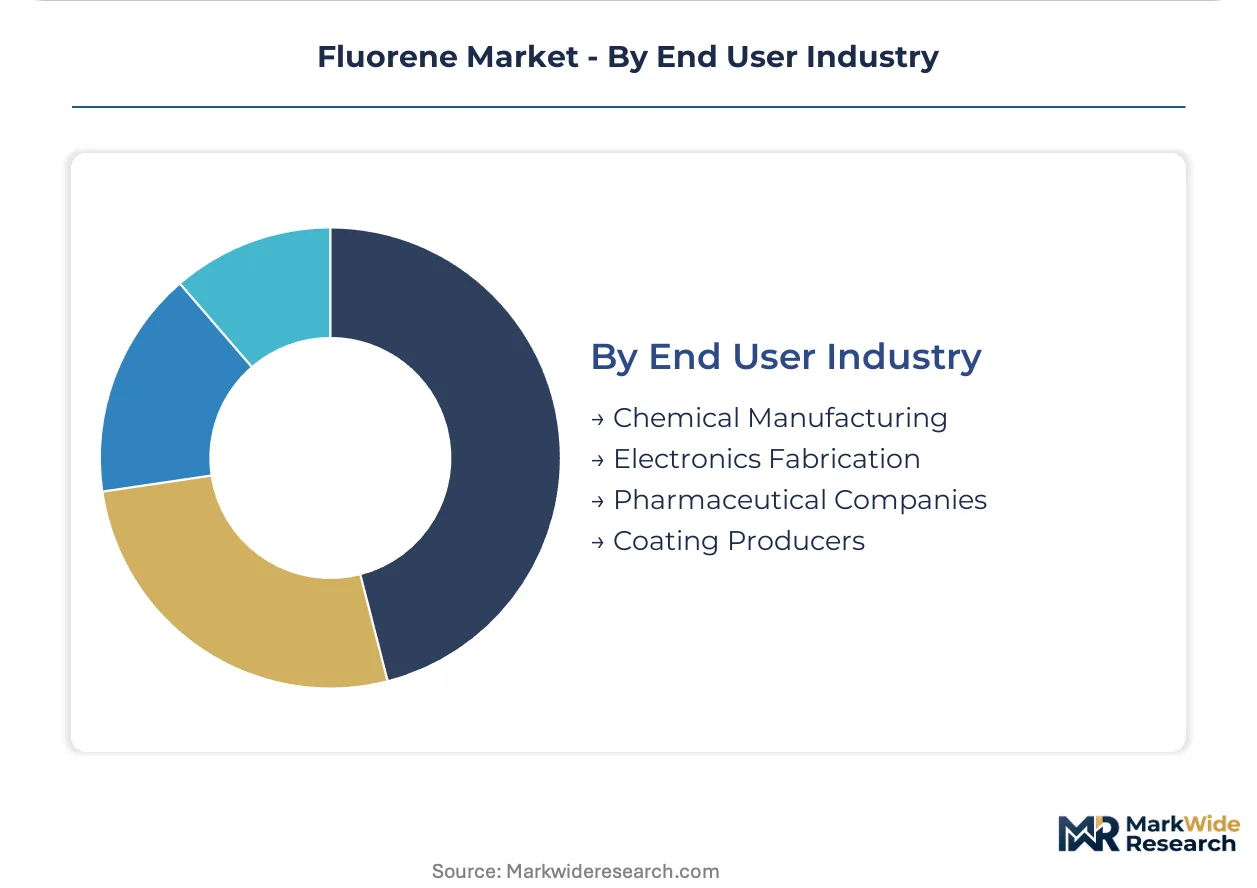
| Segmentation | Product Type: Fluorene Monomer, 9-Fluorenone, 9-Fluorenylmethanol, Fluorene Derivatives Application: Polymer Production, Organic Electronics, Dye Manufacturing, Pharmaceutical Synthesis, Specialty Chemicals Technology: Electrochemical Synthesis, Catalytic Hydrogenation, Photochemical Reaction, Thermal Cracking End User Industry: Chemical Manufacturing, Electronics Fabrication, Pharmaceutical Companies, Coating Producers |
| Companies Covered | Daikin Industries, Ltd., 3M Company, Navin Fluorine International Ltd, DIC Corporation, Gujarat Fluorochemicals Limited, Solvay, The Chemours Company, Kanto Denka Kogyo Co., Ltd, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorene Market Strategic Shifts & Innovations
Material science innovation is pushing the fluorene market toward application-specific formulations with precisely engineered electronic and optical properties. This shift prioritizes performance and purity over volume, favoring suppliers capable of advanced synthesis and collaborative development with end-users in high-tech sectors.
Fluorene-based copolymers are advanced polymers engineered to enhance charge transport efficiency and color purity in organic electronic devices. OLED panel manufacturers in South Korea and Taiwan are integrating these next-generation materials to improve the lifespan and power consumption of their displays. The development of these tailored copolymers is rewriting the performance benchmarks for stable and efficient blue-light emitters, a persistent challenge in OLED technology.
Europe's REACH framework mandates extensive data collection on the properties and risks of chemical substances like fluorene before they can be sold. This regulation increases R&D and compliance costs, compelling producers to conduct thorough toxicological and environmental impact assessments. Specialty chemical manufacturers targeting the European Union are most affected, often rationalizing their product portfolios to focus on high-margin derivatives that can justify the high cost of regulatory compliance.
Electronics manufacturers are increasingly engaging in co-development partnerships with material suppliers to create custom fluorene-based polymers for specific device requirements. This collaborative model is disrupting the traditional, transactional procurement of standardized chemicals, replacing it with integrated R&D efforts. The trend is most visible within the premium display sector, where device differentiation for firms in Japan and South Korea often hinges on unique material properties achieved through these partnerships.
Fluorene Market Segmentation
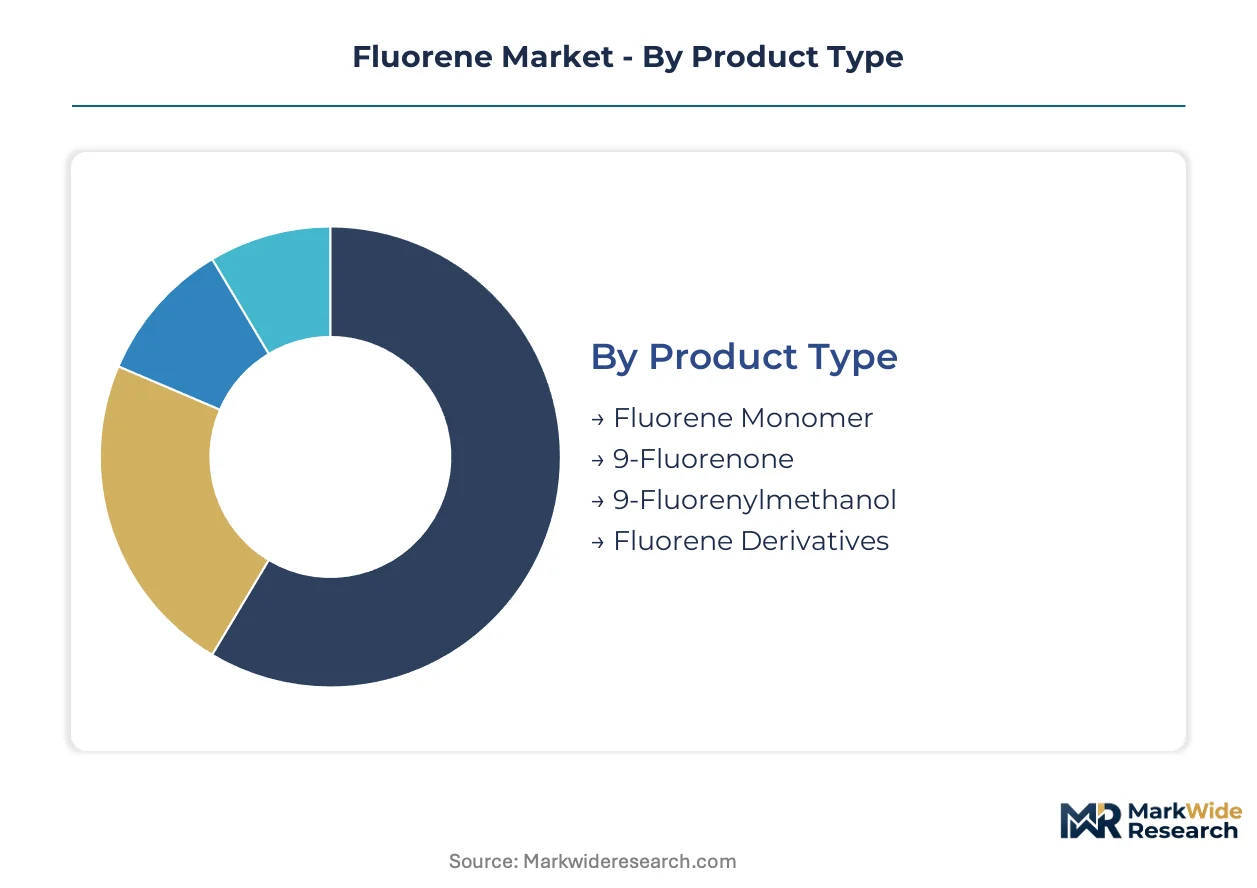
The fluorene market's intricate structure reflects diverse material requirements across high-tech industries. Understanding segmentation provides clarity on where specific product forms and applications drive value creation. This granular analysis helps stakeholders identify precise growth vectors and optimize their strategic investments.
Product Type:
Product specifications critically influence purchasing decisions for fluorene derivatives, dictating performance in advanced applications.
- Fluorene Monomer:This foundational polycyclic aromatic hydrocarbon serves as the primary building block for synthesizing complex fluorene compounds. Its high purity is essential for downstream polymer production, particularly for organic electronics manufacturers in South Korea.
- 9-Fluorenone:A versatile derivative, 9-Fluorenone features a carbonyl group, making it a key intermediate in dye manufacturing and pharmaceutical synthesis. Demand for this compound is expanding in research-intensive regions for new drug candidates.
- 9-Fluorenylmethanol:This alcohol derivative is important for protecting group chemistry in peptide synthesis and as an intermediate for certain specialty polymers.
- Fluorene Derivatives:This broad category encompasses a range of modified fluorene structures tailored for specific electronic, optical, or biological properties.
Volume sits with Fluorene Monomer; growth tilts toward Fluorene Derivatives.
Application:
The specific end-use application determines the required purity and functional properties of fluorene compounds, influencing procurement strategies.
- Polymer Production:Fluorene units are integrated into advanced polymers to enhance their electronic and optical characteristics for high-performance materials. This segment is central to the development of organic electronics, particularly in OLED display manufacturing.
- Organic Electronics:Fluorene derivatives serve as crucial components in organic light-emitting diodes (OLEDs) for blue-light emitters and host materials, improving device efficiency and lifespan. Demand is concentrating in electronics manufacturing hubs like Taiwan and Japan.
- Dye Manufacturing:Fluorene derivatives contribute to the synthesis of various dyes, offering specific color properties and stability for industrial and textile applications.
- Pharmaceutical Synthesis:Specialized fluorene derivatives are essential intermediates in the creation of new drug candidates, including anti-inflammatory and anti-cancer agents.
- Specialty Chemicals:This category includes diverse niche uses where fluorene's unique chemical structure provides specific functional benefits for advanced materials.
Polymer Production commands significant volume; Organic Electronics exhibits the steepest expansion trajectory.
Technology:
The choice of synthesis technology impacts the purity, yield, and cost structure of fluorene production, influencing supply chain dynamics.
- Electrochemical Synthesis:This method utilizes electric current to drive chemical reactions, offering precise control over reaction conditions and potentially higher purity products. Its adoption is gaining traction for specialized fluorene derivatives in research settings.
- Catalytic Hydrogenation:Catalytic hydrogenation involves the addition of hydrogen across double bonds using a catalyst, a common industrial process for modifying fluorene structures. This technology is widely used for producing specific fluorene derivatives with enhanced stability.
- Photochemical Reaction:These reactions use light energy to initiate chemical transformations, enabling the synthesis of complex fluorene compounds under mild conditions.
- Thermal Cracking:Thermal cracking processes break down larger molecules into smaller ones using high temperatures, often employed in the initial extraction of fluorene from coal tar.
Catalytic Hydrogenation represents a mature production method; Electrochemical Synthesis is gaining share fastest for high-value variants.
End User Industry:
Customer industry requirements for fluorene vary significantly in terms of volume, purity, and regulatory compliance, defining distinct market segments.
- Chemical Manufacturing:This segment represents the largest consumer of fluorene as a raw material for synthesizing a wide array of intermediate and specialty chemicals. Manufacturers require consistent supply and competitive pricing for bulk production.
- Electronics Fabrication:Electronics companies utilize high-purity fluorene derivatives for advanced display technologies, especially OLEDs, where material performance directly impacts device lifespan and efficiency. This sector demands stringent quality control.
- Pharmaceutical Companies:These firms employ fluorene derivatives for active pharmaceutical ingredients and research compounds, necessitating strict adherence to regulatory standards like those from the US EPA or Europe's ECHA.
- Coating Producers:Fluorene compounds are incorporated into specialized coatings to impart properties such as UV resistance, enhanced durability, or specific optical characteristics.
Chemical Manufacturing accounts for the largest volume; Electronics Fabrication is driving premium demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fluorene compounds is concentrating in key electronics manufacturing centers, particularly in Asia, where advanced display technologies drive material science requirements. These regions also support significant pharmaceutical research and chemical production. Regulatory frameworks across major economies influence market access and production costs for high-purity fluorene.
South Korea
South Korea's robust OLED industry fuels significant demand for fluorene derivatives as blue-light emitters and host materials. The country's MFDS oversees pharmaceutical synthesis, influencing demand for specialized fluorene intermediates. Electronics fabrication in the Seoul Capital Area drives innovation in display materials.
Taiwan
Taiwan's strong position in OLED display manufacturing creates substantial demand for high-purity fluorene monomers and derivatives. The country's EPA regulations influence the handling and use of PAHs like fluorene. Hsinchu Science Park acts as a hub for advanced electronics research and material integration.
Japan
Japan's premium display sector and pharmaceutical synthesis capabilities generate consistent demand for fluorene-based polymers and derivatives. METI industrial policies encourage high-value chemical production and advanced material development. The Kansai region supports a strong chemical and pharmaceutical manufacturing base.
Germany
Germany's advanced polymer production and chemical manufacturing sectors drive demand for fluorene as a versatile intermediate. Europe's REACH framework imposes stringent requirements on fluorene production and use within the country. The Rhine-Main region hosts major chemical companies and pharmaceutical research facilities.
United States
The United States exhibits strong demand for fluorene derivatives in pharmaceutical synthesis and specialty chemical applications. The US EPA's TSCA mandates rigorous testing and registration for chemicals like fluorene. Research-intensive regions like California and the Northeast drive organic electronics material development.
Fluorene Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments in the fluorene market, reflecting varying purity and volume requirements. The competitive structure features a mix of large diversified chemical conglomerates and niche high-purity material suppliers. Strategic archetypes include integrated producers focused on feedstock control and innovation-driven firms developing application-specific derivatives for organic electronics. Companies frequently pursue portfolio diversification and strategic partnerships to enhance market reach and reduce supply chain risks.
Specialists in advanced polymer formulations and fine chemicals actively shape the market's innovation trajectory. Solvay, a European chemical company, exemplifies a player leveraging expertise in advanced polymer formulations for high-performance materials. DIC Corporation, a Japan-based chemical company, occupies a position focused on fine chemicals for electronics applications. Arkema Group, another European chemical major, anchors its presence through a broad portfolio of specialty materials, contributing to diverse fluorene derivative applications.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| 3M Company |
| Navin Fluorine International Ltd |
| DIC Corporation |
| Gujarat Fluorochemicals Limited |
| Solvay |
| The Chemours Company |
| Kanto Denka Kogyo Co., Ltd |
| Arkema Group |
| Others |
Cost & Logistics Intelligence
Electronics manufacturers in South Korea and Taiwan, requiring ultra-high purity fluorene, drive contract-based long-term offtake pricing. This model prioritizes supply stability and stringent quality specifications over spot market fluctuations.
Pricing Analysis
Volume sales of fluorene monomer operate on contract-based long-term offtake, while high-purity derivatives command value-based pricing. Ultra-high purity (99.99%+) and application-specific customization for OLEDs drive significant price differentiation. Pricing softness affects bulk fluorene due to coal tar feedstock volatility, but premium values hold for specialized derivatives. Pharmaceutical companies and electronics fabricators exhibit lower price sensitivity for critical materials, unlike commodity chemical manufacturers.
Supply Chain Analysis
Skilled workforce availability in advanced chemical manufacturing centers like Germany and South Korea underpins specialized fluorene production. China concentrates the primary feedstock supply for fluorene, deriving from coal tar. Reliance on coal tar, a byproduct of the cyclical steel industry, creates significant feedstock volatility. Distribution runs through direct sales channels for major electronics and pharmaceutical clients, complemented by specialty chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorene market dynamics are heavily shaped by the cost of regulatory compliance. Europe's REACH framework creates a significant barrier to entry, favoring established players capable of rigorous testing and registration.
For Market Incumbents: Extend high-purity fluorene synthesis and purification capabilities within electronics manufacturing hubs in Asia. Invest in R&D for next-generation fluorene-based copolymers to counter substitution threats from TADF compounds. Secure long-term feedstock agreements to mitigate coal tar price volatility. Maintain a strong patent portfolio around specialized derivatives to defend market share.
For New Entrants and Emerging Players: Enter via specialized fluorene derivatives for emerging applications like organic photovoltaics (OPVs) and flexible sensors. Target research-intensive pharmaceutical synthesis markets requiring smaller volumes of highly customized intermediates. Focus on co-development partnerships with innovative electronics firms to tailor material properties. Leverage electrochemical synthesis for high-value, ultra-pure variants that justify capital expenditure.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers targeting niche specialists in high-purity fluorene derivatives. Long-term viability is strong for companies with proprietary synthesis and purification technologies in organic electronics. Seek targets with robust intellectual property portfolios in fluorene-based copolymers for OLEDs. Increased M&A activity within the advanced display materials supply chain signals market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures supply for growing OLED demand in South Korea and Taiwan. |
| Backward Integration | Reduces reliance on volatile coal tar feedstock for fluorene monomer. |
| Green Manufacturing Transition | Aligns with EU Ecodesign Directive and enhances market access in Europe. |
| Long-term Supply Agreement | Stabilizes pricing and ensures material availability for electronics fabricators. |
| Joint Venture | Accelerates development of novel fluorene-based copolymers for blue-light emitters. |
Research Approach
Multi-period observation of fluorene production volumes, OLED display adoption rates, and patent filings anchored the trend analysis, supplemented by interviews. Primary research engaged chemical R&D directors, electronics procurement leads, pharmaceutical synthesis managers, and regulatory compliance officers. Secondary validation drew from customs/trade data, SEC 10-K filings, ECHA REACH dossiers, and academic research papers. This approach ensured robust bottom-up and top-down triangulation.
Segment-weighting across product type, application, technology, and end-user industry informed the quantitative analysis. The analytical framework projected demand across the modeling period, with CAGRs derived from historical growth patterns and projected technological advancements. Key forecast inputs included OLED panel manufacturing capacity expansions in Asia and pharmaceutical R&D spending.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant feedstock price volatility or new PAH regulatory restrictions. Projections reflect current assumptions about technological development and market adoption. Material deviation in disruptive non-fluorene OLED materials warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Fluorochemicals Market
Chemicals
Quaternium-15 Market
Chemicals
Cumene Market
Chemicals
Iscotrizinol Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Guaiazulene Market
Chemicals
Phenylethyl Market
Chemicals
Benzalkonium Bromide Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Allyl Alcohol Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Flooring Chemicals Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Household Insecticides Market
Chemicals
Potassium Iodide Market