
 Sucroglycerides Market | 2026-2036
Sucroglycerides Market Size, Share, and Industry Trends Forecast 2026-2036
Sucroglycerides Market Analytics
Food-grade specification upgrades is reorganizing competitive dynamics across the sucroglycerides landscape. Cargill Incorporated leverages its integrated oilseed processing infrastructure to secure consistent feedstock supply for high-purity sucroglyceride output. BASF SE anchors its position through advanced esterification technology leadership in European surfactant chemistry. Stepan Company competes by specializing in tailored emulsifier blends for North American bakery and dairy processors.
Sucroglycerides are non-ionic surfactants synthesized through glycerolysis of sucrose with edible fats or oils, yielding products with hydrophilic-lipophilic balance values typically ranging from 5 to 13 depending on fatty acid chain length and degree of esterification; they function primarily as emulsifiers, stabilizers, and texturizing agents in food systems where water-oil interface control determines shelf stability and mouthfeel. Liquid sucroglycerides dominate volume consumption in industrial food manufacturing due to ease of dosing and blending, while powder formats command margin premiums in pharmaceutical and cosmetic applications where moisture sensitivity and precise unit dosing matter. The food industry application segment retains the largest revenue pool, though pharmaceutical-grade specifications are attracting R&D investment as regulatory pathways for excipient-grade sucroglycerides mature.
FDA food additive regulations and EPA chemical substance reporting requirements shape product purity thresholds and documentation burdens for suppliers targeting United States market access, while REACH registration and EFSA food contact material evaluations govern European commercialization pathways. The EU Green Deal chemical sustainability framework is pushing manufacturers toward bio-based feedstock sourcing and reduced solvent intensity in esterification processes. Stakeholders must monitor evolving excipient monograph standards from USP and Ph.Eur as pharmaceutical applications expand, since harmonization gaps between compendia create formulation complexity and dual-qualification costs.
Market Dynamics
Clean-label reformulation mandates from major food retailers are compressing synthetic emulsifier tolerance windows and forcing sucroglyceride suppliers to validate natural-origin claims through third-party certification chains.
Growth Catalysts
- EU Green Deal chemical sustainability framework:Bio-based feedstock sourcing requirements are accelerating esterification process investments among European manufacturers seeking preferred supplier status.
- Bakery sector clean-label migration:Industrial bread and pastry producers are replacing DATEM and SSL with sucroglycerides to meet retailer ingredient blacklists.
- Germany precision ingredient clusters:Technical specification upgrades around Hamburg and Frankfurt are pulling premium-grade sucroglyceride demand toward HLB 9-13 specifications.
Market Restraints
- Edible oil feedstock volatility:Palm and sunflower oil price swings compress sucroglyceride margin predictability for non-integrated processors.
- REACH registration concentration:Full data package costs favor incumbent chemical conglomerates, creating qualification barriers for specialty entrants.
- Lecithin substitution threat:Non-GMO and organic lecithin variants capture clean-label budgets in cost-sensitive confectionery applications.
Strategic Opportunities
- Pharmaceutical excipient monograph harmonization:USP-NF and Ph.Eur alignment gaps create dual-qualification service revenue for contract manufacturers.
- Cosmetic-grade powder formats:Moisture-sensitive formulation demand in South Korean skincare is opening unit-dose packaging partnerships.
- EPA chemical substance reporting streamlining:Reduced documentation burdens for bio-based emulsifiers lower US market entry costs versus petroleum-derived alternatives.
Industry Challenges
- Esterification process engineering talent scarcity:Specialized glycerolysis operators command premium wages in European surfactant chemistry hubs.
- Pharmaceutical-grade certification timelines:Excipient GMP audits and IPEC-PQG compliance extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sucroglycerides Market |
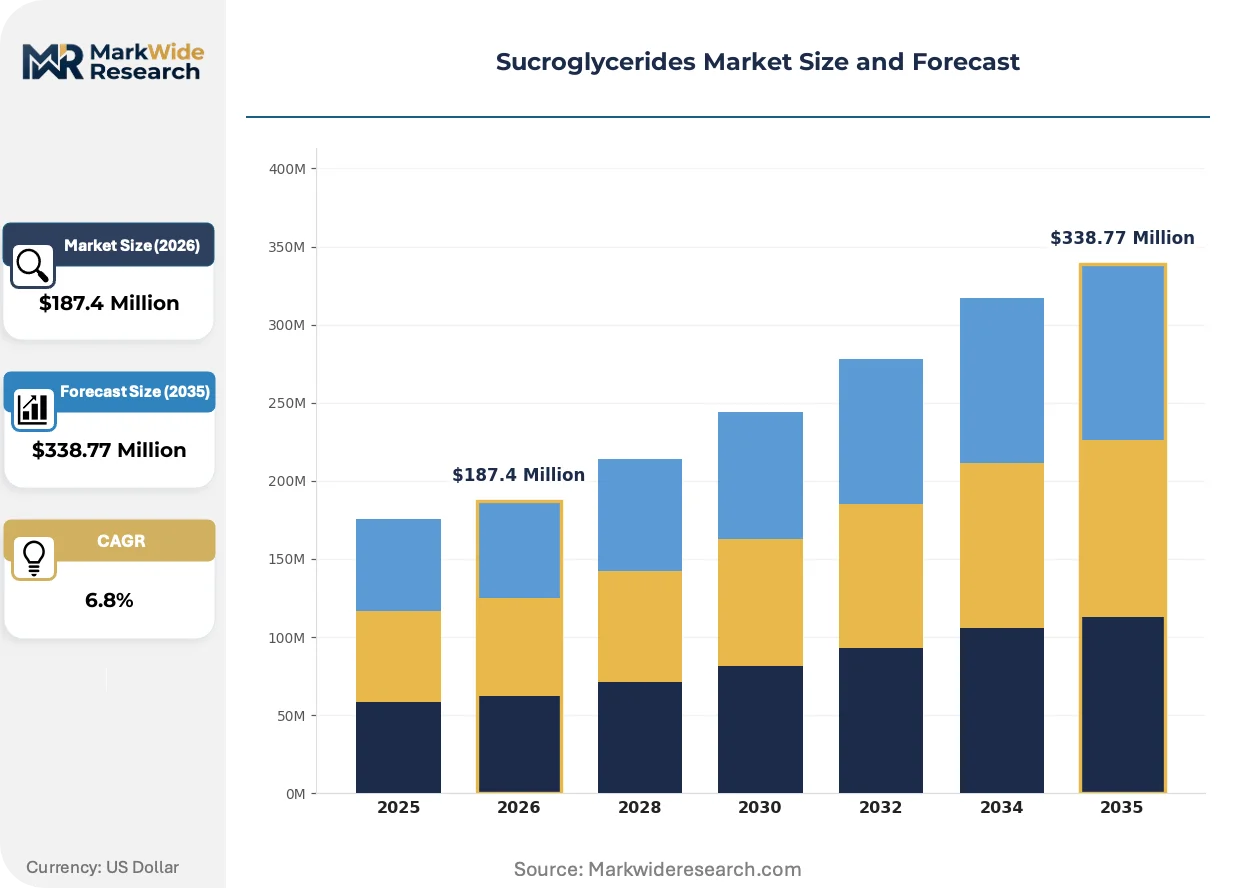
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Emulsion Application: Food Industry, Pharmaceutical, Cosmetics, Personal Care End User: Manufacturers, Retailers, Distributors, Wholesalers Distribution Channel: Online, Offline, B2B, B2C |
| Companies Covered | Archer Daniels Midland Company, AAK Bakery Services Ltd., BASF SE, Cargill Incorporated, Stepan Company, Lonza Group Ltd, Clariant AG, Beldam SA, Arakawa Chemical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sucroglycerides Market Evolving Landscape
Enzymatic esterification routes are disrupting conventional chemical catalysis, yielding selective sucroglyceride isomers with tighter HLB control for precision formulation markets.
Enzymatic glycerolysis using immobilized lipase biocatalysts is decomposing the traditional sodium methoxide catalysis monopoly in European manufacturing. Specialty lipid houses in the Netherlands and Denmark are scaling pilot volumes for pharmaceutical-grade output. This biocatalytic shift is decomposing capital barriers for mid-scale entrants while compressing thermal energy intensity by 40-60 percent versus chemical routes.
REACH registration evaluation deadlines for existing sucroglyceride substances are tightening purity disclosure requirements across the European Economic Area. ECHA substance evaluation decisions are forcing reformulation of technical-grade products into specified food-additive or pharmaceutical-grade streams. German and French suppliers are responding with dedicated registration-only product lines to isolate compliance costs from commodity volumes.
Direct procurement from emulsifier manufacturers is displacing traditional distributor intermediaries among North American bakery chains. Large industrial bakeries in the US Midwest are negotiating annual volume contracts with sucroglyceride producers for HLB-calibrated liquid deliveries. This channel consolidation is most visible in frozen dough applications where specification consistency outweighs spot-price flexibility.
Sucroglycerides Market Segmentation
Sucroglyceride procurement patterns diverge sharply across format specifications and end-use purity requirements. Channel configuration and customer scale determine which product types and applications capture margin versus volume.
Product Type:
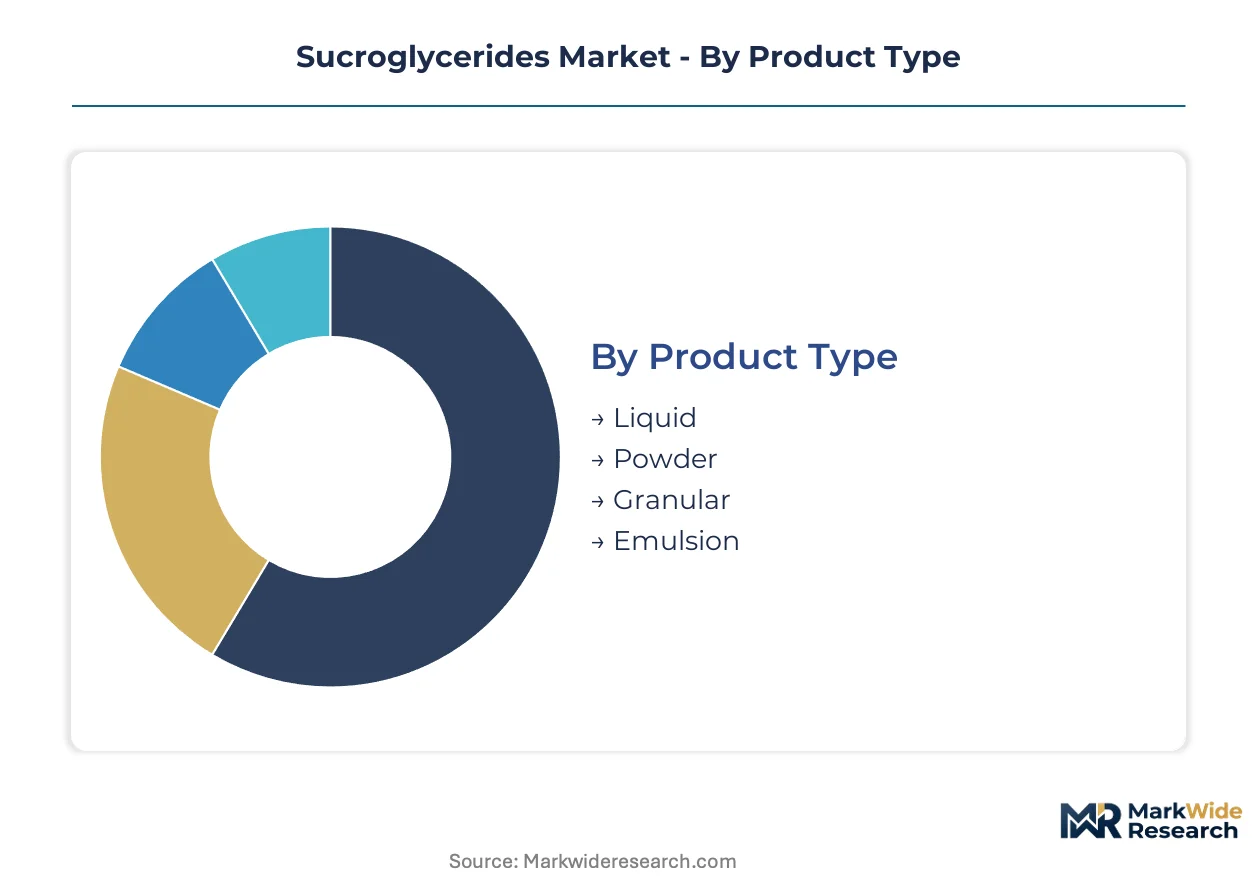
Liquid formats move predominantly through B2B bulk contracts with industrial food manufacturers, while powder and granular grades split between pharmaceutical compounders and cosmetic formulators demanding moisture-controlled packaging.
- Liquid:Dominates industrial food manufacturing through ease of dosing and blending into continuous production lines. German precision ingredient clusters around Hamburg and Frankfurt drive technical specification upgrades toward HLB 9-13 calibrated deliveries for premium bakery applications.
- Powder:Commands margin premiums in pharmaceutical and cosmetic segments where moisture sensitivity and precise unit dosing determine formulation stability. South Korean skincare manufacturers are opening unit-dose packaging partnerships for moisture-sensitive cosmetic-grade output.
- Granular:Serves intermediate processing applications requiring controlled dissolution rates in confectionery and nutritional supplement manufacturing.
- Emulsion:Targets ready-to-use formulations for small-scale food processors and specialty cosmetic compounders seeking simplified handling protocols.
Liquid sucroglycerides dominate installed base. Powder formats are where expansion concentrates.
Application:
Cost tier stratification separates commodity food-grade volumes from certified pharmaceutical and cosmetic specifications demanding dual-qualification documentation.
- Food Industry:Retains the largest revenue pool through emulsifier demand in clean-label bakery and confectionery reformulations. Industrial bread and pastry producers across the US Midwest are replacing DATEM and SSL with sucroglycerides to meet retailer ingredient blacklists.
- Pharmaceutical:Attracts R&D investment as regulatory pathways for excipient-grade sucroglycerides mature under evolving USP and Ph.Eur harmonization gaps. Excipient GMP audits and IPEC-PQG compliance extend product launch cycles by 18-24 months.
- Cosmetics:Moisture-sensitive formulation demand in South Korean skincare drives powder format adoption with specialized packaging requirements.
- Personal Care:Serves niche surfactant applications where mildness profiles and natural-origin claims support premium positioning.
Food Industry anchors volume throughput. Pharmaceutical applications are climbing the fastest.
End User:
Customer scale determines procurement modality, with large manufacturers bypassing traditional distributor intermediaries while smaller retailers and wholesalers rely on spot-market flexibility.
- Manufacturers:Large industrial bakeries negotiate annual volume contracts directly with sucroglyceride producers for HLB-calibrated liquid deliveries, displacing traditional distributor channels.
- Retailers:Clean-label reformulation mandates from major food retailers compress synthetic emulsifier tolerance windows and force suppliers to validate natural-origin claims.
- Distributors:Concentrate in technical-grade and commodity volumes where specification consistency matters less than spot-price flexibility.
- Wholesalers:Serve fragmented regional food processors and small-scale cosmetic compounders with mixed-grade inventory positions.
Manufacturers dominate direct procurement relationships. Retailers are where specification pressure concentrates.
Distribution Channel:
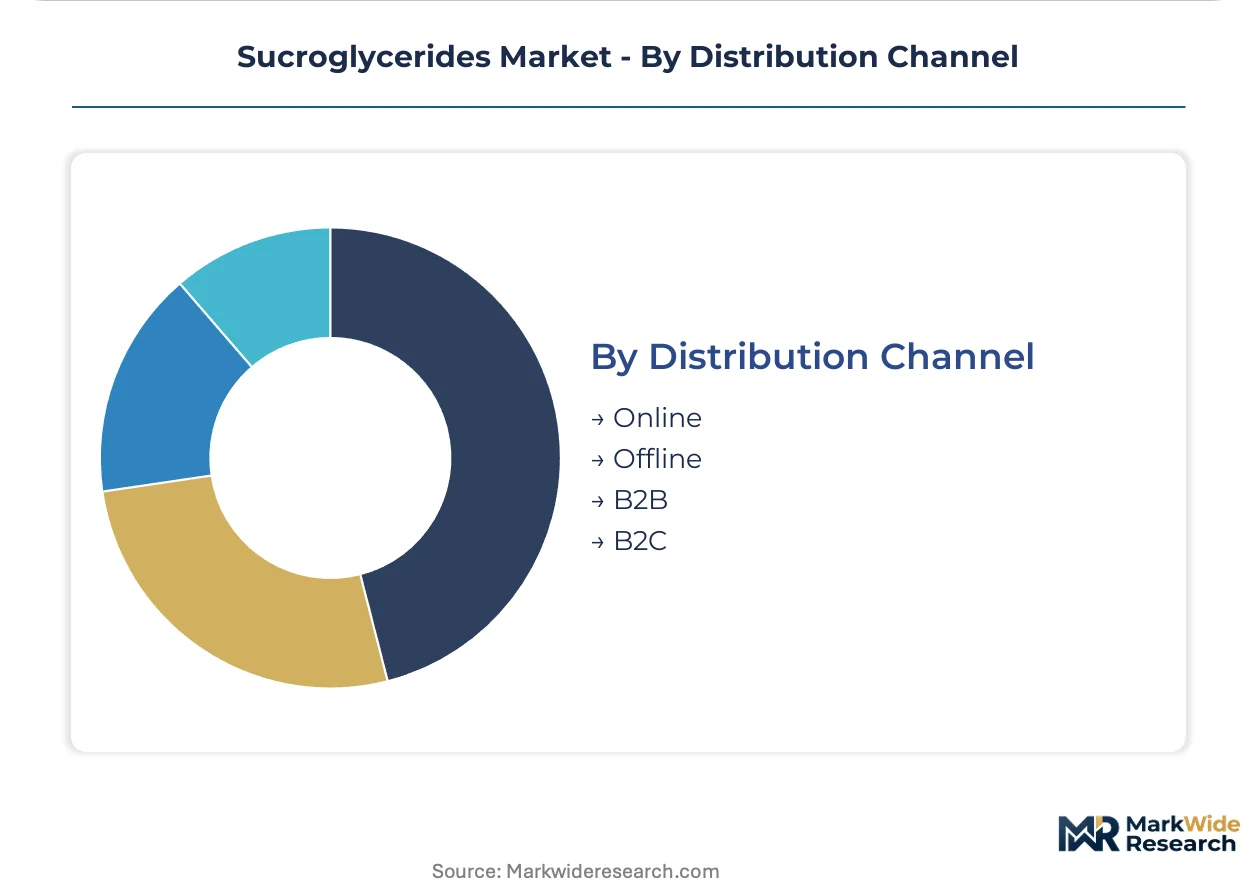
Volume scale and customer technical capability determine online versus offline channel selection, with B2B platforms capturing standardized repeat orders while B2C remains marginal.
- Online:Emerging for standardized liquid grades with established HLB specifications and certified food-additive documentation.
- Offline:Retains dominance for pharmaceutical-grade and cosmetic-grade transactions requiring technical consultation and sample validation.
- B2B:Captures bulk industrial volumes through annual contracts with specification-locked delivery schedules.
- B2C:Serves artisan food producers and small cosmetic formulators through repackaged small-lot offerings with limited technical support.
Offline B2B channels dominate transaction value. Online B2B platforms are gaining share fastest in standardized food-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated oilseed processing infrastructure concentrates in the United States, Germany, and the Netherlands, with enzymatic esterification pilots emerging in Denmark and specialty lipid houses in Japan. Regulatory divergence between FDA food additive standards and REACH registration timelines fragments supplier qualification pathways across these production hubs.
United States
Industrial bakeries across the US Midwest negotiate direct annual contracts for HLB-calibrated liquid deliveries, displacing traditional distributor channels. FDA food additive regulations and EPA chemical substance reporting requirements shape purity thresholds and documentation burdens for market access. Large frozen dough processors in Illinois and Ohio prioritize specification consistency over spot-price flexibility.
Germany
Precision food ingredient clusters around Hamburg and Frankfurt drive technical specification upgrades toward HLB 9-13 calibrated deliveries for premium bakery applications. REACH registration evaluation deadlines tighten purity disclosure requirements across the European Economic Area. ECHA substance evaluation decisions force reformulation of technical-grade products into specified food-additive or pharmaceutical-grade streams.
Netherlands
Specialty lipid houses scale pilot volumes for pharmaceutical-grade output using immobilized lipase biocatalysts. EU Green Deal chemical sustainability framework pushes manufacturers toward bio-based feedstock sourcing and reduced solvent intensity in esterification processes. Rotterdam-area surfactant chemistry hubs face specialized glycerolysis operator wage premiums.
Denmark
Enzymatic glycerolysis operations compress thermal energy intensity by 40-60 percent versus chemical routes, attracting mid-scale entrants. EFSA food contact material evaluations govern European commercialization pathways alongside REACH compliance. Copenhagen-region manufacturers respond with dedicated registration-only product lines to isolate compliance costs from commodity volumes.
Japan
Arakawa Chemical Industries anchors regional supply for moisture-sensitive cosmetic-grade powder formats demanded by South Korean skincare manufacturers. METI industrial standards and PMDA pharmaceutical regulations shape excipient-grade certification timelines. Osaka-area chemical complexes concentrate esterification capacity serving Asia-Pacific formulation markets.
Sucroglycerides Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sucroglycerides landscape. Integrated agribusiness conglomerates with captive oilseed supply chains compete against specialized surfactant houses with advanced esterification capabilities. Three strategic archetypes dominate: backward-integrated feedstock controllers, precision HLB technology specialists, and pharmaceutical-grade certification leaders. Capacity expansion in enzymatic glycerolysis and strategic partnerships for dual-qualification documentation represent the dominant competitive moves reshaping positioning.
Among integrated agribusiness players, Cargill Incorporated exemplifies the feedstock-integrated archetype through its oilseed processing infrastructure. BASF SE and Stepan Company occupy positions on the technology-specialist vector, with the former representing European surfactant chemistry leadership and the latter anchoring North American tailored emulsifier capabilities. Archer Daniels Midland Company sits within the scale-driven tier alongside these named entities.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| AAK Bakery Services Ltd. |
| BASF SE |
| Cargill Incorporated |
| Stepan Company |
| Lonza Group Ltd |
| Clariant AG |
| Beldam SA |
| Arakawa Chemical Industries |
| Others |
Value Network & Pricing Analysis
Capacity utilization at integrated oilseed processing facilities in the United States and Germany establishes price floors for high-purity sucroglyceride output, compressing margin flexibility for non-integrated processors exposed to palm and sunflower oil feedstock volatility. REACH registration cost concentration among European incumbent chemical conglomerates reinforces supply-side pricing power, while FDA food additive documentation burdens create tiered qualification premiums for United States market access.
Pricing Analysis
REACH registration dictates the pricing tier structure across the European Economic Area, separating dedicated registration-only product lines from commodity volumes. Three-tier pricing structure across pharmaceutical-grade, food-additive-grade, and technical-grade levels reflects certification investment recovery and dual-qualification documentation costs. Cost compression in food-grade liquid formats is intensifying because industrial bakeries negotiate direct annual contracts for HLB-calibrated deliveries. Small-scale cosmetic compounders and artisan food producers exhibit highest price sensitivity, while pharmaceutical compounders accept premium positioning for excipient-grade powder formats with moisture-controlled packaging.
Supply Chain Analysis
Strategic stockpiling of edible oil feedstocks dominates inventory strategy among integrated processors, while just-in-time preferences prevail among specialty lipid houses scaling enzymatic glycerolysis pilots. Supply concentrates in the United States, Germany, and the Netherlands, with emerging capacity in Denmark drawing from palm oil, sunflower oil, and sucrose feedstocks. Single-source vulnerability runs through Malaysian and Indonesian palm oil supply chains, creating tariff exposure and sustainability audit risks. Distribution runs through direct B2B bulk contracts for industrial food manufacturers, with offline channels retaining dominance for pharmaceutical-grade transactions requiring technical consultation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic esterification disruption is compressing capital barriers for mid-scale entrants while tightening HLB precision specifications across premium formulation markets. Regulatory divergence between FDA food additive standards and REACH registration timelines fragments supplier qualification pathways, favoring players with dual-jurisdiction compliance capabilities.
For Market Incumbents: Secure captive feedstock supply through backward integration into oilseed processing or long-term offtake agreements with Malaysian and Indonesian palm oil suppliers. Defend against lecithin substitution threats in clean-label confectionery by accelerating third-party natural-origin certification chains and validating enzymatic glycerolysis output for carbon intensity reductions under EU Green Deal frameworks.
For New Entrants and Emerging Players: Pharmaceutical excipient monograph harmonization fast-tracks offer service revenue opportunities in dual-qualification documentation for contract manufacturers. Target South Korean skincare manufacturers with moisture-sensitive cosmetic-grade powder formats and unit-dose packaging partnerships. Enter through enzymatic esterification pilot scale-up in Denmark or the Netherlands, leveraging 40-60 percent thermal energy intensity reductions to undercut chemical catalysis cost structures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty lipid houses with immobilized lipase biocatalyst capabilities and pharmaceutical-grade certification pipelines. Five-to-ten year viability hinges on excipient GMP audit completion and IPEC-PQG compliance achievement ahead of USP-NF and Ph.Eur alignment. Signal to watch is ECHA substance evaluation decision timing for existing sucroglyceride registrations, which will force technical-grade product line reformulations and consolidate registration-only supply among prepared players.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Esterification Scale-Up | Immobilized lipase biocatalysts compress thermal energy intensity and attract EU Green Deal preferred supplier status. |
| Pharmaceutical-Grade Certification Investment | Excipient GMP audits and IPEC-PQG compliance extend product launch cycles but lock in premium positioning. |
| Backward Integration into Oilseed Processing | Captive palm and sunflower oil supply secures margin predictability against feedstock price volatility. |
| Direct Procurement Channel Development | Annual volume contracts with US Midwest industrial bakeries displace distributor intermediaries and lock specification consistency. |
| Dual-Qualification Documentation Services | USP-NF and Ph.Eur harmonization gaps create contract manufacturing revenue for mid-scale European entrants. |
Research Methodology
A standing panel of plant managers at integrated oilseed processors, procurement leads at North American bakery chains, technical R&D directors at European surfactant houses, and regulatory affairs specialists at pharmaceutical excipient manufacturers provided ongoing calibration across the study period. Primary interview findings combined with secondary validation from FDA food additive petitions, ECHA REACH registration databases, USP-NF and Ph.Eur monograph publications, and SEC 10-K filings from disclosed agribusiness and chemical conglomerates. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Consistency checks against external benchmarks validated projection outputs across the modeling period. The analytical framework modeled segmentation dimensions including product format, application purity tier, end-user scale, and regional regulatory cluster. CAGRs derived from year-over-year growth rate progression analysis incorporating enzymatic esterification adoption curves, clean-label reformulation penetration rates, and pharmaceutical excipient certification timeline assumptions.
Underlying assumptions cover sustained EU Green Deal bio-based feedstock sourcing requirements and stable FDA food additive enforcement intensity, with deviation risk concentrated in edible oil commodity price volatility and REACH registration evaluation deadline acceleration. Revision becomes warranted when enzymatic glycerolysis cost parity thresholds cross commercial scale viability or when excipient monograph harmonization gaps narrow faster than projected.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Casamino Acids Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Spain Food Emulsifiers Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Instant Fat Powder Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Salt Substitutes Market