
 Seitan Market | 2026-2036
Seitan Market Size, Share, and Industry Trends Forecast 2026-2036
Seitan Market Intelligence
Consolidation among large food service providers and major food retailers is hardening procurement requirements for seitan producers. Sweet Earth Foods leverages its extensive distribution network to meet the demands of large-scale retail partners seeking consistent supply and volume. In contrast, Upton's Natural differentiates through its focus on specific pre-flavored and ready-to-eat product lines tailored for specialty food channels. Franklin Farms competes by offering a diverse portfolio of plant-based products, including seitan, to capture a broader consumer base.
Seitan is a high-protein food product derived from the gluten of wheat. It is produced by washing wheat flour dough with water until all the starch granules have been removed, leaving the insoluble gluten as an elastic mass. Its primary commercial purpose is to serve as a meat alternative due to its chewy, meat-like texture. The pre-flavored seitan segment is expanding, driven by consumer demand for convenience, while ready-to-eat meals and frozen foods represent major application categories for manufacturers.
Food safety and labeling standards established by regulators such as the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern market access. These regulations dictate allergen labeling, particularly concerning wheat gluten, and claims related to organic or non-GMO status. Navigating the evolving definitions of 'plant-based' and 'vegan' across international markets remains a critical strategic consideration for brand positioning and consumer trust.
Market Dynamics
Consolidation among large food service providers and retailers is hardening procurement requirements. This creates a central market tension, forcing seitan producers to balance demands for high-volume, standardized supply against consumer preferences for convenient, pre-flavored, and differentiated products.
Growth Catalysts
- Dietary Guideline Shifts:National dietary recommendations in countries like Germany endorsing plant-based proteins stimulate consumer acceptance and institutional purchasing.
- Ready-to-Eat Meal Expansion:The growing ready-to-eat meal sector provides a high-volume channel for seitan as a key protein ingredient in frozen and chilled preparations.
- Clean Label Formulations:Consumer demand for simple ingredients and non-GMO or organic certifications drives product development and premium positioning.
Market Restraints
- Input Cost Volatility:Dependence on wheat exposes producers to price fluctuations in global grain markets, affecting production costs and margin stability.
- Protein Substitute Competition:Intense competition from soy, pea, and mycoprotein alternatives, which are often gluten-free, constrains market penetration.
- Allergen-Based Market Limitation:Mandatory wheat allergen labeling under FDA and EFSA rules excludes consumers with celiac disease or gluten sensitivity.
Strategic Opportunities
- Asia-Pacific Market Development:Introducing modern, pre-flavored seitan formats to markets like Japan and South Korea builds on local familiarity with traditional wheat gluten.
- Food Service Customization:Creating tailored seitan products for quick-service restaurant (QSR) chains opens a significant volume channel beyond retail.
- Hybrid Protein Blends:Formulating products combining seitan with pea protein enhances nutritional profiles and texture, broadening consumer appeal.
Industry Challenges
- Production Consistency:Maintaining consistent texture and flavor across large-scale production batches presents a significant technical hurdle, as raw wheat gluten quality can vary.
- Navigating Labeling Ambiguity:Brands must navigate evolving definitions of 'plant-based' and 'vegan' across different regulatory jurisdictions, such as the EU and US, which complicates marketing and compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seitan Market |
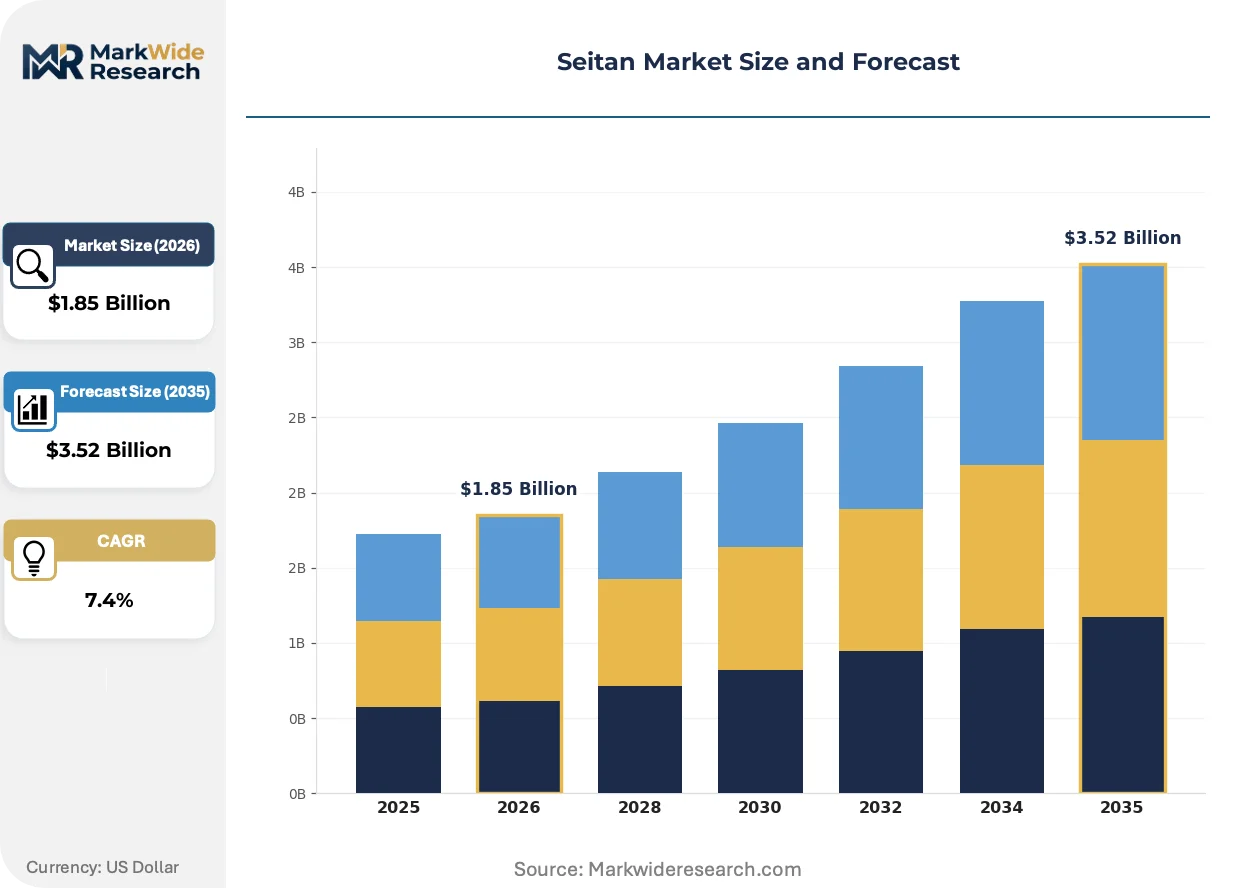
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.52 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Seitan, Dried Seitan, Pre-Flavored Seitan, Organic Seitan, Raw Seitan Application: Meat Alternatives, Snack Foods, Ready-to-Eat Meals, Vegan Bakery, Frozen Foods Packaging Type: Vacuum Packs, Resealable Bags, Cans, Trays, Bulk Packs Customer Type: Health-Conscious Consumers, Vegan Restaurants, Food Retailers, Specialty Stores, Food Service Providers |
| Companies Covered | Tofoo, Biona Organic, Upton's Natural, TerraSana, The Bridge, Companion Foods, Franklin Farms, Topas, Sweet Earth Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seitan Market Strategic Shifts & Innovations
Product innovation is shifting from basic meat mimicry towards functional integration into convenience foods. This evolution is driven by advanced processing and stricter labeling standards that redefine consumer expectations for plant-based authenticity.
High-moisture extrusion technology uses heat and pressure to create more fibrous, meat-like textures from plant proteins. Food manufacturers are adopting this to produce realistic seitan-based whole-cut alternatives, moving beyond ground formats. This capability is decentralizing product development, enabling smaller brands to compete on textural quality, not just production volume.
The adoption of front-of-pack nutrition labeling systems, like Nutri-Score in the European Union, is influencing product formulation. This pressures manufacturers to lower sodium and fat in pre-flavored seitan to achieve better health ratings. The ready-to-eat segment is most affected, with brands in France and Germany reformulating recipes to improve their scores.
Consumer purchasing is moving from specialty health food stores towards mainstream supermarkets for plant-based items. This channel shift disrupts traditional distribution, favoring producers with the scale and logistics to supply large grocery chains. The trend is highly visible in the United States and United Kingdom, where retailers are expanding dedicated plant-based sections.
Seitan Market Segmentation
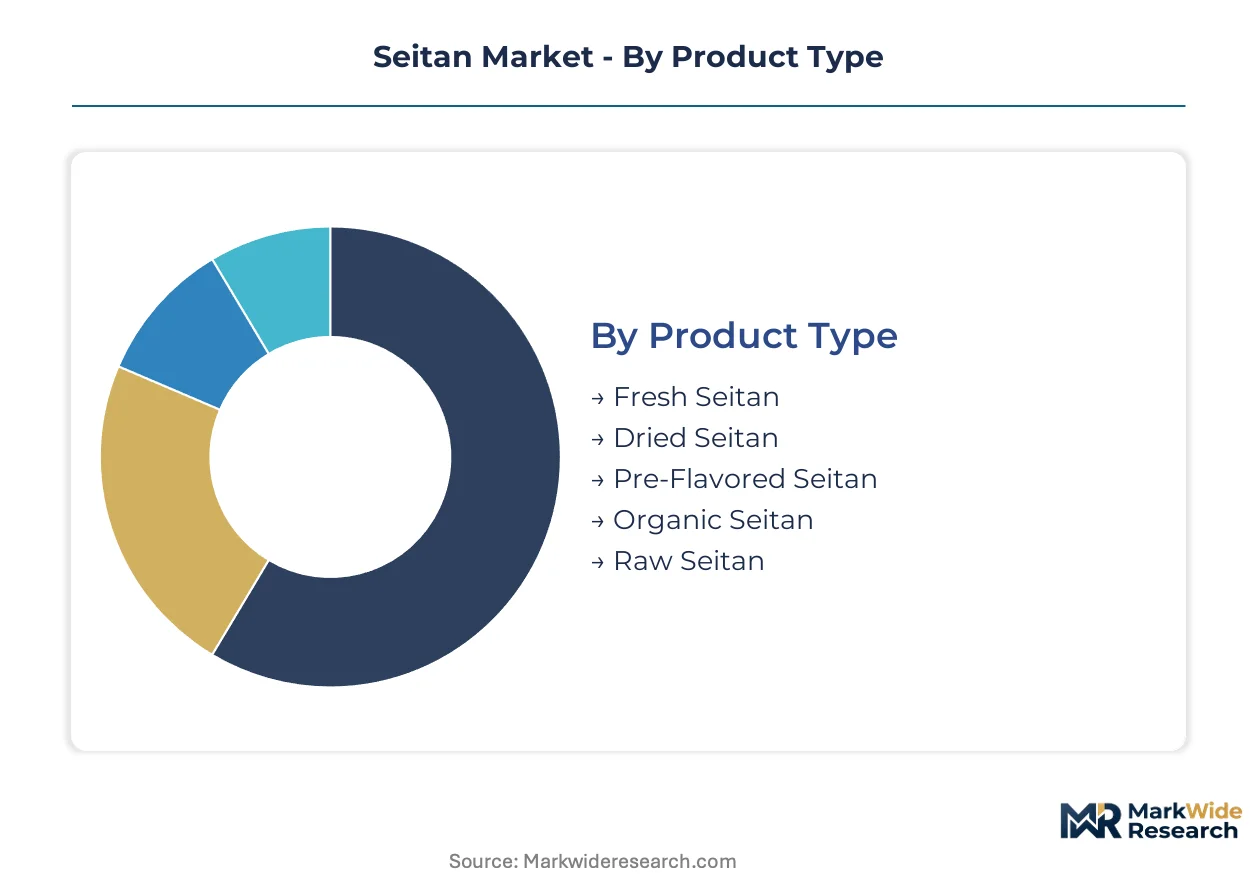
The seitan market segments across product type, application, packaging, and customer demographics, reflecting diverse consumer preferences and industrial demands. Understanding these categories helps manufacturers tailor offerings to specific market niches, from health-conscious individuals to large food service operations.
Product Type:
Product types delineate seitan's journey from raw ingredient to finished consumer good, distinguishing between fundamental forms and value-added preparations.
- Pre-Flavored Seitan:This segment includes seitan products pre-seasoned or marinated, offering consumers immediate convenience for meal preparation. Demand from the ready-to-eat meals sector in Germany drives its expansion.
- Organic Seitan:Certified organic seitan adheres to stringent agricultural and processing standards, appealing to consumers prioritizing clean labels and sustainable food choices. Stricter food labeling regulations from the European Food Safety Authority influence its formulation.
- Fresh Seitan:Unprocessed seitan typically sold in bulk or refrigerated forms, providing a versatile base for culinary applications.
- Dried Seitan:Dehydrated seitan offers extended shelf life and reduced weight, making it suitable for pantry storage and certain food manufacturing processes.
- Raw Seitan:Basic wheat gluten in its unflavored, unseasoned state, serving as a foundational ingredient for further processing by consumers or food manufacturers.
Volume placements concentrate in Fresh Seitan; the faster expansion belongs to Pre-Flavored Seitan.
Application:
Application categories illustrate the diverse ways seitan integrates into the food system, from direct meat substitutes to components in complex prepared foods.
- Ready-to-Eat Meals:Seitan serves as a primary protein component in convenience-focused prepared meals, including chilled and frozen options. The growing ready-to-eat meal sector in the United States provides a high-volume channel for seitan.
- Meat Alternatives:This category represents seitan's foundational use as a direct substitute for traditional meat in various culinary contexts. Intense competition from soy and pea protein alternatives challenges market penetration.
- Snack Foods:Seitan finds use in plant-based snack products, offering a protein-rich option for on-the-go consumption.
- Vegan Bakery:Seitan's unique texture and protein content make it suitable for specific applications within the vegan bakery sector, enhancing structure and nutritional value.
- Frozen Foods:Seitan is incorporated into a wide array of frozen plant-based dishes, capitalizing on consumer demand for convenient, long-lasting meal solutions.
The largest share of seitan consumption comes from Meat Alternatives; Ready-to-Eat Meals show the steepest expansion trajectory.
Packaging Type:
Packaging types reflect strategies for preserving freshness, extending shelf life, and facilitating distribution across various retail and food service channels.
- Vacuum Packs:This packaging method removes air to extend the shelf life of fresh seitan, maintaining product quality and preventing spoilage. It supports distribution to major food retailers in Europe.
- Bulk Packs:Larger format packaging caters to the high-volume requirements of food service providers and industrial clients, prioritizing cost-efficiency and reduced waste. Consolidation among large food service providers hardens procurement requirements.
- Resealable Bags:These offer consumer convenience, allowing for multiple uses while maintaining product freshness after opening.
- Trays:Often used for pre-portioned or marinated seitan, trays provide structural integrity and visual appeal in refrigerated sections.
- Cans:Canning provides a long-shelf-life option for seitan, suitable for ambient storage and emergency food supplies.
Packaging volume largely flows through Bulk Packs; Vacuum Packs are gaining share fastest in retail.
Customer Type:
Customer types delineate the primary end-users of seitan products, influencing product development and marketing strategies.
- Food Retailers:Supermarkets and grocery chains represent a major distribution channel, stocking diverse seitan products for mainstream consumers. Consumer purchasing is moving from specialty stores towards mainstream supermarkets in the United Kingdom.
- Food Service Providers:Restaurants, cafeterias, and institutional kitchens use seitan as a versatile plant-based protein in their menus. Creating tailored seitan products for quick-service restaurant chains opens a significant volume channel.
- Health-Conscious Consumers:Individuals actively seeking nutritious and plant-based dietary options drive demand for seitan. Germany shows a high adoption rate among health-conscious consumers.
- Vegan Restaurants:Establishments exclusively serving plant-based cuisine heavily feature seitan as a core ingredient.
- Specialty Stores:Health food stores and gourmet shops offer a curated selection of seitan products, often catering to niche preferences.
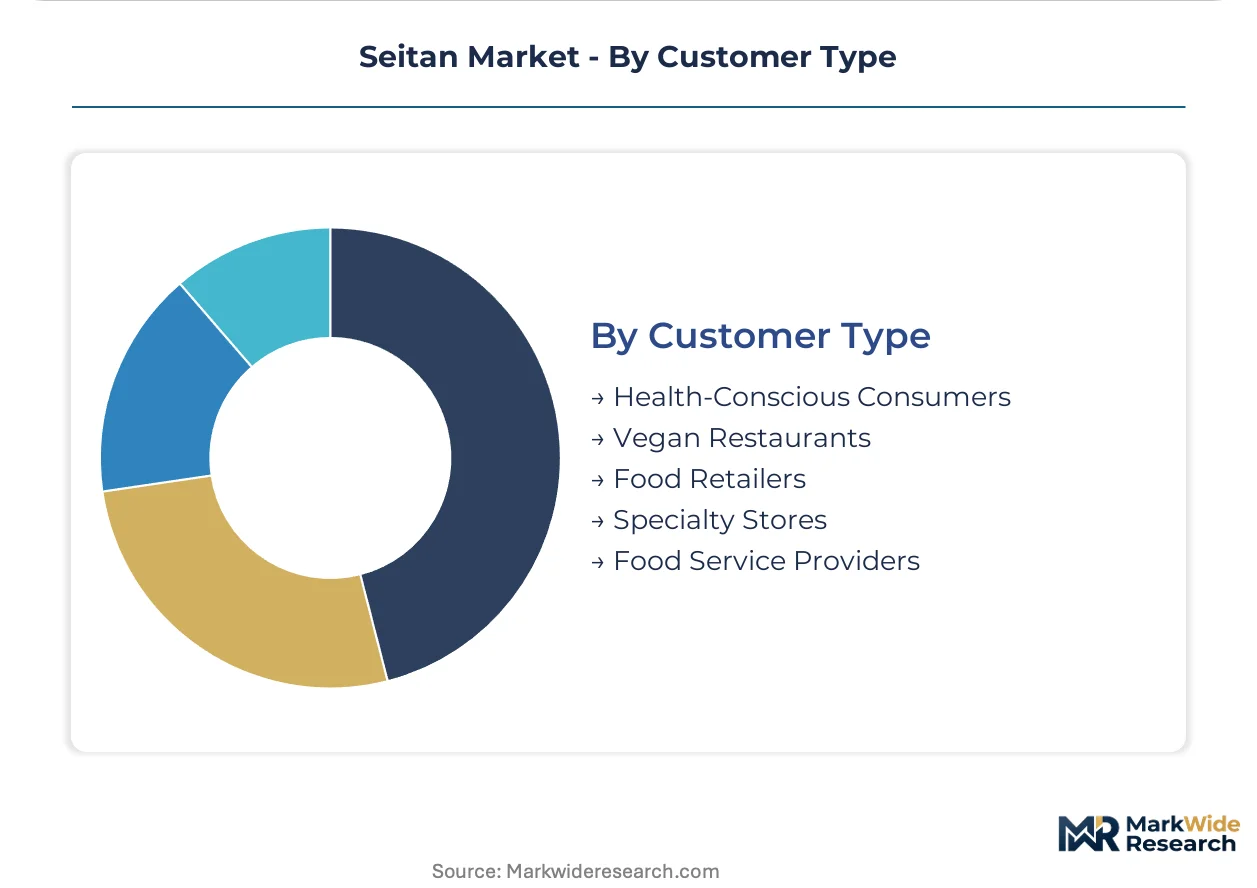
The largest customer base for seitan is Food Retailers; Food Service Providers are demonstrating climbing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Market demand for seitan concentrates in European countries, particularly Germany, driven by health-conscious consumers. The growing ready-to-eat meal sector provides a high-volume channel for seitan across various geographies. National dietary recommendations also stimulate consumer acceptance and institutional purchasing.
Germany
Demand for organic seitan is high, influenced by national dietary recommendations endorsing plant-based proteins. The European Food Safety Authority (EFSA) influences formulation for organic and clean-label products. Munich's food manufacturing cluster actively reformulates seitan recipes to improve Nutri-Score ratings.
United States
The ready-to-eat meal sector provides a significant channel for seitan as a key protein ingredient. The U.S. Food and Drug Administration (FDA) mandates allergen labeling for wheat gluten. Los Angeles food service providers increasingly customize seitan products for quick-service restaurant chains.
United Kingdom
Consumer purchasing shifts from specialty stores to mainstream supermarkets, expanding seitan's retail presence. Front-of-pack nutrition labeling systems influence product formulation to lower sodium and fat. London's vibrant plant-based food scene sees dedicated sections in large grocery chains.
Japan
Asia-Pacific market development for modern, pre-flavored seitan formats builds on local familiarity with traditional wheat gluten. The Ministry of Agriculture, Forestry and Fisheries (MAFF) supports sustainable food initiatives. Tokyo's innovative food companies develop hybrid protein blends for enhanced nutritional profiles.
France
Front-of-pack nutrition labeling systems, like Nutri-Score, pressure manufacturers to reformulate products. The Agence nationale de sécurité sanitaire de l'alimentation, de l'environnement et du travail (ANSES) guides dietary recommendations. Paris-based brands reformulate pre-flavored seitan recipes to achieve better health ratings.
Seitan Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized, convenience-driven product lines. The market structure features a mix of large-scale volume providers and niche players focusing on specific product attributes. Two strategic archetypes include diversified plant-based portfolios and pre-flavored convenience offerings. Dominant competitive moves involve expanding distribution networks and product innovation for texture and flavor.
On the premium-tier vector, Upton's Natural exemplifies differentiation through specific pre-flavored and ready-to-eat product lines tailored for specialty food channels. This approach allows them to cater to consumers seeking unique and convenient seitan preparations. Sweet Earth Foods represents a scale-driven approach, leveraging its extensive distribution network to meet the demands of large-scale retail partners seeking consistent supply and volume. Franklin Farms occupies a position as a diversified plant-based product provider, offering a broad portfolio including seitan to capture a wider consumer base across various retail channels.
| Leading Market Players |
|---|
| Tofoo |
| Biona Organic |
| Upton's Natural |
| TerraSana |
| The Bridge |
| Companion Foods |
| Franklin Farms |
| Topas |
| Sweet Earth Foods |
| Others |
Cost & Logistics Intelligence
Wheat input cost volatility directly influences seitan production expenses, subsequently impacting downstream pricing tiers for both bulk food service providers and premium retail offerings.
Pricing Analysis
Volume-driven segments often operate on tighter margins compared to specialized, pre-flavored seitan products. Contract-based long-term offtake agreements define pricing for large food service providers, while per-unit transactional models apply to retail. Price differentiation stems from certification levels, such as organic status, and the degree of product customization. Pricing pressure stems from intense competition from alternative proteins like soy and pea. Food service buyers demonstrate high price sensitivity, whereas health-conscious consumers purchasing organic or pre-flavored seitan exhibit lower price sensitivity.
Supply Chain Analysis
Raw wheat flour supply relies heavily on major agricultural regions in the United States, Europe, and China. This dependence exposes seitan producers to global commodity price fluctuations for wheat, creating a significant supply chain risk. Upstream processing of wheat gluten occurs in specialized facilities, often concentrated in these same regions. Distribution runs through a dual model, with bulk packs moving to food service providers and manufacturers, while packaged, consumer-ready products are supplied to retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seitan market presents a supply-constrained opportunity, with consistent texture and flavor across large-scale production batches representing a key capacity bottleneck propping pricing.
For Market Incumbents: Anticipate shifts in consumer preferences towards cleaner labels and invest in advanced processing technologies like high-moisture extrusion. Expand distribution networks to capitalize on the mainstreaming of plant-based products in the United States and United Kingdom. Invest in R&D to enhance textural consistency and flavor profiles, mitigating the competitive threat from soy and pea protein alternatives. Secure organic and non-GMO certifications to defend premium positioning.
For New Entrants and Emerging Players: Begin with targeted product innovation for specific, under-served dietary needs or culinary applications. Asia-Pacific markets, particularly Japan and South Korea, represent a penetrable segment for modern, pre-flavored seitan formats. Focus on differentiating through unique flavor profiles and convenient ready-to-eat offerings tailored for specialty food channels. Leverage strong digital marketing to build brand trust around specific plant-based claims.
For Investors and Strategic Acquirers: Mainstream supermarket penetration rates are the leading indicator that the seitan market is maturing beyond niche status. Long-term viability for the next 5-10 years remains strong, driven by sustained plant-based protein demand. Target mid-sized producers with established brands in pre-flavored or organic segments, or those possessing proprietary advanced processing capabilities. Watch for increased consolidation among smaller players as large food retailers harden procurement requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Processing Technology Adoption | This improves textural consistency and enables whole-cut seitan alternatives, enhancing product appeal for consumers. |
| Distribution Channel Expansion (Mainstream Retail) | This captures a broader consumer base as plant-based purchasing shifts from specialty stores to large grocery chains. |
| Product Line Diversification (Hybrid Proteins) | This enhances nutritional profiles and broadens consumer appeal beyond traditional seitan users. |
| Geographic Market Entry (Asia-Pacific) | This leverages local familiarity with wheat gluten to introduce modern, convenient seitan formats. |
| Clean Label Certification Investment | This builds consumer trust and meets evolving regulatory standards for organic and non-GMO claims. |
Research Approach
Independent corroboration across primary interviews, government food safety reports, and industry association publications underwrites the qualitative findings. This approach combines insights from food manufacturers, retail category buyers, food service procurement managers, and regulatory affairs specialists. Secondary validation draws from financial filings of public food companies and trade statistics, triangulating data through both bottom-up and top-down analyses.
The forecast framework anchored the analysis window by examining historical performance across comparable periods, extending projections over the modeling period. Segmentation dimensions included product type, application, packaging type, customer type, and regional dietary shifts. Compound Annual Growth Rates were derived from historical trends and projected market influences, incorporating inputs such as plant-based protein adoption rates and wheat commodity prices.
Underlying measurement precision varies by segment; pre-flavored seitan and ready-to-eat meals carry tighter precision than others. Forecasts reflect assumptions regarding evolving regulatory landscapes and consumer preferences. A small set of named triggers warrants ongoing watch, including volatility in wheat prices and new regulatory definitions for 'plant-based' claims.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Feather Meal Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
South America Fat Replacers Market
Alternative Food Sources
Paleo Food Market
Alternative Food Sources
Bioengineered Food Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Algal Protein Market