
 Oleic Acid Market | 2026-2036
Oleic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Oleic Acid Market Analysis
The capital-intensity divergence between integrated palm-oil refiners and standalone fatty-acid processors is unwinding as feedstock volatility reshapes margin structures. Cargill, Incorporated leverages its upstream oilseed crushing networks to sustain cost-advantaged oleic acid supply across multiple continents. KLK Oleo anchors its position through integrated oleochemical complexes in Southeast Asia that control refining and fractionation in-house. Emery Oleochemicals differentiates via specialized high-purity grades for pharmaceutical and cosmetic applications.
Oleic acid is a monounsaturated omega-9 fatty acid with the chemical formula C18H34O2, typically derived from vegetable oils such as olive, sunflower, or palm through hydrolysis and fractional distillation processes yielding purity grades from 70% to over 90%. Its primary industrial purpose centers on surfactant synthesis, emulsification, and lubricity enhancement across food, cosmetic, and pharmaceutical formulations. Refined oleic acid dominates volume flows due to established supply chains serving food and industrial buyers, while hydrogenated oleic acid captures expanding demand from lubricant formulators seeking oxidative stability. The pharmaceutical application segment concentrates margin pools where Croda International Plc and BASF SE compete on USP-grade certification and excipient compliance.
The FDA governs oleic acid used in food-contact substances and pharmaceutical excipients under 21 CFR specifications, while REACH in Europe mandates registration and hazard communication for oleochemical imports exceeding one tonne annually. India's BIS has progressively tightened oleic acid quality standards for edible and industrial grades, aligning with FSSAI safety protocols for food-chain applications. Stakeholders must monitor how diverging purity benchmarks across FDA, REACH, and BIS frameworks reshape formulation requirements and sourcing geography.
Market Dynamics
Feedstock volatility from palm and sunflower oil markets is compressing margin structures across the oleic acid value chain, forcing processors to reconfigure sourcing strategies and locking in long-term supply contracts.
Growth Catalysts
- Clean-label food formulations:Manufacturers in India and Southeast Asia are expanding oleic acid procurement for natural emulsifier applications, replacing synthetic additives in processed foods.
- REACH compliance upgrades:European purity benchmarks for oleochemical imports are pulling higher-grade oleic acid into pharmaceutical and cosmetic supply chains.
- PLI-linked manufacturing incentives:India's production-linked incentive schemes for oleochemicals are drawing capital investment into domestic fractionation capacity.
Market Restraints
- Palm oil price volatility:Malaysian and Indonesian feedstock markets exhibit cyclical swings that destabilize oleic acid production economics for non-integrated processors.
- High-purity certification barriers:USP-grade and food-grade compliance timelines stretch 18-24 months, freezing out smaller entrants from pharmaceutical and edible segments.
- Erucic acid substitution:High-erucic rapeseed oil derivatives compete in select lubricant and surfactant applications where oxidative stability requirements are less stringent.
Strategic Opportunities
- Pharmaceutical excipient expansion:Parenteral drug delivery systems and lipid nanoparticle formulations are opening new volume channels for USP-grade oleic acid.
- Bio-based lubricant mandates:EU Green Deal targets for renewable industrial fluids are creating specification pull for hydrogenated oleic acid in metalworking and hydraulic applications.
- Direct-to-formulator distribution:Specialty chemical platforms and regional distributors are disintermediating traditional merchant traders in mid-market cosmetic and personal care segments.
Industry Challenges
- Fractionation technician scarcity:Specialized distillation and crystallization expertise is concentrated among retiring cohorts in European and Southeast Asian oleochemical hubs.
- Multi-jurisdiction compliance synchronization:Reconciling divergent FDA, REACH, and BIS purity protocols requires dedicated regulatory affairs capacity that strains mid-size processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oleic Acid Market |
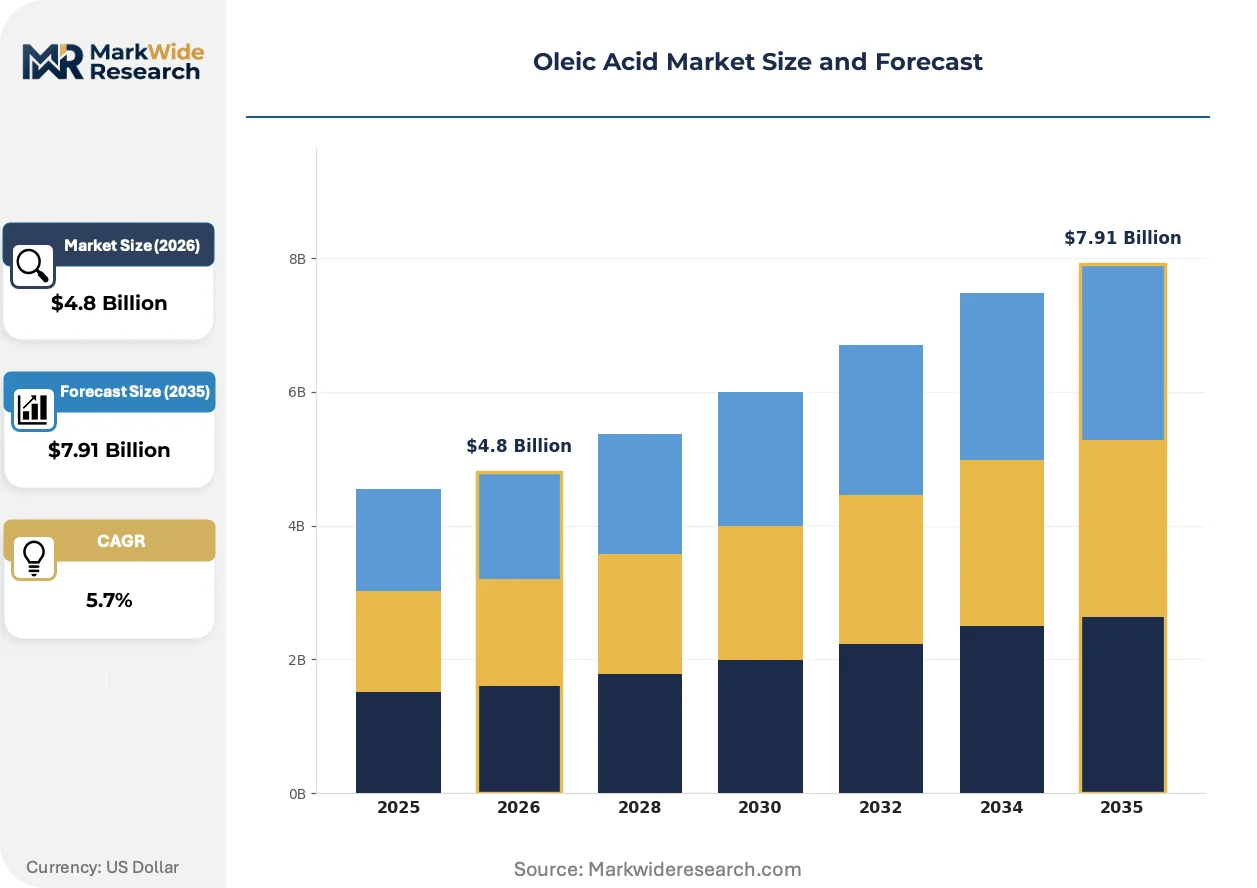
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oleic Acid, Hydrogenated Oleic Acid, Mixed Acids, Natural Oleic Acid Application: Food Industry, Cosmetic Products, Pharmaceuticals, Lubricants Form: Liquid, Solid, Emulsion, Paste End User: Food Manufacturers, Personal Care Companies, Pharmaceutical Firms, Industrial Users |
| Companies Covered | Cargill, Incorporated, KLK Oleo, Wilmar International Limited, Emery Oleochemicals, IOI Oleochemical Group, BASF SE, Croda International Plc, P&G Chemicals, Oleon NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oleic Acid Market Emerging Trajectories
Enzymatic interesterification and precision fermentation routes are emerging alongside conventional hydrolysis, fragmenting the technology base and forcing incumbents to defend process economics against novel production architectures.
Membrane filtration and simulated moving bed chromatography are displacing traditional fractional distillation for oleic acid purification, delivering energy efficiency gains of 15-25% versus thermal separation. Specialty chemical producers in Germany and the Netherlands are piloting these systems at commercial scale. The technology is bifurcating the market between legacy thermal processors and membrane-adopters, with purity premiums compressing for standard grades while widening for pharmaceutical-tier output.
REACH registration requirements for oleochemical substances exceeding one tonne annually are tightening hazard communication and safety data sheet protocols across European supply chains. Downstream formulators now demand full substance identity disclosure that was previously obscured in blended fatty acid products. Pharmaceutical and cosmetic end-users in France and Germany are driving this transparency shift, auditing supplier dossiers against ECHA compliance timelines.
Long-term offtake agreements are displacing spot market purchasing among large food and personal care manufacturers seeking supply security amid feedstock volatility. These contracts typically span 3-5 years with price collars tied to palm oil futures. Procurement consolidation is most pronounced among multinational buyers with manufacturing footprints in India and Indonesia, where local sourcing mandates intersect with global quality specifications.
Oleic Acid Market Segmentation
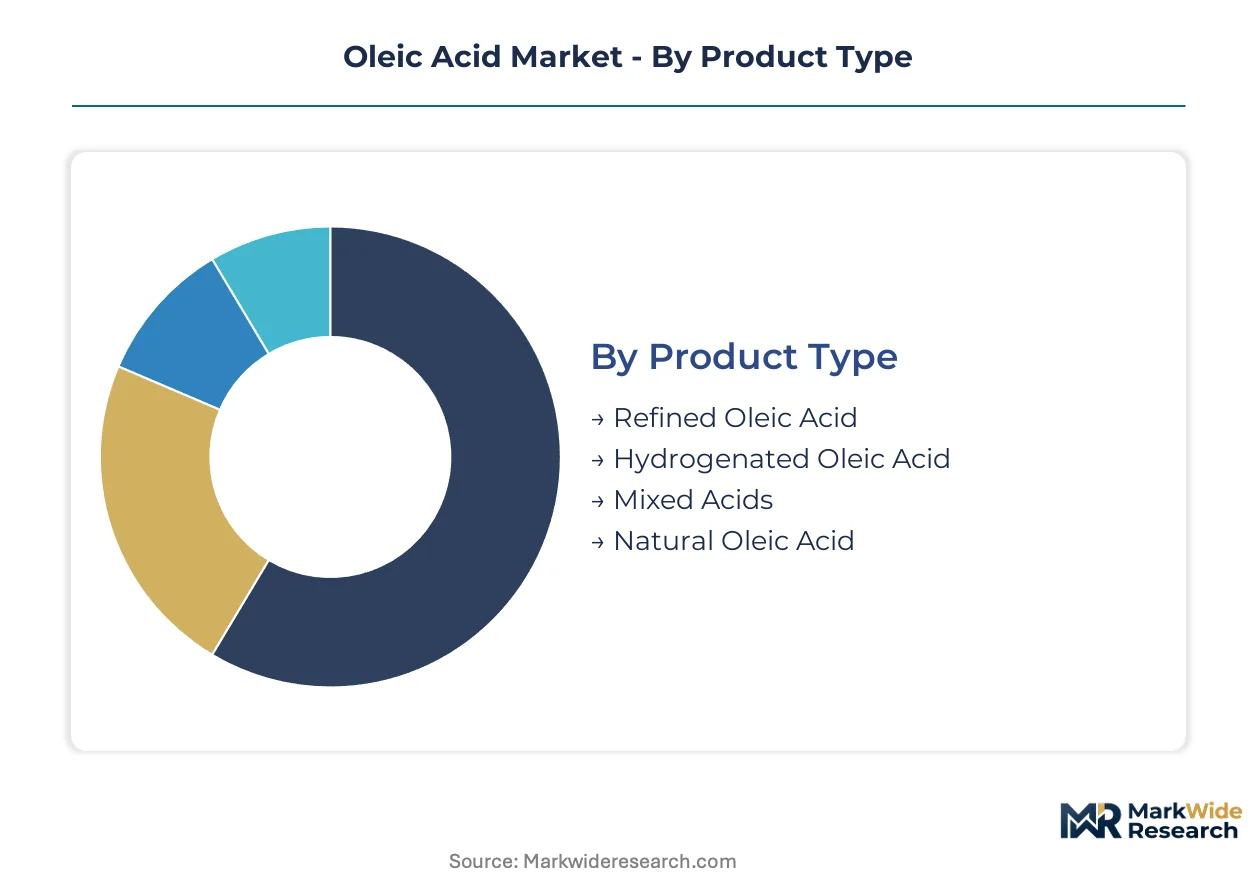
Oleic acid procurement patterns diverge sharply across product grades and end-use specifications. Formulators in food and pharmaceutical channels impose purity thresholds that reshape supplier economics and geographic sourcing priorities.
Product Type:
Refined oleic acid serves predominantly domestic food and industrial markets across India and Southeast Asia. Hydrogenated grades command export premiums into European lubricant formulations.
- Refined Oleic Acid:Standard purity grades between 70% and 90% C18H34O2 content dominate volume flows through established palm oil fractionation networks. Indian food manufacturers under FSSAI protocols are expanding procurement for clean-label emulsifier applications, displacing synthetic additives in processed foods.
- Hydrogenated Oleic Acid:Saturated derivatives deliver oxidative stability for metalworking fluids and hydraulic systems. EU Green Deal mandates for renewable industrial lubricants are pulling hydrogenated grades into German and Dutch manufacturing supply chains.
- Mixed Acids:Blended fatty acid streams from multi-feedstock refineries serve cost-sensitive surfactant producers in Indonesia and Malaysia.
- Natural Oleic Acid:Cold-pressed olive and sunflower derivatives target premium cosmetic channels in France and Italy.
Refined oleic acid commands the established base. The steepest expansion runs through hydrogenated oleic acid.
Application:
Margin concentration varies dramatically across end-use channels, with pharmaceutical and cosmetic applications capturing premium pricing over commodity food and industrial segments.
- Food Industry:Emulsification and lubricity enhancement in bakery, confectionery, and dairy formulations. Indian processors are scaling natural oleic acid procurement to meet PLI-linked domestic production incentives.
- Cosmetic Products:Surfactant synthesis for personal care formulations requiring REACH-compliant hazard disclosure. French and German formulators are auditing supplier dossiers against ECHA substance identity protocols.
- Pharmaceuticals:USP-grade excipients for parenteral drug delivery and lipid nanoparticle carriers. CDSCO alignment with ICH guidelines is tightening purity benchmarks for Indian pharmaceutical oleic acid sourcing.
- Lubricants:Bio-based metalworking and hydraulic fluids under EU renewable content mandates. Erucic acid derivatives from high-erucic rapeseed oil compete in select oxidative stability applications.
Food industry volumes anchor current procurement. Pharmaceutical applications are climbing the fastest.
Form:
Physical state selection tracks downstream processing requirements and transportation economics across liquid bulk and specialty solid formulations.
- Liquid:Bulk tanker and drum shipments dominate intercontinental trade through Rotterdam and Singapore hub terminals.
- Solid:Flake and bead forms reduce shipping costs for inland Indian and Chinese destinations lacking liquid handling infrastructure.
- Emulsion:Pre-dispersed aqueous formulations accelerate cosmetic and food manufacturer batch processing.
- Paste:Semi-solid concentrates serve niche pharmaceutical compounding and specialty lubricant blending operations.
Liquid forms capture the volume base. Emulsion formats are gaining share fastest in cosmetic manufacturing.
End User:
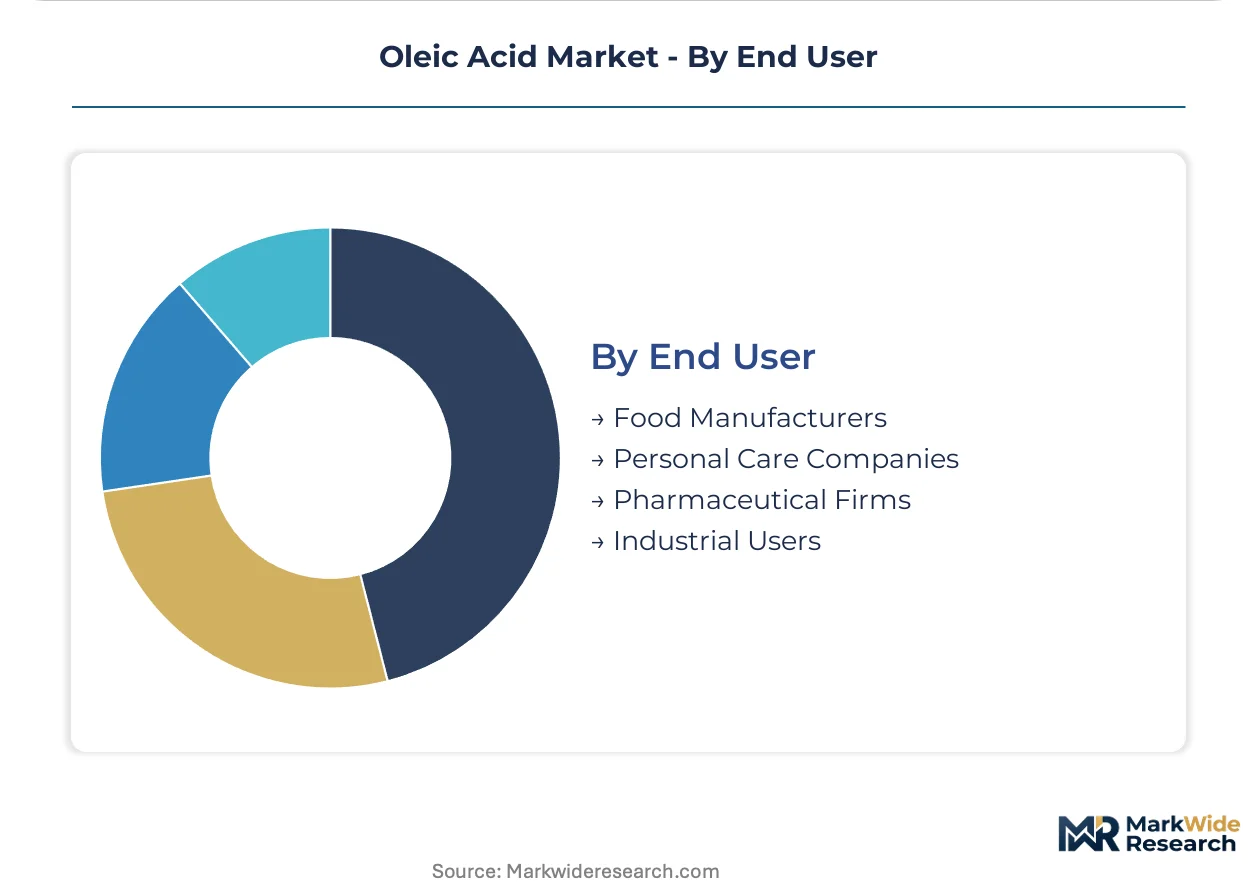
Procurement consolidation is concentrating volume among multinational food and personal care manufacturers with integrated supply chain footprints.
- Food Manufacturers:Processed food and bakery conglomerates in India and Indonesia are locking 3-5 year offtake agreements with price collars tied to palm oil futures.
- Personal Care Companies:Cosmetic formulators in Germany and the Netherlands are piloting membrane filtration grades for energy-efficient purification.
- Pharmaceutical Firms:Parenteral drug developers require USP-grade certification with 18-24 month compliance timelines that freeze out smaller oleochemical suppliers.
- Industrial Users:Lubricant blenders and surfactant producers face margin compression from feedstock volatility in Malaysian and Indonesian palm oil markets.
Food manufacturers command the established demand base. Pharmaceutical firms are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. India deploys oleic acid predominantly for food emulsification under domestic production incentives, while European buyers prioritize pharmaceutical-grade purity under REACH protocols, and U.S. procurement concentrates on lubricant applications governed by FDA food-contact rules.
India
Domestic food manufacturers are scaling natural oleic acid procurement to replace synthetic emulsifiers in processed bakery and dairy formulations. The PLI scheme for oleochemicals is drawing multinational investment into fractionation capacity at Mundra and Dahej. Gujarat's integrated oleochemical complexes now control refining and distillation operations previously sourced from Southeast Asian traders.
Germany
Pharmaceutical formulators in Ludwigshafen and Leverkusen are auditing supplier dossiers against ECHA substance identity protocols for lipid nanoparticle excipients. REACH registration requirements exceeding one tonne annually are tightening hazard communication standards. The Rhine-Ruhr industrial corridor hosts membrane filtration pilots displacing conventional thermal separation for energy-efficient purification.
United States
Lubricant blenders in Texas and Louisiana are locking long-term offtake agreements for hydrogenated grades amid bio-based fluid mandates. FDA 21 CFR specifications govern food-contact and pharmaceutical excipient applications. The Gulf Coast petrochemical corridor is integrating oleic acid into renewable metalworking fluid formulations for automotive and aerospace supply chains.
Indonesia
Palm oil refiners in Sumatra and Kalimantan are expanding fractionation output for regional surfactant producers serving ASEAN personal care markets. Feedstock volatility from Malaysian palm oil markets is compressing margins for non-integrated processors. The Surabaya-Jakarta industrial belt concentrates blending operations for cost-sensitive mixed acid streams.
Netherlands
Rotterdam terminal operators are consolidating intercontinental liquid bulk shipments for distribution into German and French cosmetic manufacturing. EU Green Deal targets for renewable industrial fluids are pulling hydrogenated oleic acid into Dutch metalworking supply chains. The Port of Rotterdam's oleochemical trading hub is disintermediating traditional merchant traders through direct-to-formulator platforms.
Oleic Acid Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the oleic acid market. The upper tier comprises agribusiness conglomerates with captive oilseed crushing and fractionation networks, while mid-tier players compete on purity certification and application-specific grades. Two strategic archetypes dominate: upstream-integrated refiners controlling feedstock-to-acid conversion, and downstream-specialized formulators targeting pharmaceutical and cosmetic channels. Competitive moves concentrate on long-term supply contract lock-ins and membrane filtration technology licensing.
Among integrated agribusiness operators, Cargill, Incorporated and Wilmar International Limited exemplify the upstream-control archetype through oilseed crushing networks spanning multiple continents. KLK Oleo anchors the Southeast Asian specialist tier with integrated oleochemical complexes. These three names represent the structural divide between feedstock-secured volume players and purity-focused grade specialists competing for pharmaceutical and cosmetic margin pools.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| KLK Oleo |
| Wilmar International Limited |
| Emery Oleochemicals |
| IOI Oleochemical Group |
| BASF SE |
| Croda International Plc |
| P&G Chemicals |
| Oleon NV |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements spanning 3-5 years with price collars tied to palm oil futures lock in supply access for Indian food manufacturers and European pharmaceutical formulators while compressing spot market liquidity. These contract structures tether oleic acid pricing visibility to Malaysian and Indonesian feedstock futures, amplifying margin pressure on non-integrated processors when vegetable oil markets swing.
Pricing Analysis
After-sales service bundling for technical fractionation support drives lifetime value in pharmaceutical-grade supply relationships. Three-tier pricing structure across USP-certified, food-grade, and industrial-grade levels separates margin pools, with certification timelines stretching 18-24 months for the top tier. Cost compression in standard refined grades is intensifying because membrane filtration adopters are capturing energy efficiency gains of 15-25% versus thermal processors. Industrial surfactant producers in Indonesia exhibit highest price sensitivity, while parenteral drug developers accept premium positioning for excipient compliance.
Supply Chain Analysis
Strait of Malacca transit underwrites intercontinental oleic acid flows from Indonesian and Malaysian palm oil complexes to Rotterdam and Singapore hub terminals. Manufacturing concentrates in Indonesia, Malaysia, and India, with fractionation capacity expanding at Mundra and Dahej under PLI-linked incentives. Feedstock dependency rests on crude palm oil, sunflower oil, and high-oleic seed varieties. Single-source vulnerability runs through Southeast Asian palm oil estates exposed to El Niño weather patterns. Distribution runs through liquid bulk tanker shipments consolidated at Rotterdam for European cosmetic and pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oleic acid procurement platforms are shifting toward direct-to-formulator distribution models that disintermediate traditional merchant traders, creating interoperability demands between specialty chemical marketplaces and ECHA-compliant supplier dossier systems.
For Market Incumbents: Fortify membrane filtration technology licensing positions against enzymatic interesterification challengers piloting novel production architectures. Lock in backward integration into high-oleic seed crushing networks to neutralize palm oil price volatility threatening margin structures. Prioritize REACH registration maintenance exceeding one tonne thresholds as ECHA substance identity audits intensify among French and German cosmetic formulators. For New Entrants and Emerging Players: Lead with USP-grade certification investment targeting parenteral drug delivery and lipid nanoparticle excipient channels where 18-24 month compliance timelines freeze out smaller competitors. Penetrate Indian pharmaceutical sourcing under CDSCO alignment with ICH guidelines, where domestic fractionation capacity is scaling fastest. Deploy direct-to-formulator digital platforms disintermediating traditional merchant traders in mid-market cosmetic segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated oleochemical complexes with captive feedstock supply and long-term offtake contracts with multinational food manufacturers. Five-to-ten year viability favors processors with membrane filtration adoption and pharmaceutical-grade certification pipelines. Target acquisition archetypes: Southeast Asian fractionators with REACH-registered dossiers and Indian PLI-linked capacity expansions. Watch enzymatic interesterification cost curves as inflection indicators threatening conventional hydrolysis economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Oleic Seed Crushing | Cargill leverages upstream oilseed networks to neutralize palm oil volatility across continents. |
| Membrane Filtration Technology Licensing | Specialty producers in Germany and Netherlands pilot energy-efficient purification displacing thermal separation. |
| Long-term Supply Agreement Lock-ins | Indian food manufacturers secure 3-5 year contracts with price collars tied to palm oil futures. |
| USP-Grade Certification Investment | Croda and BASF compete on excipient compliance for parenteral drug delivery systems. |
| Direct-to-Formulator Distribution Platform | Rotterdam trading hubs disintermediate traditional merchant traders through specialty chemical marketplaces. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed agribusiness conglomerates, BIS quality standard notifications, and ECHA registration dossiers. Primary interviews engaged plant managers at Southeast Asian fractionation complexes, procurement leads at Indian food manufacturers, regulatory affairs directors navigating REACH compliance, and technical R&D heads piloting membrane filtration systems. Bottom-up capacity modeling triangulates against top-down demand aggregation across food, pharmaceutical, cosmetic, and lubricant end-use channels.
Segmentation dimensions modeled span product grade tier, application industry, physical form state, and geographic production hub across the analysis window. CAGRs derive from installed capacity expansion trajectories, feedstock cost curve projections, and purity premium compression dynamics in standard versus pharmaceutical grades. Forecast inputs incorporate PLI scheme disbursement timelines for Indian oleochemical capacity and EU Green Deal mandate implementation for renewable industrial fluids.
The analysis sits within stated boundaries; outcomes outside sustained palm oil price stability, REACH registration continuity, and membrane filtration scale-up would require recalibration. Forecasts reflect documented assumptions about feedstock availability, regulatory compliance timelines, and technology adoption curves. Practitioners should keep alternative scenarios live as enzymatic interesterification economics, Indian domestic production incentives, and European renewable content mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Bakery Release Agents Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
Japan Feed Additives Market