
 Allulose for Food Market | 2026-2036
Allulose for Food Market Size, Share, and Industry Trends Forecast 2026-2036
Allulose for Food Market Insights
Allulose is recalibrating sweetener economics in food manufacturing by offering near-identical functionality to sucrose at one-tenth the caloric load. Tate & Lyle leverages its global ingredient portfolio and enzyme-based production expertise to supply beverage and bakery customers across North America and Europe. CJ CheilJedang anchors Asian supply chains with fermentation-derived allulose capacity serving confectionery and dairy alternative producers. Matsutani Chemical Industry Co. Ltd. dominates crystalline and liquid formats through proprietary enzymatic conversion technology refined over decades of rare sugar research.
Allulose is a rare monosaccharide epimer of fructose, occurring naturally in small quantities in figs and raisins, with approximately 70% of sucrose sweetness and 0.2-0.4 kcal/g caloric content. Food manufacturers enzymatically convert fructose using D-psicose 3-epimerase to produce commercial-grade allulose for bulk sweetening applications. Powder and granulated formats lead current revenue pools due to their compatibility with existing bakery and confectionery processing equipment. Beverage applications represent the fastest-growing segment as formulators exploit allulose's clean taste profile and favorable solubility in carbonated and still drinks.
The FDA's GRAS notification framework and exempted sugar labeling treatment fundamentally shape United States market access and product formulation decisions. EFSA's ongoing novel food evaluations and Japan's FOSHU system create divergent compliance pathways that segment international expansion opportunities. Manufacturers must monitor pending determinations from Health Canada and China's NMPA, as favorable rulings in either jurisdiction would unlock substantial new volume corridors and reshape competitive priorities for existing suppliers.
Market Dynamics
Enzymatic conversion efficiency gains are compressing production costs for rare sugar epimers while FDA labeling exemptions pull beverage formulators toward bulk allulose adoption.
Growth Catalysts
- GRAS Notification Pathway:The FDA's streamlined self-affirmation process accelerates new entrant commercialization without pre-market approval delays.
- Carbonated Beverage Reformulation:Major soft drink bottlers replace high-fructose corn syrup with allulose to achieve clean-label positioning and caloric reduction targets.
- Enzyme Immobilization:Fixed-bed bioreactor systems boost D-psicose 3-epimerase reusability above 50 cycles, slashing unit conversion costs.
Market Restraints
- Fructose Feedstock Volatility:Corn syrup price swings in the US Midwest directly compress manufacturer margins during drought cycles.
- Asian Supply Concentration:CJ CheilJedang and Matsutani Chemical anchor crystalline allulose capacity in Korea and Japan, creating single-source vulnerability.
- Thermal Stability Ceiling:Allulose browning above 160°C limits high-temperature bakery applications where Maillard reactions are desired.
Strategic Opportunities
- Health Canada Novel Food Approval:Pending determinations would unlock Canadian dairy alternative and sports nutrition corridors currently blocked by regulatory uncertainty.
- Confectionery Sugar Reduction Mandates:UK soft drinks industry levy expansion into chocolate and candy creates forced substitution demand for rare sugar sweeteners.
- Fermentation-Enzyme Hybrid Platforms:Combining cell-free enzymatic conversion with engineered yeast strains promises 40% yield improvements over current batch processes.
Industry Challenges
- Rare Sugar Biochemist Scarcity:D-psicose 3-epimerase optimization and scale-up engineering require specialized talent pools concentrated in Japanese and Korean research institutes.
- Multi-Jurisdiction Labeling Harmonization:Divergent sugar declaration rules across FDA, EFSA, and China's NMPA force parallel SKU development and compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allulose for Food Market |
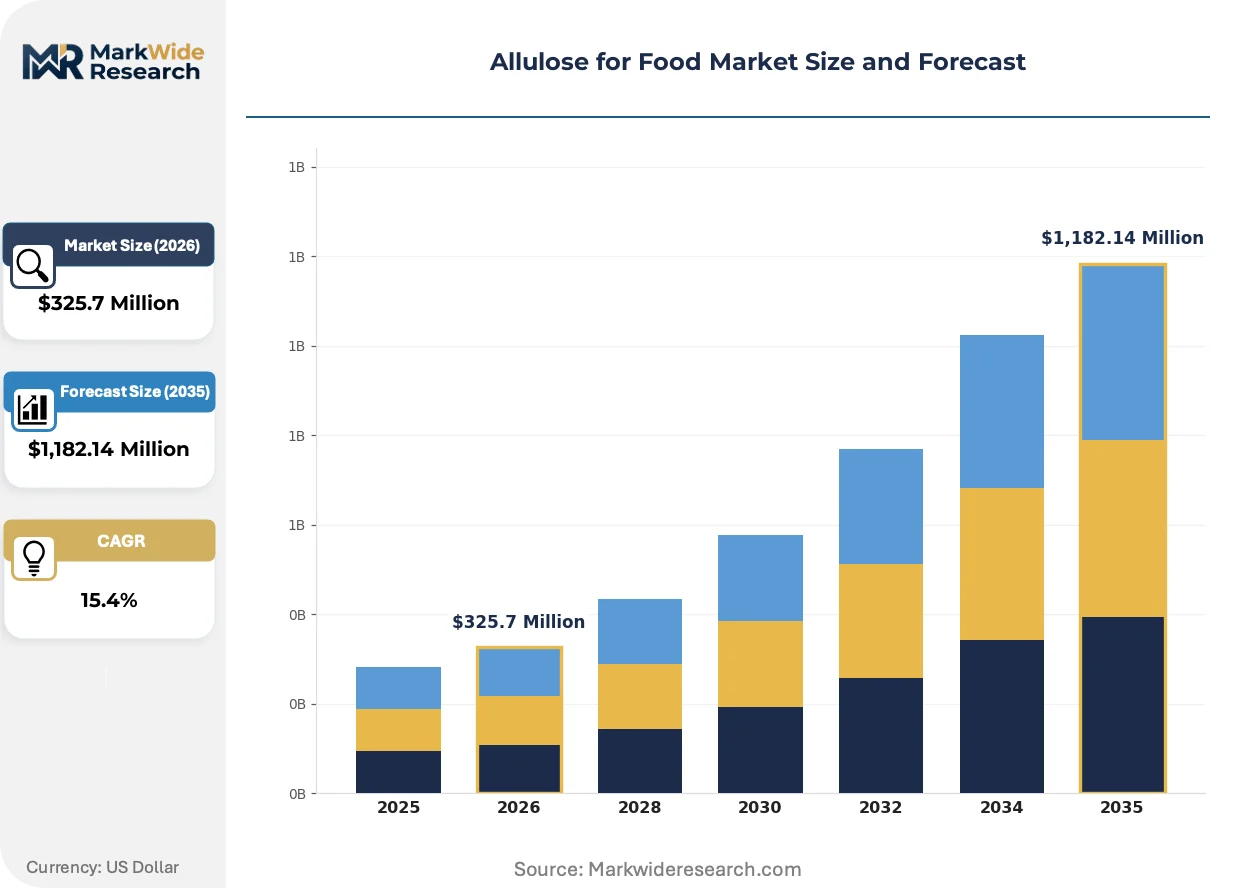
| Market Size in 2026 | $325.7 Million |
| Market Size in 2035 | $1,182.14 Million |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granulated, Syrup Application: Beverages, Bakery Products, Dairy Alternatives, Confectionery End User: Food Manufacturers, Restaurants, Retailers, Home Bakers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Tate & Lyle, CJ CheilJedang, Ingredion Incorporated, Matsutani Chemical Industry Co. Ltd., Cargill, Anderson Global Group, Apura Ingredients, Bonumose LLC, Samyang Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allulose for Food Market Trends and Innovations
Continuous processing architectures and regulatory arbitrage strategies are reconfiguring how allulose manufacturers compete on cost and market access.
Immobilized enzyme reactor technology is integrating fixed-bed systems with real-time pH monitoring to sustain D-psicose 3-epimerase activity across extended production runs. North American ingredient suppliers deploy these systems to displace batch fermentation and capture carbonated beverage volume. The shift is compressing capital intensity per kilogram while tightening quality consistency specifications.
EFSA's ongoing novel food safety evaluations are forcing European formulators to delay product launches pending Article 3 determinations. Manufacturers stockpile toxicology dossiers and exposure assessments to preempt regulatory objections. Dairy alternative producers in Germany and France face the tightest compliance timelines as EFSA prioritizes high-volume sweetener categories.
Clean-label procurement mandates from US retail grocery chains are displacing traditional sweetener RFP processes with sustainability and transparency scorecards. Category managers at conventional supermarkets now require enzymatic conversion method disclosure and carbon footprint documentation. This behavioral pivot concentrates contract awards with suppliers possessing verified supply chain traceability systems.
Allulose for Food Market Segmentation
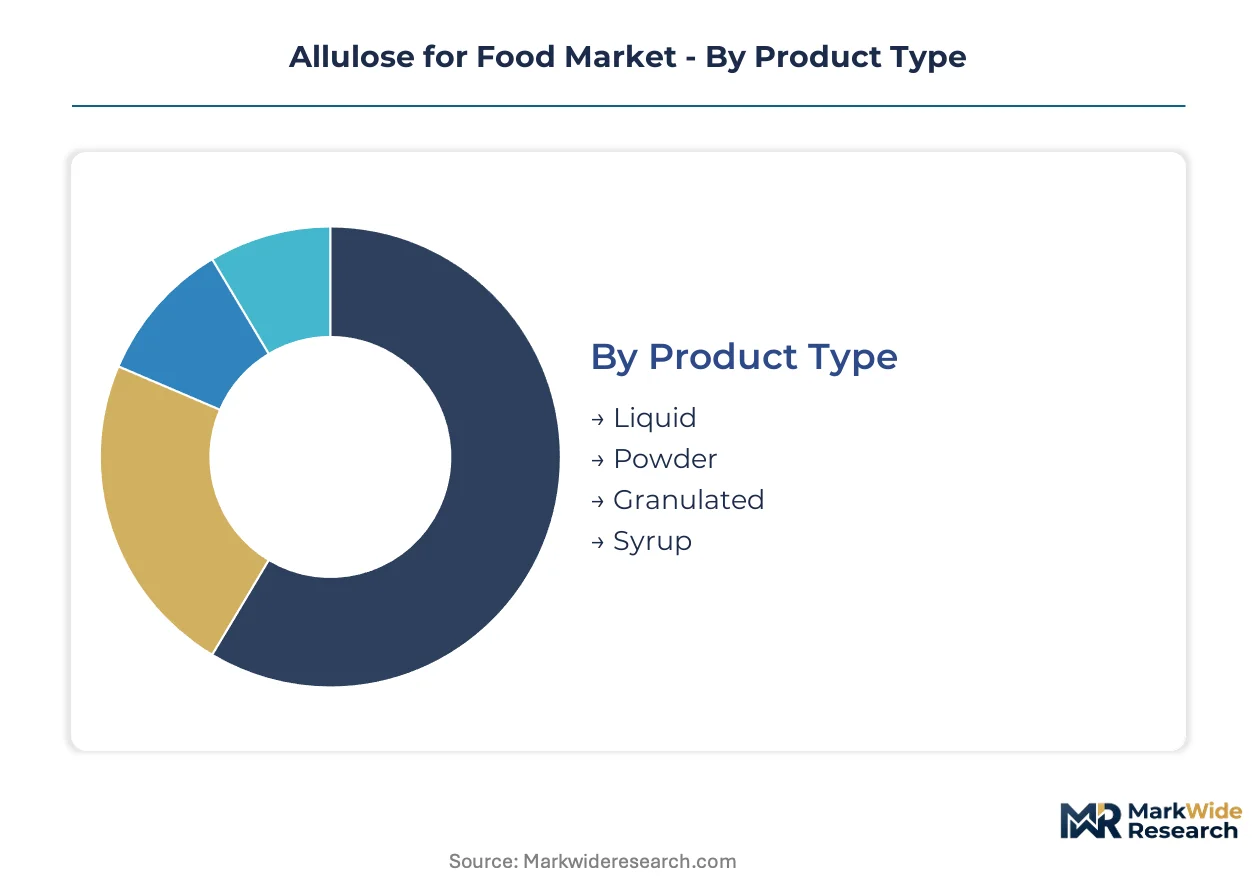
Allulose formulators face divergent equipment compatibility and solubility requirements across food manufacturing verticals. Segment-specific functionality determines procurement specifications and pricing tiers in this rare sugar market.
Product Type:
Powder and granulated formats command volume premiums due to legacy equipment compatibility, while liquid and syrup variants capture reformulation flexibility in beverage applications.
- Powder:Fine-milled crystalline allulose with 200-mesh particle size distribution integrates seamlessly into dry-blend bakery premixes and confectionery coatings. US food manufacturers specify powder grades for high-throughput cookie and cracker lines where dust-free handling and uniform dissolution are critical. Powder's shelf stability and low water activity make it the default specification for national bakery chains reformulating reduced-sugar product lines.
- Liquid:Aqueous allulose solutions at 70-75% solids concentration enable direct pump injection into carbonated beverage bottling systems without pre-dissolution steps. Major soft drink bottlers in the United States specify liquid formats for high-speed reformulation of legacy high-fructose corn syrup recipes. The format eliminates crystallization risk in cold-fill operations and supports clean-label positioning through single-ingredient declarations.
- Granulated:Coarse crystalline particles with sucrose-mimetic flow properties suit tabletop sweetener packaging and small-batch bakery operations. Home baking segments and specialty coffee chains specify granulated grades for direct consumer substitution scenarios.
- Syrup:Viscous concentrated solutions at 50-60% solids target artisanal confectionery and ice cream applications requiring controlled freezing point depression. Small-scale dairy alternative producers specify syrup formats for frozen dessert texture modulation.
Today's leader: Powder. Tomorrow's challenger: Liquid.
Application:
Beverage formulators drive premium pricing through clean-label mandates, while bakery and confectionery segments anchor volume throughput with established processing protocols.
- Beverages:Carbonated soft drinks, flavored waters, and sports drinks exploit allulose's complete water solubility and absence of bitter aftertaste. US bottlers reformulating high-fructose corn syrup recipes specify allulose for caloric reduction targets without artificial sweetener stigma. The FDA's exempted sugar labeling treatment accelerates adoption in conventional supermarket channels where added sugar declarations influence purchase decisions.
- Bakery Products:Cookies, cakes, and pastries utilize allulose for Maillard browning control and moisture retention at reduced caloric density. Commercial bakeries specify powder grades for scaled production of reduced-sugar lines targeting diabetic and weight-management consumer segments. Thermal stability constraints above 160°C limit application in crusty bread varieties requiring aggressive oven spring.
- Dairy Alternatives:Plant-based milks, yogurts, and frozen desserts leverage allulose for freezing point depression and clean sweetness without fermentation interference. Oat milk and almond milk producers specify allulose to differentiate from stevia-sweetened competitors with lingering bitterness.
- Confectionery:Hard candies, gummies, and chocolate coatings employ allulose for non-cariogenic positioning and reduced glycemic impact. Sugar-free chocolate manufacturers specify crystalline grades for tempering compatibility and snap retention.
Beverage applications are climbing the fastest as major bottlers execute high-fructose corn syrup replacement programs.
End User:
Food manufacturers concentrate procurement scale through long-term supply agreements, while restaurants and home bakers fragment demand across specialty distribution channels.
- Food Manufacturers:National bakery, beverage, and dairy companies specify allulose through RFP processes requiring GRAS documentation and supply chain traceability. Clean-label mandates from US retail grocery chains drive consolidated procurement toward suppliers with verified enzymatic conversion methods and carbon footprint disclosures.
- Restaurants:Quick-service chains and coffee shop operators specify liquid allulose for fountain beverage systems and customizable sweetener stations. Regional chain expansion of reduced-sugar menu items creates spot demand through foodservice distributors.
- Retailers:Private-label grocery brands specify allulose for store-brand reduced-sugar product lines competing with national manufacturers. Category managers require sustainability scorecards and third-party certification for shelf placement.
- Home Bakers:Enthusiast consumers purchase granulated and powder formats through specialty baking retailers and direct-to-consumer channels. Recipe influencer endorsements drive seasonal demand spikes in ketogenic and low-carbohydrate baking communities.
Food manufacturers dominate contract value. Restaurants are gaining share fastest through fountain beverage reformulation.
Distribution Channel:
Wholesale and supermarket channels consolidate volume throughput, while online retail and specialty stores fragment access for niche specifications.
- Wholesale:Ingredient distributors supply bulk liquid and powder formats to food manufacturers through tanker truck and super sack logistics. US Midwest distribution hubs concentrate inventory to service corn belt production facilities with just-in-time delivery.
- Supermarkets:Mass-market retail chains stock granulated allulose in baking aisles alongside conventional sugar alternatives. Planogram placement adjacent to stevia and monk fruit drives impulse substitution trials.
- Online Retail:E-commerce platforms enable direct procurement of specialty formats and bulk quantities by small-scale food producers and enthusiast bakers. Subscription models for recurring granulated purchases build consumer loyalty in ketogenic diet segments.
- Specialty Stores:Natural product retailers and baking supply boutiques curate premium-priced allulose SKUs targeting clean-label and allergen-free positioning. Staff expertise drives conversion among consumers navigating sweetener alternatives.
Wholesale commands volume leadership. Online retail shows steepest expansion trajectory as direct-to-producer procurement bypasses traditional distribution markups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US corn belt anchors commercial allulose production through integrated starch processing and enzymatic conversion infrastructure. Regulatory differentiation across FDA, EFSA, and Asian novel food frameworks segments market access and investment priorities. Manufacturing clusters concentrate near fructose feedstock supply and beverage formulation centers.
United States
Carbonated beverage reformulation and clean-label procurement mandates from retail grocery chains drive demand concentration. FDA GRAS notification pathways and exempted sugar labeling treatment accelerate new product launches. Midwest production corridors in Iowa and Illinois integrate corn wet milling with enzymatic rare sugar conversion for just-in-time supply to bottling facilities.
Japan
FOSHU functional food certification and decades of rare sugar research infrastructure sustain Matsutani Chemical's enzymatic production dominance. The Ministry of Health, Labour and Welfare maintains strict novel food safety evaluations that limit import competition. Kansai industrial clusters around Osaka prefecture concentrate crystalline allulose capacity serving domestic confectionery and pharmaceutical applications.
South Korea
CJ CheilJedang anchors Asian supply chains through fermentation-derived allulose capacity targeting dairy alternative and sports nutrition exports. The Ministry of Food and Drug Safety enforces novel food registration requirements that favor domestic incumbents with established toxicology dossiers. Seoul metropolitan area R&D centers specialize in D-psicose 3-epimerase optimization and bioreactor scale-up engineering.
Germany
EFSA pending novel food determinations delay commercial launches in dairy alternative and bakery segments. The Federal Office of Consumer Protection and Food Safety coordinates exposure assessments with EFSA Article 3 safety evaluations. Bavarian food technology clusters around Munich stockpile compliance documentation for post-approval rapid market entry.
Canada
Health Canada novel food approval pending status blocks allulose incorporation in sports nutrition and plant-based dairy products. The Food Directorate maintains pre-market notification requirements for rare sugar sweeteners without GRAS-equivalent pathways. Ontario food manufacturing corridors near Toronto await regulatory clarity to execute reformulation programs for US-export-aligned product lines.
Allulose for Food Market Competitive Landscape
Capacity expansion dominates the current competitive landscape as established suppliers scale enzymatic conversion infrastructure to capture beverage reformulation volume. The market structure concentrates around three strategic archetypes: integrated starch processors with backward feedstock control, specialized rare sugar enzymatic converters with proprietary bioreactor technology, and diversified ingredient distributors with formulation technical service capabilities. M&A activity and technology licensing agreements represent the primary competitive moves, with acquisition targets clustering on enzyme engineering startups and regional distribution networks.
Within the integrated processor tier, Tate & Lyle and Cargill exemplify scale-driven positions leveraging corn wet milling infrastructure and beverage industry customer relationships. Among specialized enzymatic converters, Matsutani Chemical Industry Co. Ltd. and CJ CheilJedang occupy positions defined by decades of rare sugar research and proprietary D-psicose 3-epimerase production systems. These five entities collectively anchor supply-side concentration while Ingredion Incorporated represents the diversified distributor archetype with technical service capabilities spanning multiple sweetener categories.
| Leading Market Players |
|---|
| Tate & Lyle |
| CJ CheilJedang |
| Ingredion Incorporated |
| Matsutani Chemical Industry Co. Ltd. |
| Cargill |
| Anderson Global Group |
| Apura Ingredients |
| Bonumose LLC |
| Samyang Corporation |
| Others |
Pricing and Supply Chain Analysis
Enzyme immobilization technology is compressing unit conversion costs while simultaneously concentrating production capacity among suppliers with proprietary fixed-bed bioreactor systems. This dual effect reshapes pricing power toward integrated manufacturers with backward feedstock control and advanced enzymatic engineering capabilities.
Pricing Analysis
Fructose feedstock pass-through from US Midwest corn belt pricing directly compresses manufacturer margins during drought cycles. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade specifications reflects certification investment and purity thresholds. Pricing pressure stems from Asian supply concentration as CJ CheilJedang and Matsutani Chemical anchor crystalline capacity. Food manufacturers exhibit highest price sensitivity due to thin reformulation margins, while pharmaceutical applications tolerate premium tiers for rare sugar API applications.
Supply Chain Analysis
Japan's FOSHU functional food certification and South Korea's novel food registration requirements create de facto local-content sourcing mandates favoring domestic enzymatic converters. Commercial allulose production draws from fructose syrup, immobilized D-psicose 3-epimerase, and crystallization equipment concentrated in Japan, South Korea, and the United States. Single-source vulnerability persists around Matsutani Chemical's proprietary enzymatic conversion technology refined over decades. Distribution runs through wholesale ingredient distributors supplying bulk liquid and powder formats to food manufacturers via tanker truck and super sack logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The allulose market functions as a regulatory compounder where FDA's 2019 exempted sugar labeling decision created immediate demand acceleration for beverage reformulation programs.
For Market Incumbents: Extend capacity footprints near US corn belt wet milling infrastructure to capture carbonated beverage volume migration from high-fructose corn syrup. Secure long-term enzyme supply agreements with D-psicose 3-epimerase specialists to defend against emerging fermentation-enzyme hybrid platform entrants. Backward integration into fructose feedstock production mitigates margin compression from Midwest corn price volatility.
For New Entrants and Emerging Players: Continuous processing architecture offers a technology-first wedge against incumbent batch fermentation economics. Target Health Canada novel food approval corridors currently blocked by regulatory uncertainty, positioning for rapid market entry upon favorable determination. Pursue white-label supply partnerships with dairy alternative producers seeking clean-label differentiation from stevia-bitter competitors.
For Investors and Strategic Acquirers: Roll-up economics work for regional enzyme engineering specialists because rare sugar biochemist talent pools concentrate in Japanese and Korean research institutes with limited mobility. Five-to-ten year viability hinges on multi-jurisdiction labeling harmonization reducing parallel SKU development burdens. Watch EFSA Article 3 novel food determinations as the critical inflection signal for European volume corridor unlock.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Fixed-bed bioreactor deployment near Iowa corn wet milling captures beverage reformulation volume. |
| Backward Integration | In-house fructose syrup production insulates margins from Midwest drought-driven feedstock volatility. |
| Regulatory Approval Pathway | Health Canada novel food dossier preparation unlocks Canadian dairy alternative and sports nutrition corridors. |
| Technology Licensing | D-psicose 3-epimerase immobilization patents transfer to North American producers displacing batch processes. |
| Joint Venture | Fermentation-enzyme hybrid platform partnerships combine cell-free conversion with engineered yeast strain yields. |
Research Methodology
Multiple input streams — executive interviews with rare sugar biochemists, procurement leads at beverage bottlers, and regulatory affairs directors — were reconciled against FDA GRAS notification databases, EFSA novel food submission records, and customs trade flow data. Primary fieldwork with enzymatic conversion plant managers and technical R&D directors at starch processing facilities informed production cost structures. Secondary validation drew from SEC 10-K filings of integrated ingredient suppliers, USDA corn market reports, and Japanese Ministry of Health FOSHU certification registries. Bottom-up volume modeling triangulated against top-down addressable sweetener market sizing.
Historical capacity expansion patterns cross-referenced against expert panel input on enzyme immobilization adoption timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product format, application vertical, end-user procurement scale, and regional regulatory cluster. CAGRs derived from installed capacity trajectories, beverage reformulation program announcements, and novel food approval probability-weighted scenarios. Forecast inputs incorporated fructose feedstock price elasticity, carbonated beverage volume decline rates, and clean-label procurement mandate penetration curves.
The model holds under stable FDA labeling treatment and gradual EFSA approval timelines; deviation in Health Canada or NMPA regulatory determinations would shift volume corridor priorities. Forecasts reflect assumptions regarding enzyme conversion efficiency gains and corn belt climate stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
Starch-Based Texturizing Agents Market
Food Additives and Ingredients
Global Food Texturants Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
Ellagic Acid Market