
 Beta Agonist Feed Additive Market | 2026-2036
Beta Agonist Feed Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Beta Agonist Feed Additive Market Outlook
Commercial cattle feedlots are reorganizing procurement priorities toward beta agonist premix suppliers as packer grids reward carcass yield premiums. Elanco Animal Health leverages its veterinary channel infrastructure to sustain ractopamine distribution across North American feedyards. ADM Animal Nutrition anchors its position through captive formulation capacity and direct mill relationships. Zoetis competes on regulatory dossier breadth, maintaining approved indications across multiple species and geographies.
Beta agonist feed additives comprise phenethanolamine derivatives, primarily ractopamine hydrochloride and salbutamol sulfate, formulated at concentrations between 5 and 30 grams per ton of complete feed to modulate beta-adrenergic receptors and redirect metabolic energy from fat deposition toward skeletal muscle accretion in finishing livestock. Ractopamine dominates product type volumes due to its established approval profile in major meat-exporting nations, while salbutamol retains niche positions in geographies with distinct regulatory tolerances. Poultry and swine applications generate the bulk of current demand, though ruminant formulations command premium pricing tied to stricter residue withdrawal protocols and export certification requirements.
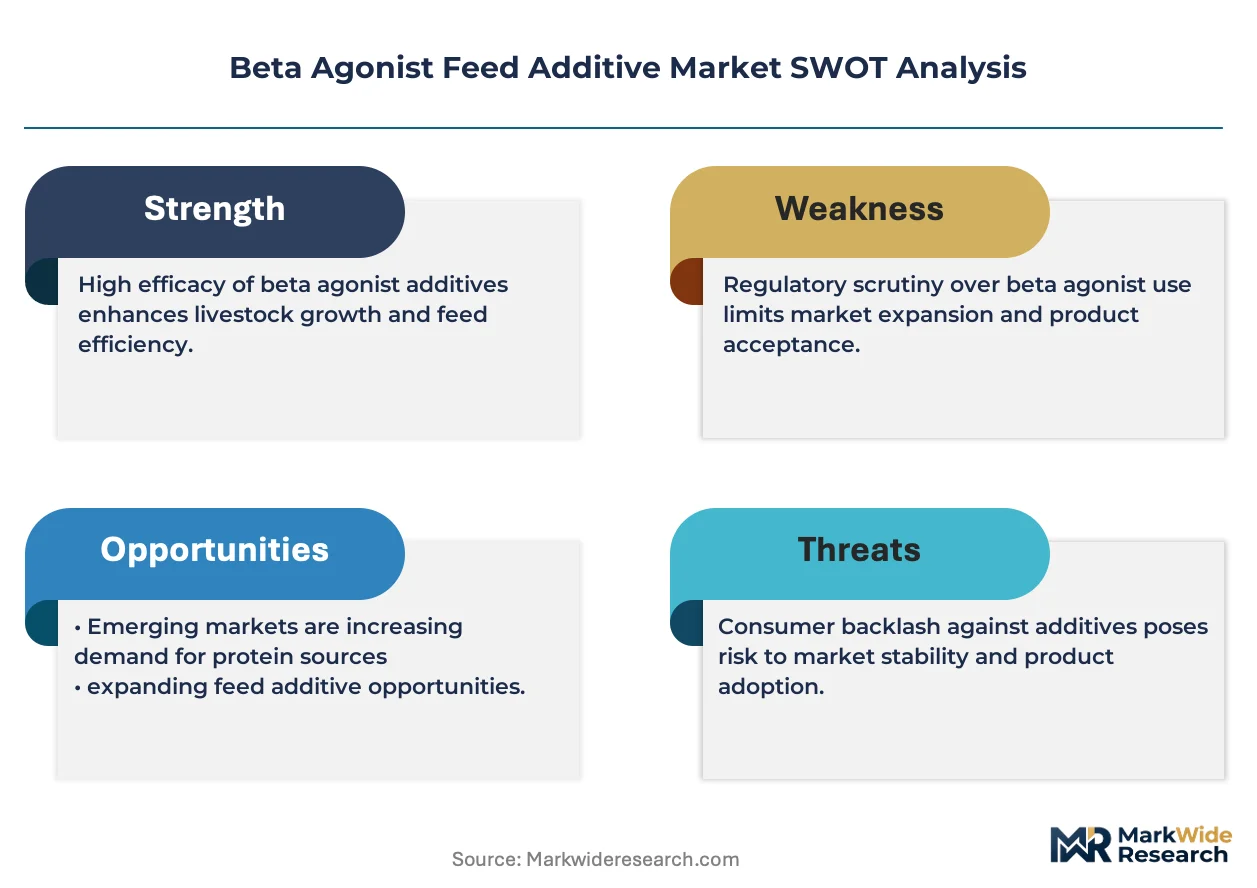
The FDA's Center for Veterinary Medicine oversees beta agonist approval and residue monitoring in the United States, while Brazil's ANVISA enforces distinct maximum residue limits that shape formulation standards for export-bound production. China's NMPA and Ministry of Agriculture maintain a separate regulatory trajectory with conditional approvals that constrain market access for non-domestic suppliers. Stakeholders must track evolving maximum residue limit harmonization efforts between Codex Alimentarius standards and national veterinary drug regulators to anticipate shifts in approved market access and competitive positioning.
Market Dynamics
Feed conversion economics in cattle finishing operations are tightening procurement criteria around residue-compliant beta agonist formulations, forcing suppliers to synchronize formulation standards with divergent national maximum residue limits.
Growth Catalysts
- Feedlot Yield Premiums:Packer grid structures in the United States reward carcass weight and lean yield, pulling ractopamine premix demand through veterinary distribution channels.
- Export Certification Alignment:Brazil's ANVISA protocols for residue monitoring enable beef processors to maintain access to markets with approved beta agonist tolerances.
- Metabolic Modulation Science:Beta-adrenergic receptor targeting redirects energy from adipose deposition toward skeletal muscle accretion, delivering measurable feed efficiency gains in finishing phases.
Market Restraints
- Regulatory Asymmetry:The European Union's EFSA prohibition blocks market access across twenty-seven member states, fragmenting addressable geography.
- Active Pharmaceutical Ingredient Concentration:Synthesis of phenethanolamine derivatives depends on specialized chemical manufacturing clusters in China, creating supply vulnerability.
- Withdrawal Protocol Complexity:Stricter residue clearance timelines for ruminant applications extend production cycle planning and elevate compliance costs.
Strategic Opportunities
- Species Portfolio Expansion:Poultry and aquaculture applications remain underdeveloped relative to swine and cattle, offering formulation diversification paths.
- Codex Harmonization:Alignment between Codex Alimentarius standards and national regulators could unlock previously restricted trade corridors.
- Precision Dosing Platforms:Integration of real-time growth monitoring with automated feed delivery enables individualized beta agonist administration protocols.
Industry Challenges
- Veterinary Pharmacology Expertise Gap:Feedlot operations lack in-house specialists capable of navigating species-specific withdrawal schedules and residue testing protocols.
- Multi-Jurisdiction Compliance Architecture:Suppliers must maintain parallel regulatory dossiers for FDA, ANVISA, and NMPA approval pathways simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beta Agonist Feed Additive Market |
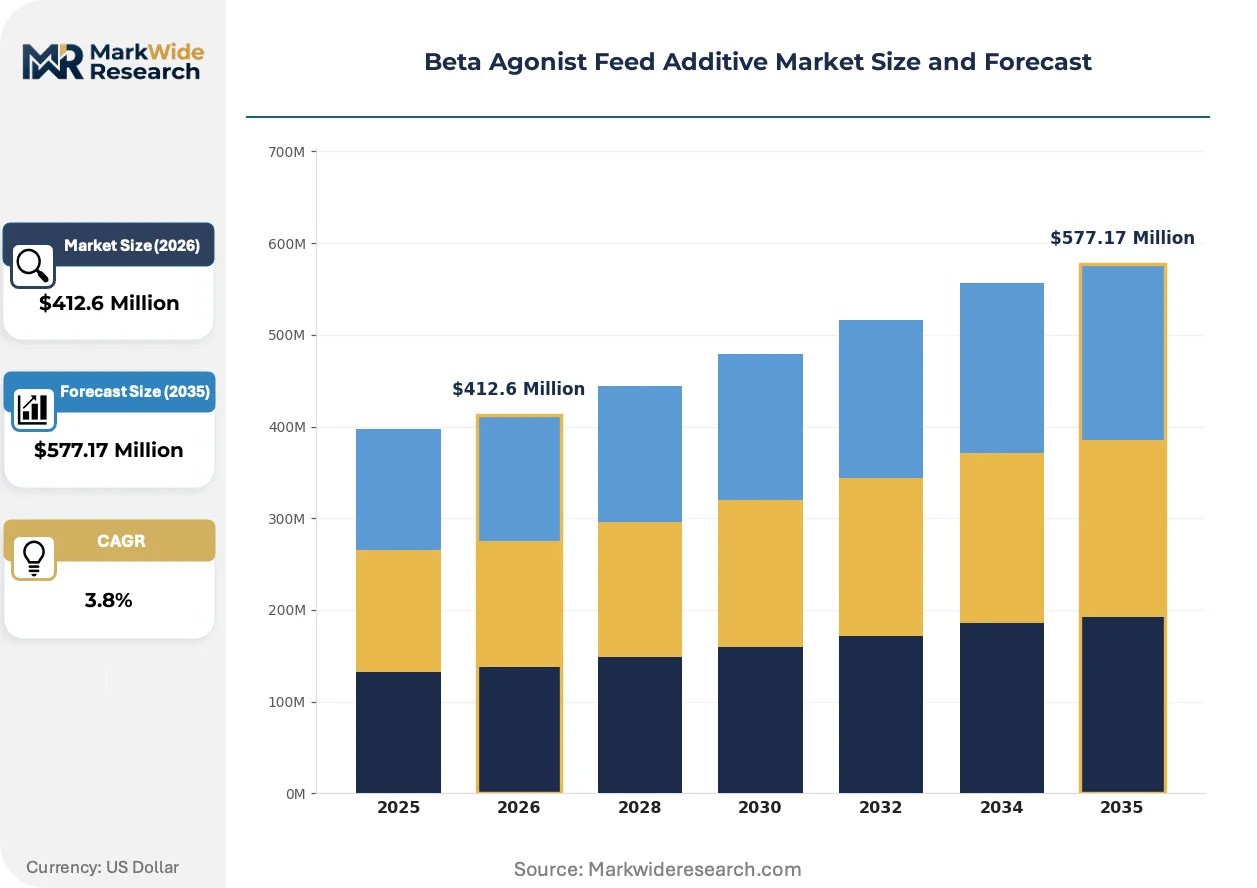
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $577.17 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ractopamine, Salbutamol, Clenbuterol, Others Application: Poultry, Swine, Ruminants, Aquaculture Formulation: Granules, Powder, Liquid, Premix Distribution Channel: Online Retail, Distributors, Direct Sales, Others |
| Companies Covered | Quality Liquid Feeds, ADM Animal Nutrition, Elanco Animal Health, Boehringer Ingelheim, Nutreco, Zoetis, Heer Pharma Private Limited, Alltech, Merck Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beta Agonist Feed Additive Market Strategic Shifts
Formulation science and residue detection capabilities are advancing faster than regulatory harmonization, creating competitive advantage for suppliers who can bridge this gap with validated analytical methods.
Microencapsulation technology for beta agonist delivery is supplanting conventional dry premix formats in high-value cattle finishing operations. Large integrated feedlots in the United States are adopting these systems to achieve more uniform active ingredient distribution and reduce dust exposure during mixing. This shift is compressing margins for commodity premix suppliers while rewarding captive formulation capabilities.
EFSA's continued prohibition of beta agonists in livestock production under Commission Regulation standards maintains a hard regulatory boundary that shapes European protein import sourcing. Meat processors in Germany and France have built supply chains around residue-free certification programs, diverting trade flows toward South American suppliers with ANVISA-approved protocols. This regulatory friction is accelerating investment in alternative growth promotion technologies within the European market.
Direct mill relationships are displacing traditional distributor intermediaries in North American feed additive procurement. Major feed manufacturers in Iowa, Texas, and Kansas are negotiating volume commitments directly with beta agonist suppliers, extracting price concessions and technical service integration. This channel compression is most visible among commercial cattle feedlots with annual capacities exceeding fifty thousand head.
Beta Agonist Feed Additive Market Segmentation
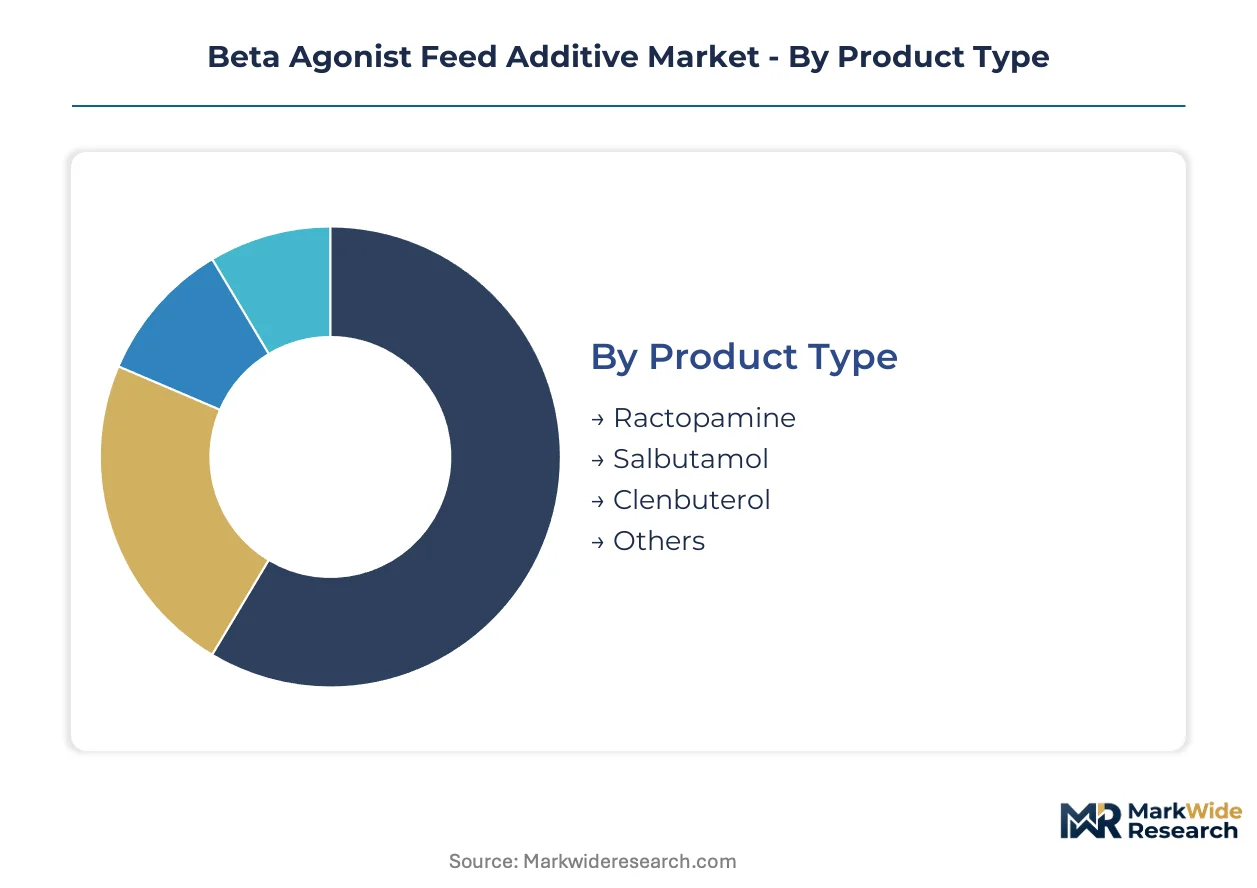
Segmentation in the beta agonist feed additive market reveals where substitution pressures from alternative growth promoters concentrate most intensely. Understanding these fracture lines enables suppliers to defend formulation portfolios and identify expansion corridors.
Product Type:
Ractopamine faces the strongest substitution threat from novel beta agonist candidates and non-pharmacological growth technologies, particularly in jurisdictions tightening residue standards.
- Ractopamine:Phenethanolamine derivative formulated as hydrochloride salt at concentrations between 5 and 30 grams per ton. Demand concentrates in Brazilian feedlots supplying export markets with Codex-aligned residue tolerances, driven by packer grid premiums for lean yield. Ractopamine retains volume leadership; Clenbuterol holds the steepest expansion curve in geographies with permissive regulatory thresholds.
- Salbutamol:Short-acting beta-2 adrenergic agonist with distinct receptor binding kinetics and shorter withdrawal windows. Procurement is intensifying in Middle Eastern poultry operations seeking alternatives to ractopamine supply constraints.
- Clenbuterol:Long-acting sympathomimetic amine with potent lipolytic and anabolic properties, restricted to specific veterinary protocols in select markets.
- Others:Emerging phenethanolamine analogs and combination formulations under regulatory review in multiple jurisdictions.
Cost tier stratification separates ractopamine commodity formulations from premium-priced niche alternatives with specialized residue profiles.
Application:
Volume concentration varies sharply across species, with poultry and swine generating baseline demand while ruminant applications command premium positioning tied to export certification complexity.
- Poultry:Broiler operations deploy beta agonists during final growth phases to enhance breast muscle yield and reduce abdominal fat deposition. Integration with automated feeding systems is accelerating in vertically integrated US processors.
- Swine:Finishing barns represent the largest addressable volume segment, with ractopamine premixes standard in North American operations pursuing feed conversion ratios below 2.8:1.
- Ruminants:Cattle feedlot applications require extended withdrawal protocols and residue documentation chains that elevate supplier technical service requirements.
- Aquaculture:Species-specific receptor pharmacology limits current adoption, though research programs in Southeast Asian shrimp farming are evaluating beta agonist effects on fillet yield.
Swine applications dominate current procurement volumes; aquaculture represents the most underdeveloped expansion frontier.
Formulation:
Microencapsulation advances are compressing margins for conventional dry formats while rewarding suppliers with captive delivery technology capabilities.
- Granules:Extruded carrier systems with controlled particle size distribution for uniform mixing in high-volume feed mills.
- Powder:Conventional crystalline formulations facing displacement by engineered particle technologies that reduce dust exposure and improve flow characteristics.
- Liquid:Aqueous suspensions for integration into automated liquid feed supplementation systems at large integrated operations.
- Premix:Concentrated blends requiring dilution prior to final feed manufacturing, standard in distributor-mediated procurement channels.
Premix formats retain distribution channel dominance; microencapsulated granules are gaining share fastest in direct mill relationships.
Distribution Channel:
Channel compression is eliminating traditional intermediaries as large feed manufacturers consolidate procurement through direct supplier negotiations.
- Direct Sales:Volume commitments between beta agonist suppliers and major feed manufacturers in Iowa, Texas, and Kansas are extracting price concessions and technical service integration.
- Distributors:Veterinary and feed additive distributors retain relevance in mid-scale operations lacking in-house formulation expertise.
- Online Retail:Digital procurement platforms are emerging for standardized premix products in regions with established regulatory frameworks.
- Others:Cooperative purchasing arrangements and integrated packer-supplier agreements in concentrated feeding geographies.
Direct sales channels are displacing distributor intermediaries most rapidly in North American cattle feedlots exceeding fifty thousand head capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos grain terminal underwrites Brazil's dominance in beta agonist feed additive distribution, channeling premix formulations to export-oriented beef processors across South America and beyond.
United States
Commercial feedlots in the Texas Panhandle and Kansas corridor drive ractopamine premix procurement through veterinary distribution networks. The FDA Center for Veterinary Medicine enforces residue monitoring protocols that shape formulation standards for domestic and export-bound production. Large integrated operations in Iowa and Nebraska negotiate direct supplier agreements, compressing traditional distributor channels.
Brazil
Export certification requirements from ANVISA-aligned processors concentrate demand for residue-compliant beta agonist protocols in São Paulo and Mato Grosso feedlot clusters. The country's national pharmaceutical regulator maintains distinct maximum residue limits that exceed Codex Alimentarius baselines in certain categories. Beef processors in the Central-West region invest in parallel testing infrastructure to maintain access to multiple regulatory jurisdictions.
China
Domestic ractopamine synthesis capacity in Jiangsu and Shandong provinces supplies captive feed additive requirements for the country's pork production sector. The NMPA and Ministry of Agriculture maintain conditional approval frameworks that constrain market access for non-domestic suppliers. Research institutes in Beijing evaluate novel phenethanolamine analogs for species-specific applications beyond current regulatory portfolios.
Canada
Prairie cattle feeding operations in Alberta and Saskatchewan align procurement with US packer grid structures, creating integrated North American demand patterns. Health Canada and PMRA coordinate residue standards with FDA protocols to enable seamless cross-border protein trade. Feed manufacturers in Manitoba consolidate procurement through direct mill relationships with major premix suppliers.
Australia
Beef export certification to beta agonist-tolerant markets concentrates formulation demand in Queensland and New South Wales feedlot regions. The TGA maintains veterinary drug scheduling that permits ractopamine use under prescribed protocols for specific export destinations. Meat processors in Brisbane and Sydney operate dual supply chains segregating production lots by destination market residue requirements.
Beta Agonist Feed Additive Market Competitive Environment
Concentration sits with diversified animal health conglomerates possessing captive formulation infrastructure and multi-jurisdiction regulatory dossiers. Three to five integrated suppliers control the majority of ractopamine premix volumes through direct mill relationships, while mid-scale distributors retain relevance in fragmented regional markets. Strategic archetypes include veterinary channel specialists leveraging technical service capabilities, nutrition companies with backward integration into active ingredient sourcing, and pharmaceutical manufacturers with species-portfolio breadth. Competitive moves center on regulatory dossier expansion into underpenetrated geographies and microencapsulation technology licensing to capture premium formulation segments.
Among US-based animal health specialists, Elanco Animal Health and Zoetis occupy positions anchored by veterinary distribution infrastructure and multi-species approval portfolios. ADM Animal Nutrition represents the nutrition-integrated archetype with captive formulation capacity and direct feed mill relationships. Boehringer Ingelheim and Merck Animal Health exemplify pharmaceutical-origin competitors with research-intensive positioning and regulatory expertise spanning human and animal health domains.
| Leading Market Players |
|---|
| Quality Liquid Feeds |
| ADM Animal Nutrition |
| Elanco Animal Health |
| Boehringer Ingelheim |
| Nutreco |
| Zoetis |
| Heer Pharma Private Limited |
| Alltech |
| Merck Animal Health |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Brazilian beef processors and ractopamine premix suppliers lock in both supply access and price visibility across volatile feed ingredient markets. These arrangements concentrate procurement leverage among integrated feedlots with annual capacities exceeding fifty thousand head, compressing margins for spot-market participants.
Pricing Analysis
Volume-discount tiering structures separate commodity ractopamine formulations from microencapsulated premium grades. Pricing stratifies across certification tiers, with Codex-aligned residue protocols commanding fifteen to twenty percent premiums over domestic-only formulations. Cost compression in standard premix tiers stems from direct mill relationships displacing distributor intermediaries. Mid-scale feedlot operations lacking captive formulation expertise exhibit highest price sensitivity, while integrated packer-processor complexes prioritize residue compliance over unit cost.
Supply Chain Analysis
Specialized chemical manufacturing clusters in Jiangsu and Shandong provinces constitute the critical chokepoint for phenethanolamine derivative synthesis. Active pharmaceutical ingredient production draws from para-hydroxyacetophenone feedstocks and specialized catalytic hydrogenation capacity concentrated in China. Single-source vulnerability in intermediate chemical supply elevates risk exposure for non-Chinese formulators. Distribution runs through veterinary channel networks in North America and direct mill relationships in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beta agonist feed additive market functions as a defensive-moat industry where regulatory entrenchment creates durable competitive advantages. Multi-jurisdiction approval portfolios require years of residue monitoring data and veterinary pharmacology investment, raising effective barriers to replication.
For Market Incumbents: Fortify position through backward integration into microencapsulation technology and captive active ingredient sourcing. Elanco Animal Health and Zoetis should expand regulatory dossier coverage into underpenetrated poultry and aquaculture segments before novel growth promoters gain traction. Channel control represents the priority lever as direct mill relationships displace veterinary distributors. For New Entrants and Emerging Players: ANVISA fast-track certification for export-bound Brazilian beef processors offers the most penetrable entry corridor. Target mid-scale feedlots in Mato Grosso and São Paulo lacking in-house residue testing infrastructure. White-space opportunities concentrate in precision dosing platforms and automated feed delivery integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with captive formulation capacity and multi-species approval portfolios. Acquisition targets should demonstrate established FDA, ANVISA, or NMPA dossiers rather than pipeline-stage candidates. Watch for Codex Alimentarius maximum residue limit harmonization as the signal for geographic expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | Multi-jurisdiction approvals unlock Brazilian and Australian export corridors for ruminant formulations. |
| Microencapsulation Technology Licensing | Premium delivery systems capture direct mill relationships from commodity premix suppliers. |
| Species Portfolio Diversification | Poultry and aquaculture applications reduce dependence on cattle feedlot procurement cycles. |
| Precision Dosing Platform Development | Real-time growth monitoring integration enables individualized beta agonist administration protocols. |
| Residue Testing Infrastructure Partnership | ANVISA-aligned laboratory networks secure export certification for Brazilian beef processors. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented approval pathways and residue monitoring protocols. Conversations with veterinary pharmacologists, feedlot operations managers, regulatory affairs directors at animal health companies, and ANVISA compliance officers informed supply chain and pricing dynamics. Secondary sources include FDA Center for Veterinary Medicine approval databases, ANVISA maximum residue limit determinations, Codex Alimentarius standards, and customs trade data for phenethanolamine derivative flows. Bottom-up segmentation analysis triangulates against top-down market sizing from feed conversion economics and packer grid structures.
Sensitivity analysis around regulatory approval timelines and residue detection technology adoption shapes the forecast confidence intervals. The analytical framework models volume and value across product type, application species, formulation technology, and distribution channel dimensions throughout the projection horizon. CAGRs derive from feedlot capacity expansion rates, export certification requirements, and metabolic modulation science adoption curves. Species-specific withdrawal protocols and maximum residue limit harmonization efforts constitute key forecast inputs.
Underlying assumptions cover stable FDA and ANVISA regulatory frameworks, with deviation risk concentrated in EFSA prohibition spillover effects and Chinese NMPA conditional approval restrictions. Practitioners should keep alternative scenarios live as Codex Alimentarius harmonization negotiations and novel growth promoter competitive threats evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Food Starch Market