
 Fermented Chymosin Market | 2026-2036
Fermented Chymosin Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Chymosin Market Foresight
Modular enzyme bundling is shifting how food manufacturers procure coagulants, with buyers now separating fermentation-grade chymosin from adjunct cultures rather than purchasing integrated starter systems. Novozymes leverages its Danish biotech infrastructure to dominate recombinant strain development. Chr. Hansen sustains deep R&D pipelines in dairy-specific enzyme cocktails. Kerry Group anchors European supply through its enzyme distribution networks.
Fermented chymosin denotes a recombinant enzyme produced via microbial fermentation of genetically modified fungi or bacteria, typically yielding 90-98% pure chymosin protein that cleaves kappa-casein at the Phe105-Met106 bond to initiate milk coagulation. Liquid formulations command the largest volume share in industrial dairy production due to dosing precision in continuous processing lines, while powder and granulated formats are gaining traction among smaller cheese makers seeking extended shelf stability and freight economy. Organic-certified chymosin carries premium positioning within the formulation dimension as EU farm-to-fork traceability rules tighten input documentation requirements.
EMA food enzyme safety evaluations and EFSA novel food opinions shape market access timelines for new fermentation-derived coagulants entering European dairy supply chains. FDA GRAS self-affirmation pathways govern US market entry, though FSMA preventive controls impose fermentation facility audit burdens. Stakeholders must monitor evolving genome-edited organism classification debates across EU and US jurisdictions, as regulatory determinations on whether precision-fermented strains constitute GMOs will reshape strain development investment priorities and geographic manufacturing placement decisions.
Market Dynamics
EU Green Deal farm-to-fork traceability mandates are compressing documentation windows for organic-certified enzyme inputs, forcing specialty cheese producers to requalify suppliers ahead of tightening 2025-2026 compliance deadlines.
Growth Catalysts
- EU Green Deal farm-to-fork requirements:Tightening traceability rules across Germany, France, and Italy are accelerating substitution of animal-derived rennet with documented fermentation-grade alternatives.
- Artisanal dairy cluster expansion:Traditional cheese producers in the Netherlands and Denmark are retrofitting small-batch facilities to accept precision-dosed liquid chymosin for heritage recipe consistency.
- Continuous processing line adoption:Industrial dairy operators are installing automated dosing systems that favor liquid chymosin formulations over powder reconstitution steps.
Market Restraints
- Organic certification input cost volatility:Non-GMO substrate sourcing for certified fermentation runs carries 15-40% feedstock premiums versus conventional glucose streams.
- Strain development supply concentration:Recombinant fungal host platforms for high-yield chymosin expression remain concentrated among Danish and Dutch biotech infrastructure operators.
- Genome-edited organism classification uncertainty:Pending EFSA determinations on whether CRISPR-optimized fermentation strains trigger GMO labeling are freezing R&D investment timelines.
Strategic Opportunities
- Underpenetrated US artisanal segment:FDA GRAS self-affirmation pathways allow faster market entry for fermentation-derived coagulants targeting farmstead cheese makers in Wisconsin and Vermont.
- Precision fermentation technology convergence:Integration of AI-driven strain optimization with continuous bioreactor monitoring is compressing batch-to-batch purity variance below 2%.
- Direct-to-producer distribution channels:Specialty enzyme distributors are bypassing traditional dairy ingredient brokers to serve small-batch producers via e-commerce platforms with technical support bundling.
Industry Challenges
- Fermentation scale-up capex intensity:Commercial-grade bioreactor installation for chymosin-dedicated production lines requires 18-24 month facility qualification timelines.
- Cross-jurisdiction licensing complexity:Patent thickets surrounding recombinant chymosin expression systems in fungi versus bacteria hosts create royalty stacking for new market entrants.
- Organic certification audit burden:EU-accredited bodies are extending documentation review cycles for fermentation-derived inputs to 6-9 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Chymosin Market |
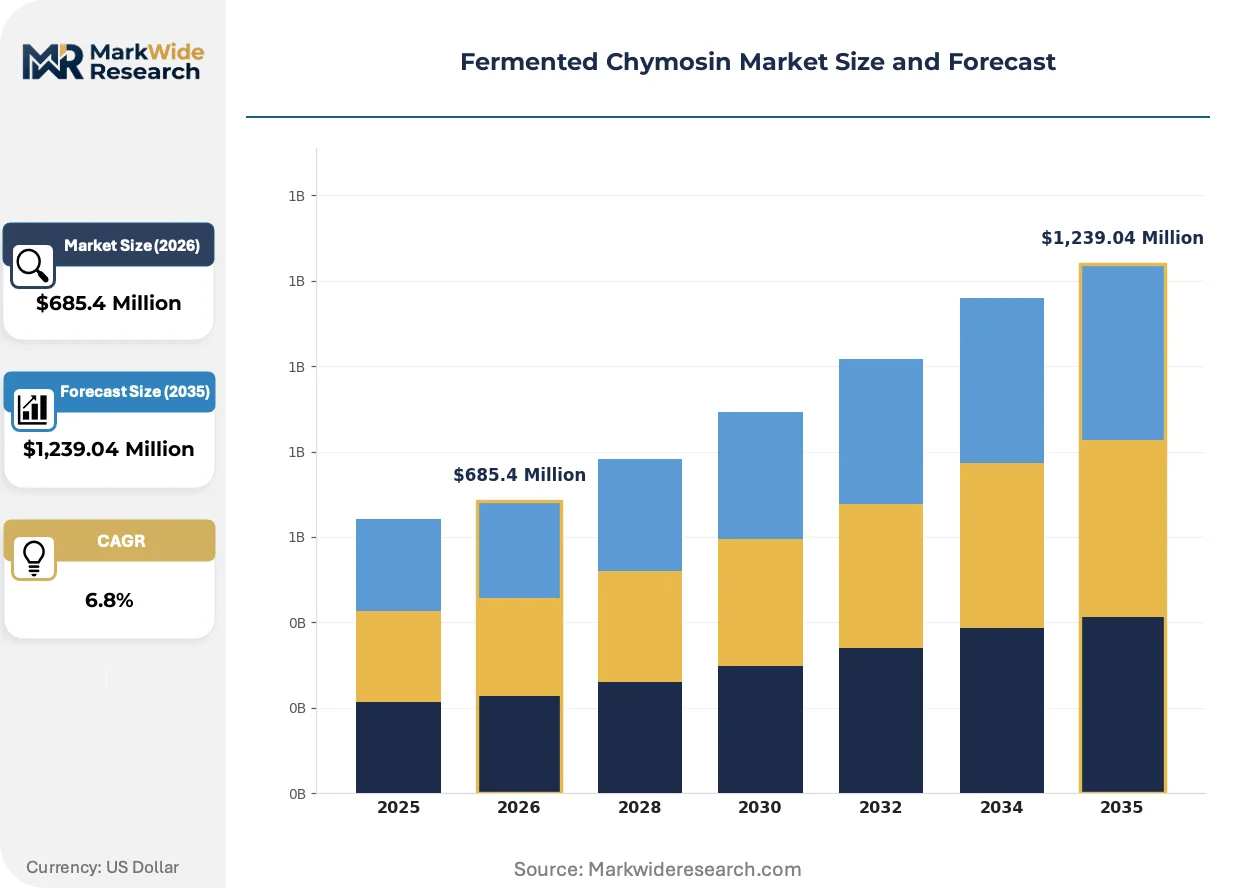
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Powder, Granulated Application: Dairy Production, Cheese Making, Meat Processing, Nutraceuticals End User: Food Manufacturers, Restaurants, Retailers, Catering Services Formulation: Conventional, Organic, Natural, Customized |
| Companies Covered | Novozymes, Maysa Gida, Chr. Hansen, Fonterra Co-operative Group, Ginkgo BioWorks, Koninklijke DSM N.V., Kerry Group, Advanced Enzyme Technologies, DuPont Nutrition & Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Chymosin Market Shifts & Advancements
Genome-editing tools and automated bioprocess control are compressing strain development cycles while regulatory clarity lags, creating a capability gap between biotech-enabled suppliers and traditional enzyme houses.
Continuous perfusion fermentation systems are replacing fed-batch protocols in industrial chymosin manufacturing. Novozymes and Chr. Hansen are retrofitting Danish facilities with real-time metabolite monitoring to sustain 90+ day production runs. This operational shift is converging with modular enzyme bundling strategies that separate coagulant procurement from adjunct culture purchasing.
EFSA novel food opinion timelines for genome-edited microbial strains are extending beyond 24 months, forcing developers to maintain parallel GMO-compliant and non-GMO strain pipelines. The regulatory friction most acutely affects powder and granulated format launches targeting extended-shelf-life applications. German and French regulators are requesting additional allergenicity data for fungal host proteins.
Specialty cheese buyers are unbundling starter culture systems to procure fermentation-grade chymosin independently, then recombining with proprietary adjunct blends. This disintermediation of integrated enzyme suppliers is most visible among Netherlands-based artisanal producers and Wisconsin farmstead operations seeking recipe differentiation through coagulant sourcing transparency.
Fermented Chymosin Market Segmentation
Segmentation in fermented chymosin procurement reveals divergent compliance burdens across product formats and certification tiers. Buyers face distinct documentation requirements from EFSA, FDA, and national organic bodies depending on segment selection.
Product Type:
Certification complexity varies sharply by physical state—liquid formulations face continuous processing audits while solid formats trigger extended allergenicity reviews under EFSA novel food pathways.
- Liquid:Precision-dosed aqueous concentrates dominate industrial dairy installations across Germany and Denmark. Continuous processing lines in Dutch cheese cooperatives favor this format for automated metering accuracy and batch consistency.
- Powder:Spray-dried formulations offer freight economy and 24-month shelf stability for smaller Italian and French artisanal producers. Extended storage reduces working capital pressure for seasonal milk supply regions.
- Solid:Tablet and cake formats persist in traditional meat processing applications across Spain and Portugal where heritage recipe preservation overrides processing efficiency priorities.
- Granulated:Free-flowing particulate structures improve dispersibility in reconstitution steps for Wisconsin farmstead operations lacking liquid handling infrastructure.
Leading the category by volume: Liquid. Growing fastest: Granulated.
Application:
End-use concentration determines regulatory pathway intensity—dairy applications trigger EMA enzyme safety evaluations while nutraceutical entrants face novel food opinion timelines.
- Dairy Production:Industrial-scale milk coagulation for commodity cheese manufacturing across Bavaria and Lombardy. Automated dosing systems in these regions require 98%+ purity specifications with batch-to-batch variance below 2%.
- Cheese Making:Heritage recipe protection drives artisanal adoption in the Netherlands and Vermont. PDO certification requirements in these jurisdictions mandate documented non-animal coagulant provenance.
- Meat Processing:Traditional applications in Iberian cured meat production face declining enzyme substitution as plant-based alternatives displace fermentation-derived inputs.
- Nutraceuticals:Emerging encapsulation formats for digestive health supplements encounter 18-24 month EFSA novel food approval cycles delaying commercial launch timelines.
Volume concentration: Dairy Production. Steepest expansion trajectory: Cheese Making.
End User:
Procurement scale separates compliance burden tiers—food manufacturers face consolidated supplier audits while foodservice operators navigate fragmented distributor documentation.
- Food Manufacturers:Consolidated purchasing power among German and French dairy conglomerates drives multi-year supply agreements with embedded organic certification guarantees. These buyers command dedicated fermentation runs with full substrate traceability.
- Restaurants:Farm-to-table concepts in Copenhagen and Amsterdam source micro-batch liquid chymosin through specialty enzyme distributors with technical support bundling.
- Retailers:Private-label cheese programs at European supermarket chains impose tiered supplier qualification standards separating organic-certified from conventional inputs.
- Catering Services:Institutional procurement in Nordic school and hospital systems follows national organic foodservice mandates with 80%+ fermentation-derived coagulant sourcing targets.
Demand weight: Food Manufacturers. Gaining share fastest: Restaurants.
Formulation:
Input documentation intensity escalates across the certification spectrum—organic tiers require 6-9 month audit cycles while conventional pathways qualify in 8-12 weeks.
- Organic:Non-GMO substrate fermentation with EU 2018/848 compliance documentation. German specialty cheese producers face tightening farm-to-fork traceability windows ahead of 2025-2026 deadlines.
- Conventional:Glucose-fed fermentation runs using standard recombinant fungal hosts. Cost advantage of 15-40% versus organic feedstock tiers sustains volume leadership in commodity dairy applications.
- Natural:Ambiguous regulatory classification between animal-derived and fermentation-derived sources creates labeling uncertainty across Italian and French enforcement jurisdictions.
- Customized:Client-specified purity grades and adjunct compatibility profiles for Netherlands-based artisanal producers seeking recipe differentiation through coagulant sourcing transparency.
Volume leader: Conventional. Climbing the fastest: Organic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's biotech special economic zones concentrate recombinant strain development infrastructure, drawing precision fermentation investment from across Northern Europe. These tax-advantaged clusters anchor continental supply for fermentation-derived coagulants.
Germany
Bavarian dairy cooperatives are retrofitting facilities for organic-certified chymosin dosing ahead of EU Green Deal farm-to-fork deadlines. The country's federal food safety office enforces tightening substrate traceability documentation. Artisanal cheese clusters in the Allgäu region now require 80% fermentation-derived coagulant sourcing for PDO compliance.
United States
Wisconsin farmstead operations and Vermont creameries drive artisanal adoption of liquid chymosin formats. FDA GRAS self-affirmation pathways accelerate market entry versus European novel food timelines. The Upper Midwest dairy belt is installing automated dosing systems that favor precision-fermented inputs over traditional rennet.
France
PDO certification requirements in Normandy and Auvergne-Rhône-Alpes mandate documented non-animal coagulant provenance for heritage cheese protection. ANSM allergenicity reviews extend EFSA evaluation timelines for fungal host proteins. Comté and Roquefort producers are unbundling starter systems to source chymosin independently.
Netherlands
Gouda and Edam heritage producers in North Holland retrofit small-batch facilities for liquid chymosin precision dosing. The Dutch food safety authority enforces EU 2018/848 organic compliance for exported cheese. Wageningen University biotech incubators anchor strain optimization R&D pipelines serving domestic dairy cooperatives.
Italy
Parma and Grana Padano consortia face labeling uncertainty between animal-derived and fermentation-derived rennet classifications. The Ministry of Health interprets EU enzyme safety rules with regional variation across Lombardy and Emilia-Romagna. Parmesan producers in the Po Valley are qualifying dual-source supply chains pending regulatory clarity.
Fermented Chymosin Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the fermented chymosin value chain. Danish and Dutch biotech infrastructure operators dominate recombinant fungal host platforms for high-yield expression. Three archetypes define competitive positioning: integrated enzyme houses with distribution networks, precision fermentation technology developers, and regional dairy cooperative suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with bioreactor installation timelines stretching 18-24 months.
Among Danish biotech specialists, Novozymes and Chr. Hansen occupy positions anchoring recombinant strain development and dairy-specific enzyme cocktails respectively. Kerry Group represents the integrated distribution archetype, leveraging Irish-originated supply networks across European dairy markets. These three exemplify the geographic concentration of fermentation-grade chymosin capability within Northern European biotech clusters.
| Leading Market Players |
|---|
| Novozymes |
| Maysa Gida |
| Chr. Hansen |
| Fonterra Co-operative Group |
| Ginkgo BioWorks |
| Koninklijke DSM N.V. |
| Kerry Group |
| Advanced Enzyme Technologies |
| DuPont Nutrition & Biosciences |
| Others |
Supply & Pricing Matrix
Danish precision-fermentation specialists in the Copenhagen-Roskilde corridor command wage premiums of 25-35% above standard chemical manufacturing rates, compressing margin spreads between organic-certified and conventional chymosin tiers to their narrowest differential in the analysis window.
Pricing Analysis
Expedited delivery premiums of 8-15% apply to liquid chymosin orders requiring sub-48-hour fulfillment from Danish bioreactor facilities, while spot-market powder inventory from Dutch distributors trades at 5-12% discounts to contract rates. Three-tier pricing structure across organic-certified, conventional fermentation-grade, and animal-derived rennet alternatives reflects substrate traceability documentation burdens and purity variance specifications. Cost compression in conventional glucose-fed tiers is intensifying because German dairy cooperatives are consolidating procurement volumes under multi-year framework agreements. Food manufacturers with dedicated fermentation runs exhibit lowest price sensitivity, while Wisconsin farmstead operations and Italian artisanal producers show highest elasticity to freight-adjusted delivered costs.
Supply Chain Analysis
Bioprocess engineering talent scarcity in Denmark, the Netherlands, and Germany constrains facility expansion timelines, with qualified fermentation technicians commanding relocation packages and retention bonuses that feed directly into unit economics. Commercial-grade chymosin production draws from recombinant fungal host strains, pharmaceutical-grade glucose or certified organic substrates, and single-use bioreactor components sourced from specialized cleanroom equipment suppliers. Single-source vulnerability concentrates in Novozymes' proprietary Aspergillus expression platforms, which anchor 60-70% of European recombinant chymosin yield capacity. Distribution runs through Kerry Group's pan-European enzyme distribution network for industrial dairy accounts, while specialty distributors serve artisanal segments via direct technical-support-bundled channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermented chymosin supply remains structurally constrained by 18-24 month bioreactor qualification timelines, with capacity additions lagging demand acceleration from EU Green Deal substitution mandates and artisanal dairy cluster expansion.
For Market Incumbents: To counter patent-thicket encroachment from genome-editing startups, secure exclusive substrate supply agreements with non-GMO glucose refiners in Northern France and accelerate backward integration into fungal host strain libraries through Wageningen University partnership structures. For New Entrants and Emerging Players: Launch via direct-to-producer e-commerce platforms with embedded technical support, targeting the underpenetrated US artisanal segment in Wisconsin and Vermont where FDA GRAS self-affirmation pathways compress regulatory entry timelines versus European novel food opinions. For Investors and Strategic Acquirers: The window for entry favors precision-fermentation technology developers with demonstrated CRISPR strain optimization capabilities and existing dairy enzyme regulatory dossiers, positioning for 5-10 year horizon consolidation as EFSA genome-edited organism classifications clarify; watch for EFSA opinion publication velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Dedicated chymosin production lines in Danish special economic zones anchor supply security for EU dairy cooperatives. |
| Organic Substrate Backward Integration | Non-GMO glucose refining partnerships in Northern France reduce feedstock cost volatility for certified fermentation runs. |
| Genome-Edited Strain Pipeline | Parallel GMO-compliant and non-GMO strain development hedges regulatory uncertainty pending EFSA classification determinations. |
| Direct-to-Producer Distribution | E-commerce platforms with technical support bundling bypass traditional dairy ingredient brokers serving Wisconsin farmstead operations. |
| Regulatory Dossier Acceleration | Pre-submission engagement with FDA GRAS pathways and EMA enzyme safety evaluations compresses market access timelines for new entrants. |
Research Methodology
Multi-period observation of bioreactor utilization rates, organic certification audit cycle durations, and artisanal dairy facility retrofit announcements anchored the trend analysis, supplemented by interviews with fermentation plant managers, specialty cheese procurement leads, regulatory affairs directors at enzyme houses, and Dutch dairy cooperative technical officers. Secondary validation drew from EFSA novel food opinion databases, FDA GRAS notification filings, EU 2018/848 organic compliance registries, and SEC 10-K disclosures from diversified ingredient suppliers. Bottom-up volume modeling across product format, application, and certification tier segments triangulated against top-down value estimates derived from disclosed supply agreements and distributor pricing benchmarks.
Input-output matrices mapped substrate feedstock costs, bioprocess yield coefficients, and purity-grade premiums to unit economics across the projection horizon, with segmentation dimensions spanning physical state, end-use application, procurement scale, and formulation certification level. CAGRs were synthesized from segment-level growth rate distributions weighted by disclosed capacity expansion timelines and regulatory pathway probability assessments. Industry-specific forecast inputs included EFSA opinion pipeline velocity, EU Green Deal implementation phase schedules, and precision-fermentation technology convergence indicators from automated bioreactor monitoring system deployments.
Genome-edited organism reclassification, organic substrate supply disruption, and artisanal dairy demand deceleration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory timeline continuity and strain development success rates. Material deviation in named triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Japan Feed Additives Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
China Food Preservatives Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Europe Food Enzymes Market
Food Additives and Ingredients
Brazil Food Emulsifiers Market
Food Additives and Ingredients
Alpha-Linolenic Acid Market
Food Additives and Ingredients
Tapioca Starch Market