
 Seed Packaging Market | 2026-2036
Seed Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Packaging Market Analytics
The gap between premium and commodity seed packaging is expanding in material complexity and unit economics. Mondi Group leverages kraft-paper hybrid platforms to serve European organic seed producers requiring compostable certification. Amcor plc anchors North American volume through high-barrier foil laminates engineered for extended shelf life in corn and soybean distribution. SÜDPACK differentiates via precision-printed small-format sachets targeting vegetable seed companies with varietal traceability demands.
Seed packaging encompasses engineered containment systems designed to protect germplasm from moisture, oxygen, and mechanical damage across storage and transit cycles, typically incorporating barrier layers of polyethylene, aluminum oxide-coated films, or bio-based polymers with specified water vapor transmission rates below 5 g/m²/day. Plastic materials still dominate tonnage across bag and box formats, though biodegradable segments are gaining fastest as agricultural cooperatives in the EU and California face extended producer responsibility mandates. Heat-seal closures occupy the mature core of the market, while resealable ziplock configurations capture margin pools in home gardening channels where repeat access drives premium pricing.
The EPA regulates pesticide-treated seed packaging under FIFRA labeling requirements, while the EU Green Deal and REACH constrain phthalate and heavy-metal additives in polymer formulations. India's BIS enforces IS 8198 standards for woven polypropylene seed bags, shaping export competitiveness for domestic converters. Stakeholders must monitor evolving compostability certification schemes and state-level plastic bans to align capital allocation with regulatory trajectories.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing adoption timelines for multilayer plastic alternatives, forcing converters to requalify barrier formulations ahead of 2030 mandates while specialty crop producers in Brazil and California accelerate biodegradable pouch trials.
Growth Catalysts
- Extended Producer Responsibility mandates:California's SB 54 and the EU Packaging and Packaging Waste Regulation compel agricultural cooperatives to source certified compostable seed pouches, creating pull-through demand for bio-based polymer converters.
- Contract farming cluster formation:India's Punjab and Haryana belt concentrates bulk seed procurement volumes, driving economies of scale in woven polypropylene bag production for domestic and export markets.
- Aluminum oxide-coated film platforms:High-barrier transparent films with sub-5 g/m²/day water vapor transmission rates enable premium vegetable seed producers to eliminate foil laminates while maintaining shelf life.
Market Restraints
- Biopolymer feedstock cost volatility:PLA and PHA resin prices fluctuate with corn sugar and vegetable oil commodity markets, compressing margin structures for converters serving price-sensitive commodity grain segments.
- Multilayer film recycling infrastructure gaps:Europe lacks industrial-scale collection and separation capacity for metallized polyethylene-nylon laminates, stranding existing equipment investments.
- Barrier performance trade-offs:Current kraft-paper hybrid structures fail oxygen ingress specifications for tropical climate storage, limiting addressable market share in high-humidity geographies.
Strategic Opportunities
- Home gardening channel expansion:Resealable ziplock sachets with varietal traceability QR codes capture margin pools in direct-to-consumer seed retail, where repeat access commands 40-60% price premiums over heat-seal formats.
- Precision agriculture integration:Printed electronics embedding moisture and temperature sensors within seed packaging is converging with farm management software platforms, enabling condition monitoring through distribution chains.
- EU Green Deal material transition subsidies:Innovation funding under the Circular Economy Action Plan offsets capital equipment costs for converters retooling to compostable certification schemes.
Industry Challenges
- Compostability certification timeline compression:TÜV Austria's OK Compost HOME and INDUSTRIAL validation cycles extend 12-18 months, delaying product launches ahead of seasonal planting windows.
- Legacy heat-seal equipment reconfiguration:Converters must retrofit ultrasonic and induction sealing lines to handle bio-based polymer melt-flow properties without compromising line speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Packaging Market |
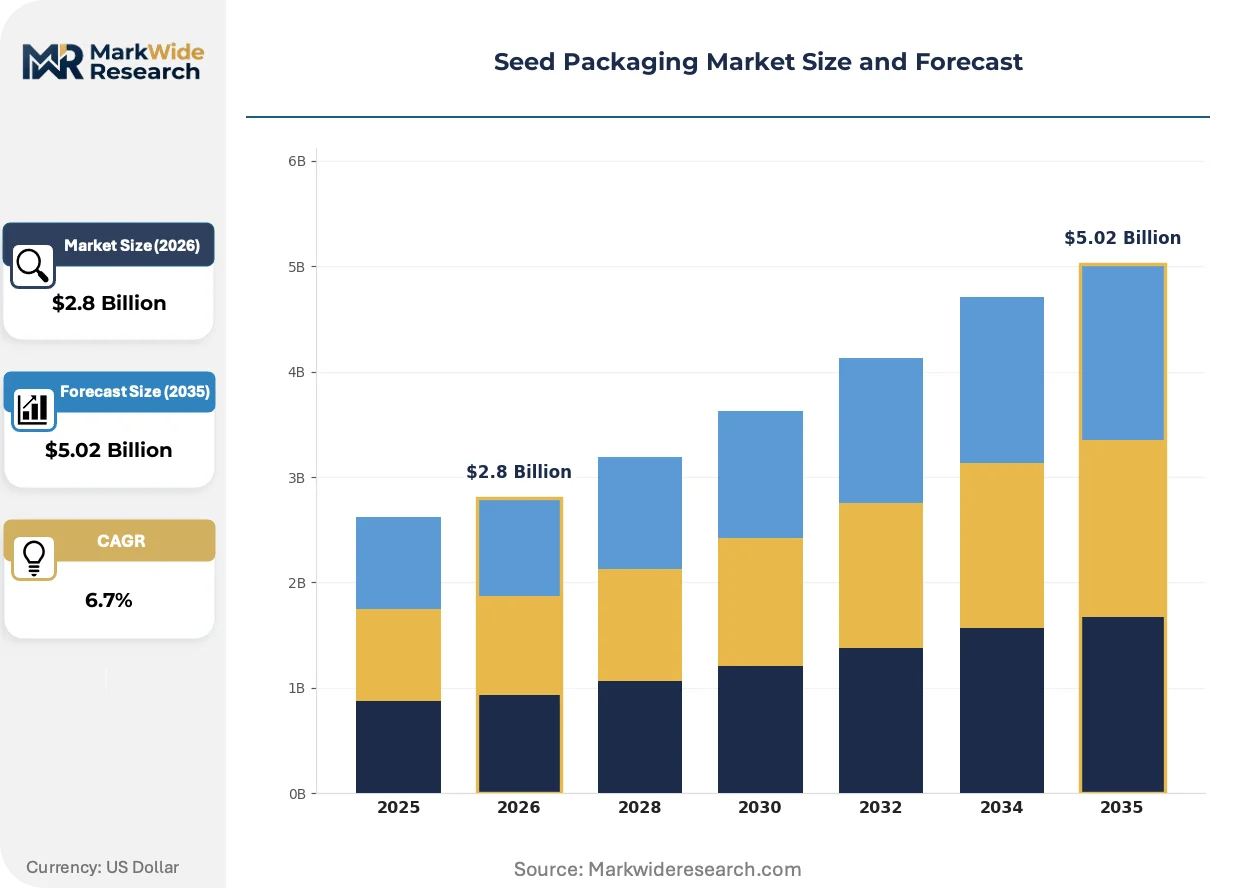
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Biodegradable, Foil Packaging Format: Bag, Box, Wrapper, Bottle End Use: Agricultural, Home Gardening, Commercial, Horticultural Closure Type: Ziplock, Heat Seal, Taped, Resealable |
| Companies Covered | Mondi Group, SÜDPACK, Amcor plc, WestRock, Sonoco Products Company, Berry Global Inc., Sealed Air Corporation, LC Packaging International, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Packaging Market Evolving Landscape
Active and intelligent packaging technologies are penetrating seed containment systems, shifting competitive differentiation from static barrier properties to dynamic condition monitoring and authentication capabilities.
Printed electronics with near-field communication chips is converging with blockchain traceability platforms, enabling vegetable seed companies to verify varietal provenance and germination batch records. European organic producers are piloting these hybrid systems at 15-20% cost premiums over conventional labels. The structural consequence is compressing counterfeiting margins while creating new data-service revenue streams for packaging suppliers.
REACH restrictions on phthalate plasticizers and heavy-metal colorants are forcing polymer compounders to reformulate masterbatch additives for seed bag inks and coatings. The industrial consequence is qualification bottlenecks at European converters, with reformulation cycles extending 8-12 months. Vegetable seed sachets with direct food-contact surfaces face the most stringent migration testing requirements, driving substitution toward mineral-based pigment systems.
Direct procurement relationships between seed multinationals and packaging converters are displacing traditional distributor intermediaries in North American corn and soybean segments. Bayer and Corteva Agriscience are consolidating supplier bases to capture volume discounts and technical collaboration on barrier design. This channel compression is most visible in the US Midwest, where regional distributors have lost 25-30% of historical seed bag volumes to direct contracts since 2022.
Seed Packaging Market Segmentation
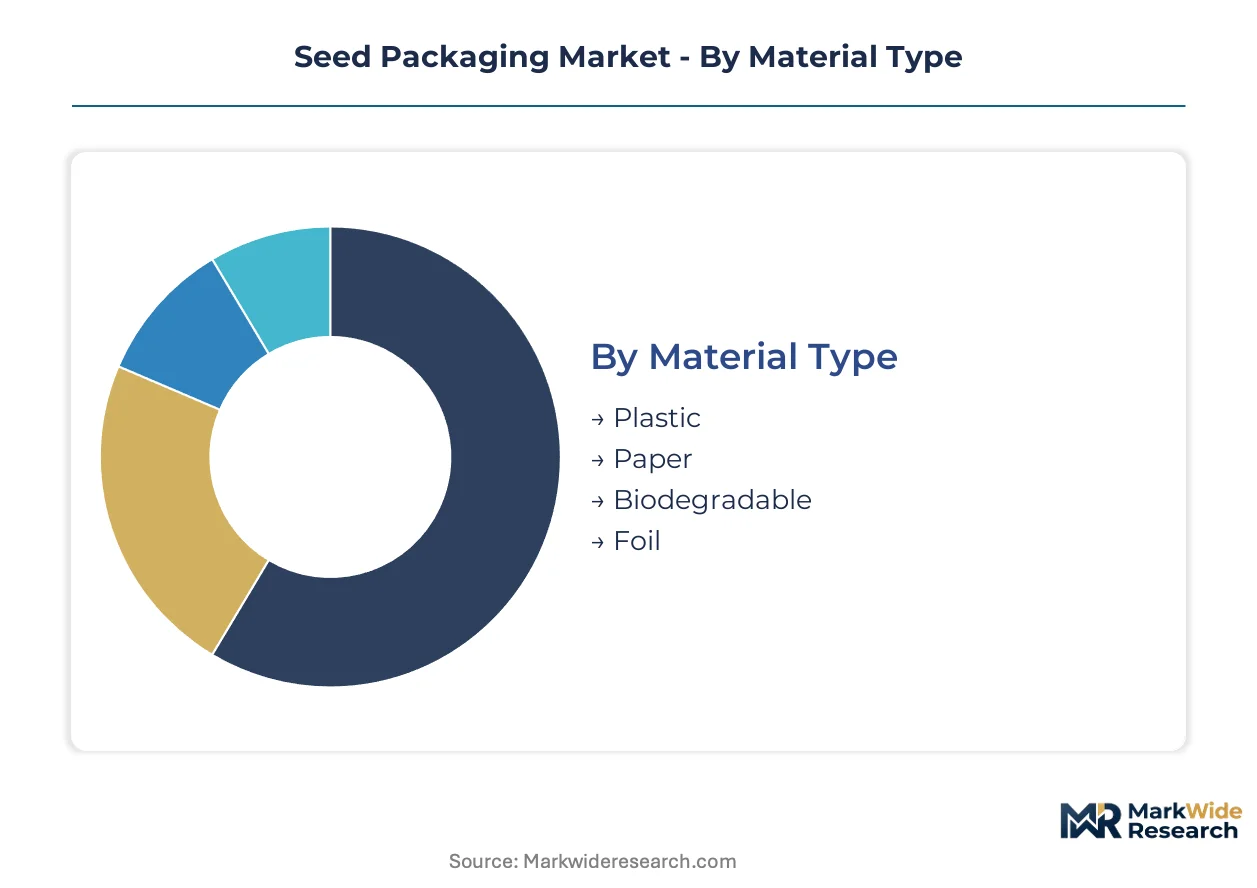
Seed packaging segmentation reveals divergent economics across material platforms and distribution channels. Volume-driven commodity grain segments prioritize cost minimization in woven polypropylene, while premium vegetable and organic seed producers absorb material premiums for compostable certification and traceability integration.
Material Type:
Plastic dominates tonnage across bulk agricultural applications, while biodegradable alternatives command margin premiums in regulated European and Californian markets.
- Plastic:Polyethylene and polypropylene laminates deliver sub-5 g/m²/day water vapor transmission rates essential for tropical climate corn and soybean storage. India's BIS IS 8198 standards shape woven polypropylene specifications for domestic converters and export competitiveness.
- Biodegradable:PLA and PHA polymers from corn sugar and vegetable oil feedstocks serve EU Green Deal compliance requirements, though resin price volatility compresses margins in price-sensitive commodity segments. TÜV Austria OK Compost certification cycles extend 12-18 months, delaying seasonal product launches.
- Paper:Kraft-paper hybrid structures with aluminum oxide barrier coatings target European organic producers requiring compostable certification, though oxygen ingress limitations restrict tropical market penetration.
- Foil:Metallized aluminum laminates anchor North American high-barrier applications for extended shelf life in corn and soybean distribution networks.
Today's leader: Plastic. Tomorrow's challenger: Biodegradable.
Packaging Format:
Format selection tracks seed value density and mechanized handling requirements across agricultural supply chains.
- Bag:Woven polypropylene sacks concentrate in India's Punjab and Haryana contract farming clusters, where bulk procurement volumes drive economies of scale for domestic converters.
- Box:Corrugated fiberboard containers with moisture-barrier liners serve precision agriculture distributors requiring palletized logistics and retail-ready presentation.
- Wrapper:Flow-wrap configurations with printed electronics integration enable vegetable seed companies to embed NFC chips for blockchain traceability verification.
- Bottle:Rigid PET and HDPE containers capture home gardening channel premiums for ornamental flower and herb seed assortments with resealable closures.
Bags anchor agricultural volume. Wrappers gain share fastest in traceability-enabled premium segments.
End Use:
Customer type determines performance specifications, with commercial producers prioritizing barrier properties and home gardeners valuing access convenience.
- Agricultural:Corn and soybean multinationals in the US Midwest consolidate direct procurement relationships with converters, displacing traditional distributor intermediaries and capturing volume discounts on high-barrier foil laminates.
- Home Gardening:Resealable ziplock sachets with varietal traceability QR codes command 40-60% price premiums over heat-seal formats in direct-to-consumer retail channels where repeat access drives purchasing decisions.
- Commercial:Horticultural nursery operators require batch-coded packaging for inventory rotation compliance, favoring precision-printed formats with germination date visibility.
- Horticultural:Specialty crop producers in Brazil scale biodegradable pouch purchases ahead of extended producer responsibility mandates, piloting compostable platforms for export market access.
Agricultural volume dominates. Home gardening delivers the steepest margin expansion trajectory.
Closure Type:
Closure mechanics separate commodity bulk handling from premium retail experiences, with heat-seal equipment legacy constraining bio-based polymer transitions.
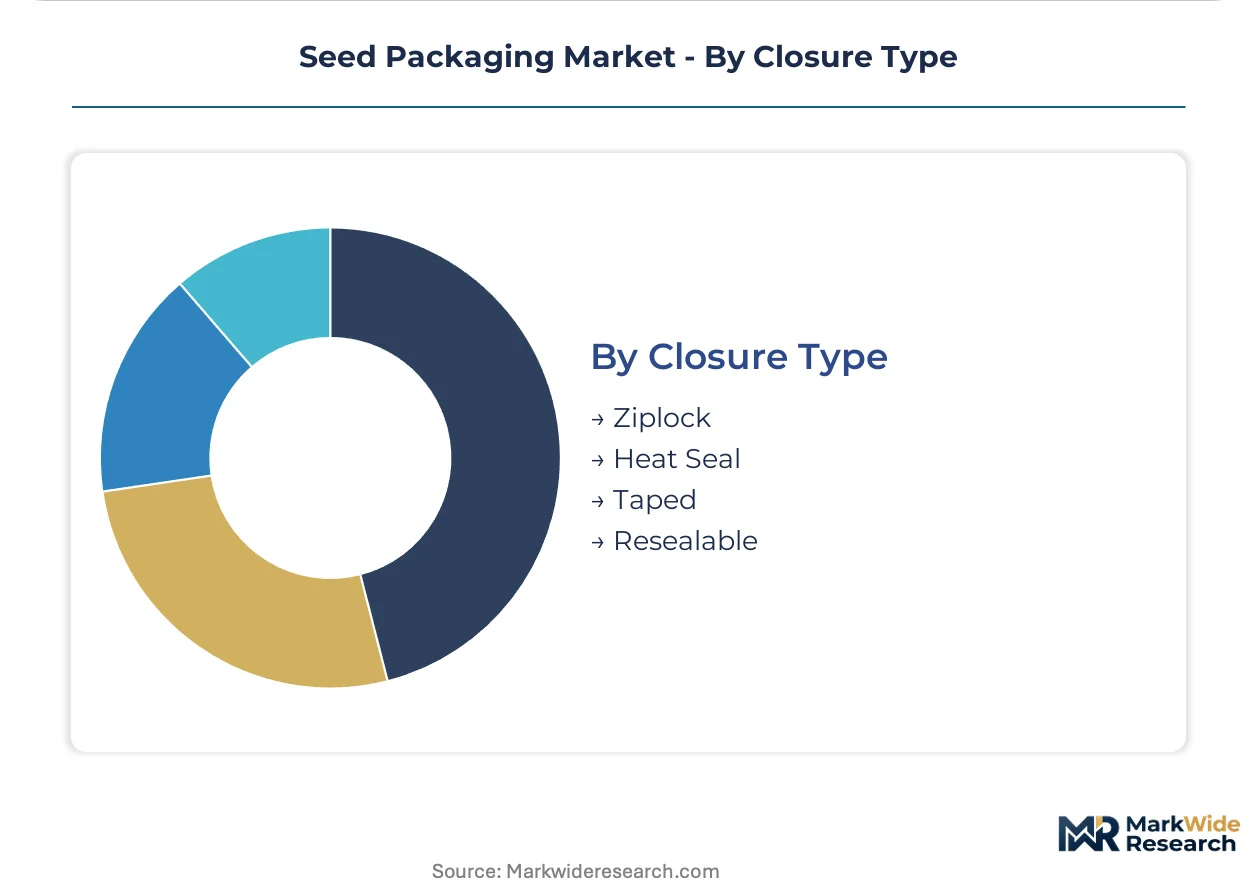
- Heat Seal:Mature core technology for woven polypropylene agricultural bags, with legacy equipment requiring ultrasonic retrofit to handle bio-based polymer melt-flow properties without line speed compromise.
- Ziplock:Resealable configurations capture home gardening margin pools through repeat access functionality, with precision-molded slider mechanisms adding unit cost for premium positioning.
- Taped:Pressure-sensitive adhesive closures serve interim applications in developing market distribution where reseal functionality is non-critical.
- Resealable:Induction-sealed membranes with peelable secondary access layers bridge barrier integrity and convenience for high-value vegetable seed sachets.
Heat seal holds agricultural volume. Ziplock resealability expands fastest in consumer-facing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and polymer chemists concentrate in Germany's industrial belt, Brazil's agribusiness corridors, and India's northern agricultural heartland, anchoring regional specialization in barrier film innovation and sustainable material transitions.
Germany
REACH restrictions on phthalate plasticizers and heavy-metal colorants force polymer compounders to reformulate masterbatch additives for seed bag inks. The EU Green Deal's packaging waste directives compress adoption timelines for multilayer plastic alternatives ahead of 2030 mandates. Bavaria's converter clusters near Munich pilot kraft-paper hybrid platforms with aluminum oxide barrier coatings for organic seed producers.
United States
Corn and soybean multinationals in the US Midwest consolidate direct procurement relationships with converters, displacing traditional distributor intermediaries. The EPA regulates pesticide-treated seed packaging under FIFRA labeling requirements. Illinois and Iowa host precision agriculture integration pilots where printed electronics embed moisture sensors within seed packaging for farm management software convergence.
Brazil
Specialty crop producers scale biodegradable pouch purchases ahead of extended producer responsibility mandates. ANVISA oversees agricultural input regulations affecting treated seed containment standards. São Paulo state's agribusiness clusters drive export-oriented compostable packaging trials targeting EU market access requirements.
India
Contract farming clusters in Punjab and Haryana concentrate bulk seed procurement volumes, driving economies of scale in woven polypropylene bag production. BIS enforces IS 8198 standards for woven polypropylene seed bags, shaping export competitiveness for domestic converters. Ludhiana and Hisar house specialized extrusion and printing facilities serving domestic and Middle Eastern export markets.
China
Dual carbon goals and MEE environmental standards accelerate biopolymer R&D investments among domestic packaging conglomerates. GB standards govern food-contact and agricultural packaging migration limits. Yangtze River Delta manufacturing zones near Shanghai produce aluminum oxide-coated transparent films with sub-5 g/m²/day water vapor transmission rates for premium vegetable seed exports.
Seed Packaging Market Competitive Landscape
Top-tier vendors anchor high-barrier foil and film platforms, while mid-scale specialists occupy compostable certification niches and regional converters serve commodity grain segments with cost-optimized woven polypropylene. The vendor base stratifies across three archetypes: multinational material science conglomerates with integrated polymer supply chains, mid-cap specialists holding TÜV Austria compostability certifications, and regional fabricators leveraging proximity to India's agricultural belt. Dominant competitive moves include direct procurement relationship consolidation between seed multinationals and converters, and equipment retooling to handle bio-based polymer melt-flow properties without line speed compromise.
Within the multinational tier, Mondi Group and Amcor plc exemplify divergent strategic positioning—Mondi leveraging kraft-paper hybrid platforms for European organic certification requirements, Amcor anchoring North American volume through extended shelf-life barrier engineering. SÜDPACK occupies a specialist position in precision-printed small-format sachets, representing the traceability-enabled premium segment where varietal authentication commands material premiums.
| Leading Market Players |
|---|
| Mondi Group |
| SÜDPACK |
| Amcor plc |
| WestRock |
| Sonoco Products Company |
| Berry Global Inc. |
| Sealed Air Corporation |
| LC Packaging International |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters across India's Punjab and Haryana belt maintain pricing discipline through captive extrusion capacity and direct contract farming relationships, while European specialist firms absorb bio-based polymer premiums to secure EU Green Deal compliance positioning.
Pricing Analysis
Bundled barrier engineering services with compostability certification command 25-40% premiums over unbundled commodity bag supply. Three-tier pricing structure across premium, standard, and economy levels separates TÜV Austria-certified bio-polymer platforms from BIS IS 8198-compliant woven polypropylene and untreated kraft-paper hybrids. Cost compression in standard-tier foil laminates is intensifying because seed multinationals consolidate direct procurement volumes. Commodity grain producers in Brazil and India exhibit highest price sensitivity, while European organic vegetable seed companies absorb material premiums for traceability integration.
Supply Chain Analysis
India's domestic-content mandates under Make in India and PLI scheme incentives are reshaping sourcing patterns for woven polypropylene feedstock and extrusion equipment. Manufacturing gravity centers on India, China, and Germany, with resin compounding anchored in the Yangtze River Delta and Bavaria's industrial corridor. Supply chains draw from corn sugar and vegetable oil feedstocks for PLA and PHA biopolymers, aluminum oxide-coated PET films, and metallized foil laminates. Single-source vulnerability concentrates in TÜV Austria certification capacity for compostable validation. Distribution runs through direct procurement relationships between seed multinationals and converters, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory compliance premiums exceed Indian manufacturing cost advantages by 35-50% on equivalent barrier specifications.
For Market Incumbents: Deploy certification pre-qualification capacity to lock in seasonal planting window availability ahead of competitor product launches. Capture backward integration into bio-polymer resin compounding to offset PLA and PHA feedstock volatility. Defend against mid-cap specialists holding TÜV Austria OK Compost INDUSTRIAL validation by accelerating kraft-paper hybrid platform R&D for oxygen barrier improvement. For New Entrants and Emerging Players: Precision-printed small-format sachets with NFC-enabled traceability offer the most penetrable white-space target, as incumbent conglomerates underinvest in home gardening channel customization. Target California's SB 54 compliance-driven biodegradable pouch demand where extended producer responsibility mandates create guaranteed offtake. Pursue equipment-leasing partnerships with Indian extrusion fabricators to bypass capital-intensive barrier film co-extrusion setup. For Investors and Strategic Acquirers: Valuations sit cheapest among regional Indian converters with BIS IS 8198 certification and captive woven polypropylene capacity serving Middle Eastern export markets. Long-term viability over a five-to-ten-year horizon rests on successful navigation of EU Green Deal material transition timelines and bio-based polymer qualification bottlenecks. Monitor TÜV Austria certification queue lengths as the critical inflection signal for compostable platform supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Compostability Certification Investment | TÜV Austria OK Compost validation unlocks EU Green Deal-compliant revenue pools ahead of 2030 mandates. |
| Direct Procurement Relationship Consolidation | Bayer and Corteva-style volume discounts displace distributor intermediaries and capture technical collaboration value. |
| Printed Electronics Integration | NFC-embedded moisture sensors enable farm management software convergence and data-service revenue streams. |
| Backward Integration into Bio-Polymer Compounding | In-house PLA and PHA resin production hedges corn sugar and vegetable oil commodity volatility exposure. |
| Regional Converter Acquisition in India | Punjab and Haryana belt facilities access contract farming cluster volumes and BIS IS 8198 export certification. |
Research Methodology
Bottom-up seed packaging format modeling reconciled against top-down polymer converter capacity tracking forms the analytical core of this study. Primary interviews with extrusion plant managers, seed company procurement directors, TÜV Austria certification auditors, and agricultural cooperative supply chain officers combined with secondary validation from BIS standards documentation, EU Packaging and Packaging Waste Regulation filings, EPA FIFRA labeling guidance, and customs trade data for woven polypropylene and bio-polymer resin flows. Triangulation across stakeholder inputs and documentary sources ensures segment-level volume and value consistency.
Historical trendline analysis of material platform adoption rates, barrier specification evolution, and regulatory compliance timelines informs projection mechanics. The forecast framework segments by material type, packaging format, end-use application, closure mechanism, and regional regulatory cluster, with CAGRs derived from elasticity-adjusted penetration curves and substitution rate modeling. Industry-specific inputs include compostability certification queue durations, heat-seal equipment retrofit lead times, and seed multinational direct procurement consolidation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal implementation pacing, bio-polymer feedstock commodity cycles, and breakthrough oxygen barrier technologies for kraft-paper hybrid structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Cartoning Machines Market
Packaging
Insulated Food Delivery Bags Market
Packaging
Latin America Canned Food Packaging Market
Packaging
Continuous Thread Metal Cap Market
Packaging
India BOPP Films Market
Packaging
Bags and Containers Market
Packaging
Brazil Plastic Packaging Market
Packaging
Reusable Barrels Market
Packaging
Food Packaging Robotics Market
Packaging
North America Paper Cups Market
Packaging
Pharmaceutical Cold Chain Packaging Market
Packaging
Clay Coated Recycled Boxboard Market
Packaging
Global Thermal Transfer Ribbon Market
Packaging
Liquid Packaging Bag Market
Packaging
Ambient Packaging Market
Packaging
Fiber Bale Packaging Film Market