
 Global Feed Phytobiotics Market | 2026-2036
Global Feed Phytobiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feed Phytobiotics Market Foresight
The EU Green Deal's Farm to Fork strategy is consolidating demand for plant-derived feed additives across European livestock operations. Cargill, Incorporated leverages its integrated nutrition platforms to supply phytobiotic premixes directly to poultry integrators. Delacon Biotechnik GmbH specializes in essential oil formulations for ruminant methane mitigation, anchoring its position in climate-stressed dairy regions. BASF SE extends its phytogenics portfolio through controlled-release technologies that protect active compounds from rumen degradation.
Feed phytobiotics comprise bioactive plant-derived compounds including essential oils, oleoresins, and herbal extracts incorporated into animal diets to enhance performance without synthetic antimicrobial inputs. These formulations typically contain terpenoids, phenolic compounds, and alkaloids at standardized concentrations to ensure batch-to-batch efficacy in gut microbiota modulation. Essential oils dominate current volume flows due to established supply chains from spice-producing regions and proven efficacy in poultry gut health applications. The aquaculture segment registers accelerated uptake as shrimp and salmon producers in Norway and Vietnam substitute phytobiotics for prophylactic antibiotics amid export certification requirements.
The European Food Safety Authority evaluates novel phytobiotic submissions under feed additive authorization protocols, while the FDA's Veterinary Feed Directive restricts medically important antibiotics in US livestock, redirecting procurement toward botanical alternatives. China's Ministry of Agriculture and Rural Affairs enforces stricter residue limits on animal products destined for domestic retail and export markets. Stakeholders must monitor evolving maximum residue limits across destination markets and align formulation investments with jurisdiction-specific approval timelines.
Market Dynamics
Antibiotic withdrawal mandates across major protein-exporting nations are restructuring feed additive procurement, forcing integrators to validate phytobiotic efficacy through controlled field trials before full diet conversion.
Growth Catalysts
- EU Green Deal Farm to Fork:Binding antimicrobial reduction targets for livestock operations create compliance-driven demand for botanical feed additives across member state poultry and swine sectors.
- Essential oil microencapsulation:Advances in lipid-shell protection technologies enable rumen-stable delivery of terpenoid compounds, expanding phytobiotic applicability from monogastrics to dairy cattle.
- Brazil's southern poultry belt:Export-oriented processors facing EU residue compliance pressure are accelerating phytobiotic inclusion rates in antibiotic-free broiler programs.
Market Restraints
- Raw material concentration:Seventy percent of global oregano and thyme oil supply originates in Turkey and Morocco, creating price volatility exposure for formulators.
- Standardization gaps:Batch-to-batch variation in active compound concentration complicates veterinary prescribing and feed mill integration protocols.
- Probiotic competition:Direct-fed microbial products with established mode-of-action documentation capture budget share in gut health applications.
Strategic Opportunities
- Vietnamese aquaculture:Shrimp and salmon producers seeking ASC certification present unmet demand for phytobiotic alternatives to prophylactic antibiotics in pond and cage systems.
- China's residue enforcement:Stricter domestic retail and export limits by the Ministry of Agriculture and Rural Affairs redirect procurement toward approved botanical alternatives.
- Precision delivery platforms:Convergence of nanoliposome encapsulation with real-time feed monitoring systems enables targeted release in specific gut segments.
Industry Challenges
- Phytochemist talent scarcity:Shortage of specialists capable of isolating and standardizing bioactive compounds from complex botanical matrices delays product development cycles.
- EFSA authorization timelines:Novel feed additive submissions require 18-24 month safety and efficacy evaluations, compressing commercialization windows.
- Legacy antibiotic infrastructure:Existing veterinary supply chains and prescriber relationships create switching friction for botanical alternatives.
Report Scope
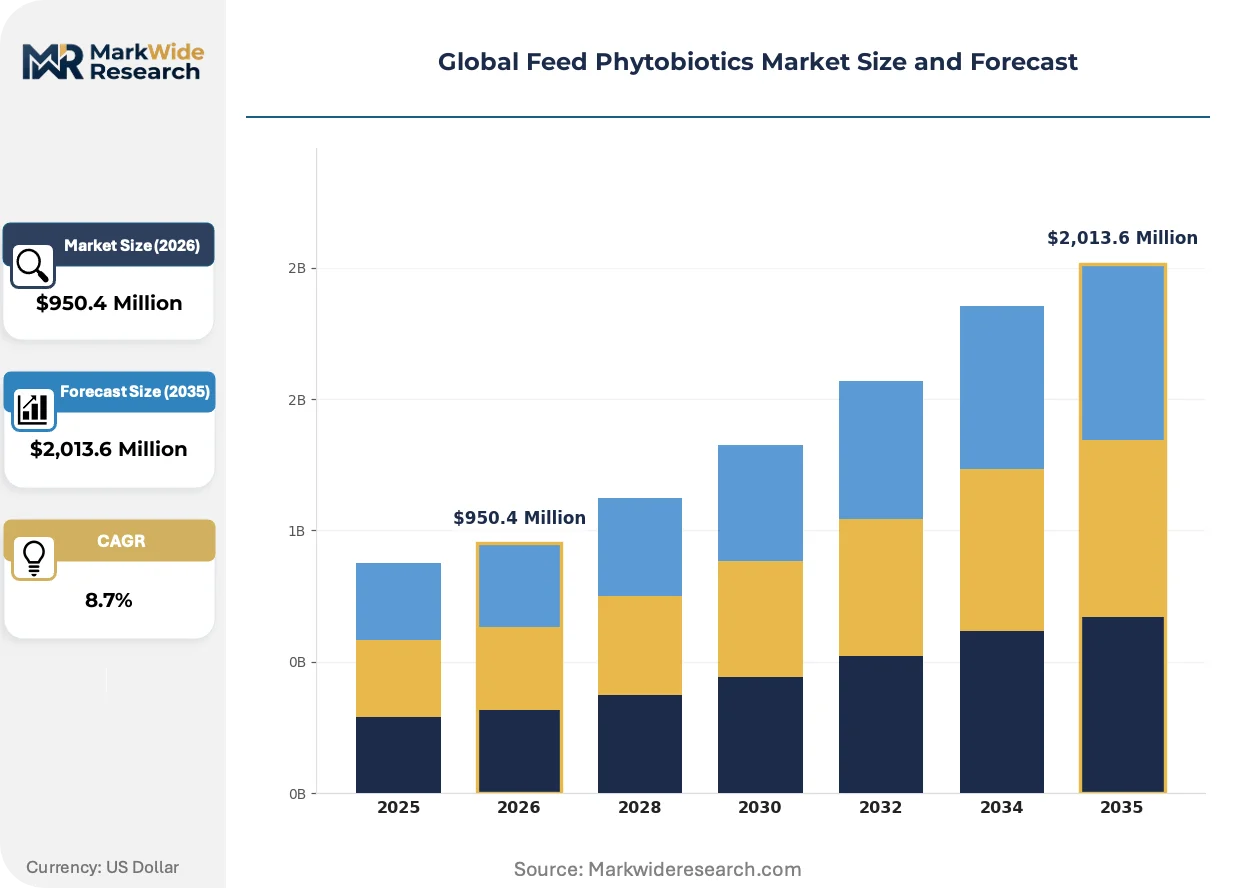
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feed Phytobiotics Market |
| Market Size in 2026 | $950.4 Million |
| Market Size in 2035 | $2,013.6 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Plant Extracts, Oleoresins, Spices, Herbs Animal Type: Poultry, Swine, Ruminants, Aquaculture, Pets Function: Growth Promotion, Disease Resistance, Digestive Health, Immunomodulation, Antioxidant Activity Distribution Channel: Direct Sales, Distributors, Online Platforms, Veterinary Clinics, Feed Mills |
| Companies Covered | Alltech, Inc., Phytobiotics Futterzusatzstoffe GmbH, Cargill, Incorporated, Nutreco N.V., Delacon Biotechnik GmbH, BASF SE, DSM-Firmenich AG, Archer Daniels Midland Company, Kemin Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feed Phytobiotics Market Shifts & Advancements
Formulation science is advancing faster than regulatory harmonization, creating capability gaps between suppliers with protected-release technologies and commodity botanical traders.
Microencapsulated essential oil blends are absorbing capital investment from major nutrition platforms seeking rumen-protected alternatives to ionophores. Dairy cooperatives in the Netherlands and Wisconsin are piloting these formulations in methane-mitigation programs. The technology is absorbing market share previously held by synthetic growth promoters by demonstrating measurable feed conversion improvements in controlled trials.
The FDA's Veterinary Feed Directive restricts medically important antibiotics in US livestock, redirecting procurement toward botanical alternatives with documented growth promotion claims. Feed mills in the Corn Belt are reformulating starter diets for weaned pigs to exclude tylosin and lincomycin. Poultry integrators in the Southeast are submitting phytobiotic protocols to export auditors as residue prevention documentation.
Buyer concentration among top-ten protein processors is compressing supplier negotiation leverage and demanding outcome-based efficacy guarantees. Direct contracting between integrators and phytobiotic developers is displacing distributor-mediated procurement in North American broiler operations. Brazil's JBS and BRF are consolidating approved supplier lists to three botanical premix partners per protein category.
Global Feed Phytobiotics Market Segmentation
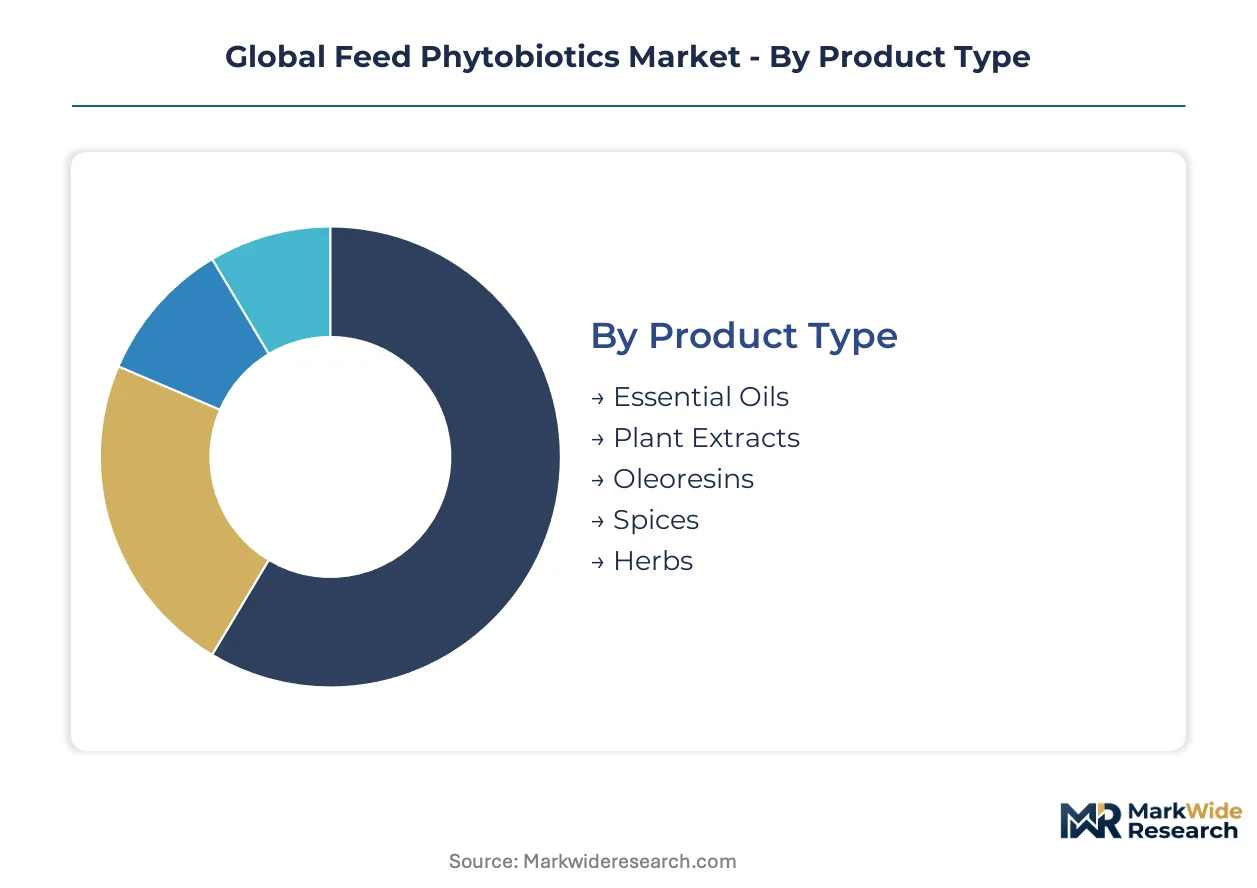
Feed phytobiotics demand fragments across product chemistries, animal physiology, and procurement pathways. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that shape supplier strategy.
Product Type:
Standardization intensity varies sharply across this category, from commodity spice powders to precision-formulated essential oil microcapsules requiring protected-release engineering.
- Essential Oils:Concentrated terpenoid and phenolic compounds extracted through steam distillation or cold pressing, standardized to minimum active thresholds. Poultry integrators in Brazil's southern belt specify thymol and carvacrol concentrations above 60% for antibiotic-free broiler programs facing EU residue audits.
- Plant Extracts:Solvent-derived bioactive fractions including saponins, flavonoids, and alkaloids with documented gut microbiota modulation. Dairy cooperatives in the Netherlands pilot these in methane-mitigation protocols, though batch-to-batch variation complicates veterinary prescribing.
- Oleoresins:Viscous solvent-extracted concentrates retaining lipophilic actives and natural antioxidants.
- Spices:Ground botanical material with variable active compound density, typically deployed in cost-sensitive ruminant applications.
- Herbs:Dried leaf and stem material requiring minimal processing, dominant in artisanal and organic livestock operations.
Leading the category by volume: Essential Oils. Expanding most quickly: Oleoresins as encapsulation technologies mature.
Animal Type:
Physiological complexity and regulatory scrutiny intensity diverge across species, from monogastric systems with rapid feed conversion measurement to ruminant chambers demanding rumen-stable delivery mechanisms.
- Poultry:Broiler and layer operations generate the densest efficacy data supporting phytobiotic claims, with gut health improvements measurable within 21-day grow-out cycles. Southeast Asian integrators scale inclusion rates fastest as antibiotic-free programs expand to meet export certification requirements.
- Swine:Post-weaning diarrhea control drives demand, with nursery diet reformulation accelerating under FDA Veterinary Feed Directive restrictions on medically important antibiotics.
- Ruminants:Methane mitigation and ionophore replacement applications require protected-release formulations to survive rumen degradation.
- Aquaculture:Shrimp producers in Vietnam and salmon operators in Norway substitute phytobiotics for prophylactic antibiotics to secure ASC certification for EU retail access.
- Pets:Companion animal formulations emphasize palatability and digestive tolerance in premium kibble and therapeutic diets.
Poultry commands absolute volume. Aquaculture climbs fastest on export certification pressure.
Function:
Claim substantiation requirements and measurement protocols create tiered pricing structures, with growth promotion claims demanding the most rigorous trial documentation.
- Growth Promotion:Feed conversion ratio and weight gain improvements documented through controlled field trials, the claim category most scrutinized by EFSA and FDA. Poultry integrators in the US Southeast submit these protocols to export auditors as residue prevention documentation.
- Disease Resistance:Pathogen challenge studies and immune marker assays support reduced mortality claims, particularly valued in high-density swine finishing operations.
- Digestive Health:Gut morphology and microbiota composition endpoints, the most widely validated function across species.
- Immunomodulation:Cytokine and antibody response measurements, emerging as a differentiation axis in breeding stock and layer applications.
- Antioxidant Activity:Oxidative stress reduction in high-performance animals and product shelf-life extension for feed manufacturers.
Digestive Health leads volume flows. Immunomodulation gains share fastest on breeding stock premiums.
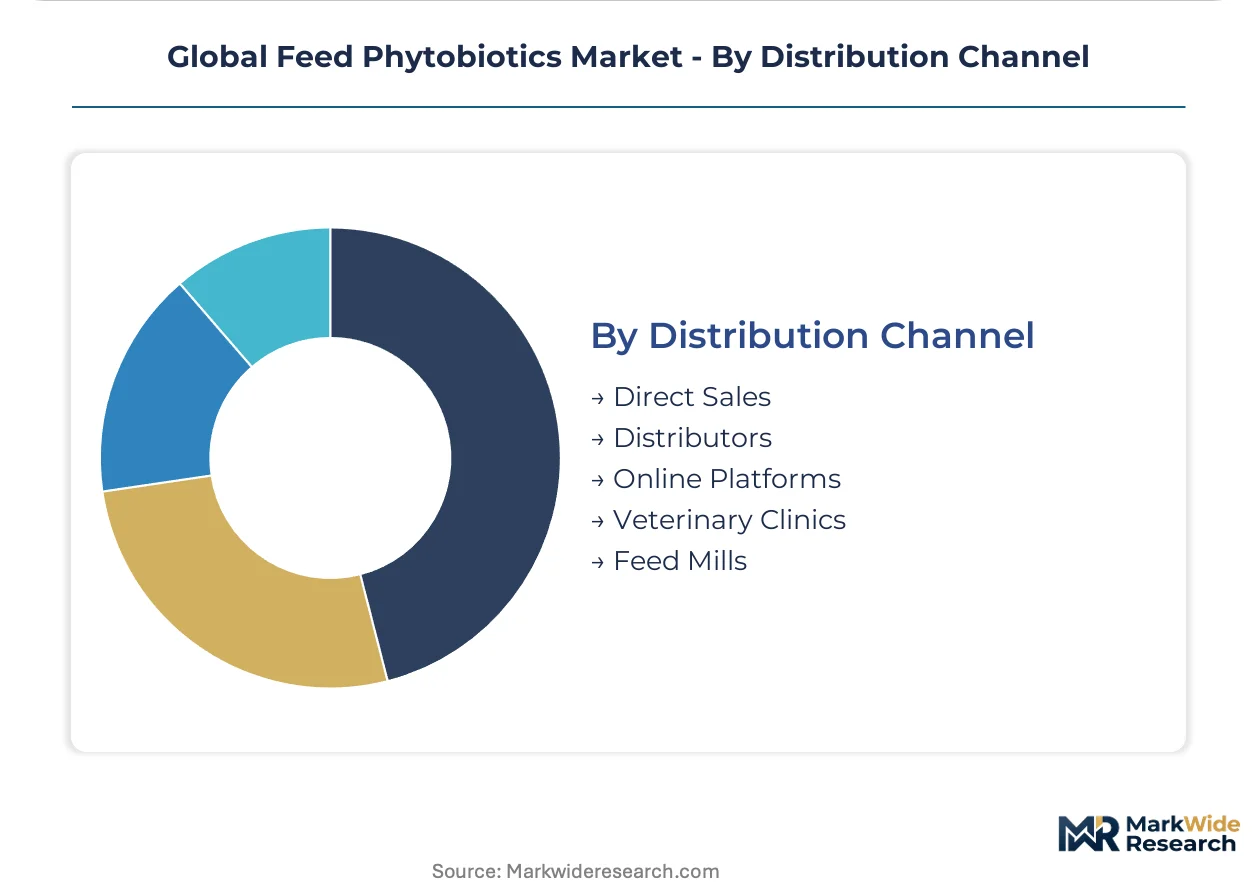
Distribution Channel:
Channel selection correlates with customer scale and technical service requirements, from self-serve online procurement for smallholders to embedded nutritionist support for integrated protein processors.
- Direct Sales:Technical specialists co-develop protocols with top-ten protein processors, outcome-based contracts displacing distributor-mediated procurement in North American broiler operations. JBS and BRF in Brazil consolidate approved supplier lists to three botanical premix partners per protein category.
- Distributors:Regional inventory and credit terms serve mid-scale independent feed mills and veterinary practices.
- Online Platforms:Growing penetration among smallholder cooperatives and specialty organic producers seeking transparent sourcing documentation.
- Veterinary Clinics:Prescription-aligned phytobiotic recommendations in jurisdictions with restricted antibiotic access.
- Feed Mills:Integrated blending operations demanding just-in-time delivery and batch certification.
Direct Sales dominates value capture. Online Platforms expand fastest on smallholder digital adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's southern poultry corridor anchors Brazilian phytobiotic procurement, with integrators there reformulating antibiotic-free rations to meet EU residue protocols for export-bound broiler shipments.
Brazil
JBS and BRF processors in Rio Grande do Sul and Paraná states scale essential oil inclusion rates under pressure from EU border inspection audits. ANVISA aligns domestic feed additive registration with Codex Alimentarius standards to accelerate export clearance. The Santa Catarina poultry cluster concentrates technical trials validating thymol-based formulations for antibiotic-free certification.
United States
Corn Belt feed mills reformulate weaned pig starter diets following FDA Veterinary Feed Directive restrictions on tylosin and lincomycin. The FDA's residue prevention framework redirects procurement toward botanical alternatives with documented growth promotion claims. North Carolina and Georgia poultry integrators submit phytobiotic protocols to export auditors as compliance documentation.
Netherlands
Dairy cooperatives in Friesland and Gelderland pilot microencapsulated essential oil blends for methane mitigation under EU Green Deal Farm to Fork binding targets. EFSA feed additive authorization protocols evaluate novel phytobiotic submissions through 18-24 month safety windows. The Wageningen agricultural research corridor anchors controlled-release technology development for rumen-stable delivery.
Vietnam
Shrimp producers in the Mekong Delta substitute phytobiotics for prophylactic antibiotics to secure ASC certification enabling EU retail access. The Ministry of Agriculture and Rural Affairs tightens residue limits on aquaculture products destined for export markets. Bạc Liêu and Cà Mau provinces concentrate pond system trials validating herbal extract protocols.
Germany
Baden-Württemberg and Bavaria livestock operations consolidate procurement around standardized essential oil premixes as the EU Green Deal tightens antimicrobial restrictions. ECHA REACH compliance requirements shape botanical raw material sourcing from spice-producing regions. The Lower Saxony dairy belt integrates phytobiotic formulations into climate-stressed methane reduction programs.
Global Feed Phytobiotics Market Competitive Landscape
The competitive structure tilts toward integrated nutrition platforms with captive feed formulation capabilities. Supplier negotiation leverage compresses as buyer concentration among top-ten protein processors intensifies. Three archetypes dominate: multinational nutrition conglomerates with premix integration, specialized essential oil formulators with microencapsulation IP, and regional botanical traders serving cost-sensitive ruminant applications. Direct contracting displaces distributor-mediated procurement, while protected-release technology licensing creates differentiation moats.
Within the integrated nutrition tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven platforms blending phytobiotic premixes directly into feed mill operations. Delacon Biotechnik GmbH and Phytobiotics Futterzusatzstoffe GmbH represent specialized formulators with technical service depth in species-specific applications. DSM-Firmenich AG occupies a position bridging nutrition science and precision delivery technologies.
| Leading Market Players |
|---|
| Alltech, Inc. |
| Phytobiotics Futterzusatzstoffe GmbH |
| Cargill, Incorporated |
| Nutreco N.V. |
| Delacon Biotechnik GmbH |
| BASF SE |
| DSM-Firmenich AG |
| Archer Daniels Midland Company |
| Kemin Industries, Inc. |
| Others |
Supply & Pricing Matrix
The EU Green Deal's Farm to Fork antimicrobial reduction mandates gate qualified supply and premium-tier pricing access for phytobiotic formulators, as compliance documentation and EFSA authorization timelines separate certified premix suppliers from commodity botanical traders.
Pricing Analysis
Value-based pricing anchored to measurable feed conversion outcomes dominates procurement contracts between top-ten protein processors and specialized formulators. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA authorization status, microencapsulation IP ownership, and technical service depth. Cost compression in standard-grade essential oil blends is intensifying because Turkish and Moroccan supply volatility exposes non-integrated formulators. Contract poultry integrators in Brazil's southern belt demonstrate lowest price sensitivity due to EU export certification requirements, while independent feed mills in Southeast Asia exhibit highest sensitivity to per-kilogram premix costs.
Supply Chain Analysis
Dual-sourcing requirements from JBS, BRF, and Cargill procurement teams mandate multi-supplier qualification for oregano and thyme oil origins, forcing formulators to maintain approved vendor lists across Turkey, Morocco, and Spain. Raw material dependencies center on steam-distilled terpenoid concentrates, lipid-shell encapsulation polymers, and standardized herbal extract matrices. Single-source vulnerability concentrates in Turkish oregano oil supply, where geopolitical and climatic disruptions propagate price volatility. Distribution runs through integrated nutrition platforms with captive feed mill networks, displacing independent distributor channels in North American and Brazilian broiler operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with players pursuing backward integration into Turkish and Moroccan essential oil extraction to secure supply and margin control.
For Market Incumbents: Anchor market position through captive supply agreements with Turkish oregano cooperatives and accelerated EFSA dossier submissions for novel microencapsulated formulations. Threat from probiotic competitors with documented mode-of-action papers demands defensive patent filings around controlled-release delivery mechanisms. Capacity addition in Brazil's Santa Catarina poultry cluster captures export-oriented demand from JBS and BRF consolidation programs.
For New Entrants and Emerging Players: Enter via Vietnamese aquaculture certification gaps, where ASC-compliant shrimp producers seek phytobiotic alternatives to prophylactic antibiotics with limited incumbent technical service presence. The Mekong Delta pond system segment offers lowest penetration resistance due to fragmented supplier relationships and urgent export market access requirements. Direct contracting with provincial processing cooperatives bypasses distributor margin capture.
For Investors and Strategic Acquirers: EFSA authorization timeline compression is the leading indicator that specialized formulators with approved dossiers will command acquisition premiums from integrated nutrition platforms seeking regulatory fast-tracks. Long-term viability favors mid-cap specialists with microencapsulation IP and species-specific trial databases over commodity botanical traders. Watch for Delacon-style methane-mitigation positioning in climate-stressed dairy regions as the inflection signal for premium valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Essential Oil Extraction | Turkish and Moroccan supply control reduces raw material volatility exposure for formulators. |
| Microencapsulation Technology Licensing | Rumen-stable delivery patents differentiate suppliers in dairy methane mitigation programs. |
| EFSA Dossier Acceleration | Feed additive authorization timelines compress commercialization windows for novel actives. |
| Direct Contracting with Protein Integrators | JBS and BRF supplier list consolidation favors embedded technical service relationships. |
| Species-Specific Trial Database Expansion | Controlled field documentation supports outcome-based pricing in poultry gut health applications. |
Research Methodology
Trade databases, EFSA feed additive registers, and ANVISA approval records formed the secondary backbone, cross-referenced with primary interviews involving phytobiotic formulator R&D directors, poultry integrator nutritionists, feed mill procurement managers, and veterinary regulatory affairs specialists. Bottom-up volume estimates from species-specific inclusion rate assumptions and top-down value reconciliation against disclosed nutrition platform revenues were triangulated to constrain forecast variance.
Historical trendline analysis of essential oil price indices, antimicrobial regulatory phase-out schedules, and protein export certification volumes informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, animal physiology category, functional claim substantiation level, and distribution channel structure. CAGRs were derived from elasticity-adjusted adoption curves reflecting FDA Veterinary Feed Directive compliance deadlines and EU Green Deal binding target trajectories. Feed conversion ratio improvement coefficients and residue audit failure cost estimates served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA authorization delays, Turkish supply disruptions, or probiotic efficacy breakthroughs. A model refresh is warranted upon material change in EU residue limit enforcement intensity or Brazilian export audit protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
US Biofungicide Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Spain Biopesticides Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Plant-Based Biologics Market