
 Indonesia Biopesticides Market | 2026-2036
Indonesia Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Biopesticides Market Foresight
Agricultural supply store networks across Indonesia is fragmenting as online retail platforms and direct sales channels gain ground among smallholder farmers. Bayer CropScience AG leverages its established agronomic advisory services to sustain dealer loyalty in tier-one rice belts. Koppert Biological Systems specializes in microbial biocontrol solutions for high-value horticulture, anchoring its position in greenhouse clusters near Bandung. Nufarm competes through broad-spectrum biofungicide portfolios tailored to tropical humidity conditions.
Indonesia biopesticides comprise naturally derived or microbially produced crop protection agents, typically formulated with Bacillus thuringiensis, Trichoderma species, or botanical extracts, that target specific pests through non-chemical modes of action. These agents function by disrupting insect feeding, colonizing pathogenic fungi, or inducing systemic resistance in host plants, primarily serving commercial agriculture and export-oriented horticulture. Bioinsecticides command the largest product type position due to relentless pressure from rice stem borers and fruit flies across archipelago growing regions. Biofungicides represent the fastest-expanding category as wet tropical climates amplify soil-borne and foliar fungal diseases in vegetable systems. Plant growth regulators concentrate margin pools among export banana and pineapple operations seeking uniform ripening and shelf-life extension for shipment to East Asian markets.
BIS-equivalent national standards and the Ministry of Agriculture's pesticide registration framework govern active substance approval, field efficacy trials, and residue monitoring for biopesticide market access across Indonesian territory. The national food safety authority enforces tightened maximum residue limits that directly shift farmer procurement toward registered biological alternatives with favorable toxicological profiles. Stakeholders must monitor evolving registration pathways for novel microbial strains and anticipate how provincial agricultural extension budgets will allocate between synthetic and biological input subsidies.
Market Dynamics
Indonesia's tightened maximum residue limits under national food safety regulations are compressing farmer procurement cycles toward registered biological alternatives, while provincial extension budgets pivot subsidy allocations away from synthetic chemistry.
Growth Catalysts
- Rice Stem Borer Pressure:Persistent infestation across Java and Sumatra irrigation belts sustains farmer demand for Bacillus thuringiensis formulations as synthetic resistance widens.
- West Java Vegetable Export Mandates:EU-bound horticulture shipments face residue scrutiny that elevates biocontrol adoption in greenhouse clusters near Bandung.
- Microbial Strain Registration Pathways:Indonesia's Ministry of Agriculture streamlined field efficacy trial protocols for novel Trichoderma variants, accelerating product pipeline velocity.
Market Restraints
- Cold Chain Fragmentation:Spore viability degradation during inter-island shipping constrains microbial biopesticide reach to outer provinces beyond Java.
- Synthetic Chemical Stockpiles:Subsidized organophosphate inventories in East Java district warehouses delay grower transition timelines.
- Extension Agent Capacity:Provincial agricultural departments lack trained personnel to demonstrate biocontrol application protocols at scale.
Strategic Opportunities
- North Sumatra Smallholder Networks:Direct-to-farmer digital platforms bypass fragmented cooperative structures in Medan corridor vegetable systems.
- Export Banana Ripening Control:Plant growth regulator demand concentrates among East Kalimantan plantations supplying Japanese supermarket chains.
- Subsidized Biological Input Pilots:Ministry of Agriculture trial programs in Sulawesi reallocate synthetic pesticide vouchers toward microbial biocontrol coupons.
Industry Challenges
- Field Efficacy Validation Timelines:Multi-season tropical testing requirements for novel strains extend registration cycles beyond investor patience thresholds.
- Spore Formulation Stability:Humidity-induced shelf-life degradation in traditional supply chain nodes forces refrigeration infrastructure capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Biopesticides Market |
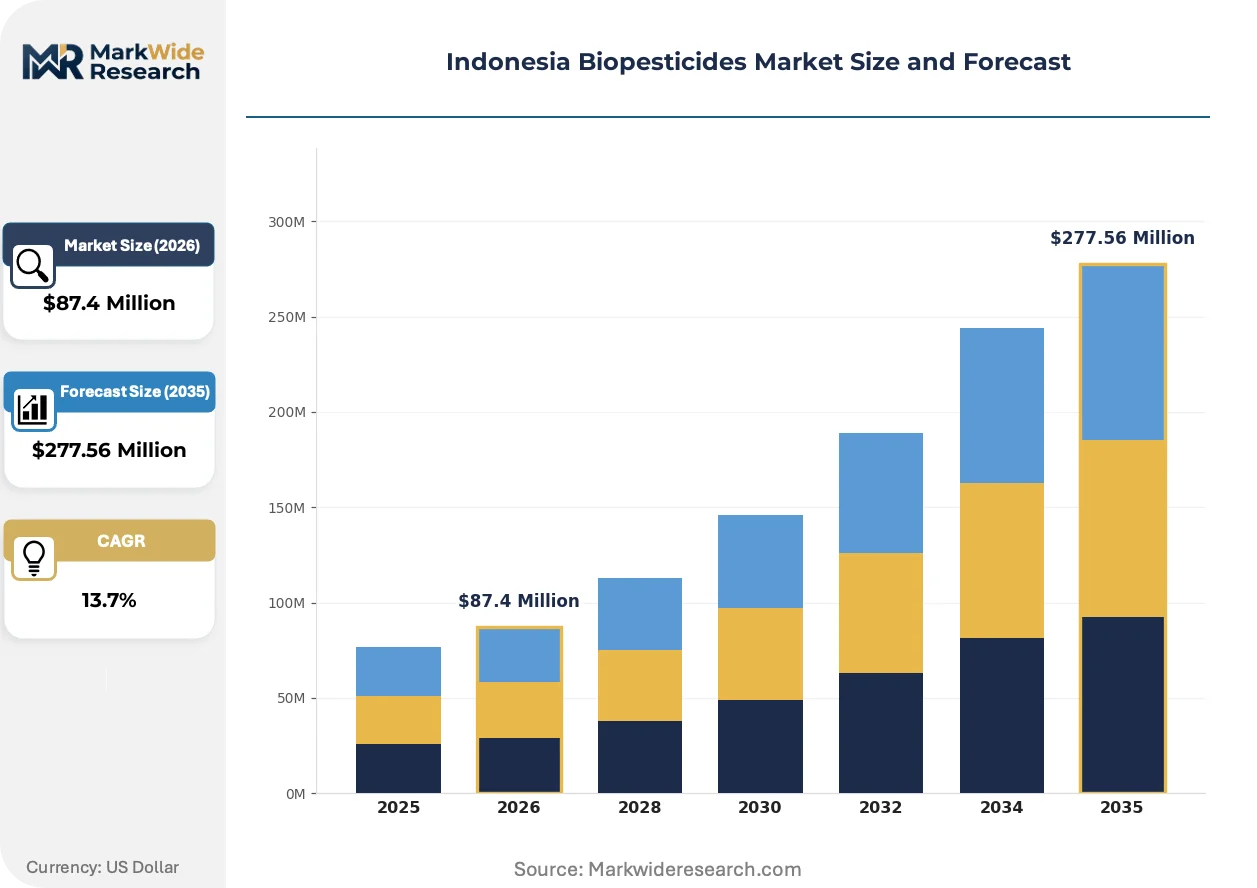
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $277.56 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioinsecticides, Biofungicides, Bioherbicides, Plant Growth Regulators Application: Agricultural, Horticultural, Ornamental, Vegetables End User: Farmers, Agricultural Cooperatives, Agrochemical Companies, Research Institutions Distribution Channel: Online Retail, Agricultural Supply Stores, Distributors, Direct Sales |
| Companies Covered | Kan biosys, Bayer CropScience AG, Nufarm, Koppert Biological Systems, FMC Corporation, BASF SE, Pro Farm Group Inc., Seipasa, Custom Biologicals, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Biopesticides Market Shifts & Advancements
Biological crop protection in Indonesia is pivoting toward precision delivery systems and digital advisory integration, compressing the gap between laboratory strain development and field-scale efficacy validation.
RNA interference biopesticide platforms targeting rice stem borers are virtualizing traditional broad-spectrum insecticide categories by enabling species-specific genetic disruption without non-target organism impact. Seed treatment applicators in Central Java irrigation districts are piloting these formulations at commercial scale. The technology is virtualizing legacy pest management economics by collapsing application frequency and eliminating harvest interval restrictions.
Indonesia's Ministry of Agriculture tightened maximum residue limit enforcement under national food safety regulations, triggering downstream procurement audits across export-oriented horticulture supply chains. West Java packing houses serving Singapore and Hong Kong markets now require biocontrol documentation for supplier qualification. Vegetable cooperatives in Lembang highlands are restructuring input procurement to preempt inspection failures.
Smallholder buying collectives in North Sumatra are consolidating purchase volumes through mobile-enabled aggregator platforms that disintermediate traditional agricultural supply store networks. These digital channels bundle biocontrol products with satellite-derived pest pressure alerts and voice-message application guidance. The model is most visible in Deli Serdang district chili pepper systems where cooperative penetration previously lagged Java benchmarks.
Indonesia Biopesticides Market Segmentation
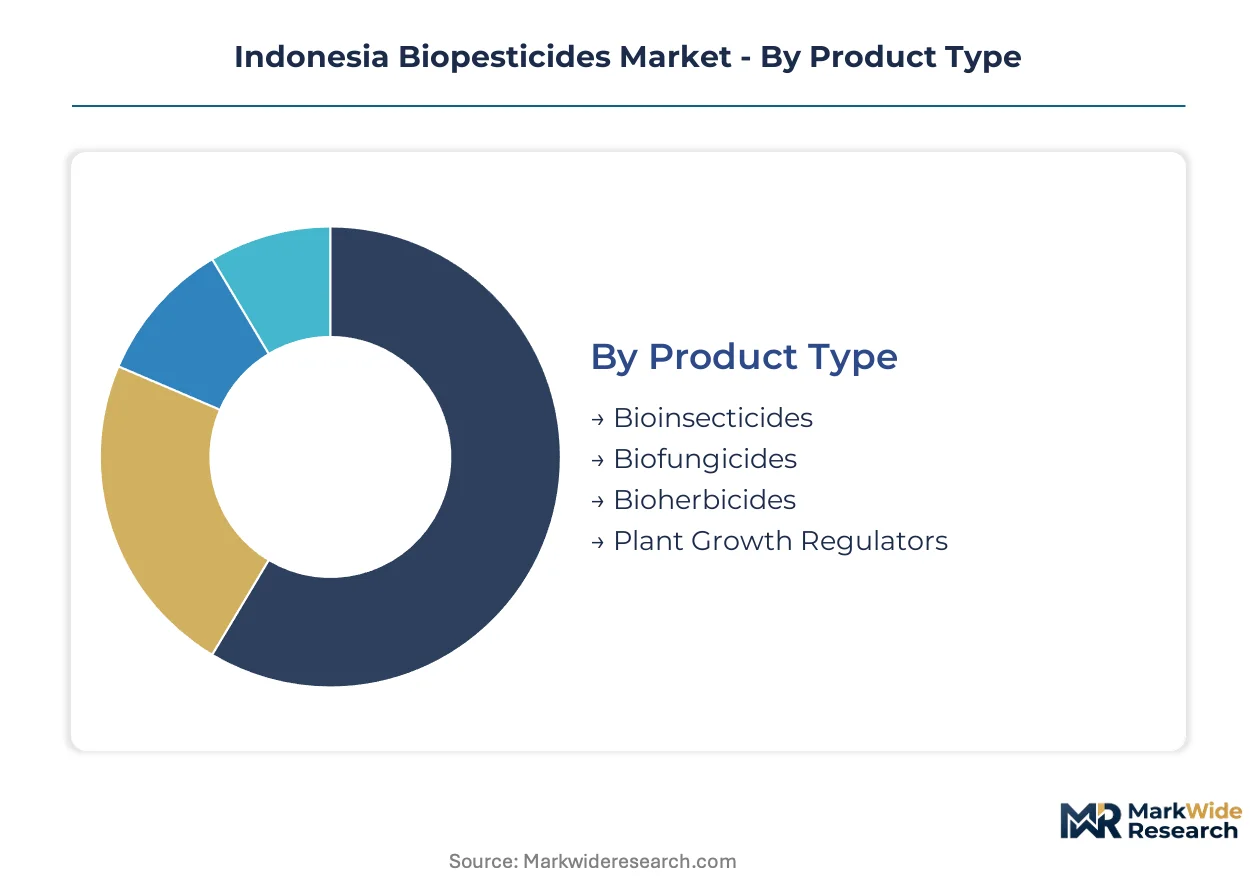
Segmentation in Indonesia's biopesticides market reflects the archipelago's agricultural heterogeneity, where rice monocultures in Java, export horticulture in West Java highlands, and smallholder vegetable systems in Sumatra each generate distinct product requirements and procurement behaviors.
Product Type:
Mature microbial formulations dominate current revenue pools, while emerging RNA interference and novel strain technologies are accelerating registration pipelines.
- Bioinsecticides:Formulations based on Bacillus thuringiensis and entomopathogenic fungi target rice stem borers and fruit flies through gut paralysis and cuticle penetration. Java's irrigation belts sustain concentrated demand as synthetic pyrethroid resistance widens across Scirpophaga incertulas populations.
- Biofungicides:Trichoderma harzianum and T. viride preparations colonize root zones to outcompete Rhizoctonia and Fusarium in wet tropical soils. West Java greenhouse clusters near Bandung drive fastest category expansion as EU residue mandates tighten procurement specifications for export-bound tomatoes and peppers.
- Bioherbicides:Phytopathogenic fungal isolates and allelopathic botanical extracts suppress weed competition in organic rice systems.
- Plant Growth Regulators:Gibberellin and cytokinin formulations from microbial fermentation control ripening uniformity in East Kalimantan banana plantations supplying Japanese retail chains.
Bioinsecticides handle the majority of throughput; biofungicides are expanding most quickly on share as vegetable export compliance tightens.
Application:
Volume concentrates in staple crop protection, while margin pools shift toward high-value horticultural systems with certification premiums.
- Agricultural:Rice, corn, and soybean operations across Java and Sumatra account for bulk consumption, with Ministry of Agriculture subsidy pilots redirecting synthetic vouchers toward microbial alternatives in Sulawesi trial districts.
- Horticultural:Greenhouse tomatoes, peppers, and strawberries in Lembang highlands require documented biocontrol protocols for Singapore and Hong Kong market access.
- Ornamental:Cut flower operations near Jakarta supply domestic event markets with lower regulatory pressure than export channels.
- Vegetables:Open-field chili and shallot systems in North Sumatra's Deli Serdang district adopt mobile-aggregated biocontrol purchases as cooperative structures fragment.
Agricultural applications absorb the greatest volume; horticultural systems command the steepest expansion trajectory on value per hectare.
End User:
Procurement authority is decentralizing from district agricultural offices toward direct farmer purchasing and cooperative aggregation platforms.
- Farmers:Smallholders under two hectares in Central Java and East Java represent the largest addressable population, with adoption constrained by extension agent capacity gaps.
- Agricultural Cooperatives:West Java vegetable cooperatives restructure input procurement to preempt BIS-equivalent residue inspection failures in export supply chains.
- Agrochemical Companies:Distributors with established synthetic portfolios add biological lines to defend dealer relationships as farmer demand pivots.
- Research Institutions:Bogor Agricultural University and Ministry of Agriculture research stations validate novel strain field efficacy for registration pathway acceleration.
Farmers constitute the broadest user base; agricultural cooperatives are gaining procurement concentration fastest as compliance documentation requirements intensify.
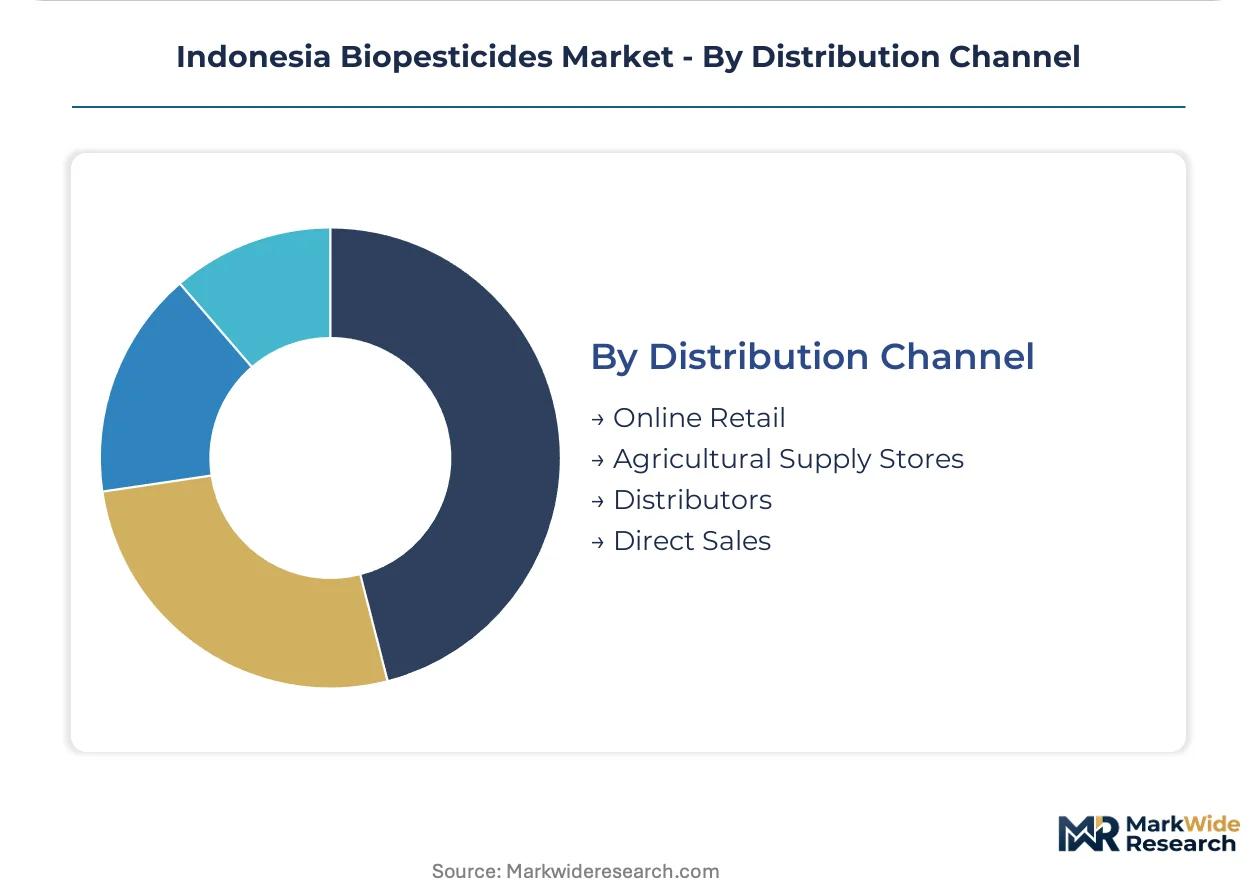
Distribution Channel:
Channel structure is bifurcating between legacy agricultural supply store networks and digital platforms that compress price discovery and technical advisory delivery.
- Online Retail:Mobile-enabled aggregator platforms in North Sumatra bundle biocontrol products with satellite pest alerts and voice-message guidance, disintermediating cooperative structures.
- Agricultural Supply Stores:Fragmented independent retailers in Java rice belts face loyalty erosion as direct manufacturer channels and digital alternatives gain ground.
- Distributors:Regional distributors with cold chain capabilities extend microbial biopesticide reach beyond Java, though spore viability degradation constrains outer province penetration.
- Direct Sales:Manufacturers deploy agronomic advisory teams to tier-one rice belts, replicating Bayer CropScience's dealer loyalty model with biological product portfolios.
Agricultural supply stores retain the widest physical footprint; online retail is climbing the fastest on transaction share as smallholder smartphone penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tanjung Priok Port container terminal in North Jakarta underwrites Java's dominance in agricultural input distribution, with refrigerated cargo corridors extending microbial biopesticide formulations into Sumatra and Sulawesi.
West Java
EU-bound vegetable exports from Lembang highlands drive biocontrol procurement as packing houses enforce residue documentation for Singapore and Hong Kong market access. The Ministry of Agriculture's tightened maximum residue limits redirect farmer demand toward registered biological alternatives. Greenhouse clusters near Bandung anchor the fastest-expanding biofungicide consumption as wet tropical conditions amplify soil-borne disease pressure in tomato and pepper systems.
Central Java
Rice stem borer infestations across irrigation districts sustain concentrated demand for Bacillus thuringiensis formulations as synthetic pyrethroid resistance widens. BIS-equivalent national standards govern active substance approval and field efficacy trials for biopesticide registration. Seed treatment applicators in Demak and Grobogan districts pilot RNA interference platforms at commercial scale, collapsing traditional broad-spectrum insecticide application economics.
East Java
Subsidized organophosphate stockpiles in district warehouses delay grower transition timelines despite tightening residue regulations. Provincial agricultural extension budgets pivot subsidy allocations away from synthetic chemistry toward biological input pilots. The Surabaya corridor serves as the primary distribution node for microbial formulations entering outer island provinces.
North Sumatra
Smallholder chili and shallot systems in Deli Serdang district adopt mobile-enabled biocontrol aggregators as cooperative structures fragment. Direct-to-farmer digital platforms bypass traditional agricultural supply store networks, bundling products with satellite-derived pest alerts. Medan corridor vegetable operations concentrate demand for microbial biocontrol as export compliance documentation requirements intensify.
Sulawesi
Ministry of Agriculture trial programs reallocate synthetic pesticide vouchers toward microbial biocontrol coupons in select districts. Cold chain fragmentation constrains spore viability during inter-island shipping from Java manufacturing nodes. Makassar serves as the southern archipelago transshipment point for biological inputs entering Eastern Indonesia growing regions.
Indonesia Biopesticides Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational agrichemical conglomerates with established distribution infrastructure, specialized microbial biocontrol firms with tropical formulation expertise, and regional distributors bridging cold chain gaps to outer provinces. Strategic archetypes include advisory-anchored loyalty builders, humidity-specialized portfolio diversifiers, and digital platform integrators. Dominant competitive moves encompass direct manufacturer channels disintermediating legacy supply stores and provincial extension partnerships securing subsidized input program placement.
Within the multinational tier, Bayer CropScience AG and BASF SE occupy positions anchored by agronomic advisory services and broad-spectrum portfolios. Among specialized biocontrol operators, Koppert Biological Systems exemplifies microbial formulation focus for high-value horticulture systems. Nufarm sits within the tropical adaptation archetype, competing through biofungicide portfolios calibrated to humidity conditions. These three represent distinct strategic postures: loyalty defense through technical service, segment specialization, and environmental condition targeting.
| Leading Market Players |
|---|
| Kan biosys |
| Bayer CropScience AG |
| Nufarm |
| Koppert Biological Systems |
| FMC Corporation |
| BASF SE |
| Pro Farm Group Inc. |
| Seipasa |
| Custom Biologicals, Inc. |
| Others |
Supply & Pricing Matrix
Cold chain fragmentation during inter-island shipping determines both margin compression in outer provinces and the three-tier pricing structure that separates Java-based manufacturers from regional distributors and direct-to-farmer platforms. Spore viability degradation risks force refrigeration infrastructure capex that propagates through landed cost calculations across Sulawesi and Eastern Indonesia.
Pricing Analysis
Volume-discount tiering structures separate premium Trichoderma formulations for export-oriented West Java greenhouses from standard Bacillus thuringiensis products for rice belts and economy-grade botanical extracts for subsistence vegetable systems. Price differentiation rests on certification grade under BIS-equivalent national standards and cold chain integrity guarantees. Pricing pressure stems from subsidized organophosphate stockpiles in East Java district warehouses that delay grower transition timelines. Smallholders under two hectares in Central Java exhibit highest price sensitivity, while East Kalimantan banana plantation operators supplying Japanese retail chains absorb premium tiers without volume negotiation.
Supply Chain Analysis
Indonesia's Ministry of Agriculture pesticide registration framework functions as an export-control regime limiting novel microbial strain flows until multi-season tropical efficacy validation completes. Manufacturing concentrates in Java-based fermentation facilities near Bandung and Jakarta, with active ingredient sourcing from domestic agricultural research stations and specialized biocontrol laboratories. Raw material dependencies include specific Trichoderma harzianum isolates, Bacillus thuringiensis kurstaki strains, and humidity-stable carrier substrates. Single-source vulnerability characterizes cold chain logistics providers capable of maintaining spore viability beyond Java. Distribution runs through Tanjung Priok Port container terminals with refrigerated cargo corridors extending into Sumatra and Sulawesi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained extension agent scarcity constrains biocontrol adoption velocity across Indonesia's smallholder base, creating capability bottlenecks that determine competitive outcomes more than product formulation differences. Field demonstration capacity gaps at provincial agricultural departments represent the critical skill shortage separating market leaders from laggards.
For Market Incumbents: Harden dealer loyalty in tier-one rice belts through embedded agronomic advisory teams that replicate Bayer CropScience's service model with biological product portfolios. Invest in captive cold chain infrastructure to defend margin position against spore viability degradation during inter-island shipping. Prioritize backward integration into microbial strain development partnerships with Bogor Agricultural University to accelerate registration pathway velocity ahead of synthetic resistance widening. For New Entrants and Emerging Players: North Sumatra's Deli Serdang district chili pepper systems represent the most penetrable entry point, where cooperative structures fragment and mobile-enabled aggregator platforms disintermediate legacy supply stores. Sulawesi's Ministry of Agriculture subsidized biological input pilots offer policy-anchored demand visibility unavailable in saturated Java markets. Deploy direct-to-farmer digital channels bundling biocontrol products with satellite-derived pest alerts and voice-message application guidance. For Investors and Strategic Acquirers: Indonesia's tightened maximum residue limits under national food safety regulations reshape the acquisition landscape toward registrant portfolios with favorable toxicological profiles. Long-term viability across the projection horizon favors specialized microbial biocontrol firms with tropical formulation expertise over synthetic-legacy distributors pivoting into biological lines. Watch provincial agricultural extension budget reallocations between synthetic and biological input subsidies as the primary inflection signal for demand trajectory shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Buildout | Refrigerated cargo corridors from Tanjung Priok Port extend viable microbial reach to Sulawesi and Eastern Indonesia growing regions. |
| Strain Registration Acceleration | Streamlined field efficacy trial protocols for novel Trichoderma variants compress product pipeline velocity ahead of competitor submissions. |
| Direct-to-Farmer Platform Integration | Mobile-enabled aggregators in North Sumatra disintermediate fragmented cooperative structures with bundled biocontrol and pest alert services. |
| Provincial Extension Partnership | Collaboration with Ministry of Agriculture trial programs secures subsidized biocontrol coupon placement in Sulawesi pilot districts. |
| Export Compliance Documentation | Biocontrol protocol certification enables West Java packing house qualification for Singapore and Hong Kong market access. |
Research Methodology
Initial hypotheses were tested against primary input from provincial agricultural extension officers, biocontrol product distributors, greenhouse cluster managers, and Ministry of Agriculture registration officials and refined through secondary validation. Data synthesis combined structured interviews with cold chain logistics providers and satellite pest alert platform operators with customs records, BIS-equivalent standards documentation, and provincial subsidy allocation disclosures. Bottom-up farmer adoption modeling and top-down market sizing triangulated volume estimates across Java, Sumatra, and Eastern Indonesia.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product type, application category, end-user archetype, and distribution channel. CAGRs derived from province-level adoption curves weighted by subsidy program exposure and export compliance intensity. Industry-specific forecast inputs included rice stem borer infestation pressure indices and EU-bound horticulture shipment volume trajectories.
Practitioners should monitor regulatory enforcement patterns for maximum residue limits and provincial subsidy reallocation decisions for early signals of demand inflection. Forecasts reflect documented assumptions regarding extension agent capacity expansion and cold chain infrastructure deployment timelines. Material shifts in Ministry of Agriculture registration pathway duration or inter-island shipping cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
North America Biopesticides Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Biorational Pesticides Market
Bio-Agriculture
US Bio Pesticides Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
Brazil Biofertilizers Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
India Biomass Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Microphytes Market